
 Poly Coated Paperboard Market | 2026-2036
Poly Coated Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Coated Paperboard Market Outlook
A shift from single-source polyethylene procurement to multi-resin sourcing strategies is hardening among North American and European converters. WestRock leverages captive pulp supply and integrated extrusion lines to defend input cost stability. Mondi Group anchors its position through lightweighting R&D in barrier-coated formats for protein trays. Smurfit Kappa competes via recycled-fiber integration and regional mill networks across Iberia and the Nordics.
Poly coated paperboard consists of a cellulose-fiber substrate laminated with extruded polymer layers, typically polyethylene at 12–30 gsm coat weights, to impart liquid and grease resistance for direct food contact applications. The material serves as a structural barrier in cups, trays, and folding cartons where uncoated board would absorb moisture or oils. Double-sided coated grades command premium positioning in dairy and frozen-food segments where two-sided moisture protection extends shelf stability. Biodegradable polymer coatings represent the fastest-expanding coating material category as brand owners face extended producer responsibility mandates. Food packaging occupies the dominant end-use share, though healthcare packaging for sterilized instrument trays is gaining specification traction.
FDA food-contact notification requirements govern polymer migration limits in US applications, while EU REACH and the Packaging and Packaging Waste Regulation constrain single-use plastic integration in coated structures. China's GB standards for food packaging materials and India's BIS certification for paper-based food contact articles add compliance layers for exporters targeting those markets. Stakeholders must monitor polymer-to-fiber separation economics as mechanical recycling infrastructure scales, since recyclability claims increasingly determine buyer qualification criteria.
Market Dynamics
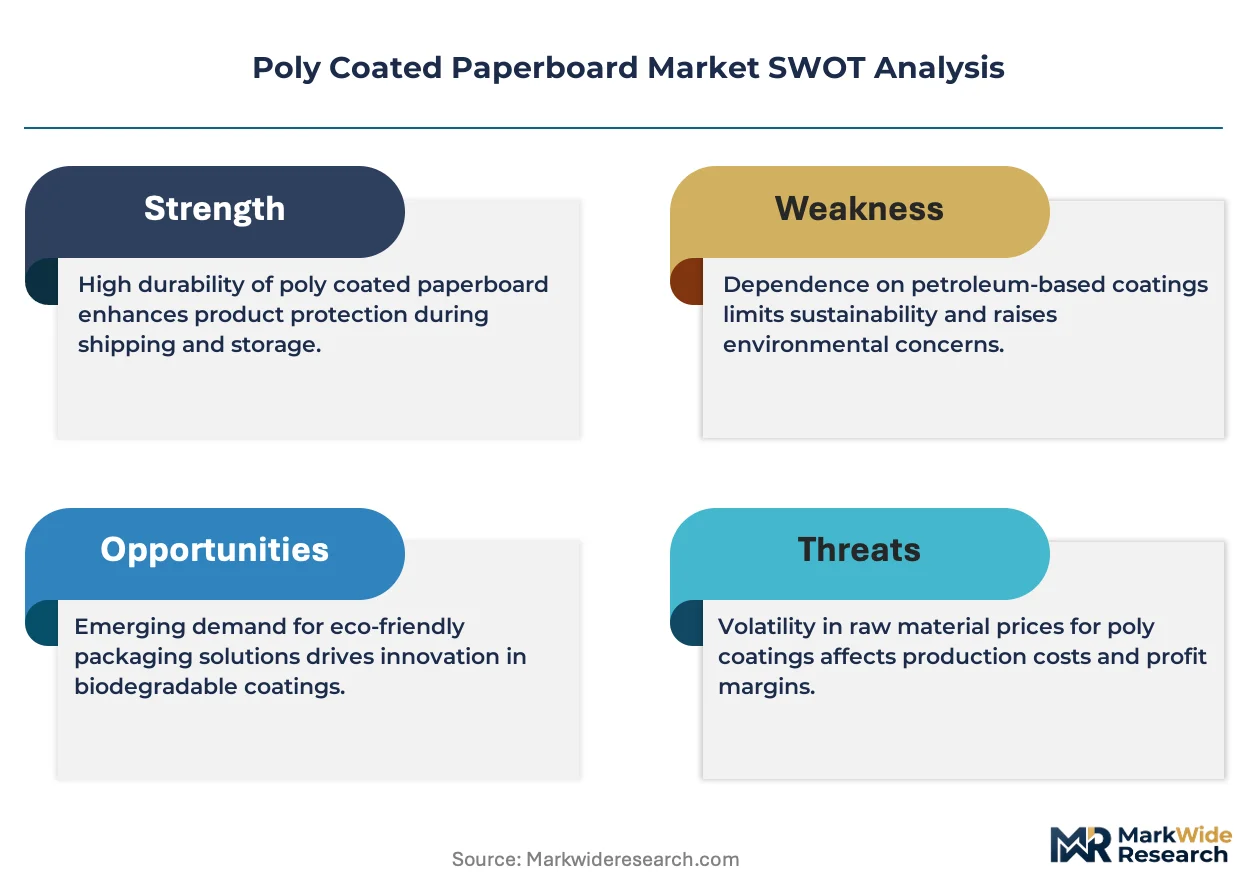
Converters face intensifying pressure to decouple from single-resin polyethylene sourcing as FDA migration limits tighten and EU extended producer responsibility schemes penalize non-recyclable barrier structures. This structural pivot toward multi-material compliance is reshaping capital allocation across extrusion and coating lines.
Growth Catalysts
- Quick-service restaurant expansion:Chains in India and Southeast Asia are scaling grease-resistant container specifications for cold-chain dairy and ready-to-eat meal formats.
- Biodegradable coating mandates:EU Packaging and Packaging Waste Regulation amendments are accelerating specification shifts toward compostable polymer barriers in protein tray applications.
- Healthcare sterilization demand:Hospitals and surgical centers are adopting coated instrument trays as single-use plastic alternatives face procurement restrictions.
Market Restraints
- Polyethylene price volatility:Crude-linked resin costs create margin compression for converters locked into annual supply contracts without pass-through clauses.
- Mechanical recycling economics:Polymer-to-fiber separation infrastructure remains underdeveloped in North American and European sorting facilities, limiting recyclability claims.
- Fluorochemical substitution gaps:PFAS-free grease barriers currently deliver inferior performance in high-temperature fried food applications versus legacy coated grades.
Strategic Opportunities
- India cold-chain infrastructure:Dairy and frozen food distribution network expansion is creating first-mover positioning for domestic coated board production capacity.
- Lightweighting R&D convergence:Barrier-coated formats below 250 gsm are penetrating protein tray segments previously served by heavier solid board structures.
- Recycled fiber integration premiums:Post-consumer fiber content thresholds are becoming qualification criteria for quick-service restaurant chain tenders in Nordic markets.
Industry Challenges
- Migration testing timelines:FDA food-contact notification review periods for novel biodegradable coatings extend qualification cycles by 12-18 months versus conventional polyethylene.
- Extrusion line retrofit costs:Multi-resin coating capability requires capital outlays for coextrusion dies and barrier layer thickness control systems that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Coated Paperboard Market |
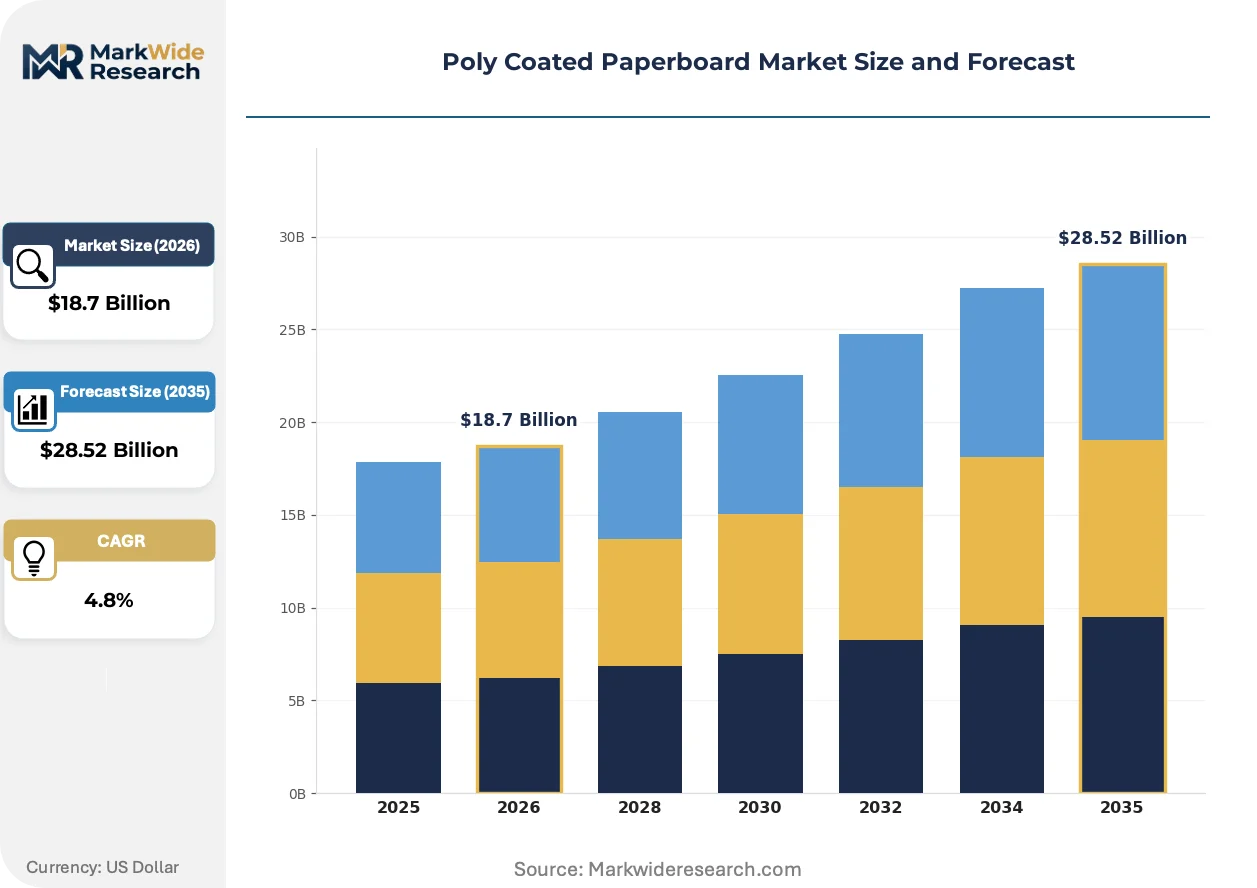
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Moisture Resistant, Tear Resistant End Use: Food Packaging, Beverage Packaging, Healthcare Packaging, Industrial Packaging Thickness: Lightweight, Standard, Heavyweight, Ultra-Heavyweight Coating Material: Polyethylene, Polypropylene, Biodegradable Polymers, Others |
| Companies Covered | WestRock, Stora Enso, Smurfit Kappa, Graphic Packaging International, International Paper Company, Mondi Group, Tetra Pak, Sappi Ltd, Nippon Paper Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Coated Paperboard Market Strategic Shifts
Coating technology evolution is compressing the performance gap between conventional polyethylene barriers and bio-based alternatives while regulatory pressure accelerates specification turnover. Material scientists and equipment manufacturers are converging on process innovations that reduce coat weights without sacrificing grease resistance.
Water-based barrier coatings incorporating plant-derived polymers are automating quality-control protocols in high-speed cup and tray production lines. Quick-service restaurant suppliers in Germany and France are qualifying these systems for hot-beverage applications at scale. The technology is automating defect detection and coat-weight uniformity adjustments that previously required manual intervention, reducing line stoppages and material waste.
EU REACH restrictions on intentionally added microplastics are forcing reformulation of conventional extruded polyethylene layers in food-contact articles. Manufacturers serving export markets must now maintain dual product lines: REACH-compliant grades for European destinations and legacy formulations for jurisdictions without equivalent restrictions. Dairy and frozen-food packaging categories face the steepest compliance cost escalation as double-sided coated grades require full barrier system redesigns.
Chain-level sustainability scorecards are consolidating supplier rosters around converters with verified recyclability certifications and post-consumer fiber integration capabilities. Quick-service restaurant procurement teams in the United States and United Kingdom are awarding multi-year contracts exclusively to vendors demonstrating closed-loop collection partnerships with municipal recycling operators. This behavioral shift is marginalizing smaller converters lacking capital for certification auditing and chain-of-custody documentation systems.
Poly Coated Paperboard Market Segmentation
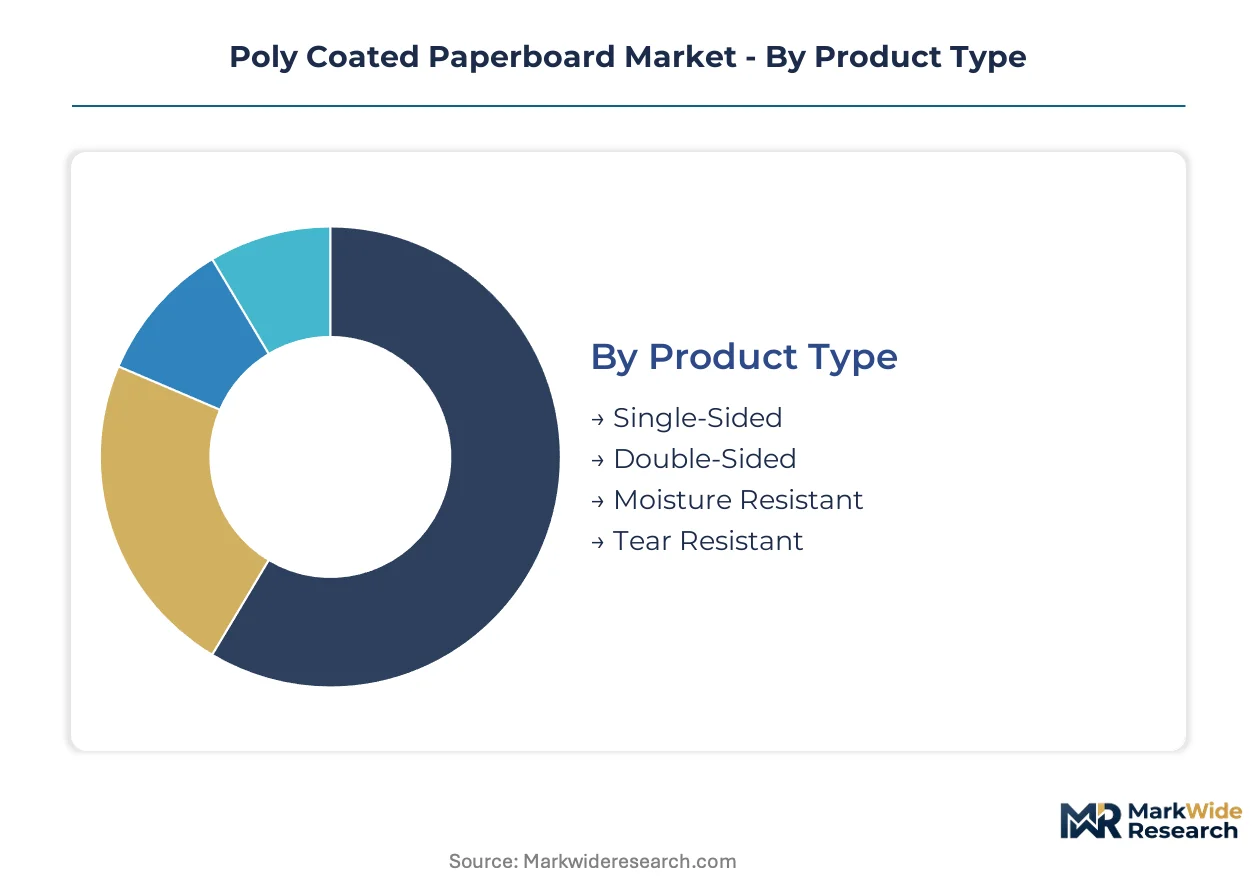
Poly coated paperboard specifications diverge sharply across food-contact compliance tiers and barrier-performance requirements. Buyers configure material stacks against precise end-use constraints rather than selecting from commodity catalogs.
Product Type:
Customization intensity spans single-sided commodity grades through engineered double-sided barriers, with standardization concentrated in high-volume quick-service restaurant formats.
- Single-Sided:One polymer face protects against moisture ingress while the reverse remains untreated cellulose for cost-sensitive folding cartons and dry-food sleeves. Quick-service restaurant chains in India specify this grade for cold-chain dairy cups where single-face grease resistance suffices.
- Double-Sided:Extruded polymer layers on both faces create hermetic moisture barriers for frozen-food trays and protein packaging requiring extended shelf stability. EU Packaging and Packaging Waste Regulation compliance costs concentrate specification authority with converters maintaining dual-formulation capabilities.
- Moisture Resistant:Engineered fiber substrates with enhanced internal sizing reduce dependence on external polymer coatings for humid-climate distribution.
- Tear Resistant:Long-fiber pulp blends and polymer reinforcement layers serve industrial strapping and heavy-duty retail display applications.
Most installed capacity flows through Single-Sided grades. Expansion is steepest in Double-Sided as frozen-food distribution networks proliferate.
End Use:
Application-specific migration limits and sterilization protocols fragment demand across food-contact, medical-device, and industrial durability tiers.
- Food Packaging:Direct-contact grease barriers for fried-food containers and ready-to-eat meal trays dominate volume. FDA food-contact notification requirements govern polymer migration thresholds, while EU REACH constraints on intentionally added microplastics force barrier-system redesigns for export-bound production.
- Beverage Packaging:Hot-fill cup and cold-drink sleeve specifications demand distinct polymer coat weights and heat-seal activation temperatures. German and French quick-service restaurant suppliers are qualifying water-based plant-derived barrier coatings for high-speed automated lines.
- Healthcare Packaging:Sterilized instrument trays and single-use surgical kits require bioburden-resistant coatings as hospitals restrict conventional plastic alternatives.
- Industrial Packaging:Moisture-resistant board for automotive parts and electronics shipping serves protective functions without food-contact compliance overhead.
Food Packaging commands the dominant share of extrusion line allocation. Healthcare Packaging is gaining specification traction fastest as procurement restrictions on single-use plastics harden.
Thickness:
Weight-class selection tracks structural load requirements against material-yield economics in converter operations.
- Lightweight:Sub-250 gsm barrier-coated formats penetrate protein tray segments previously served by heavier solid board, reducing per-unit fiber consumption.
- Standard:Mid-range calipers balance rigidity and cost for general-purpose folding cartons and cup sleeves.
- Heavyweight:Structural integrity for multi-component frozen dinner trays and industrial protective packaging.
- Ultra-Heavyweight:Maximum durability specifications for export shipping and heavy retail display units.
Standard thickness absorbs the majority of current mill capacity. Lightweight grades are expanding most quickly as lightweighting R&D converges on barrier performance parity.
Coating Material:
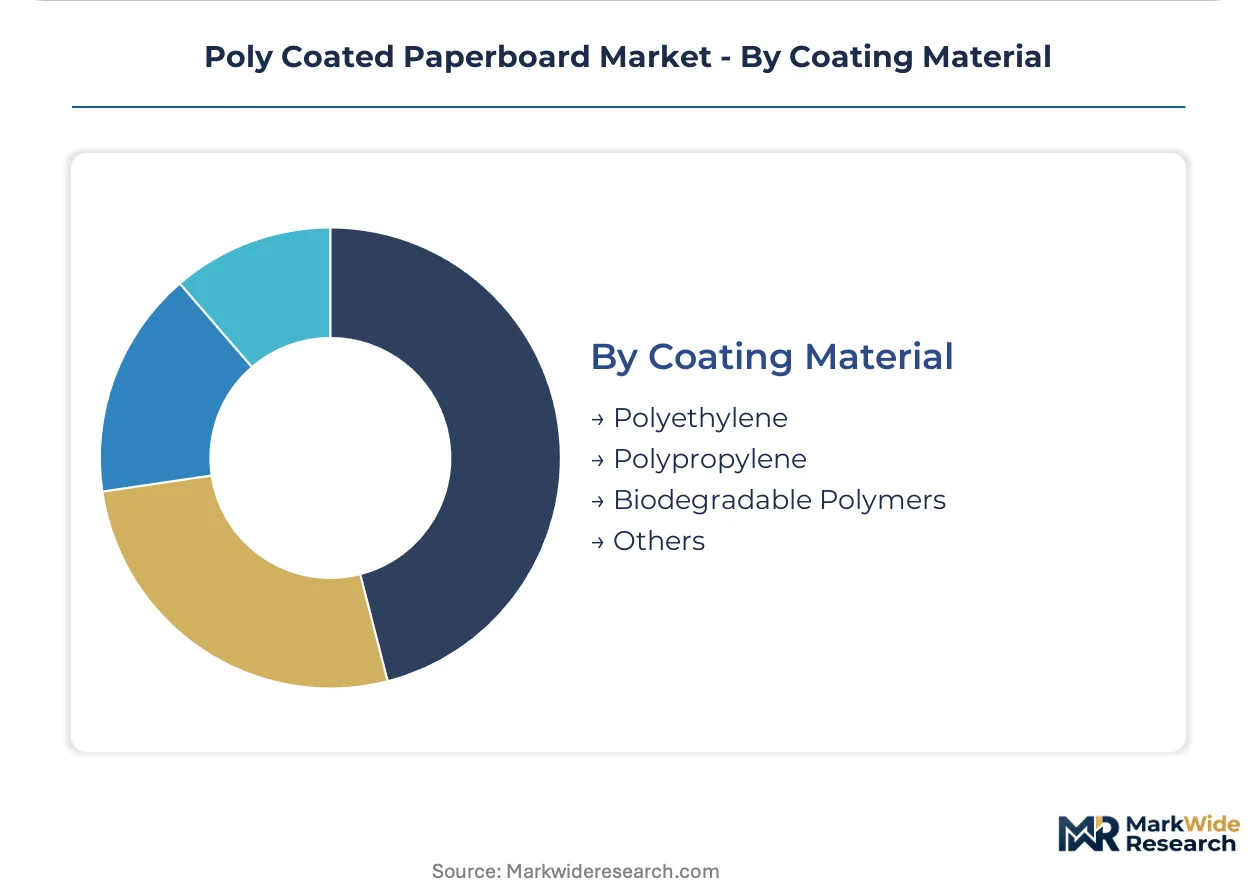
Resin selection determines recyclability certification eligibility and regulatory compliance jurisdiction for finished articles.
- Polyethylene:Conventional extruded PE at 12–30 gsm coat weights remains the baseline for grease and moisture resistance. Crude-linked price volatility creates margin compression for converters lacking pass-through contract clauses.
- Polypropylene:Higher thermal stability serves hot-fill and microwaveable applications where PE barriers soften.
- Biodegradable Polymers:Compostable barriers derived from plant starches and polylactic acid formulations are accelerating specification turnover as EU extended producer responsibility mandates penalize non-recyclable structures.
- Others:Fluorochemical-free grease barriers and hybrid bio-synthetic formulations address PFAS substitution gaps in high-temperature fried food packaging.
Polyethylene maintains the largest installed extrusion base. Biodegradable Polymers are climbing the fastest as brand-owner sustainability scorecards harden qualification thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating coating capacity toward jurisdictions with lower compliance-cost burdens as EU REACH amendments and FDA notification timelines diverge. This regulatory arbitrage is reshaping investment flows across extrusion line deployments.
United States
Quick-service restaurant chains in Texas and the Southeast are scaling grease-resistant container specifications for fried-food delivery formats. FDA food-contact notification requirements govern polymer migration thresholds for all coated structures entering food service. Georgia and the Carolinas host the densest converter clusters where extrusion lines serve regional dairy and ready-to-eat meal distributors.
Germany
Water-based plant-derived barrier coatings are automating quality-control protocols in high-speed cup production lines across Baden-Württemberg. EU REACH restrictions on intentionally added microplastics force full barrier-system redesigns for double-sided coated grades. The Eindhoven-to-Ruhr industrial corridor concentrates lightweighting R&D facilities serving protein tray specifications.
India
Cold-chain dairy and ready-to-eat segments in Maharashtra and Gujarat are expanding coated board consumption as distribution networks penetrate tier-2 cities. BIS certification for paper-based food contact articles adds compliance layers for domestic producers and importers alike. The Mumbai-Pune industrial belt anchors first-mover production capacity targeting frozen-food tray demand.
China
Export-oriented converters in the Yangtze River Delta maintain dual product lines: REACH-compliant grades for European destinations and legacy formulations for other markets. GB standards for food packaging materials govern domestic polymer migration limits. Shanghai and Jiangsu province concentrate extrusion capacity serving global quick-service restaurant supply chains.
Brazil
Protein export packaging demand in São Paulo state is driving specification for moisture-resistant coated board in frozen beef and poultry distribution. ANVISA regulates food-contact polymer barriers for domestic consumption and export qualification. The Campinas industrial corridor hosts the primary converter base serving Mercosur dairy and meatpacking operations.
Poly Coated Paperboard Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable coating specializations and regional recycling partnerships. The vendor base stratifies across integrated pulp-to-board operators, independent extrusion specialists, and downstream converters with captive coating lines. Three archetypes dominate: fiber-integrated multinationals with captive pulp supply, regional specialists with recycled-fiber integration capabilities, and technology-focused players with multi-resin extrusion competence. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification timelines extend.
Among integrated fiber-to-board operators, WestRock, Mondi Group, and Smurfit Kappa exemplify scale-driven positioning. WestRock represents the archetype of captive pulp supply married to integrated extrusion infrastructure. Mondi Group occupies a position emphasizing lightweighting R&D in barrier-coated formats. Smurfit Kappa anchors the recycled-fiber integration tier with regional mill network density across Iberia and the Nordics.
| Leading Market Players |
|---|
| WestRock |
| Stora Enso |
| Smurfit Kappa |
| Graphic Packaging International |
| International Paper Company |
| Mondi Group |
| Tetra Pak |
| Sappi Ltd |
| Nippon Paper Industries |
| Others |
Value Chain & Pricing Dynamics
Crude-linked polyethylene resin indices cascade through converter pricing tiers, compressing margins for extrusion specialists locked into annual contracts without pass-through mechanisms while rewarding integrated operators with captive pulp supply. FDA food-contact notification costs and EU extended producer responsibility fees concentrate pricing power among multinationals capable of absorbing compliance overhead across high-volume quick-service restaurant contracts.
Pricing Analysis
Input-cost pass-through clauses dominate contract structures for North American and European converters, though annual lock-ins without resin escalation triggers expose mid-cap extrusion specialists to margin erosion when polyethylene benchmarks spike. Pricing stratifies across premium double-sided coated grades for frozen-food trays, standard single-sided formats for dairy cups, and economy uncoated fiber substrates for dry-food sleeves. Cost compression in standard tiers intensifies as Indian domestic capacity ramps and import substitution hardens. Quick-service restaurant procurement teams exhibit highest price sensitivity, while healthcare sterilization tray buyers prioritize barrier performance over unit economics.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale quick-service restaurant demand, while distributor networks serve regional dairy and frozen-food processors with fragmented order patterns. Raw material supply concentrates in the United States, Sweden, and Finland for bleached kraft pulp, with polymer resin feedstocks drawing from Gulf Coast petrochemical complexes and Middle Eastern crude derivatives. Extrusion line equipment and coextrusion die systems hinge on German and Italian engineering suppliers. Single-source polyethylene procurement remains a structural vulnerability as geopolitical disruptions strain resin allocation protocols. Distribution runs through integrated mill-direct relationships for volume buyers and regional paper merchants for smaller converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable coating premiums and lightweighting R&D as brand-owner sustainability scorecards harden qualification thresholds and fiber-yield economics improve. Coat-weight reduction below 250 gsm without barrier performance degradation offers the clearest path to cost-down capture.
For Market Incumbents: Hedge polyethylene price volatility through backward integration into pulp supply or long-term resin offtake agreements with Gulf Coast producers. Invest in multi-resin extrusion capability to defend positioning as EU Packaging and Packaging Waste Regulation amendments accelerate specification shifts away from conventional polyethylene barriers. Prioritize certification auditing and closed-loop collection partnerships to maintain quick-service restaurant procurement access as chain-level sustainability scorecards consolidate supplier rosters. For New Entrants and Emerging Players: The premium-to-economy price gap in double-sided coated grades creates entry space for domestic Indian producers targeting Maharashtra and Gujarat cold-chain dairy expansion. Capture share in biodegradable polymer barrier segments where FDA notification timelines have stalled multinational qualification cycles. Pursue co-development partnerships with quick-service restaurant suppliers in Germany and France automating water-based plant-derived coating lines. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-focused converters possessing multi-resin extrusion competence and verified recyclability certifications. Five-to-ten year viability favors assets with lightweighting R&D pipelines and regional recycling infrastructure partnerships over commodity extrusion capacity. Monitor EU REACH amendment implementation timelines as the inflection signal for accelerated specification turnover toward compostable barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Resin Extrusion Line Retrofit | Enables compliance with EU Packaging and Packaging Waste Regulation amendments penalizing single-resin polyethylene structures. |
| Lightweighting R&D Partnership | Reduces fiber consumption per unit while maintaining grease resistance for protein tray specifications below 250 gsm. |
| Closed-Loop Collection Partnership | Qualifies converters for quick-service restaurant sustainability scorecards requiring verified recyclability chain-of-custody documentation. |
| Domestic Indian Capacity Buildout | Captures first-mover positioning in Maharashtra and Gujarat as cold-chain dairy distribution penetrates tier-2 cities. |
| Biodegradable Coating Certification Investment | Accelerates FDA food-contact notification timelines for novel plant-derived barriers competing with conventional polyethylene. |
Study Parameters
Direct dialogue with extrusion line operators, quick-service restaurant procurement directors, FDA regulatory consultants, and recycling facility managers grounded qualitative insights in operational reality. Secondary validation drew from FDA food-contact substance notifications, EU Packaging and Packaging Waste Regulation amendment drafts, BIS certification records for Indian food-contact articles, and SEC filings of integrated pulp-to-board operators. Bottom-up and top-down triangulation cross-checked installed extrusion capacity estimates against end-use demand segmentation.
Bottom-up modeling built from individual mill capacity, coat-weight specifications, and regional regulatory compliance cost structures, while top-down approaches validated aggregate market sizing against macro consumption trends in quick-service restaurant and frozen-food distribution. Segmentation dimensions spanned product type, end-use application, thickness class, and coating material chemistry across the projection horizon. CAGRs derived from regression analysis of historical capacity expansion, regulatory implementation timelines, and substitution elasticity between conventional and biodegradable barrier systems. Forecast inputs incorporated cold-chain infrastructure investment pipelines in India and EU extended producer responsibility penalty schedules.
The model assumes a particular technology adoption path for water-based plant-derived barrier coatings; alternative pathways for fluorochemical-free grease barriers would alter the outlook if high-temperature fried-food performance gaps close faster than projected. Forecasts reflect assumptions around FDA notification review period stability and mechanical recycling infrastructure deployment rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market