
 United States Ampoules Packaging Market | 2026-2036
United States Ampoules Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ampoules Packaging Market Analytics
The gap between premium borosilicate glass ampoules and commodity soda-lime alternatives is expanding as biologics manufacturers reject lower-grade materials for temperature-sensitive injectables. Gerresheimer AG leverages its vertical integration from tubing to finished ampoules to sustain quality consistency across FDA-regulated batches. Schott AG anchors the high-end segment with FIOLAX borosilicate tubing that dominates parenteral packaging specifications.
United States Ampoules Packaging refers to small sealed vials, typically holding 1–20 mL, manufactured from Type I borosilicate glass or pharmaceutical-grade polymers through forming, annealing, and surface treatment processes; they provide hermetic sterile containment for liquid pharmaceuticals requiring protection from oxidation and microbial ingress. Glass Ampoules retain the largest volume share due to USP <660> compliance mandates for injectable drug stability, while Plastic Ampoules are gaining traction in emergency medicine and military field kits where breakage resistance outweighs gas-barrier concerns. Breakable Ampoules still lead hospital pharmacy procurement for single-dose anesthetics and contrast agents, though Non-Breakable Ampoules with scored neck designs are displacing traditional snap-open formats in home-injection therapies.
FDA container closure integrity testing under USP <1207> and updated guidance on leachables and extractables are forcing manufacturers toward higher-purity glass compositions and validated polymer alternatives. OSHA needlestick prevention standards and EPA pharmaceutical waste rules further shape ampoule design specifications for break resistance and disposal classification. Stakeholders must monitor how FDA's advancing quality-by-design expectations for sterile packaging will reshape supplier qualification timelines and capital allocation across domestic manufacturing networks.
Market Dynamics
FDA's updated container closure guidance for sterile drug products is tightening material compatibility requirements across domestic manufacturing networks, forcing ampoule suppliers toward higher-purity glass compositions and validated polymer alternatives.
Growth Catalysts
- Biologics expansion:Biologics manufacturers are expanding their use of pre-sterilized single-dose glass ampoules to reduce contamination risk in temperature-sensitive injectables. This end-use vertical now dominates procurement specifications for parenteral packaging.
- USP 1207 compliance mandates:FDA container closure integrity testing under USP 1207 is accelerating qualification timelines for hermetic sterile containment systems. Suppliers with validated testing protocols capture disproportionate share of new drug filings.
- Northeast pharmaceutical corridor concentration:Demand concentrates in the pharmaceutical corridor spanning New Jersey and Massachusetts, where contract manufacturing organizations cluster near major biopharma headquarters.
Market Restraints
- FIOLAX tubing supply concentration:High-end borosilicate glass ampoule production depends on concentrated European tubing supply, creating vulnerability to transatlantic logistics disruptions and currency volatility.
- EPA pharmaceutical waste classification:Stricter disposal rules for glass ampoules containing residual drug product elevate end-of-life costs and complicate hospital waste management protocols.
- Plastic barrier performance limitations:Pharmaceutical-grade polymers cannot match Type I borosilicate gas-barrier properties for oxidation-sensitive biologics, restricting substitution in premium applications.
Strategic Opportunities
- Home-injection therapy formats:Non-Breakable Ampoules with scored neck designs are displacing traditional snap-open formats in patient-administered therapies, opening retail pharmacy and direct-to-patient channels.
- Military and emergency medicine kits:Plastic Ampoules are gaining traction in field-deployed medical units where breakage resistance outweighs gas-barrier concerns, creating specialized procurement programs.
- OSHA needlestick prevention alignment:Ampoule designs incorporating integrated safety features can capture hospital pharmacy contracts subject to federal workplace safety standards.
Industry Challenges
- Quality-by-design validation timelines:FDA's advancing expectations for sterile packaging documentation are extending supplier qualification periods and tying up regulatory affairs capacity.
- Annealing process energy intensity:Glass ampoule manufacturing requires sustained high-temperature thermal processing, exposing producers to natural gas price volatility and emissions compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ampoules Packaging Market |
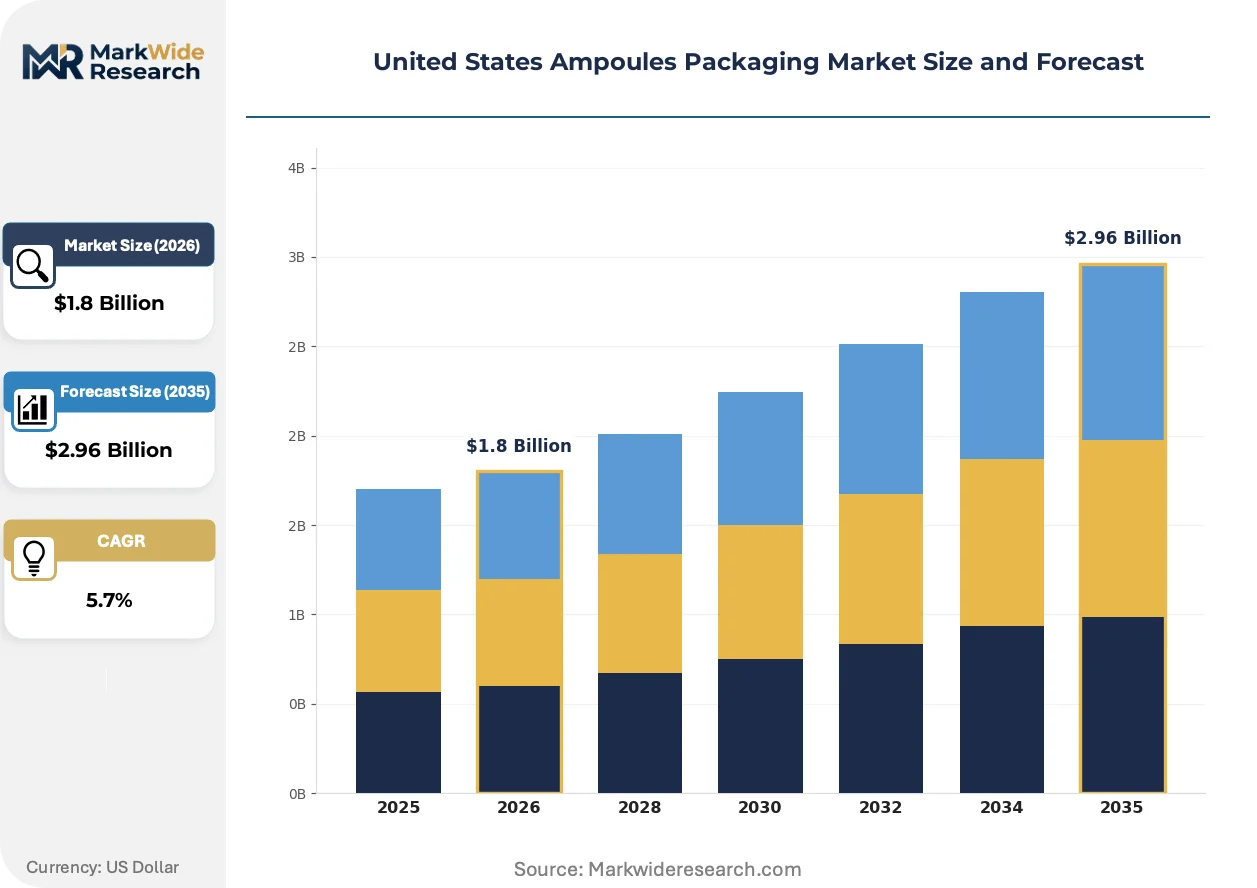
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Ampoules, Plastic Ampoules, Breakable Ampoules, Non-Breakable Ampoules End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Hospitals Packaging Type: Single Dose, Multi Dose, Customized Solutions, Standard Size Closure Type: Crimped, Screw Cap, Twist-Off, Others |
| Companies Covered | James Alexander Corporation, Nipro Pharma Packaging International NV, Schott AG, Accu-Glass LLC, J Penner Corporation, Gerresheimer AG, Wheaton Group (DWK Life Sciences Inc.), ESSCO Glass, Stevanato Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ampoules Packaging Market Evolving Landscape
Material science advances and regulatory precision are compressing the acceptable performance window for ampoule packaging, eliminating marginal suppliers and rewarding manufacturers with captive control over raw material quality.
Pre-sterilized ready-to-use (RTU) glass ampoules are rewriting procurement specifications for parenteral drug manufacturers. Biologics producers with fill-finish operations in the Northeast corridor are adopting RTU formats at accelerated pace to eliminate in-house washing and depyrogenation steps. This technology is compressing supplier qualification timelines and consolidating purchasing power among vertically integrated packaging providers.
USP 660 and USP 1207 harmonization is elevating glass chemistry requirements for injectable drug stability. The industrial consequence is rejection of commodity soda-lime alternatives by temperature-sensitive biologics manufacturers. Parenteral packaging specifications now mandate Type I borosilicate compositions, with suppliers lacking validated surface treatment processes excluded from FDA-regulated batches.
Hospital pharmacy procurement is consolidating around single-dose formats with integrated safety features. Group purchasing organizations are unbundling traditional supply contracts and awarding dedicated ampoule programs to manufacturers with OSHA-compliant break-resistant designs. This pattern is most visible in Massachusetts and New Jersey health systems leading workplace safety compliance.
United States Ampoules Packaging Market Segmentation
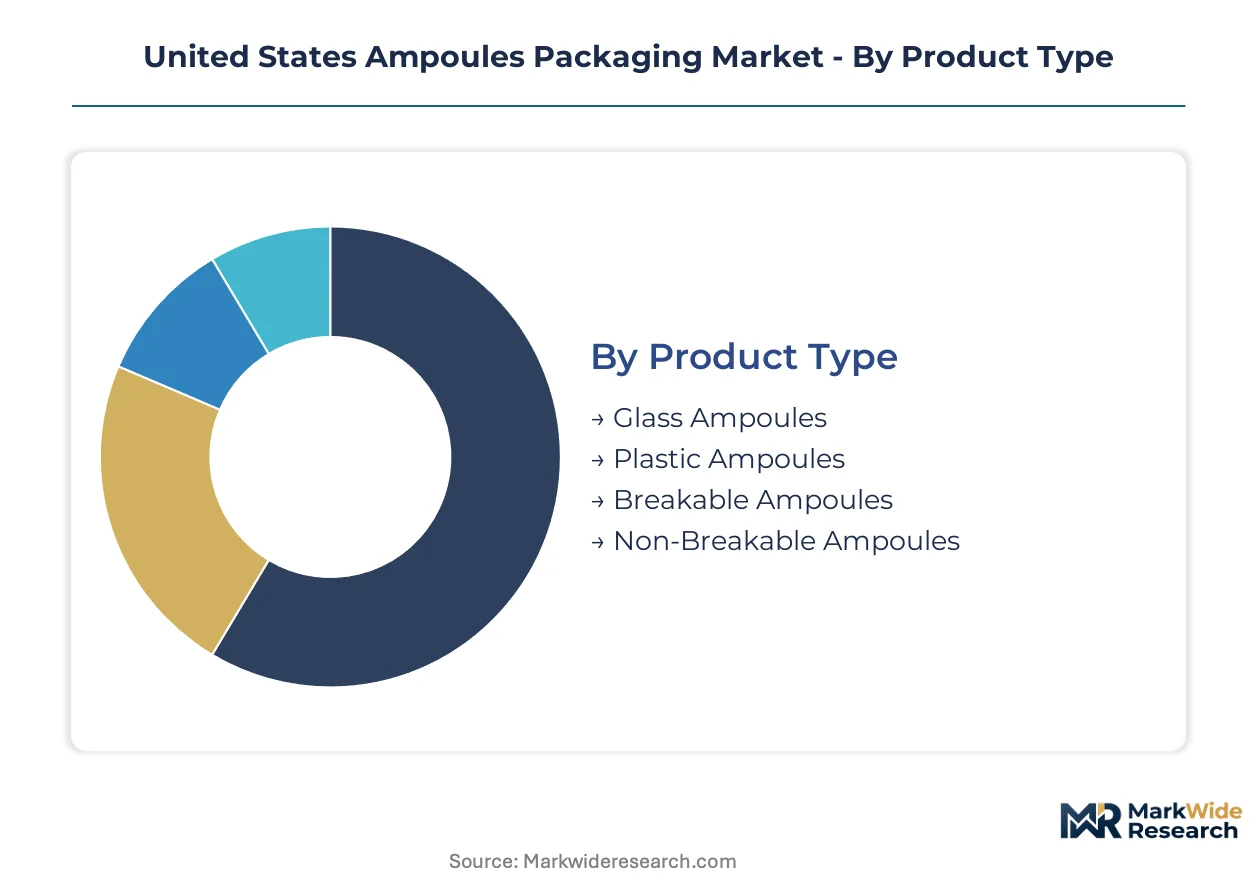
Ampoule packaging specifications diverge sharply across end-use contexts, with FDA compliance tiers and material science capabilities determining viable supplier participation. Each segmentation axis reveals distinct procurement patterns and qualification barriers that shape competitive positioning.
Product Type:
Type I borosilicate chemistry and mechanical durability specifications define supplier capability tiers.
- Glass Ampoules:USP 660 mandates Type I borosilicate compositions for parenteral stability, concentrating procurement among tubing-integrated manufacturers serving New Jersey and Massachusetts biopharma clusters. FDA container closure integrity testing under USP 1207 disqualifies suppliers lacking validated annealing and surface treatment protocols.
- Plastic Ampoules:Pharmaceutical-grade polymers trade gas-barrier performance for impact resistance, finding traction in military field kits and emergency medicine where breakage tolerance outweighs oxidation protection. Cyclic olefin copolymer formulations are displacing polypropylene in pre-filled syringe-compatible designs.
- Breakable Ampoules:Traditional snap-open formats dominate hospital pharmacy procurement for single-dose anesthetics and contrast agents.
- Non-Breakable Ampoules:Scored neck designs are gaining share in home-injection therapies requiring patient-safe opening mechanisms.
Glass Ampoules lead on scale; Plastic Ampoules lead on momentum.
End User:
Regulatory sophistication and volume scale separate procurement tiers across the pharmaceutical value chain.
- Pharmaceutical Companies:Fill-finish operations in the Northeast corridor demand pre-sterilized RTU formats with documented closure integrity validation, compressing supplier qualification timelines to 18-24 months. Merck and Pfizer procurement specifications now mandate vertical tubing-to-ampoule traceability.
- Biotechnology Firms:Temperature-sensitive biologics manufacturers reject soda-lime alternatives entirely, sourcing exclusively from Schott AG and Gerresheimer AG for FIOLAX-derived borosilicate. Cell and gene therapy startups are accelerating adoption of non-breakable scored formats for patient-administered therapies.
- Research Laboratories:Lower volume requirements and less stringent USP compliance enable broader supplier participation.
- Hospitals:Group purchasing organizations in Massachusetts and New Jersey health systems are unbundling ampoule contracts around OSHA needlestick prevention alignment.
Pharmaceutical Companies anchor procurement volume; Biotechnology Firms drive specification escalation fastest.
Packaging Type:
Unit-dose sterility assurance and dosing flexibility requirements shape format selection.
- Single Dose:Pre-sterilized hermetic containment eliminates in-house depyrogenation for biologics manufacturers, with RTU glass formats capturing Northeast contract manufacturing organization procurement. FDA quality-by-design expectations favor validated single-dose systems with documented container closure integrity.
- Multi Dose:Preservative-compatible formats retain niche position in veterinary and certain generic injectable applications where cost sensitivity outweighs sterility assurance premium.
- Customized Solutions:Patient-specific dosing and combination product integration are expanding fastest among cell therapy developers requiring non-standard fill volumes.
- Standard Size:1-10 mL formats dominate commodity procurement for established small-molecule injectables.
Single Dose commands revenue concentration; Customized Solutions climbs the fastest.
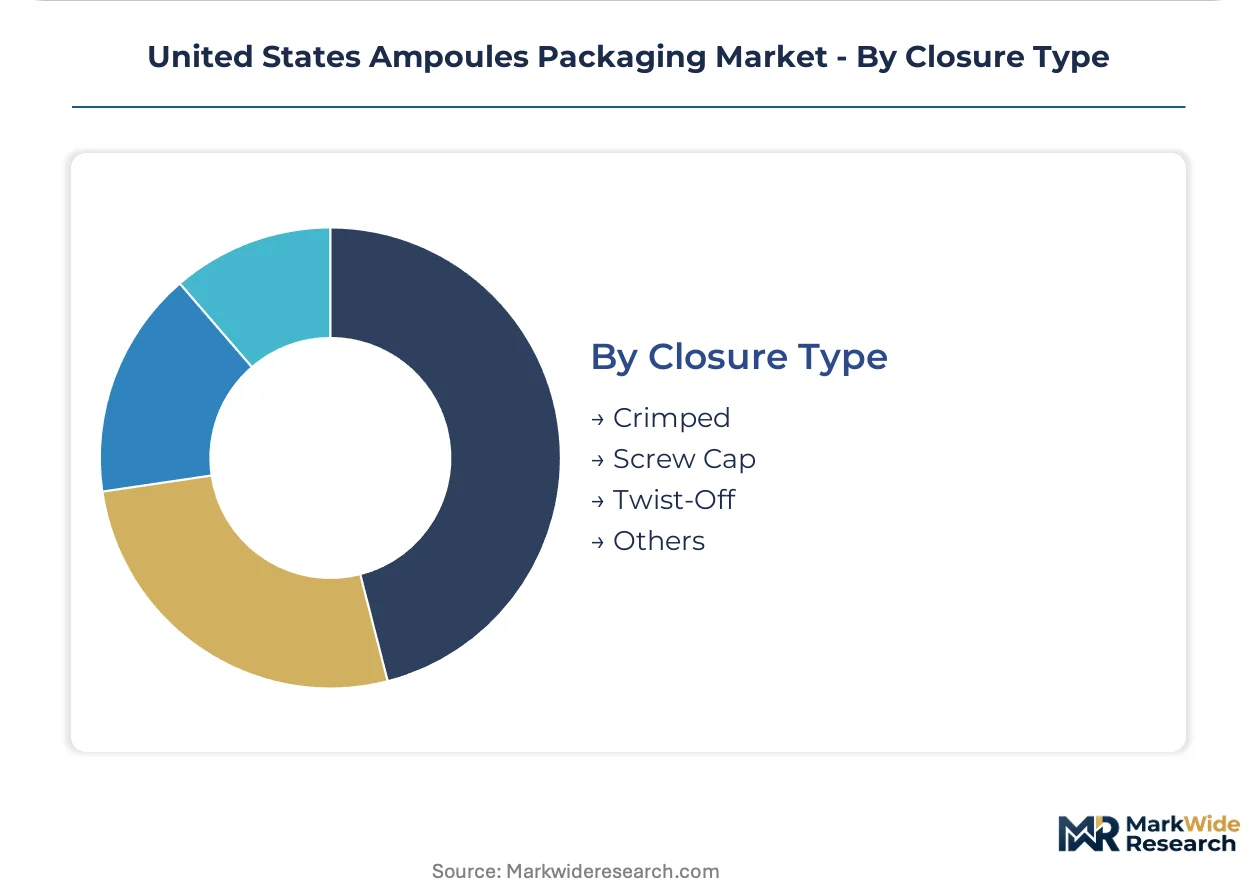
Closure Type:
Opening mechanics and seal integrity specifications determine end-use compatibility.
- Crimped:Aluminum seal systems provide tamper-evident hermetic closure for parenteral drugs requiring extended shelf stability, dominating FDA-regulated biologics packaging.
- Screw Cap:Reclosable formats suit multi-dose ophthalmic and diagnostic applications where repeated access is required.
- Twist-Off:Integrated plastic or composite closures are displacing traditional break-tips in field medicine and home care where controlled opening force reduces contamination risk.
- Others:Peel-off foil and snap-cap variants serve specialized diagnostic and veterinary segments.
Crimped retains specification dominance; Twist-Off gains share fastest in patient-administered formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glass-forming technicians and pharmaceutical packaging engineers concentrate in the Northeast pharmaceutical corridor, anchoring domestic ampoule production capacity.
New Jersey
Contract manufacturing organizations cluster near Princeton and Newark, driving demand for pre-sterilized RTU glass formats. FDA's updated container closure guidance tightens material compatibility requirements for sterile drug products. Merck and Pfizer procurement specifications mandate vertical tubing-to-ampoule traceability across fill-finish operations.
Massachusetts
Biotechnology firms in Cambridge and Boston reject soda-lime alternatives entirely for temperature-sensitive biologics. OSHA needlestick prevention standards shape hospital pharmacy procurement for single-dose anesthetics. Cell and gene therapy startups accelerate adoption of non-breakable scored formats for patient-administered therapies.
Pennsylvania
Generic injectable manufacturers in Philadelphia suburbs source standard 1-10 mL formats for established small-molecule drugs. EPA pharmaceutical waste rules elevate end-of-life costs for glass ampoules containing residual drug product. Group purchasing organizations consolidate contracts around OSHA-compliant break-resistant designs.
North Carolina
Emerging biologics manufacturing in Research Triangle Park expands demand for Type I borosilicate compositions. USP 1207 compliance mandates accelerate qualification timelines for hermetic sterile containment systems. Contract development and manufacturing organizations build fill-finish capacity to serve Southeast pharmaceutical distribution networks.
California
Specialty pharmaceutical developers in South San Francisco and San Diego adopt customized ampoule solutions for combination products. California's pharmaceutical waste regulations exceed federal EPA standards for disposal classification. Biologics startups prioritize patient-safe opening mechanisms for home-injection therapies.
United States Ampoules Packaging Market Competitive Landscape
Top-tier vendors anchor premium borosilicate supply, while mid-scale fabricators compete on qualification speed and regional proximity. The market structures around tubing-integrated manufacturers with captive glass chemistry control, specialty converters serving niche formats, and diversified packaging conglomerates with broad pharmaceutical portfolios. Dominant competitive moves include backward integration into tubing production and strategic partnerships with Northeast contract manufacturing organizations.
Among German-origin specialists, Schott AG and Gerresheimer AG exemplify the premium-tier archetype through FIOLAX-derived borosilicate chemistry. James Alexander Corporation occupies a position within the specialized converter segment. Nipro Pharma Packaging International NV represents the diversified Asian industrial group model with pharmaceutical packaging breadth.
| Leading Market Players |
|---|
| James Alexander Corporation |
| Nipro Pharma Packaging International NV |
| Schott AG |
| Accu-Glass LLC |
| J Penner Corporation |
| Gerresheimer AG |
| Wheaton Group (DWK Life Sciences Inc.) |
| ESSCO Glass |
| Stevanato Group |
| Others |
Value Network & Pricing Analysis
FDA's updated container closure guidance for sterile drug products is forcing biologics manufacturers toward pre-sterilized RTU formats with documented USP 1207 validation, compelling suppliers to absorb qualification cost burdens and compress margins on commodity-grade alternatives while capturing premiums on validated borosilicate systems.
Pricing Analysis
The bundled-vs-unbundled service split separates tubing-integrated manufacturers from component converters. Three-tier pricing structure across premium FIOLAX-derived borosilicate, validated standard glass, and commodity soda-lime alternatives reflects certification grade and vertical integration depth. Cost compression in commodity tiers is intensifying because European tubing supply concentration exposes converters to currency volatility and transatlantic logistics premiums. Generic injectable manufacturers in Pennsylvania exhibit highest price sensitivity; biotechnology firms in Massachusetts accept premium pricing for traceability-assured supply.
Supply Chain Analysis
Domestic-content mandates under FDA quality-by-design expectations are reshaping sourcing toward vertically integrated North American production. High-end borosilicate ampoule manufacturing draws from concentrated European tubing supply, primarily Germany and Czech Republic, with emerging North Carolina fill-finish capacity feeding Southeast distribution networks. Single-source vulnerability in FIOLAX tubing creates structural exposure to transatlantic shipping disruptions. Distribution runs through Northeast pharmaceutical corridor contract manufacturing organizations with direct procurement relationships to Merck and Pfizer fill-finish operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Ampoules Packaging Market functions as a regulatory compounder where FDA's advancing USP 660 and USP 1207 harmonization continuously escalates entry barriers and consolidates procurement around validated suppliers.
For Market Incumbents: Hedge against European tubing supply concentration by securing captive North American glass chemistry capacity or long-term offtake agreements with Schott AG and Gerresheimer AG. Invest in RTU format validation infrastructure to compress 18-24 month qualification timelines for Northeast contract manufacturing organizations. Biologics specification escalation threatens commodity soda-lime positioning; backward integration into tubing production defends margin structure. For New Entrants and Emerging Players: Contract manufacturing organizations in North Carolina's Research Triangle Park represent the most penetrable channel partner type for regional qualification speed advantages. Target military field kit procurement programs for plastic ampoule formats where breakage resistance outweighs gas-barrier requirements. Pursue OSHA-compliant break-resistant designs for Massachusetts and New Jersey hospital pharmacy contracts unbundling from traditional group purchasing organizations. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing validated surface treatment protocols and regional proximity to Northeast biopharma clusters. Long-term viability favors acquisition targets with demonstrated FDA batch approval history and captive tubing relationships. Monitor USP 1207 enforcement intensity as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tubing Production | Captive FIOLAX-derived borosilicate supply secures FDA batch consistency against European logistics disruptions. |
| RTU Format Validation Investment | Eliminates customer in-house depyrogenation steps, compressing Gerresheimer AG and Schott AG qualification timelines. |
| OSHA-Compliant Break-Resistant Design Development | Captures Massachusetts and New Jersey hospital pharmacy contracts subject to federal needlestick prevention standards. |
| North Carolina Manufacturing Footprint Expansion | Positions suppliers near Research Triangle Park biologics capacity to serve Southeast distribution networks. |
| Plastic Ampoule Military Procurement Program | Opens specialized channels for cyclic olefin copolymer formats in field-deployed medical units. |
Research Methodology
Direct dialogue with regulatory affairs leads at FDA-regulated fill-finish operations, procurement managers at New Jersey and Massachusetts contract manufacturing organizations, and hospital pharmacy directors at Massachusetts General and Hackensack Meridian Health grounded qualitative findings. Secondary validation drew from FDA 483 inspection observations, USP <660> and <1207> documentation, SEC 10-K filings of listed packaging suppliers, and pharmaceutical packaging trade association capacity surveys. Bottom-up volume estimates from individual facility throughput combined with top-down pharmaceutical production value triangulation anchored market sizing.
Segment-level projections across product type, end user, packaging format, and closure mechanism fed into analytical framework outputs across the projection horizon. CAGRs derived from regression against historical FDA new drug filings, biologics pipeline expansion rates, and Northeast pharmaceutical corridor capital expenditure announcements. Modeled inputs incorporated USP 1207 adoption curves, RTU format penetration assumptions, and OSHA needlestick compliance implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA quality-by-design guidance evolution, European tubing supply disruption scenarios, and natural gas price volatility affecting annealing process economics. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and biologics manufacturer specification escalation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Vaccine Packaging Market