
 China Pharmaceutical Packaging Market | 2026-2036
China Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Pharmaceutical Packaging Market Insights
Pharma-grade borosilicate glass certification is redrawing supplier hierarchies in China's pharmaceutical packaging sector. Gerresheimer Shuangfeng Pharmaceutical Glass leverages its Danyang furnace complex to dominate high-barrier vial output for injectables. Shandong Pharmaceutical Glass anchors domestic supply through captive soda-lime and borosilicate melting capacity. West Pharmaceutical Services differentiates via elastomeric closure integration with prefillable syringe systems.
China pharmaceutical packaging encompasses primary and secondary containment systems engineered to maintain sterility, chemical stability, and tamper evidence for drug products across distribution temperatures from minus eighty degrees Celsius to ambient conditions. Glass vials and aluminum-plastic blister foils serve biologics and oral solid dosages respectively, with barrier specifications measured in oxygen transmission rates and water vapor ingress. Blister packaging captures volume leadership through oral solid dispensing dominance, while plastic bottles accelerate in over-the-counter and pediatric liquid segments where child-resistant closure innovation determines placement. Metal collapsible tubes retain margin concentration in semi-solid dermatological applications despite slower volume expansion.
NMPA's updated pharmacopoeia chapters on glass delamination and particulate limits are disqualifying legacy soda-lime suppliers from biologics contracts. GB standards administered by SAMR mandate serialization-ready labeling infrastructure that packaging converters must embed at line level. China's dual carbon goals under MEE pressure energy-intensive glass melting operations toward electric furnace retrofits or natural gas substitution. Stakeholders must weigh backward integration into pharmaceutical-grade resin compounding against specialty converter partnerships as polymer-based alternatives gain NMPA approval momentum.
Market Dynamics
NMPA's tightened traceability mandates for injectable drugs are compressing supplier timelines and forcing material certification upgrades across China's pharmaceutical packaging value chain. This regulatory pressure is redrawing competitive hierarchies as legacy converters face disqualification from biologics contracts.
Growth Catalysts
- Biologics cold-chain expansion:mRNA and cell therapy manufacturers are scaling temperature-stable packaging orders from minus eighty degrees Celsius to two-to-eight degrees Celsius ranges.
- NMPA serialization mandates:Track-and-trace infrastructure requirements are accelerating converter investments in line-level labeling automation.
- Jiangsu manufacturing concentration:Taizhou and Suzhou pharmaceutical hubs are generating clustered demand for high-barrier primary packaging within a two-hundred-kilometer radius.
Market Restraints
- Borosilicate glass supply concentration:Domestic pharma-grade melting capacity remains captive to three furnace operators, creating input bottlenecks for vial converters.
- Energy cost volatility:Natural gas and electricity price swings under MEE dual carbon enforcement are compressing margins at energy-intensive glass melting operations.
- Legacy soda-lime delamination risk:NMPA pharmacopoeia updates on glass particulate limits are structurally excluding uncertified suppliers from high-value injectables segments.
Strategic Opportunities
- Polymer-based alternatives:Cyclic olefin polymer and multilayer coextrusion technologies are gaining NMPA approval momentum for biologics containment.
- Guangdong and Sichuan expansion:Underpenetrated southwestern and southern provinces present white space for secondary packaging converters serving regional distributors.
- Prefillable syringe integration:Combination product regulations are creating demand for elastomeric closure and needle safety system bundling.
Industry Challenges
- Pharma-grade resin compounding expertise:Converter talent gaps in polymer rheology and barrier layer design are delaying product qualification timelines.
- Serialization line retrofit capex:SAMR-mandated aggregation and verification infrastructure requires seven-figure capital commitments from mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pharmaceutical Packaging Market |
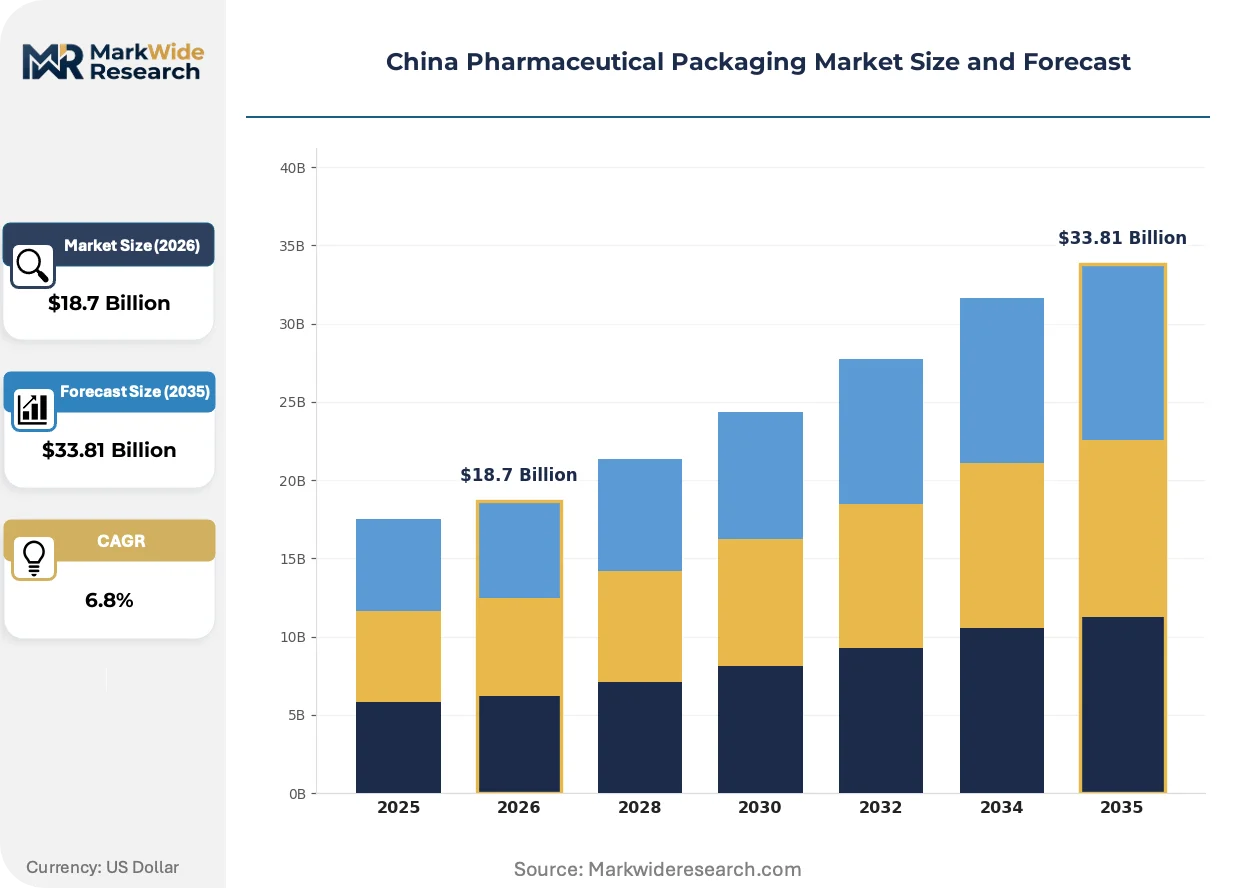
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blisters, Bottles, Vials, Pouches Material: Glass, Plastic, Paper, Metal End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Hospitals Form: Solid, Liquid, Semi-Solid, Powder |
| Companies Covered | Gerresheimer Shuangfeng Pharmaceutical Glass (Danyang) Co. Ltd, Shandong Pharmaceutical Glass Co. Ltd, West Pharmaceutical Services Inc., Amcor Plc, Taishan Xinhua Pharmaceutical Packaging Co. Ltd, Ningbo Zhengli Pharmaceutical Packaging, Perlen Packaging (Suzhou) Co. Ltd, Yuhuan Kang-jia Enterprise Co. Ltd, Jiangsu Hanlin Pharmaceutical Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pharmaceutical Packaging Market Trends and Innovations
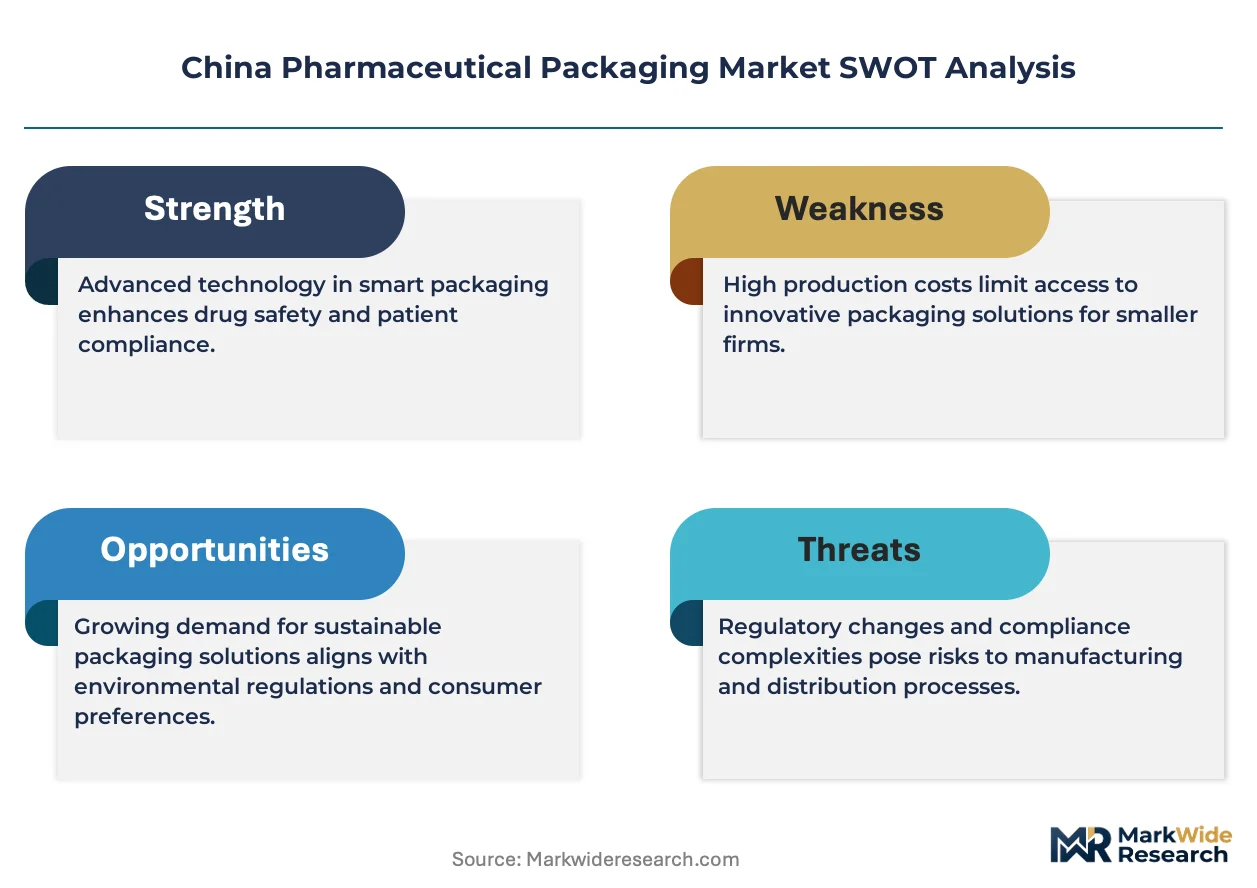
Active packaging intelligence and sustainable material transitions are fragmenting traditional converter business models. Regulatory pressure on traceability and carbon intensity is forcing simultaneous investment in digital infrastructure and furnace technology.
Smart labels with embedded temperature loggers and NFC authentication are fragmenting the commodity label segment. Biologics manufacturers in Jiangsu and Zhejiang are piloting these systems for cold-chain verification. The technology is compressing price premiums for standard printed labels while creating new service revenue streams around data analytics and compliance documentation.
NMPA's updated pharmacopoeia chapters on glass delamination and particulate limits are disqualifying uncertified soda-lime suppliers from biologics contracts. This regulatory friction is accelerating furnace upgrades toward electric melting or natural gas substitution. High-barrier vial converters with Danyang and Shandong melting assets are capturing displaced volume from legacy suppliers.
Hospital procurement consolidation through centralized volume-based purchasing is compressing converter margins on standard blister and bottle formats. Group purchasing organizations in tier-one cities are unbundling packaging from drug supply contracts. Pediatric liquid and over-the-counter segments in eastern coastal provinces are seeing accelerated switching to child-resistant closure specialists who can demonstrate compliance differentiation.
China Pharmaceutical Packaging Market Segmentation
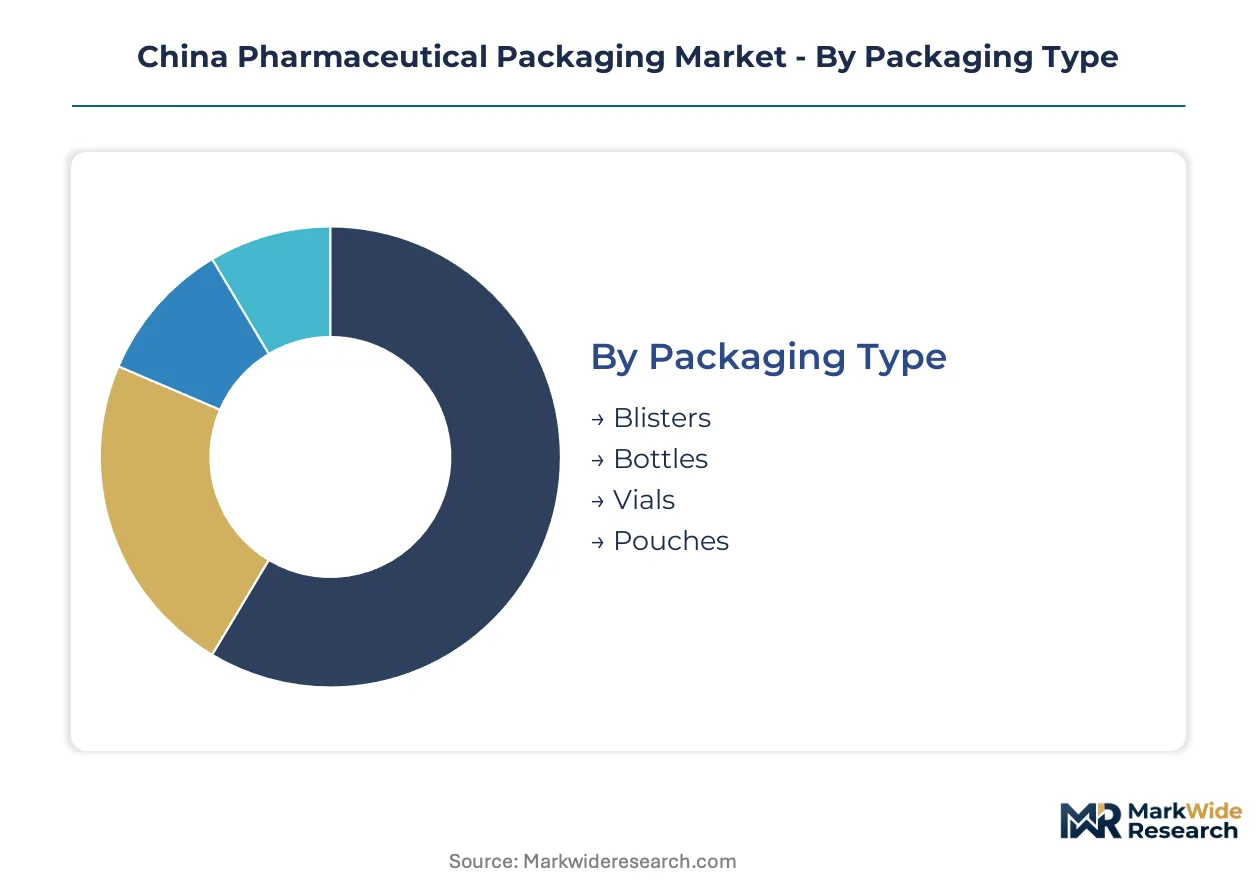
Packaging specification in China pharmaceutical markets is fragmenting across temperature stability, barrier performance, and serialization readiness. Each segment category carries distinct substitution threats from adjacent materials or formats.
Packaging Type:
Polymer-based alternatives are displacing glass in temperature-sensitive biologics, while aluminum-plastic laminates erode metal dominance in semi-solid applications.
- Blisters:Aluminum-plastic cold-form laminates and push-through PVC structures dominate oral solid dispensing. Demand clusters around Taizhou and Suzhou manufacturing hubs where high-speed thermoforming lines serve centralized procurement contracts.
- Vials:Borosilicate glass and cyclic olefin polymer formats maintain sterility for injectable biologics across minus eighty to two-to-eight degrees Celsius distribution ranges. NMPA pharmacopoeia updates on particulate limits are structurally excluding uncertified soda-lime suppliers from high-value segments.
- Bottles:High-density polyethylene and PET containers with child-resistant closures serve over-the-counter and pediatric liquid segments.
- Pouches:Multilayer coextrusion films with oxygen barrier layers address unit-dose powder and granule formats.
Blisters anchor the volume base while vials gain share at the steepest rate.
Material:
Cost tiers separate furnace-operating glass specialists from converter-dependent polymer and paper processors.
- Glass:Pharma-grade borosilicate and soda-lime melting operations concentrate at Danyang and Shandong furnace complexes. MEE dual carbon enforcement is compressing margins through natural gas and electricity price volatility.
- Plastic:Cyclic olefin polymer and multilayer coextrusion technologies are climbing fastest as NMPA approval momentum builds for biologics containment.
- Paper:Serialization-ready folding cartons and patient information leaflets serve secondary packaging functions.
- Metal:Aluminum collapsible tubes retain margin concentration in dermatological semi-solid applications despite slower volume expansion.
Glass captures the premium tier while plastic expands most quickly across mid-market applications.
End User:
Customer procurement scale determines converter qualification barriers and contract duration structures.
- Pharmaceutical Companies:Integrated manufacturers in Jiangsu province demand high-barrier primary packaging with embedded traceability infrastructure. SAMR-mandated serialization requires seven-figure line-level capital commitments from converter partners.
- Contract Manufacturers:CDMO facilities serving mRNA and cell therapy developers are scaling cold-chain compatible packaging orders.
- Research Laboratories:Clinical trial material packaging requires small-batch flexibility with temperature excursion documentation.
- Hospitals:Group purchasing organizations in tier-one cities are unbundling packaging from drug supply contracts.
Pharmaceutical companies dominate contract value while contract manufacturers are expanding orders fastest.
Form:
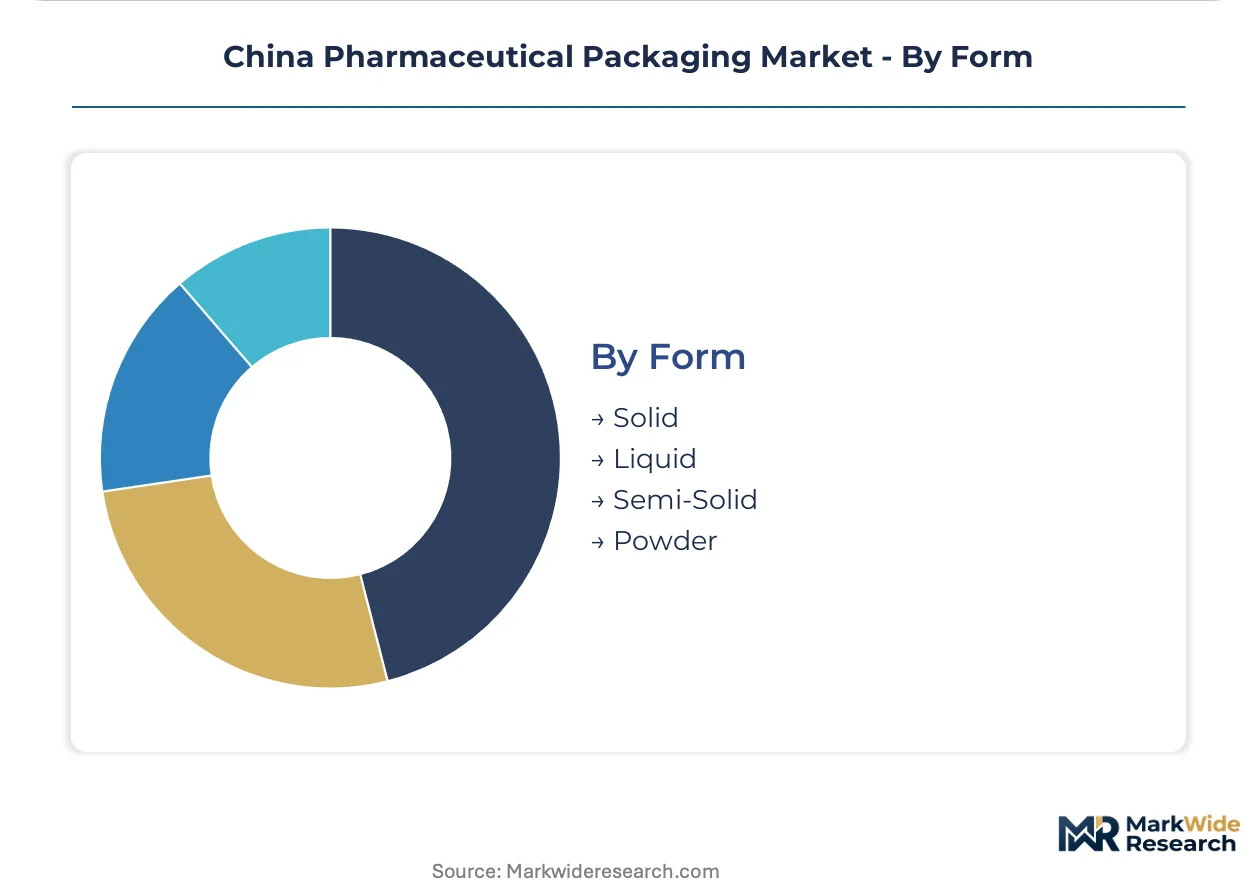
Physical state dictates barrier specification, with liquid and semi-solid formats demanding the most sophisticated containment engineering.
- Solid:Tablets and capsules in blister packs drive volume through oral solid dosage dominance.
- Liquid:Vials and bottles with elastomeric closures require particulate and extractables testing under NMPA pharmacopoeia chapters.
- Semi-Solid:Metal collapsible tubes and laminated pouches serve topical formulations with viscosity-specific dispensing requirements.
- Powder:Unit-dose sachets and stick packs address reconstitutable antibiotics and nutritional supplements.
Solid formulations anchor volume leadership while liquid formats command the highest per-unit packaging value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pharmaceutical packaging trade balance tilts toward import substitution in high-barrier glass while surplus capacity in secondary formats drives export competitiveness. Domestic borosilicate melting expansion is narrowing the deficit in pharma-grade vial inputs. Regional demand clusters concentrate in eastern coastal provinces where biologics manufacturing density is highest.
Jiangsu Province
Taizhou and Suzhou pharmaceutical hubs generate concentrated demand for high-barrier primary packaging within a two-hundred-kilometer radius. NMPA serialization mandates require line-level traceability infrastructure that converters must embed to serve these clusters. Suzhou-based CDMO facilities are scaling cold-chain compatible packaging orders for mRNA and cell therapy developers.
Shandong Province
Captive soda-lime and borosilicate melting capacity anchors domestic glass supply for oral solid and injectable formats. MEE dual carbon enforcement is pressuring energy-intensive furnace operations toward natural gas substitution or electric retrofits. Zibo and Jinan industrial corridors house integrated converters serving northern China's generic drug manufacturers.
Guangdong Province
Pearl River Delta contract manufacturers are piloting polymer-based alternatives for temperature-sensitive biologics containment. SAMR-mandated aggregation infrastructure is accelerating converter investments in secondary packaging automation. Shenzhen and Guangzhou distribution centers present white space for serialization-ready label and carton specialists.
Sichuan-Chongqing Region
Underpenetrated southwestern markets offer expansion opportunity for secondary packaging converters serving regional distributors. Chongqing's growing pharmaceutical manufacturing base is attracting blister and bottle suppliers from eastern provinces. Chengdu's hospital procurement consolidation is compressing margins on standard formats while creating entry points for compliance-differentiated specialists.
Zhejiang Province
Hangzhou and Ningbo biologics developers are driving demand for smart labels with embedded temperature loggers and NFC authentication. NMPA pharmacopoeia updates on glass particulate limits are disqualifying uncertified suppliers from high-value injectables contracts. Taizhou-Ningbo corridor converters with Danyang glass supply relationships are capturing displaced volume from legacy soda-lime operators.
China Pharmaceutical Packaging Market Competitive Landscape
Concentration sits with furnace-operating glass specialists who control captive borosilicate melting capacity. Three operators dominate pharma-grade vial input supply, creating structural bottlenecks for downstream converters. Strategic archetypes separate integrated furnace owners from converter-dependent polymer processors and elastomeric closure specialists. Capacity expansion and strategic partnerships represent the dominant competitive vectors as NMPA certification requirements harden.
Within the furnace-owning tier, Gerresheimer Shuangfeng Pharmaceutical Glass and Shandong Pharmaceutical Glass exemplify backward-integrated positioning through captive Danyang and Shandong melting assets. West Pharmaceutical Services occupies a differentiated position representing the elastomeric closure and prefillable syringe integration archetype. These three anchors illustrate how certification-grade melting capacity and combination product bundling are redrawing supplier hierarchies under tightened NMPA traceability mandates.
| Leading Market Players |
|---|
| Gerresheimer Shuangfeng Pharmaceutical Glass (Danyang) Co. Ltd |
| Shandong Pharmaceutical Glass Co. Ltd |
| West Pharmaceutical Services Inc. |
| Amcor Plc |
| Taishan Xinhua Pharmaceutical Packaging Co. Ltd |
| Ningbo Zhengli Pharmaceutical Packaging |
| Perlen Packaging (Suzhou) Co. Ltd |
| Yuhuan Kang-jia Enterprise Co. Ltd |
| Jiangsu Hanlin Pharmaceutical Packaging |
| Others |
Pricing and Supply Chain Analysis
Cyclic olefin polymer substitution for borosilicate glass in biologics containment is redrawing supply geography toward Guangdong polymer compounders while compressing pricing power at legacy soda-lime furnace operators across eastern China. NMPA approval momentum for these alternatives forces incumbent glass specialists to defend position through certification-tier differentiation rather than volume scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across certification-grade tiers. Price differentiation hinges on NMPA pharmacopoeia compliance level and captive melting capacity ownership, with uncertified converters facing steepest cost compression. Pricing pressure stems from hospital group purchasing organization consolidation in tier-one cities. Generic drug manufacturers in northern China exhibit highest price sensitivity, while biologics developers in Jiangsu demonstrate lowest sensitivity due to cold-chain performance requirements.
Supply Chain Analysis
Strategic stockpiling of pharma-grade borosilicate cullet dominates inventory strategy given furnace supply concentration. Geographic supply draws from China, Germany, and Japan for melting equipment and boron raw materials. Raw material dependencies center on high-purity silica sand, boron compounds, and natural gas feedstock. Single-source vulnerability sits with three domestic furnace operators controlling pharma-grade vial input supply. Distribution runs through converter networks clustered within two-hundred-kilometer radius of Taizhou and Suzhou pharmaceutical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as cyclic olefin polymers gain NMPA approval momentum for temperature-sensitive biologics containment, threatening legacy glass incumbents with structural volume displacement.
For Market Incumbents: Secure captive pharma-grade resin compounding capability or specialty converter partnerships to hedge polymer substitution threat. Deepen backward integration into electric furnace technology ahead of MEE dual carbon enforcement tightening. Certification investment in GB standards compliance represents the critical defensive lever against NMPA pharmacopoeia disqualification. For New Entrants and Emerging Players: Serialization-ready label and carton automation services present the most penetrable white-space target, as mid-tier converters lack seven-figure capital for SAMR-mandated line infrastructure. Guangdong and Sichuan secondary packaging markets offer lowest competitive density. A compliance-differentiated go-to-market angle targeting regional distributors outside Jiangsu manufacturing clusters accelerates initial contract capture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors furnace-owning specialists with NMPA-certified melting assets. Long-term viability over the next decade hinges on regulatory compliance durability rather than volume scale. Acquisition targets should demonstrate electric furnace retrofit progress or polymer barrier layer design expertise. Watch NMPA pharmacopoeia chapter revisions on glass particulate limits as the inflection signal for accelerated soda-lime displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Retrofit | MEE dual carbon enforcement is pressuring energy-intensive melting operations toward natural gas substitution or electric conversion. |
| Polymer Barrier Layer R&D | Cyclic olefin polymer qualification for mRNA cold-chain containment opens substitution pathways beyond traditional glass. |
| Serialization Line Automation | SAMR-mandated track-and-trace infrastructure requires seven-figure capital commitments that filter mid-tier converters. |
| Regional Converter Partnership | Underpenetrated southwestern markets present white space for secondary packaging specialists serving Sichuan-Chongqing distribution. |
| Prefillable Syringe Integration | NMPA combination product regulations create demand bundling opportunities for elastomeric closure and needle safety systems. |
Research Methodology
Cross-validation between primary fieldwork with pharmaceutical packaging converters and secondary validation through NMPA regulatory filings anchors the qualitative findings. Primary interviews engaged regulatory affairs directors at CDMO facilities, procurement managers at Jiangsu biologics manufacturers, furnace operations heads at Danyang and Shandong complexes, and serialization automation specialists. Secondary sources incorporated SAMR GB standards documentation, MEE environmental enforcement circulars, customs trade data on borosilicate glass imports, and SEC filings of listed packaging converters. Bottom-up demand modeling across dosage formats triangulated with top-down market sizing from production capacity assessments.
Sensitivity analysis around NMPA approval timelines for polymer alternatives and MEE carbon enforcement stringency brackets the projection range. The analytical framework segments by packaging type, material grade, end-user procurement scale, and physical formulation state across the modeling period. CAGRs derive from production capacity expansion schedules, regulatory qualification timelines, and hospital procurement contract renewal cycles. Forecast inputs incorporate furnace utilization rates at Danyang and Shandong complexes and cold-chain packaging order volumes from mRNA developers.
Material uncertainties — NMPA pharmacopoeia revision timing, MEE dual carbon enforcement intensity, polymer barrier layer qualification success rates — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory continuity and technology substitution pace. Revision becomes warranted when NMPA glass particulate limits tighten beyond current draft thresholds or when polymer approval momentum accelerates past modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Nutraceutical Packaging Market