
 Latin America Pharmaceutical Packaging Market | 2026-2036
Latin America Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Packaging Market Foresight
Buyer consolidation among Brazilian and Mexican generic pharmaceutical manufacturers is realigning procurement volumes toward full-service packaging suppliers. Amcor Group GmbH leverages its regional film extrusion network to supply high-barrier blister laminates across São Paulo and Querétaro. Gerresheimer AG anchors glass primary packaging demand through its molded vial capacity serving injectable producers. Berry Global Inc. competes in polyethylene bottle segments where cost sensitivity drives material substitution.
Latin America pharmaceutical packaging encompasses primary and secondary containment systems engineered to protect drug stability, ensure patient safety, and comply with serialization requirements, with specifications including moisture vapor transmission rates below 0.5 g/m²/day for high-barrier blisters and child-resistant closure torque standards. Blister packs lead value contribution due to unit-dose compliance packaging growth in chronic disease categories, while glass vials sustain premium positioning in temperature-sensitive biologics requiring USP Type I borosilicate integrity. Polypropylene bottles are displacing polyethylene in liquid oral applications where dimensional stability and autoclave compatibility matter.
ANVISA in Brazil mandates item-level traceability for prescription medicines, compelling packaging line investments in aggregation-capable serialization equipment. Mexico's COFEPRIS aligns with PIC/S guidelines for sterile product container closure integrity, elevating demand for pre-sterilized ready-to-use vials. Stakeholders must monitor regulatory harmonization progress between Mercosur and PA member states to anticipate divergence in primary packaging certification requirements.
Market Dynamics
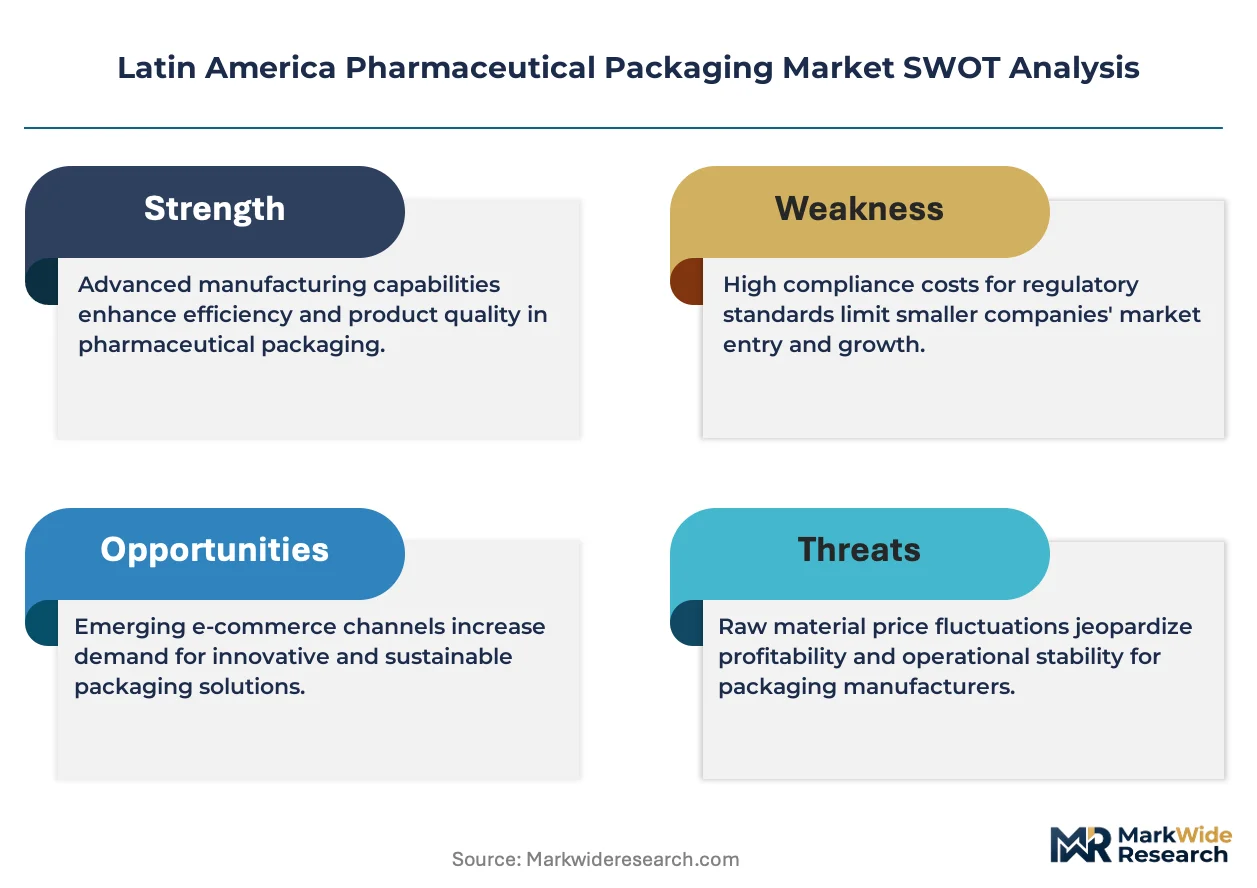
ANVISA's serialization mandates and COFEPRIS's sterile integrity standards are compressing supplier qualification timelines while concentrating procurement among full-service packaging integrators capable of dual-jurisdiction compliance.
Growth Catalysts
- Traceability mandates:ANVISA's item-level serialization requirements for prescription medicines are forcing line retrofits that favor aggregation-capable equipment suppliers.
- Biologics expansion:Temperature-sensitive injectables in Brazil's São Paulo corridor are sustaining demand for USP Type I borosilicate glass vials with validated cold-chain integrity.
- Chronic disease prevalence:Unit-dose compliance packaging for hypertension and diabetes medications is accelerating blister pack conversion from bulk bottles in Mexican retail pharmacies.
Market Restraints
- Resin import dependency:Polyethylene and polypropylene feedstock volatility ties Latin American converters to US Gulf Coast petrochemical pricing swings.
- Equipment lead times:European serialization hardware manufacturers face 18-month delivery backlogs that stall Brazilian generic producers' ANVISA compliance deadlines.
- Aluminum foil concentration:High-barrier blister laminates rely on a narrow supplier base in São Paulo state, creating single-source vulnerability for regional drug manufacturers.
Strategic Opportunities
- Colombia's regulatory ascent:INVIMA's alignment with PIC/S standards is opening pre-sterilized ready-to-use vial demand among Bogotá's emerging injectable producers.
- Smart packaging convergence:Near-field communication tags combined with temperature loggers are enabling real-time cold-chain verification for biologics distributors.
- Hospital-direct channels:Bypassing traditional pharmaceutical wholesalers, packaging suppliers are contracting directly with Mexico's IMSS and Brazil's SUS procurement networks.
Industry Challenges
- Serialization engineering scarcity:Qualified technicians capable of integrating aggregation software with legacy filling lines command premium wages that strain mid-tier generic manufacturers.
- Dual-certification timelines:Achieving simultaneous ANVISA and COFEPRIS primary packaging approvals extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Packaging Market |
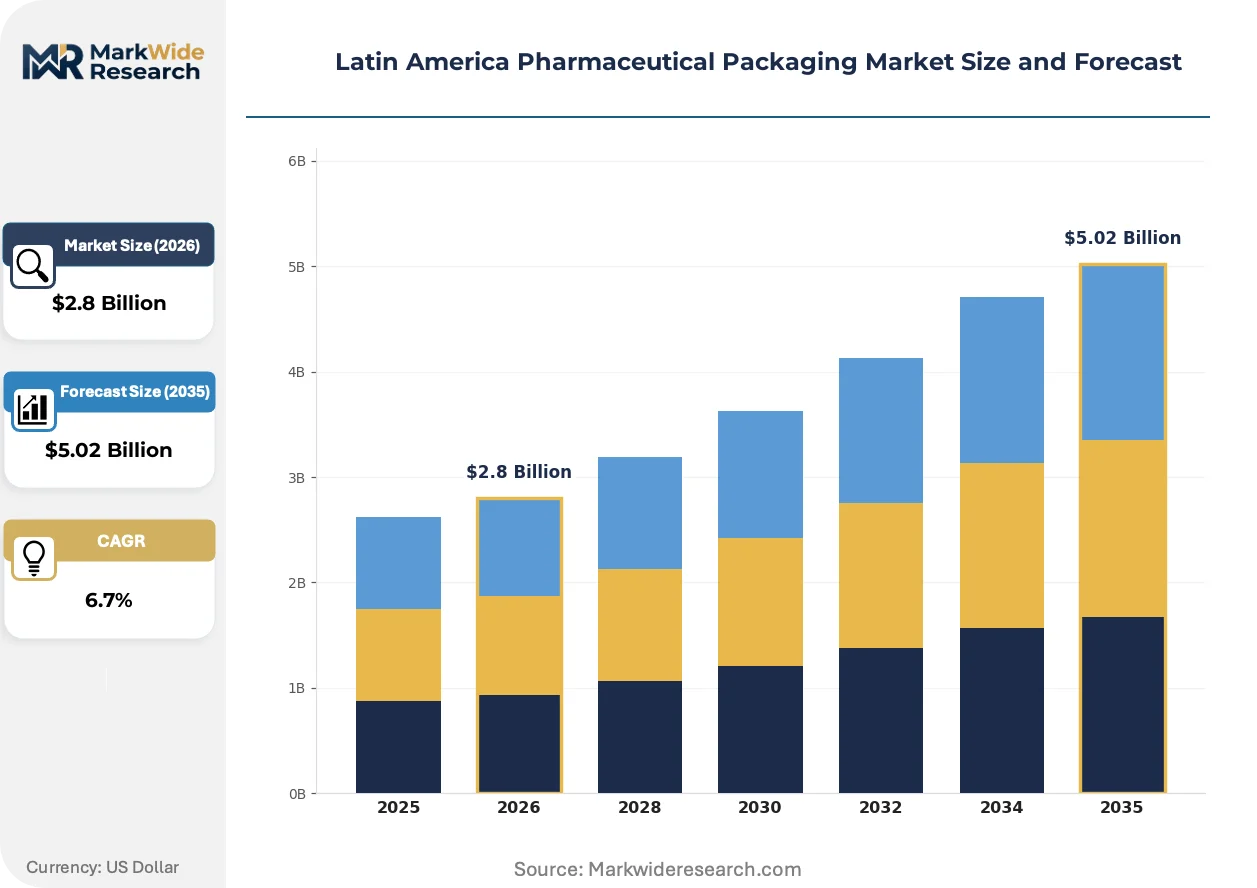
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blister Packs, Vials, Ampoules Material: Glass, Polyethylene, Polypropylene, Aluminum Closure Type: Screw Caps, Flip-Tops, Corks, Snap-Fit End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Retail Pharmacies |
| Companies Covered | Aptar Group Inc., Robert Bosch GmbH, Amcor Group GmbH, Marchesini Group S.p.A., Körber AG, Berry Global Inc., Gerresheimer AG, Multivac Group, Schott AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Packaging Market Shifts & Advancements
Packaging functionality is converging with digital traceability and sustainability mandates, forcing material science investments that reconcile barrier performance with recyclability targets.
Cyclic olefin polymers are integrating into pre-filled syringe barrels and vial alternatives where glass breakage risk and protein adsorption compete. Brazilian biologics producers are piloting COP primary containers for monoclonal antibody formulations. This substitution is integrating polymer suppliers into traditionally glass-dominated supply chains.
COFEPRIS's adoption of PIC/S Annex 1 sterile manufacturing guidelines is elevating container closure integrity testing to mandatory status for all parenteral products. Mexican injectable manufacturers must now validate seal integrity across distribution temperature excursions. The guideline revision is compressing qualification timelines for ready-to-use closure systems.
Hospital purchasing consortia are consolidating pharmaceutical packaging specifications to reduce SKU complexity and leverage volume pricing. Brazil's SUS regional procurement hubs and Mexico's IMSS central buying are standardizing on child-resistant closure torque ranges and blister cavity dimensions. This concentration is marginalizing bespoke packaging formats in favor of platform designs.
Latin America Pharmaceutical Packaging Market Segmentation
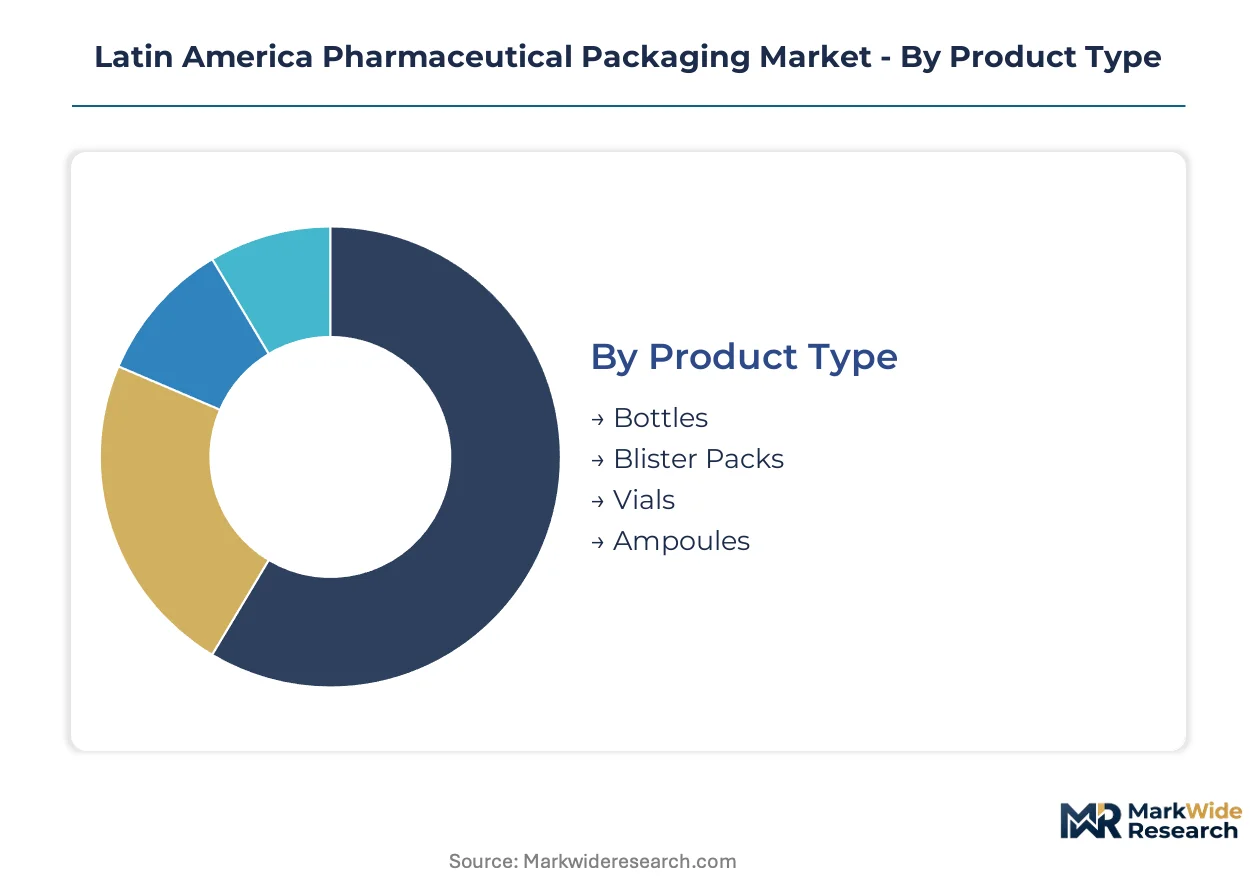
Pharmaceutical packaging segmentation in Latin America reflects divergent cost pressures between high-volume generic oral solids and premium biologics requiring validated cold-chain integrity. Material selection and closure specifications cluster around regulatory compliance thresholds rather than discretionary brand differentiation.
Product Type:
Volume-driven oral solid formats dominate procurement tonnage, while injectable containment commands per-unit premiums that reshape supplier margin profiles.
- Bottles:Polyethylene and polypropylene containers serve bulk oral solid dispensing across Brazilian retail pharmacy networks. São Paulo's generic manufacturers favor 60cc and 100cc HDPE bottles with induction-sealed liners to meet ANVISA child-resistance mandates at lowest unit cost.
- Blister Packs:Cold-form aluminum-PVC laminates and push-through foil configurations protect moisture-sensitive tablets in Mexico's chronic disease categories. Querétaro packaging lines are converting from bulk bottles to unit-dose blisters for hypertension medications as COFEPRIS tightens stability documentation requirements.
- Vials:Molded and tubular glass containers serve parenteral antibiotics and vaccines requiring USP Type I borosilicate integrity.
- Ampoules:Single-dose glass containers persist in hospital-administered injectables where immediate-use sterility overrides multi-dose convenience.
Today's leader: Blister Packs. Tomorrow's challenger: Vials.
Material:
Resin import dependency concentrates material selection around regional converter capabilities and petrochemical price exposure.
- Glass:USP Type I borosilicate vials and molded bottles sustain premium positioning in temperature-sensitive biologics. Brazilian injectable producers in São Paulo state specify glass for monoclonal antibody formulations where protein stability demands inert contact surfaces.
- Polyethylene:HDPE and LDPE resins dominate oral liquid bottles and caps across cost-sensitive generic portfolios. Mexican converters face margin compression when US Gulf Coast ethylene pricing spikes disrupt procurement hedging strategies.
- Polypropylene:Copolymer and homopolymer grades displace polyethylene where autoclave sterilization and dimensional stability matter for hospital-preferred containers.
- Aluminum:Cold-form foil and lidding materials enable high-barrier blister performance against moisture vapor transmission.
Polyethylene holds current volume dominance. Polypropylene is climbing the fastest as sterilization requirements tighten.
Closure Type:
Regulatory mandates for child-resistance and tamper-evidence are compressing closure diversity toward certified platform designs.
- Screw Caps:Continuous-thread HDPE closures with induction foil liners seal oral solid bottles across Brazilian retail distribution. ANVISA's torque testing protocols favor standardized 28mm and 38mm neck finishes that streamline line changeover efficiency.
- Flip-Tops:Hinged polypropylene caps enable single-handed dispensing for geriatric and pediatric compliance packaging. Mexican hospital consortia specify flip-top vial seals for emergency medication access where screw-thread delays risk clinical outcomes.
- Corks:Elastomeric stoppers persist in legacy wine-based tincture and select oral liquid applications.
- Snap-Fit:Press-on closures serve unit-dose blister cards and disposable diagnostic cassettes where resealability is unnecessary.
Screw Caps retain installed base dominance. Flip-Tops are gaining share fastest as hospital-direct procurement expands.
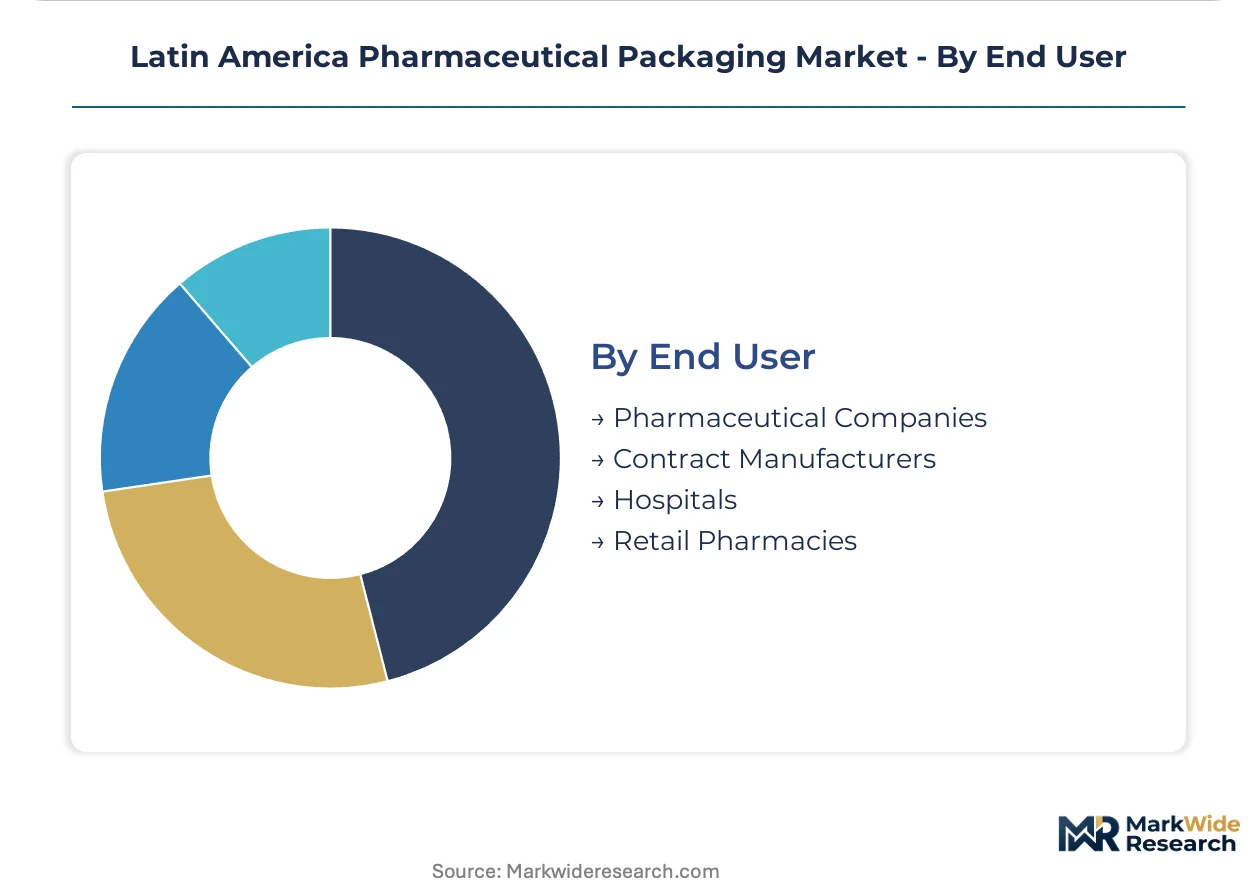
End User:
Procurement centralization among institutional buyers is marginalizing bespoke specifications in favor of standardized platform formats.
- Pharmaceutical Companies:Integrated manufacturers in Brazil's São Paulo corridor specify primary packaging during formulation development to secure ANVISA approval timelines. These firms demand full-service suppliers capable of serialization-ready formats from launch.
- Contract Manufacturers:CDMOs in Mexico's Querétaro cluster serve multinational clients requiring dual COFEPRIS-FDA packaging qualifications. Their procurement favors flexible formats accommodating multiple drug products without line revalidation.
- Hospitals:Brazil's SUS regional procurement hubs and Mexico's IMSS central buying standardize on child-resistant closures and pre-sterilized vials.
- Retail Pharmacies:Mexican pharmacy chains drive blister pack conversion for chronic disease medications requiring patient adherence packaging.
Pharmaceutical Companies anchor current demand concentration. Contract Manufacturers represent the steepest expansion trajectory as outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands larger pharmaceutical packaging procurement volumes than Mexico, yet Mexican contract manufacturers pursue more aggressive dual-certification strategies with US FDA alignment.
Brazil
ANVISA's item-level serialization mandates for prescription medicines are forcing line retrofits among São Paulo state's generic manufacturers. The regulator's traceability deadlines compress supplier qualification timelines toward full-service integrators. São Paulo's pharmaceutical corridor concentrates demand for high-barrier blister laminates and aggregation-capable packaging equipment.
Mexico
COFEPRIS adoption of PIC/S Annex 1 sterile manufacturing guidelines elevates container closure integrity testing to mandatory status for parenteral products. The regulatory alignment opens procurement channels for pre-sterilized ready-to-use vials among Querétaro's injectable producers. Querétaro's manufacturing cluster anchors dual-jurisdiction packaging qualifications serving multinational clients.
Argentina
Chronic disease prevalence drives unit-dose compliance packaging conversion from bulk bottles in Buenos Aires retail pharmacy networks. ANMAT's traceability regulations lag Brazil's ANVISA mandates, creating regulatory arbitrage for packaging suppliers. Buenos Aires province concentrates pharmaceutical manufacturing demand for cost-sensitive polyethylene bottles.
Colombia
INVIMA's progressive alignment with PIC/S standards is opening pre-sterilized ready-to-use vial demand among Bogotá's emerging injectable producers. The regulatory ascent positions Colombian manufacturers to supply Andean region markets with compliant primary packaging. Bogotá's pharmaceutical corridor attracts contract packaging investments from regional CDMOs.
Chile
ISP's pharmaceutical stability requirements tighten documentation for moisture-sensitive oral solids, favoring high-barrier blister configurations. The country's private health insurance penetration supports premium packaging formats for chronic disease medications. Santiago's pharmaceutical distribution hub concentrates secondary packaging and labeling operations serving domestic and export markets.
Latin America Pharmaceutical Packaging Market Competitive Landscape
European producers anchor the premium-tier supply of glass primary containers and serialization equipment; North American specialists hold dominant positions in flexible film and plastic containment systems. Market structure tilts toward consolidated procurement relationships where full-service integrators capture multi-year contracts from generic manufacturers facing compressed compliance timelines. Three archetypes define competitive positioning: multinational material science conglomerates with regional extrusion networks, specialized glass and closure manufacturers with validated sterile product lines, and packaging machinery integrators with aggregation software capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for ANVISA and COFEPRIS dual-certification demand.
Among European-based manufacturers, Gerresheimer AG and Schott AG exemplify the glass primary packaging archetype serving temperature-sensitive biologics with USP Type I borosilicate integrity requirements. Amcor Group GmbH occupies a position within the flexible material tier, leveraging film extrusion capabilities across São Paulo and Querétaro manufacturing corridors. These three entities represent distinct strategic anchors: glass specialists commanding premium positioning in injectable containment, and flexible material suppliers capturing volume-driven oral solid demand through regional converter networks.
| Leading Market Players |
|---|
| Aptar Group Inc. |
| Robert Bosch GmbH |
| Amcor Group GmbH |
| Marchesini Group S.p.A. |
| Körber AG |
| Berry Global Inc. |
| Gerresheimer AG |
| Multivac Group |
| Schott AG |
| Others |
Supply & Pricing Matrix
Polyethylene resin feedstock volatility transmits from US Gulf Coast petrochemical pricing through São Paulo converters to Brazilian generic manufacturers, compressing margins at the economy tier while premium glass vial suppliers in Querétaro command stability premiums through long-term pharmaceutical contracts.
Pricing Analysis
Capacity additions in Mexico's Querétaro cluster are reshaping price floors for pre-sterilized ready-to-use vials as COFEPRIS compliance investments concentrate procurement among full-service integrators. Three-tier pricing structure across premium, standard, and economy levels separates USP Type I borosilicate glass from polypropylene alternatives and cost-sensitive polyethylene bottles. Cost compression in the economy tier is intensifying because resin import dependency ties converters to dollar-denominated feedstock swings. Contract manufacturers represent the most price-sensitive buyer segment, while biologics producers demonstrate lowest sensitivity due to validated cold-chain integrity requirements.
Supply Chain Analysis
Return flows for aggregation-capable serialization equipment create refurbishment channels as European hardware manufacturers face extended delivery backlogs that stall ANVISA compliance timelines. Manufacturing concentrates in Brazil, Mexico, and Argentina, with São Paulo state anchoring high-barrier blister laminate production and Querétaro serving dual-jurisdiction sterile containment. Raw material dependencies center on US Gulf Coast polyethylene and polypropylene resins, São Paulo-state aluminum foil, and imported USP Type I borosilicate glass tubing. Single-source vulnerability in aluminum foil supply creates structural risk for regional drug manufacturers. Distribution runs through hospital purchasing consortia and pharmaceutical wholesalers serving retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America pharmaceutical packaging functions as a geographic-arbitrage play where ANVISA's accelerated serialization mandates in Brazil create cost premiums against Mexico's COFEPRIS alignment with PIC/S standards, rewarding suppliers with dual-certification capabilities.
For Market Incumbents: Deploy backward integration into regional aluminum foil extrusion to defend against São Paulo-state supply concentration. Consolidate procurement relationships with full-service packaging integrators capable of simultaneous ANVISA and COFEPRIS qualifications. Capacity additions in Colombian converter networks threaten margin stability for established Brazilian suppliers. For New Entrants and Emerging Players: Capture pre-sterilized ready-to-use vial demand among Bogotá's emerging injectable producers as INVIMA advances PIC/S alignment. Target hospital-direct procurement channels bypassing traditional pharmaceutical wholesalers in Brazil's SUS regional hubs. Partner with European serialization equipment resellers to overcome 18-month hardware delivery backlogs. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier generic manufacturers face dual-certification timeline extensions of 8-14 months that strain working capital. Long-term viability favors specialized glass and closure manufacturers with validated sterile product lines over commodity polyethylene converters. Monitor regulatory harmonization progress between Mercosur and Pacific Alliance member states as inflection indicator for platform standardization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | Simultaneous ANVISA and COFEPRIS approvals compress product launch windows for multinational clients. |
| Regional Film Extrusion Network Expansion | Captive supply of high-barrier blister laminates reduces exposure to São Paulo aluminum foil concentration. |
| Aggregation-Capable Serialization Equipment Partnership | European hardware reseller agreements overcome delivery backlogs threatening Brazilian compliance deadlines. |
| Hospital-Direct Procurement Channel Development | Brazil's SUS regional hubs and Mexico's IMSS central buying standardize specifications and volumes. |
| Cyclic Olefin Polymer Primary Container Piloting | Brazilian biologics producers test COP vial alternatives where protein adsorption and glass breakage compete. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Colombia, and Chile, with primary inputs from each market combining interviews with packaging procurement managers at generic pharmaceutical manufacturers, regulatory affairs leads navigating ANVISA and COFEPRIS compliance, hospital purchasing committee members at SUS and IMSS, and serialization equipment integration specialists. Secondary validation draws from ANVISA traceability mandate documentation, COFEPRIS PIC/S Annex 1 guideline revisions, customs records for polyethylene and polypropylene resin imports, and pharmaceutical packaging trade association reports. Bottom-up demand modeling triangulates against top-down market sizing across material and product type segments.
Granularity-level modeling disaggregates volume and value outputs by product type, material, closure specification, and end-user channel throughout the forecast period. Treatment line differentiation separates chronic disease oral solids from temperature-sensitive biologics, while regional regulatory cluster segmentation captures divergence between Mercosur and Pacific Alliance compliance frameworks. CAGRs derive from installed base expansion rates, line retrofit requirements, and generic drug manufacturer consolidation patterns. Industry-specific forecast inputs include ANVISA serialization deadline compliance curves and COFEPRIS sterile manufacturing guideline adoption trajectories.
Regulatory deadline delays, resin price volatility spikes, and equipment delivery backlogs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory harmonization progress and petrochemical feedstock pricing stability. Practitioners should monitor ANVISA enforcement intensity, US Gulf Coast ethylene contract pricing, and European serialization hardware order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market