
 Europe Pharmaceutical Packaging Market | 2026-2036
Europe Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Packaging Market Foresight
Market Context
The EU Falsified Medicines Directive is restructuring compliance budgets across European pharmaceutical packaging operations. Amcor plc leverages its integrated film and converting footprint to anchor supply security for blister and sachet formats. Gerresheimer AG sustains specialized leadership in pharmaceutical glass, particularly for injectable and biologic drug containment. Schott AG dominates borosilicate and aluminosilicate tubing supply for prefillable syringes and cartridges.
Technical Definition and Structural Segments
Europe pharmaceutical packaging encompasses primary, secondary, and tertiary systems engineered to protect drug stability, ensure patient safety, and enable regulatory traceability, with barrier properties measured by oxygen transmission rates, moisture vapor transmission rates, and extractables profiles. Blister packs occupy the largest product-type position due to their cost efficiency in oral solid-dose distribution across retail pharmacy networks. Glass vials and ampoules represent the fastest-expanding material-format intersection, driven by parenteral biologics requiring inert, non-reactive containment with validated container closure integrity. Child-resistant packaging commands premium positioning as pediatric safety regulations tighten dispensing standards across EU member states.
Regulatory Frame and Outlook
EMA guidelines on quality target product profiles, REACH chemical safety protocols, and the EU Packaging and Packaging Waste Regulation collectively shape material selection, recyclability mandates, and migration testing protocols for all market participants. ECHA substance restrictions and the EU Green Deal's circular economy requirements are forcing accelerated substitution of halogenated plastics and virgin petroleum-based polymers. Stakeholders must monitor evolving serialization deadlines and eco-design standards to align capital allocation with compliance-driven procurement criteria.
Market Dynamics
The EU Falsified Medicines Directive and Medical Device Regulation are compressing compliance timelines while biologics manufacturers scramble for high-barrier primary packaging formats. This regulatory-squeeze is forcing capital reallocation toward serialization infrastructure and specialized containment technologies.
Growth Catalysts
- Biologics containment demand:Parenteral biologics requiring validated container closure integrity are pulling borosilicate glass and advanced polymer formats into accelerated qualification cycles.
- REACH chemical safety protocols:ECHA substance restrictions are accelerating substitution of halogenated plastics, creating procurement windows for compliant material suppliers.
- Germany:Concentrated investment in sterile fill-finish infrastructure and advanced glass conversion capacity is anchoring regional supply security for prefillable syringes.
Market Restraints
- Aluminosilicate tubing concentration:Schott AG dominates borosilicate and aluminosilicate supply for prefillable syringes, creating single-source vulnerability for cartridge manufacturers.
- Petroleum-based polymer input costs:Virgin petroleum-based polymers face ECHA restrictions and EU Green Deal circular economy mandates, forcing costly material transitions.
- Serialization infrastructure capex:The EU Falsified Medicines Directive mandates traceability systems that require multimillion-euro line upgrades with compressed ROI timelines.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated Central European markets present greenfield opportunities for contract packaging organizations serving Western European sponsors.
- Child-resistant packaging:Tightening pediatric safety regulations across EU member states are expanding premium-positioned dispensing format demand.
- Recyclable barrier films:EU Packaging and Packaging Waste Regulation recyclability mandates are creating first-mover advantages for mono-material blister solutions.
Industry Challenges
- Container closure integrity validation:Biologics manufacturers face extended qualification timelines for new primary packaging formats, compressing product launch windows.
- Serialization integration:Legacy packaging lines require complete hardware and software overhauls to meet EMA quality target product profile guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Packaging Market |
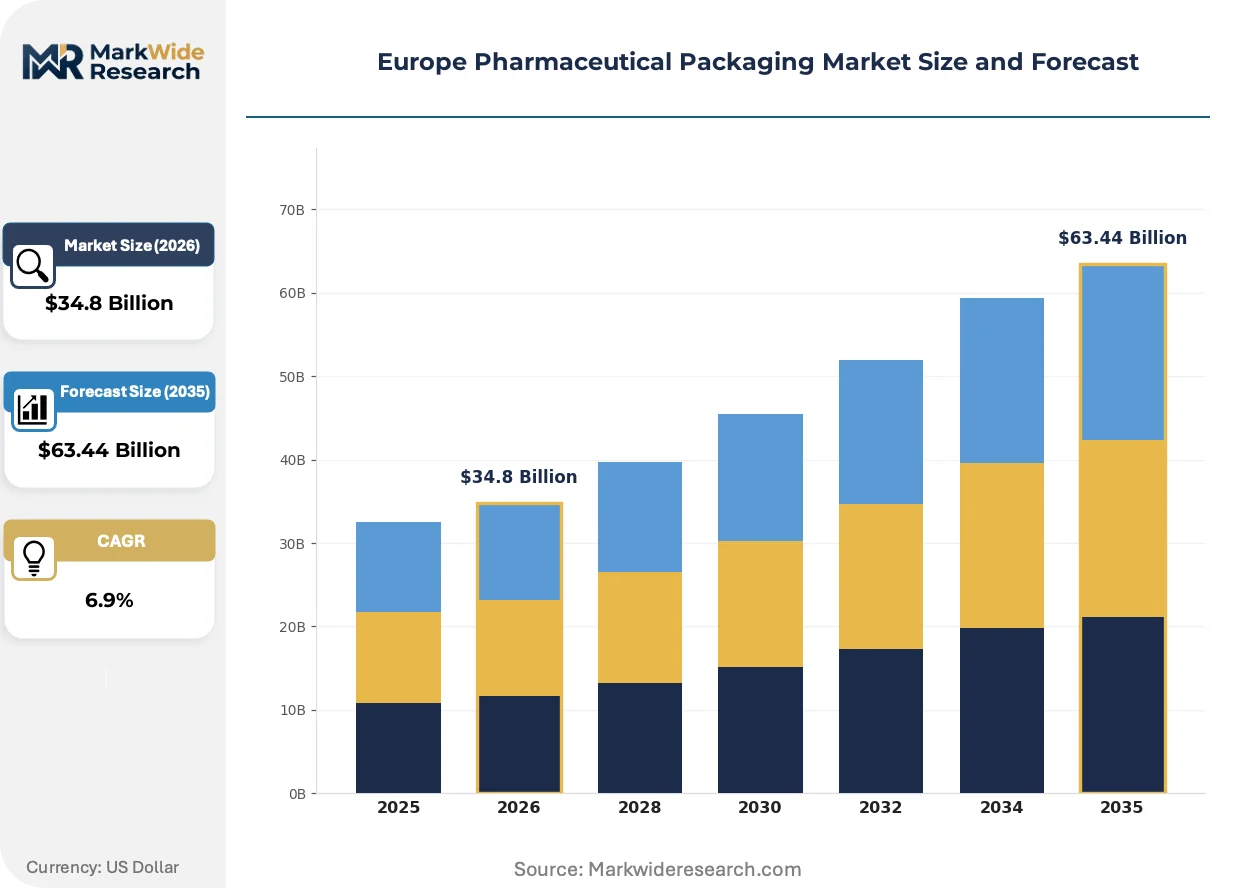
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $63.44 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Bottles, Vials, Ampoules Material: Plastic, Glass, Aluminum, Cardboard End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutes, Retail Pharmacies Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Child-resistant Packaging |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, AptarGroup Inc., Constantia Flexibles, CCL Industries Inc., Stevanato Group, SGD Pharma, Nolato AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Packaging Market Shifts & Advancements
Digital watermarking and connected packaging technologies are intersecting with circular economy mandates to redefine how pharmaceutical packaging demonstrates compliance and engages end-users. Material science advances are simultaneously addressing barrier performance and end-of-life recovery requirements.
Cyclic olefin polymers are rewriting the material hierarchy for prefillable syringes and vials. Biologics manufacturers in Germany and Switzerland are adopting COP formats at triple-digit annual rates for protein-based therapeutics requiring ultra-low extractables profiles. This polymer transition is compressing glass conversion capacity planning and forcing traditional suppliers to defend position through specialized coating technologies.
The EU Green Deal's circular economy requirements are mandating recycled content minimums and design-for-recyclability protocols across all packaging tiers. ECHA substance restrictions are simultaneously banning halogenated flame retardants and certain phthalate plasticizers used in secondary packaging. Blister pack manufacturers in Italy and Spain are responding fastest, piloting PET-based mono-material alternatives to PVC-PVDC laminates.
Hospital and pharmacy procurement coalitions are consolidating volume and demanding outcome-based packaging performance guarantees. Large EU hospital networks now specify oxygen transmission rate and moisture vapor transmission rate thresholds in tender documents, displacing generic material specifications. This specification tightening is most visible in France and the Netherlands, where centralized purchasing bodies have consolidated 60 percent of acute-care pharmaceutical distribution.
Europe Pharmaceutical Packaging Market Segmentation
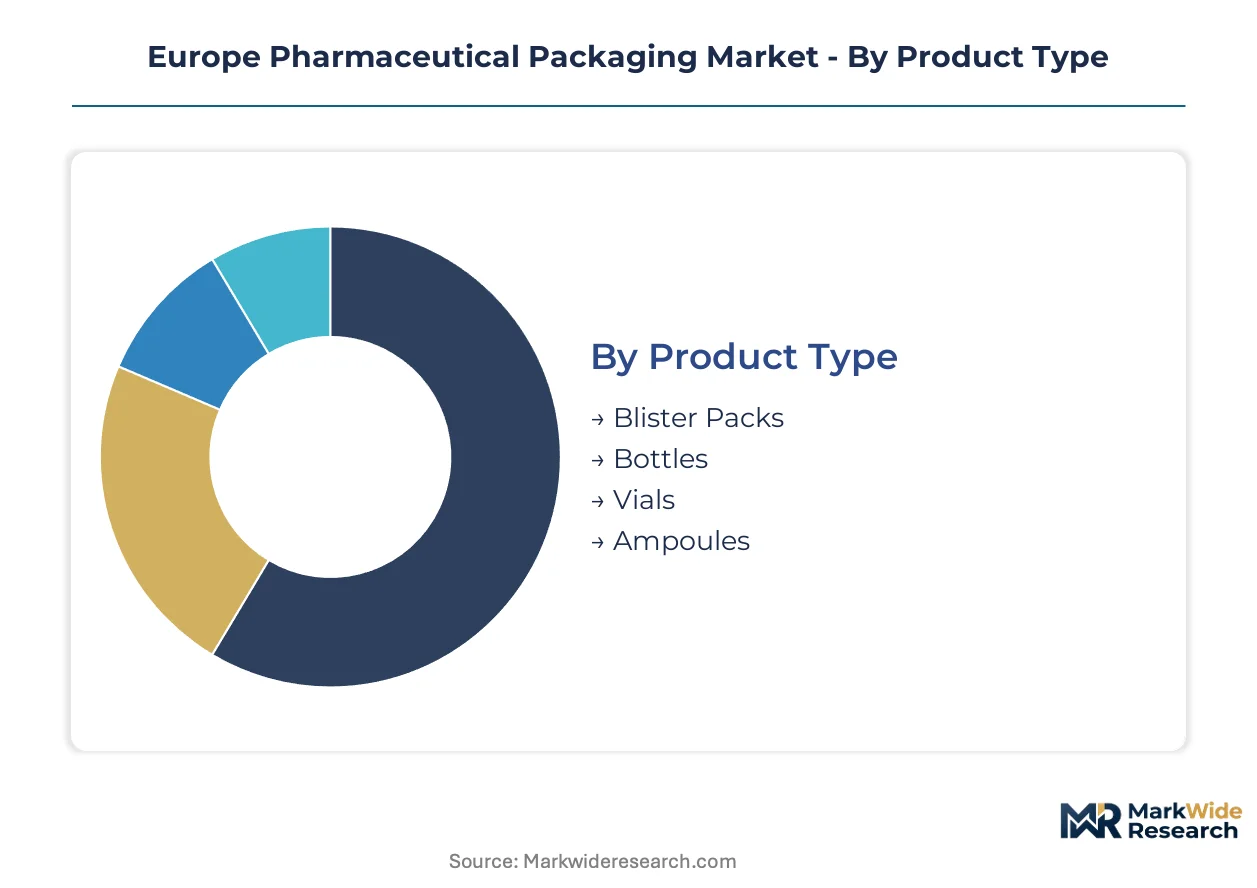
Packaging selection in Europe hinges on drug stability requirements, regulatory compliance tiers, and distribution channel specifications. Each segmentation axis reveals distinct procurement patterns and margin structures across the value chain.
Product Type:
Customization intensity varies from standardized oral solid formats to highly specialized parenteral containment systems requiring validated container closure integrity.
- Blister Packs:Multi-layer barrier films with aluminum foil lidding dominate oral solid-dose distribution across retail pharmacy networks in Germany and France. EMA serialization mandates are forcing line upgrades for thermoformed PVC-PVDC and cold-form aluminum alternatives.
- Vials:Borosilicate and aluminosilicate glass formats with validated elastomeric closures anchor biologics containment in Swiss and German manufacturing clusters. Parenteral protein therapeutics demand ultra-low extractables profiles and proven container closure integrity.
- Bottles:HDPE and PET containers with induction-sealed closures serve high-volume oral liquid and solid-dose prescriptions across centralized EU hospital procurement networks.
- Ampoules:Single-dose glass formats retain niche positioning for emergency injectables and anesthetics in acute-care settings, particularly within French and Italian hospital systems.
Most installed capacity flows through blister packs. Expansion is steepest in vials.
Material:
Cost tiers separate commodity substrates from performance-engineered alternatives subject to REACH substance restrictions and EU Green Deal circular economy mandates.
- Glass:Borosilicate tubing from German and Swiss suppliers dominates prefillable syringes and cartridges for biologics. ECHA scrutiny of extractables profiles is tightening qualification protocols for molded and tubular formats.
- Plastic:Cyclic olefin polymers and advanced polypropylene formulations are displacing PVC in barrier applications across Italian and Spanish converting operations. EU Packaging and Packaging Waste Regulation recyclability mandates favor mono-material structures.
- Aluminum:Cold-form foil and blister lidding materials provide absolute moisture and oxygen barriers for humidity-sensitive APIs, concentrated in German and Austrian rolling mill supply.
- Cardboard:Secondary and tertiary packaging substrates face escalating recycled content minimums under EU circular economy requirements, with Nordic markets demanding FSC-certified sourcing.
Glass commands the highest unit economics. Plastic formats are climbing the fastest on biologics polymer transitions.
End User:
Customer type determines specification rigor, volume scale, and direct regulatory liability exposure across the packaging procurement chain.
- Pharmaceutical Companies:Originators in Germany, Switzerland, and Denmark drive specification-setting for primary containment, with in-house packaging engineering teams validating supplier processes against EMA quality target product profiles.
- Contract Manufacturers:CDMOs in Ireland, Belgium, and the Netherlands aggregate packaging demand across multiple sponsor portfolios, requiring flexible line configurations and rapid format changeover capabilities.
- Research Institutes:Clinical trial supply operations in the UK and Sweden demand small-batch, serialized packaging with adaptive labeling for multi-country protocols.
- Retail Pharmacies:Centralized purchasing bodies in France and the Netherlands consolidate 60 percent of acute-care distribution, specifying oxygen transmission rate and moisture vapor transmission rate thresholds in tender documents.
Pharmaceutical companies anchor specification authority. Contract manufacturers are expanding capacity most aggressively.
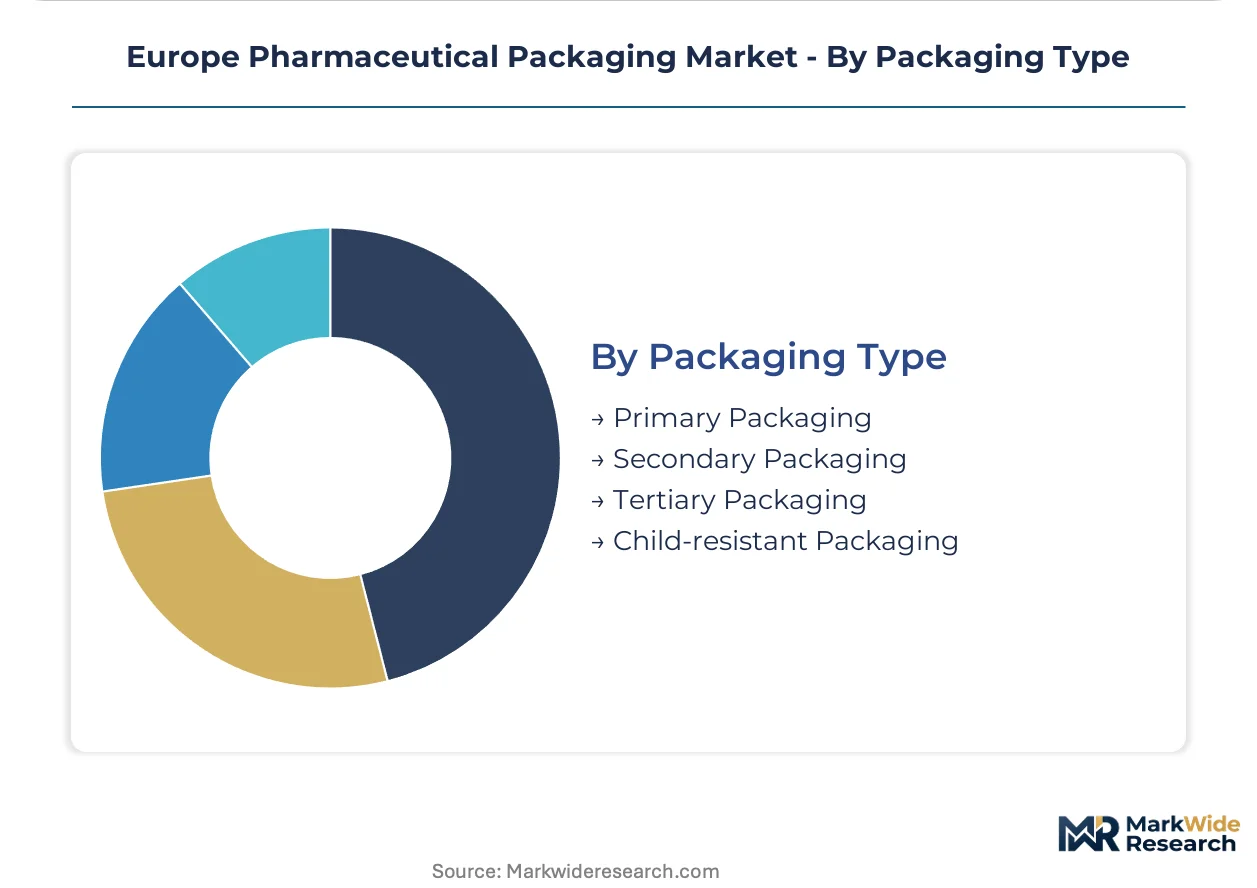
Packaging Type:
Maturity gradients separate established primary containment from emerging functional formats addressing pediatric safety and traceability requirements.
- Primary Packaging:Direct drug-contact materials including glass vials, polymer syringes, and blister films face the most intensive EMA and ECHA compliance scrutiny, with extractables and leachables testing consuming 18-24 month qualification cycles.
- Child-resistant Packaging:Senior-friendly yet pediatric-secure closures command premium positioning as EU member states tighten dispensing standards, with French and German regulators leading enforcement.
- Secondary Packaging:Cartons, labels, and inserts carry serialization data mandated by the EU Falsified Medicines Directive, with line integration costs driving consolidation among mid-tier converters.
- Tertiary Packaging:Shippers and pallets for cold-chain distribution incorporate temperature monitoring and tamper-evidence features, critical for biologics distribution from Belgian and Dutch logistics hubs.
Primary packaging absorbs the largest compliance investment. Child-resistant formats are gaining share fastest on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packaging in Europe traces its industrial lineage to nineteenth-century glassworks in Germany and Switzerland, where borosilicate tubing for medical containment first achieved commercial scale. These Alpine and Rhine-Ruhr manufacturing clusters established the technical standards and regulatory frameworks that now govern EU-wide compliance. Today, national specialization patterns reflect this historical foundation while adapting to EMA harmonization and the EU Green Deal's circular economy mandates.
Germany
Biologics manufacturers in Baden-Württemberg and Bavaria are driving demand for prefillable syringes and high-barrier vials. The country's implementation of the EU Falsified Medicines Directive has compressed serialization timelines for packaging converters. Münsterland and Mainz glass conversion clusters are expanding sterile fill-finish capacity to anchor regional supply security for parenteral therapeutics.
Switzerland
Basel and Zürich-based pharmaceutical originators specify ultra-low extractables profiles for protein-based therapeutics, pulling cyclic olefin polymers into accelerated qualification cycles. Swissmedic guidelines on container closure integrity exceed baseline EMA requirements, creating a premium compliance tier. The Rhine corridor between Basel and Schaffhausen concentrates specialized glass and polymer converting operations serving global biologics sponsors.
France
Centralized hospital procurement through the Agence Régionale de Santé networks specifies oxygen transmission rate and moisture vapor transmission rate thresholds in tender documents, displacing generic material specifications. ANSM enforcement of pediatric safety regulations is tightening child-resistant packaging standards. The Paris-Saclay and Lyon bioclusters are driving demand for serialized secondary packaging with adaptive labeling capabilities.
Netherlands
Belgian and Dutch logistics hubs for temperature-sensitive biologics distribution are mandating tertiary packaging with integrated temperature monitoring and tamper-evidence features. The country's national pharmaceutical regulator aligns with EMA quality target product profiles while emphasizing cold-chain validation. Contract manufacturing organizations in Oss and Leiden aggregate packaging demand across multiple sponsor portfolios, requiring flexible line configurations.
Italy
Blister pack manufacturers in Lombardy and Emilia-Romagna are piloting PET-based mono-material alternatives to PVC-PVDC laminates in response to EU Packaging and Packaging Waste Regulation recyclability mandates. The national pharmaceutical regulator enforces REACH chemical safety protocols with particular scrutiny on halogenated plasticizers. Milan and Bologna converting clusters are consolidating volume to meet specification tightening from French and Dutch hospital procurement coalitions.
Europe Pharmaceutical Packaging Market Competitive Landscape
The competitive structure tilts toward integrated material-converting specialists with captive glass tubing or film extrusion capabilities. Tier-one positions concentrate among German and Swiss industrial conglomerates with multi-decade pharmaceutical relationships, while mid-tier converters compete on serialization line integration speed and format flexibility. Three archetypes dominate: integrated material-to-package conglomerates, specialized primary containment engineers, and regional contract packaging organizations. Capacity expansion and strategic partnerships represent the dominant competitive moves, with line automation and sustainability certification serving as secondary differentiators.
Among integrated material specialists, Amcor plc and Gerresheimer AG exemplify the conglomerate archetype through their spanning of raw material production through finished package delivery. Schott AG occupies a position within the specialized engineering tier, anchoring borosilicate and aluminosilicate supply for prefillable syringes. These three entities represent the structural concentration at the premium end of European pharmaceutical packaging, with their geographic positioning in Germany and Australia-UK reflecting historical industrial clustering rather than emergent strategic repositioning.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| AptarGroup Inc. |
| Constantia Flexibles |
| CCL Industries Inc. |
| Stevanato Group |
| SGD Pharma |
| Nolato AB |
| Others |
Supply & Pricing Matrix
EU Green Deal circular economy requirements gate qualified supply access and premium-tier pricing positioning for pharmaceutical packaging converters across Europe. REACH substance restrictions on halogenated plastics and virgin petroleum-based polymers compress compliant material availability, forcing buyers into longer-term offtake agreements with certified suppliers who command price premiums for validated extractables profiles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates qualified containment systems for biologics from commodity oral solid-dose formats. Certification grade under EMA quality target product profiles and volume scale through centralized hospital procurement coalitions drive price differentiation. Cost compression in standard-tier blister films intensifies because Italian and Spanish converters are piloting PET-based mono-material alternatives. Contract manufacturers in Ireland and Belgium exhibit highest price sensitivity due to multi-sponsor portfolio pressures, while Swiss biologics originators show least sensitivity given ultra-low extractables requirements.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics mandate integrated cold-chain validation and tamper-evidence documentation before tertiary packaging re-enters distribution. Geographic supply concentrates in Germany, Switzerland, and Italy, with borosilicate tubing from Münsterland glassworks and cyclic olefin polymers from Basel-area converters anchoring primary containment. Raw material dependencies rest on petroleum-based polymer feedstocks, aluminum foil from Austrian rolling mills, and elastomeric closure compounds. Single-source vulnerability for aluminosilicate tubing creates structural risk for cartridge manufacturers dependent on Schott AG supply. Distribution runs through Belgian and Dutch logistics hubs serving EU-wide hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through premium-tier shifts toward child-resistant and serialized packaging formats, justified by REACH compliance costs that eliminate low-cost competitors.
For Market Incumbents: Acquire sterile fill-finish infrastructure in Baden-Württemberg and Bavaria to anchor regional supply security for prefillable syringes. Backward integration into borosilicate tubing production defends against single-source concentration risk from Schott AG dominance. EMA serialization deadlines compress ROI timelines and threaten mid-tier converters lacking capital for line upgrades. For New Entrants and Emerging Players: The EU Falsified Medicines Directive in Europe opens a window for contract packaging organizations specializing in rapid format changeover and adaptive labeling. Underpenetrated Central European markets in Poland and the Czech Republic present greenfield opportunities for greenfield CDMO facilities. Target procurement coalitions in France and the Netherlands with outcome-based performance guarantees for oxygen transmission rate and moisture vapor transmission rate thresholds. For Investors and Strategic Acquirers: Roll-up economics work for regional contract packaging organizations because EMA harmonization is consolidating specification authority among sponsors seeking flexible line configurations. Platform consolidation across Italian and Spanish blister converters captures recyclability-mandate first-mover advantages. Monitor ECHA substance restriction announcements for inflection signals on material substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Tubing | Captive borosilicate supply from German glassworks reduces single-source dependency for prefillable syringe manufacturers. |
| Mono-Material Blister Transition | PET-based alternatives to PVC-PVDC laminates position Italian converters ahead of EU Packaging and Packaging Waste Regulation mandates. |
| Serialization Infrastructure Deployment | Line upgrades for EU Falsified Medicines Directive compliance secure tender eligibility from French hospital procurement coalitions. |
| Cold-Chain Validation Partnerships | Integrated temperature monitoring capabilities anchor tertiary packaging demand from Belgian biologics distribution hubs. |
| Child-Resistant Format Expansion | Premium positioning for pediatric-secure closures captures ANSM enforcement tightening across French dispensing standards. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the Alpine corridor, with primary inputs from each region combined with secondary validation. Primary interviews engaged packaging engineering directors at German biologics originators, regulatory affairs leads at Swiss pharmaceutical conglomerates, procurement managers at French hospital networks, and operations heads at Italian blister converting clusters. Secondary sources included EMA quality target product profile guidelines, ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation filings, and centralized hospital tender documents from the Netherlands and France. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Rate-of-change decomposition across the analysis window isolates volume growth from price-mix effects in pharmaceutical packaging. Segmentation dimensions modeled include product type, material substrate, end-user archetype, and packaging tier, with additional granularity on regional regulatory cluster differentiation. CAGRs were derived from installed capacity expansion schedules, sponsor pipeline disclosures, and procurement coalition volume consolidation trends. Forecast inputs incorporated biologics containment demand curves and serialization infrastructure deployment timelines.
Revisions become necessary when EMA guideline amendments, ECHA substance ban accelerations, or EU Green Deal mandate tightening materialize beyond baseline assumptions. Forecasts reflect modeling assumptions on qualification cycle durations and sponsor capital allocation priorities. Practitioners should monitor ECHA restriction proposals and hospital procurement specification releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market