
 Middle East and Africa Ampoules Packaging Market | 2026-2036
Middle East and Africa Ampoules Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ampoules Packaging Market Foresight
SFDA serialization requirements for pharmaceutical traceability are rebalancing procurement priorities across the Middle East and Africa. SCHOTT AG leverages its borosilicate glass expertise to anchor supply relationships with regional vaccine fill-finish operations. Gerresheimer AG sustains manufacturing scale through its specialized ampoule forming and conversion capabilities. Borosil Limited competes on cost-optimized glass formulations tailored to emerging market temperature profiles.
Ampoules packaging denotes hermetically sealed single-dose containers, typically formed from borosilicate glass or cyclic olefin polymers, designed to preserve sterility and prevent contamination of injectable pharmaceuticals. Glass ampoules dominate the product type landscape due to chemical inertness and established regulatory acceptance for parenteral applications. The pharmaceuticals application commands the structural margin pool, while the cosmetics segment occupies faster-growing niches in premium serum and ampoule-based skincare formats prevalent in Gulf beauty markets.
SFDA, MOHAP, and WHO prequalification standards collectively govern material compliance, dimensional tolerances, and extractables testing for ampoules entering regional pharmaceutical supply chains. South Africa's health products regulator and Egypt's drug authority enforce parallel conformity requirements that shape import substitution strategies for local glass converters. Stakeholders must monitor evolving biodegradability mandates and polymer migration thresholds as regulators tighten primary packaging specifications for temperature-sensitive biologics.
Market Dynamics
Serialization mandates from Saudi Arabia's SFDA and the UAE's MOHAP are restructuring procurement workflows across the Middle East and Africa, forcing pharmaceutical manufacturers to upgrade fill-finish lines and traceability infrastructure ahead of compliance deadlines.
Growth Catalysts
- SFDA Track-and-Trace Mandates:Saudi Arabia's pharmaceutical serialization requirements are accelerating investments in automated inspection and labeling systems for glass ampoule production lines.
- Vaccine Manufacturing Localization:Regional governments are prioritizing domestic fill-finish capacity for temperature-sensitive biologics, creating sustained demand for borosilicate glass primary packaging.
- Biologics Pipeline Expansion:Monoclonal antibody and biosimilar development across Egypt and South Africa is amplifying consumption of chemically inert glass ampoules over polymer alternatives.
Market Restraints
- Borosilicate Glass Supply Concentration:Specialized tubing supply from European and Asian manufacturers creates vulnerability to freight cost volatility and currency fluctuation exposure.
- Polymer Migration Thresholds:WHO prequalification standards for extractables testing impose technical barriers that delay market entry for cyclic olefin polymer ampoule variants.
- Energy Input Cost Volatility:Glass forming and annealing processes face margin pressure from natural gas price swings affecting furnace operations across regional converter facilities.
Strategic Opportunities
- Cosmetics Ampoule Formats:Premium skincare brands in Dubai and Riyadh are adopting pharmaceutical-grade glass ampoules for single-dose serum packaging, opening non-pharma revenue streams.
- Pre-Filled Syringe Conversion:Biologics manufacturers seeking patient administration convenience present white space for ready-to-use ampoule-syringe combination products.
- Egyptian Import Substitution:The Egyptian Drug Authority's local content incentives create openings for domestic glass converters to displace European import dependency.
Industry Challenges
- Serialization System Integration:Pharmaceutical manufacturers face execution complexity embedding aggregation and verification hardware into existing ampoule packaging lines without throughput degradation.
- Specialized Forming Technician Shortage:Regional converter operations struggle to recruit operators proficient in Danner and Vello process controls for dimensional tolerance compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ampoules Packaging Market |
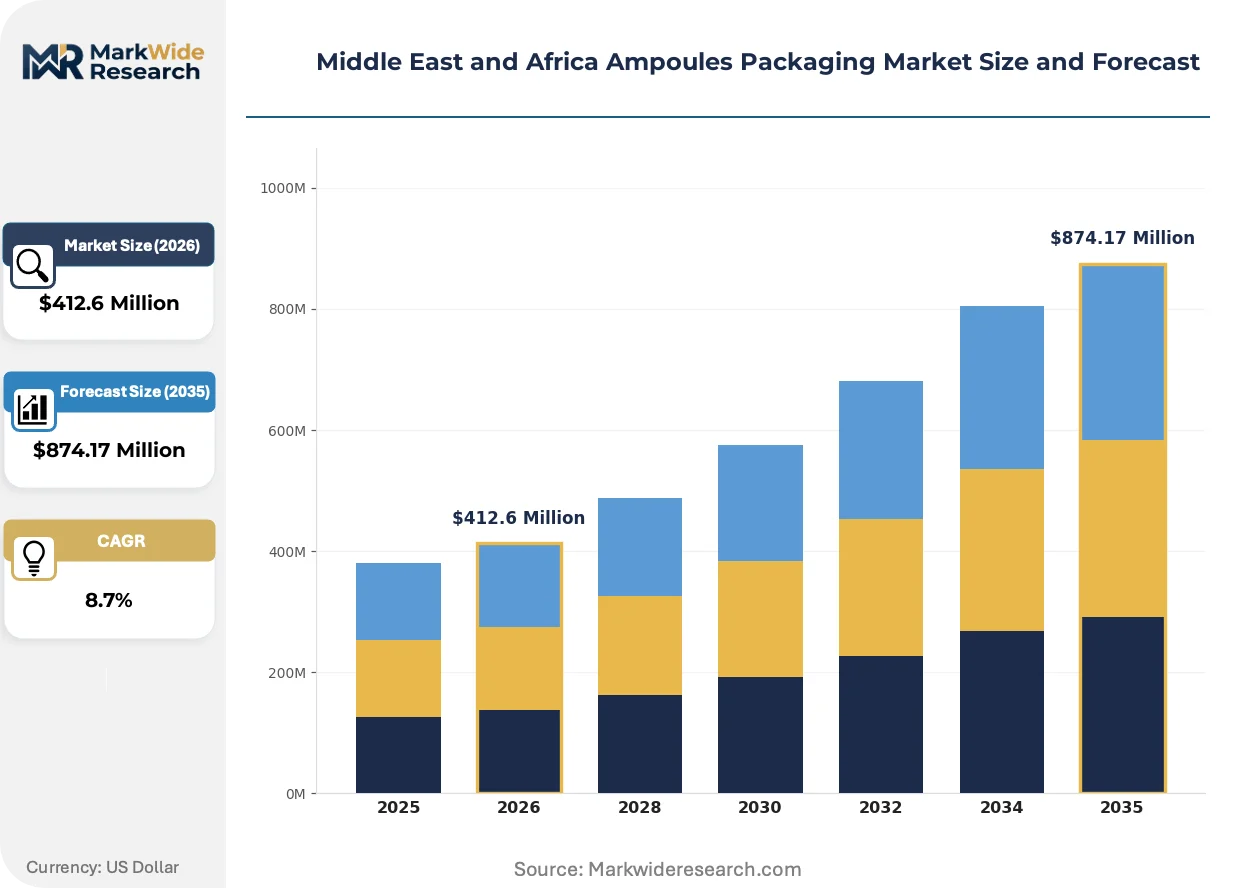
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Plastics, Biodegradable Application: Pharmaceuticals, Cosmetics, Chemicals, Nutraceuticals Capacity: 1ml, 2ml, 5ml, 10ml End User: Hospitals, Clinics, Laboratories, Pharmacies |
| Companies Covered | Syntegon Technology GmbH, SCHOTT AG, Gerresheimer AG, Adelphi Group, DWK Life Sciences Ltd., Stevanato Group S.P.A, Borosil Limited, RAK Ghani Glass LLC, Arab Pharmaceutical Glass Co., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ampoules Packaging Market Shifts & Advancements
Automation and material science advances are compressing production cycles and expanding application boundaries for ampoule packaging across pharmaceutical and cosmetics verticals in the Middle East and Africa.
Robotic visual inspection systems is automating defect detection in glass ampoule forming operations, with Saudi and UAE-based fill-finish contractors deploying machine-vision arrays at line speeds exceeding manual quality thresholds. Pharmaceutical manufacturers are adopting these systems to satisfy SFDA lot-release documentation requirements without expanding headcount. This automation is compressing the gap between regional converter capability and European quality benchmarks.
WHO prequalification standards for primary packaging materials are tightening extractables and leachables testing protocols, compelling glass manufacturers to document elemental impurity profiles across borosilicate tubing batches. The industrial consequence is a bifurcation between suppliers with in-house analytical laboratories and those dependent on third-party certification. Vaccine fill-finish operations in South Africa and Egypt are most affected, with procurement teams now requiring certificate-of-analysis packages that extend supplier qualification timelines.
Direct procurement relationships between pharmaceutical manufacturers and specialized glass converters are displacing traditional distribution intermediaries across the Gulf Cooperation Council states. Large-volume buyers are establishing annual contracting frameworks that bypass regional distributors and secure allocation priority during supply-constrained periods. This channel compression is most visible in Saudi Arabia, where SFDA serialization investments have concentrated buying power among a smaller cohort of compliant manufacturers seeking supply certainty.
Middle East and Africa Ampoules Packaging Market Segmentation
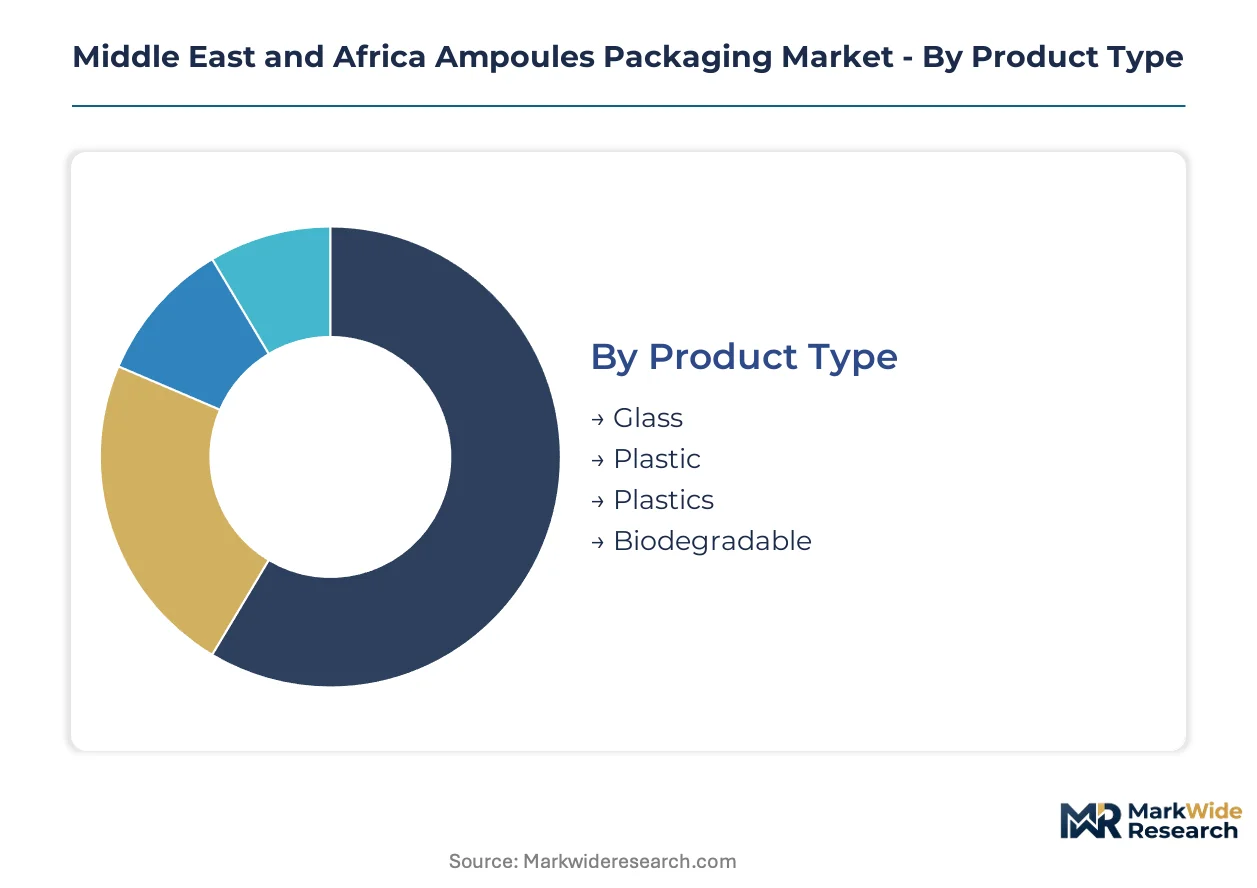
Ampoules packaging serves divergent performance requirements across pharmaceutical sterility standards, cosmetic premium positioning, and chemical resistance needs. Segmentation reveals where borosilicate glass commands price premiums versus where polymer alternatives penetrate on cost and design flexibility.
Product Type:
Standardization dominates at the commodity end while specialty formulations command customization premiums for temperature-sensitive applications.
- Glass:Borosilicate formulations provide chemical inertness and thermal shock resistance essential for biologics and vaccines. Demand concentrates in Saudi vaccine fill-finish operations and Egyptian injectable manufacturing, where SFDA and EDA compliance mandates disqualify lower-grade alternatives.
- Plastic:Cyclic olefin polymers and polypropylene variants reduce breakage risk in field distribution. South African primary care clinics and Nigerian rural pharmacy networks favor these for cost-sensitive essential medicines, though WHO prequalification extractables testing delays broader adoption.
- Plastics:Multi-layer coextruded structures combine moisture barriers with mechanical durability for veterinary and diagnostic reagent applications.
- Biodegradable:Polylactic acid and starch-based formulations target cosmetics brands in Dubai and Riyadh seeking sustainability credentials for premium serum packaging.
Most installed capacity flows through Glass. Expansion is steepest in Biodegradable.
Application:
Margin pools separate sharply between regulated pharmaceutical channels and discretionary cosmetic purchasing.
- Pharmaceuticals:Parenteral drug packaging demands Type I borosilicate compliance, dimensional tolerances for automated fill-finish lines, and full traceability documentation. Saudi and UAE serialization mandates have concentrated procurement among manufacturers with integrated inspection and aggregation systems.
- Cosmetics:Single-dose ampoules for vitamin C serums and hyaluronic acid treatments command 3-5x unit premiums over pharmaceutical equivalents. Gulf beauty markets in Dubai, Riyadh, and Jeddah drive format innovation with metallic overcaps and silk-screen branding.
- Chemicals:Reagent and diagnostic applications require inert seals for aggressive solvents, with South African industrial laboratories representing the regional demand anchor.
- Nutraceuticals:Liquid vitamin and probiotic shots in 2-5ml formats occupy a mid-tier pricing band between pharmaceutical compliance costs and cosmetic premium positioning.
Pharmaceuticals absorb the majority of borosilicate glass volume. Cosmetics is climbing the fastest on unit value expansion.
Capacity:
Fill-finish line economics and dose standardization create volume concentration at specific size points.
- 1ml:Ophthalmic and pediatric vaccine applications specify tight tolerances for micro-dose accuracy. Egyptian and Moroccan fill-finish contractors maintain dedicated 1ml lines for measles and polio vaccine campaigns.
- 2ml:The workhorse specification for antibiotic and analgesic injectables balances material efficiency with handling practicality. Saudi hospital procurement tenders standardize on 2ml for formulary alignment.
- 5ml:Veterinary and large-volume therapeutic applications dominate, with South African agricultural pharmaceutical distributors representing steady demand.
- 10ml:Diagnostic reagents and contrast media require larger volumes, though adoption is constrained by limited regional fill-finish equipment configured for this format.
2ml commands the largest installed base. 1ml is gaining share fastest on vaccine localization programs.
End User:
Purchasing authority and compliance liability vary dramatically across institutional settings.
- Hospitals:Centralized procurement with serialization aggregation requirements favors direct supplier relationships. Saudi MOH and UAE MOHAP tenders specify lot-level traceability that excludes smaller converters.
- Clinics:Fragmented purchasing across primary care networks in Egypt and Nigeria prioritizes unit cost over technical specifications, creating openings for polymer alternatives.
- Laboratories:Research and diagnostic facilities in South Africa and Kenya demand certified low-extractables glass for analytical integrity.
- Pharmacies:Retail dispensing of reconstituted antibiotics and cosmetic ampoules drives small-lot, high-SKU distribution complexity.
Hospitals channel the highest value throughput. Clinics show the steepest volume expansion on primary care network growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glass forming technicians cluster in Riyadh, Cairo, and Johannesburg, anchoring regional converter capacity for borosilicate ampoule production. Their expertise determines dimensional tolerance compliance for SFDA and WHO prequalification standards.
Saudi Arabia
Vaccine fill-finish contractors in Riyadh and Jeddah drive demand for Type I borosilicate ampoules. SFDA serialization mandates force procurement consolidation among manufacturers with integrated inspection systems. The King Abdullah Economic City pharmaceutical zone hosts sterile injectable capacity expansions serving Gulf Cooperation Council markets.
United Arab Emirates
MOHAP track-and-trace requirements reshape labeling and aggregation workflows for Dubai-based distributors. The Jebel Ali pharmaceutical free zone concentrates regional logistics and secondary packaging operations. Biologics cold chain infrastructure in Abu Dhabi supports temperature-sensitive ampoule storage for vaccine campaigns.
Egypt
Domestic injectable manufacturing expands in Cairo and Alexandria under Egyptian Drug Authority local content incentives. The 10th of Ramadan industrial city hosts glass converter investments targeting import substitution. Measles and polio vaccine programs sustain 1ml ampoule demand at dedicated fill-finish lines.
South Africa
Biologics development in Cape Town and Johannesburg amplifies consumption of chemically inert glass ampoules. The country's health products regulator enforces extractables testing protocols matching WHO standards. Durban pharmaceutical logistics corridors handle regional distribution for temperature-sensitive parenterals.
Morocco
Casablanca pharmaceutical manufacturing clusters serve North African and sub-Saharan export markets. The Tangier Med industrial platform hosts foreign fill-finish investments seeking proximity to European supply chains. Local glass conversion capacity remains underdeveloped, creating dependency on Spanish and Italian tubing imports.
Middle East and Africa Ampoules Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa ampoules packaging landscape. Glass tubing foundries with captive forming operations command supply security premiums, while converters dependent on merchant tubing face allocation risk during supply-constrained periods. The market structure separates into three archetypes: integrated borosilicate specialists, regional conversion contractors, and polymer alternative developers. Dominant competitive moves include backward integration into tubing production and direct contracting frameworks that displace distribution intermediaries.
Among European-integrated specialists, SCHOTT AG and Gerresheimer AG exemplify the foundry-tier archetype with in-house borosilicate expertise and analytical laboratory capabilities. Borosil Limited represents the cost-optimized regional converter model, competing on formulations tailored to emerging market temperature profiles. These three anchors illustrate how supply security and regulatory documentation capabilities determine procurement priority in Saudi and UAE serialization-compliant markets.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| SCHOTT AG |
| Gerresheimer AG |
| Adelphi Group |
| DWK Life Sciences Ltd. |
| Stevanato Group S.P.A |
| Borosil Limited |
| RAK Ghani Glass LLC |
| Arab Pharmaceutical Glass Co. |
| Others |
Supply & Pricing Matrix
SFDA certification tiers create a three-tier pricing structure across premium, standard, and economy levels that manifests in divergent procurement behaviors and supply chain configurations across the Middle East and Africa. Pharmaceutical manufacturers in Saudi Arabia and the UAE pay substantial premiums for borosilicate ampoules with full traceability documentation and integrated inspection systems, while Egyptian and Nigerian clinic networks prioritize unit economics over technical specifications.
Pricing Analysis
Bundled certification-and-inspection services command 40-60% premiums over unbundled commodity glass across Saudi and UAE hospital procurement tenders. Price differentiation rests on SFDA serialization compliance status and in-house analytical laboratory capabilities, with WHO prequalification tiers adding further stratification. Pricing pressure stems from Egyptian Drug Authority local content incentives that favor domestic converters over European imports. Clinic networks in Nigeria and Kenya exhibit highest price sensitivity, while Saudi MOH centralized tenders show lowest elasticity due to compliance liability concentration.
Supply Chain Analysis
Single-source vulnerability sits with European and Asian borosilicate tubing manufacturers who feed regional converter operations. Supply concentrates in Germany, India, and China for specialized glass formulations, with Egyptian and South African converters drawing from these hubs. Raw material dependencies include soda ash, boron compounds, and natural gas for furnace operations. Tariff exposure on European tubing imports threatens margin structures at Egyptian glass converters. Distribution runs through direct annual contracting frameworks between large-volume pharmaceutical manufacturers and integrated foundries, displacing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa ampoules packaging market functions as a stable compounder anchored by irreversible pharmaceutical serialization mandates that permanently elevate compliance requirements and procurement consolidation.
For Market Incumbents: Lock in supply allocation priority through backward integration into borosilicate tubing production or captive analytical laboratory investments. SFDA serialization deadlines threaten to exclude non-compliant converters from Saudi and UAE hospital tenders, making certification infrastructure the decisive defensive lever. Establish direct contracting frameworks with Riyadh and Dubai fill-finish contractors to displace distribution intermediaries and defend volume positions. For New Entrants and Emerging Players: Egyptian Drug Authority local content incentives represent the most penetrable entry point for domestic glass converters seeking to displace European import dependency. Target cosmetics ampoule formats in Dubai and Riyadh premium beauty markets where pharmaceutical-grade glass commands 3-5x unit premiums and regulatory barriers remain lower than pharmaceutical channels. Partner with Gulf-based contract fill-finish operators to bypass capital-intensive sterile manufacturing infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing WHO prequalification status and underutilized forming capacity in Egypt and Morocco. The five-to-ten-year viability window favors assets with demonstrated SFDA compliance pathways and existing relationships with Saudi vaccine fill-finish contractors. Monitor Egyptian Drug Authority local content enforcement intensity as the critical inflection signal for import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tubing Production | Captive borosilicate supply secures allocation priority during European supply-constrained periods. |
| SFDA Serialization Compliance Investment | Integrated inspection and aggregation systems unlock Saudi hospital procurement tender eligibility. |
| Cosmetics Ampoule Format Expansion | Premium skincare brands in Dubai and Riyadh drive 3-5x unit value expansion over pharmaceutical equivalents. |
| Egyptian Local Content Partnership | Egyptian Drug Authority incentives create displacement opportunities for European import-dependent supply chains. |
| WHO Prequalification Pathway Acceleration | Documented elemental impurity profiles enable vaccine fill-finish procurement in South Africa and Egypt. |
Research Methodology
Bottom-up pharmaceutical manufacturer modeling reconciled against top-down glass converter capacity tracking forms the analytical core of this study. Primary interviews with fill-finish operations managers, regulatory affairs leads at Saudi and UAE pharmaceutical firms, Egyptian Drug Authority compliance officers, and procurement directors at South African hospital groups combined with secondary validation from SFDA serialization guidelines, WHO prequalification standards, Egyptian industrial development authority filings, and regional customs trade data. This dual-layer approach triangulates demand signals against supply-side constraints.
Input-output matrices map borosilicate glass tubing flows through regional converter operations to end-use pharmaceutical and cosmetics applications across the analysis window. Segmentation dimensions include product type (glass, polymer, biodegradable), application (pharmaceuticals, cosmetics, chemicals), capacity specification, and end-user channel. CAGRs derive from installed base erosion rates, vaccine localization program timelines, and cosmetics premium format adoption curves. Forecast inputs incorporate SFDA compliance deadline schedules and Egyptian Drug Authority local content incentive enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas price volatility affecting furnace economics and polymer migration threshold revisions under evolving WHO standards. Forecasts reflect documented assumptions about serialization mandate adherence timelines and regional converter qualification success rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Medical Flexible Packaging Market