
 Spouted Dispensing Closures Market | 2026-2036
Spouted Dispensing Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Spouted Dispensing Closures Market Analytics
Polypropylene is broadening its share in spouted dispensing closures as converters replace polystyrene to meet tightened food-contact migration limits and improve post-consumer recyclability. AptarGroup leverages precision injection-molding expertise across European personal care lines to sustain premium positioning. Berry Global anchors North American supply through integrated resin-to-closure manufacturing. Silgan Dispensing Systems competes on high-speed capping compatibility with major filling equipment platforms.
Spouted dispensing closures are threaded or snap-fit dispensing devices featuring an integrated pour spout, typically injection-molded in single- or two-shot processes with living-hinge or tethered-cap designs, engineered to control viscosity flow and enable resealability for liquid, semi-liquid, or powdered contents. Flip-top formats lead volume in food and household applications where one-handed operation drives consumer preference, while push-pull variants are gaining fastest in sports nutrition and on-the-go beverage segments where flow-rate control commands price premiums. Plastic dominates material tonnage though composite laminates are penetrating personal care where barrier performance and aesthetic differentiation concentrate margin pools.
FDA food-contact notifications and EU Regulation 10/2011 on plastic materials shape migration testing protocols and approved substance lists, directly influencing resin selection and additive packages. REACH and state-level extended producer responsibility frameworks in California and Germany are forcing redesigns toward mono-material constructions and tethered-cap mandates to improve sortability and reduce litter. Stakeholders must monitor evolving mechanical recycling infrastructure compatibility standards and decide whether to prioritize chemical recycling partnerships or redesign for existing PET and HDPE streams.
Market Dynamics
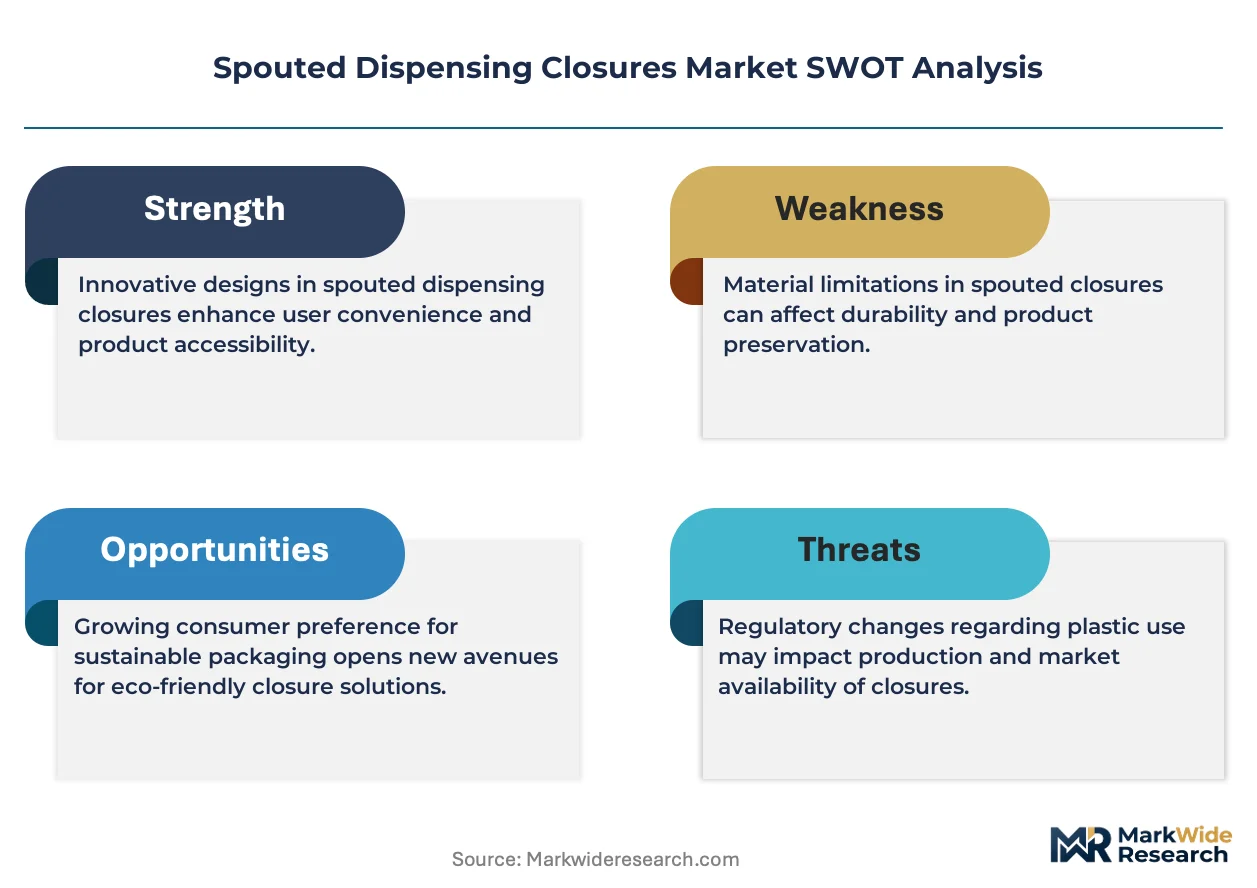
Spouted dispensing closures face mounting pressure from EU tethered-cap mandates and California's extended producer responsibility frameworks, forcing converters to redesign legacy snap-fit architectures while maintaining flow-rate precision across viscosity ranges.
Growth Catalysts
- REACH migration thresholds:Tightened EU substance restrictions on plastic food-contact materials accelerate polypropylene substitution for polystyrene, pulling demand toward recyclable mono-material designs.
- Precision injection-molding clusters:Southern Germany's tooling corridors supply living-hinge expertise that brand owners specify for premium sauce and condiment lines.
- Ready-to-drink beverage formats:On-the-go consumption patterns in sports nutrition drive push-pull variant specifications with calibrated flow control.
Market Restraints
- Resin price volatility:Polypropylene feedstock exposure to propylene monomer swings compresses converter margins during supply crunches.
- Mold fabrication bottlenecks:High-cavitation tooling for tethered-cap geometries concentrates among specialized German and Austrian suppliers.
- Mechanical recycling incompatibility:Living-hinge polypropylene closures contaminate PET sort streams, triggering MRF rejection penalties.
Strategic Opportunities
- India FSSAI packaging codes:Emerging formalization of food-grade plastic standards creates first-mover positioning for compliant closure suppliers.
- Chemical recycling partnerships:Pyrolysis of mixed polypropylene waste streams enables circularity claims without sort-purity requirements.
- Connected packaging integration:QR-embedded tethered caps bridge physical dispensing with digital loyalty and traceability platforms.
Industry Challenges
- Living-hinge fatigue engineering:Cycle-testing expertise for 10,000+ open-close durability requirements concentrates among aging specialist technicians.
- Dual-cavity validation timelines:FDA food-contact notification parallel with EU 10/2011 compliance extends new product qualification by 18-24 months.
- Legacy filling line retrofit costs:High-speed capping equipment compatibility demands constrain design freedom for innovative spout geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spouted Dispensing Closures Market |
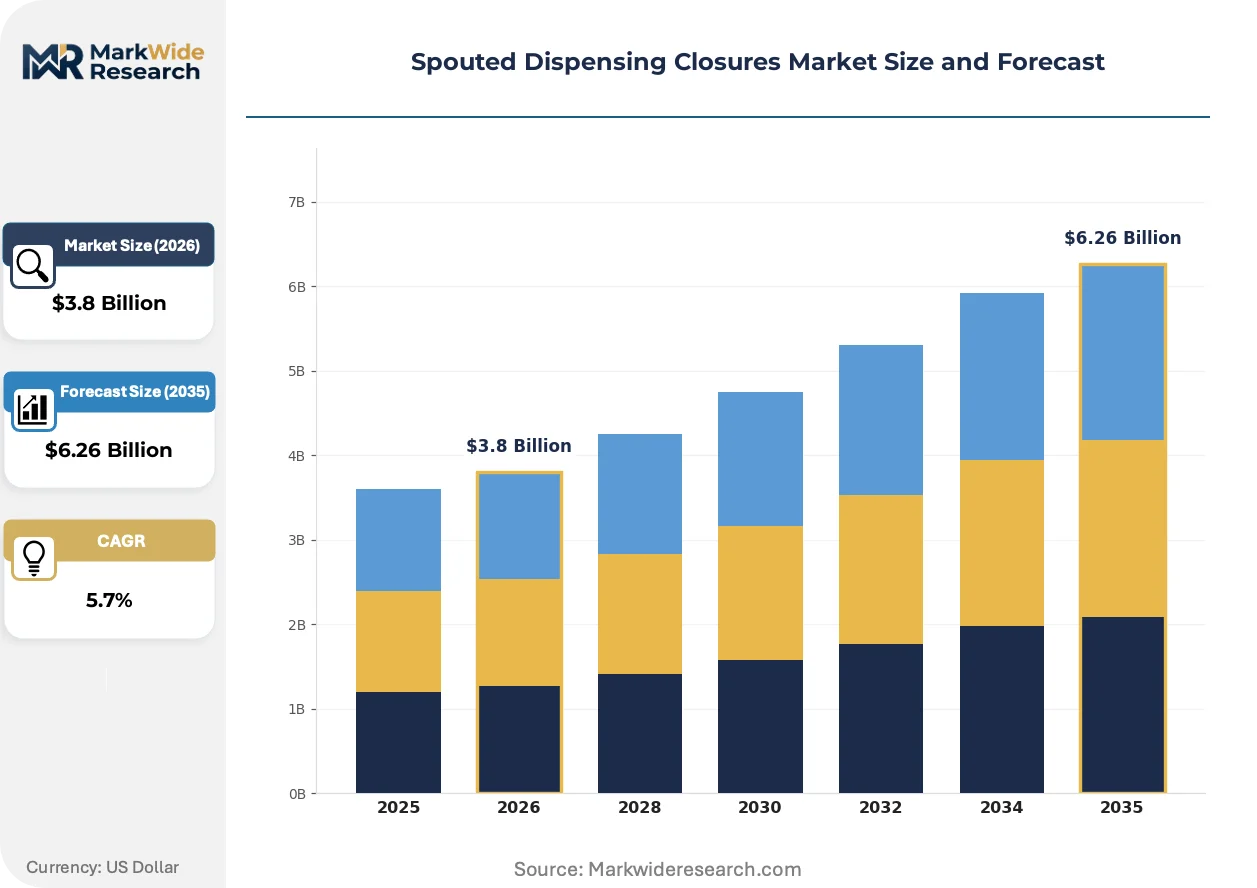
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Flip Top, Screw Cap, Push Pull, Snap-On Material: Plastic, Metal, Glass, Composite Application: Food & Beverage, Personal Care, Household, Industrial End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | AptarGroup, Inc., Berry Global Inc., Silgan Dispensing Systems, Mold-Rite Plastics, Weener Plastics Group, BERICAP, O.Berk Company, LLC, Closure Systems International, Albea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spouted Dispensing Closures Market Evolving Landscape
Active redesign of closure architectures is compressing development cycles as converters balance regulatory mandates against performance specifications and recyclability claims.
Biobased polypropylene derived from renewable feedstocks is electrifying material specification conversations among European personal care brand owners. Premium cosmetics lines in France and Germany now require mass-balance certified resins for new product launches. This shift is compressing conventional fossil-based sourcing contracts and forcing resin suppliers to secure ISCC PLUS chain-of-custody documentation.
EU Regulation 10/2011 amendments on migration testing protocols are tightening substance authorization lists for additives in food-contact plastics. Converters must reformulate antioxidant and slip-agent packages to maintain compliance. Sauce and condiment applications face the steepest reformulation burdens due to acidic content acceleration of migration rates.
Direct-to-retail procurement models are consolidating buyer power among private-label grocery chains in Germany and the Netherlands. These retailers now specify closure performance metrics and sustainability credentials through centralized technical teams. Mid-tier converters face margin compression as volume concentrates with suppliers offering integrated design-to-delivery capabilities.
Spouted Dispensing Closures Market Segmentation
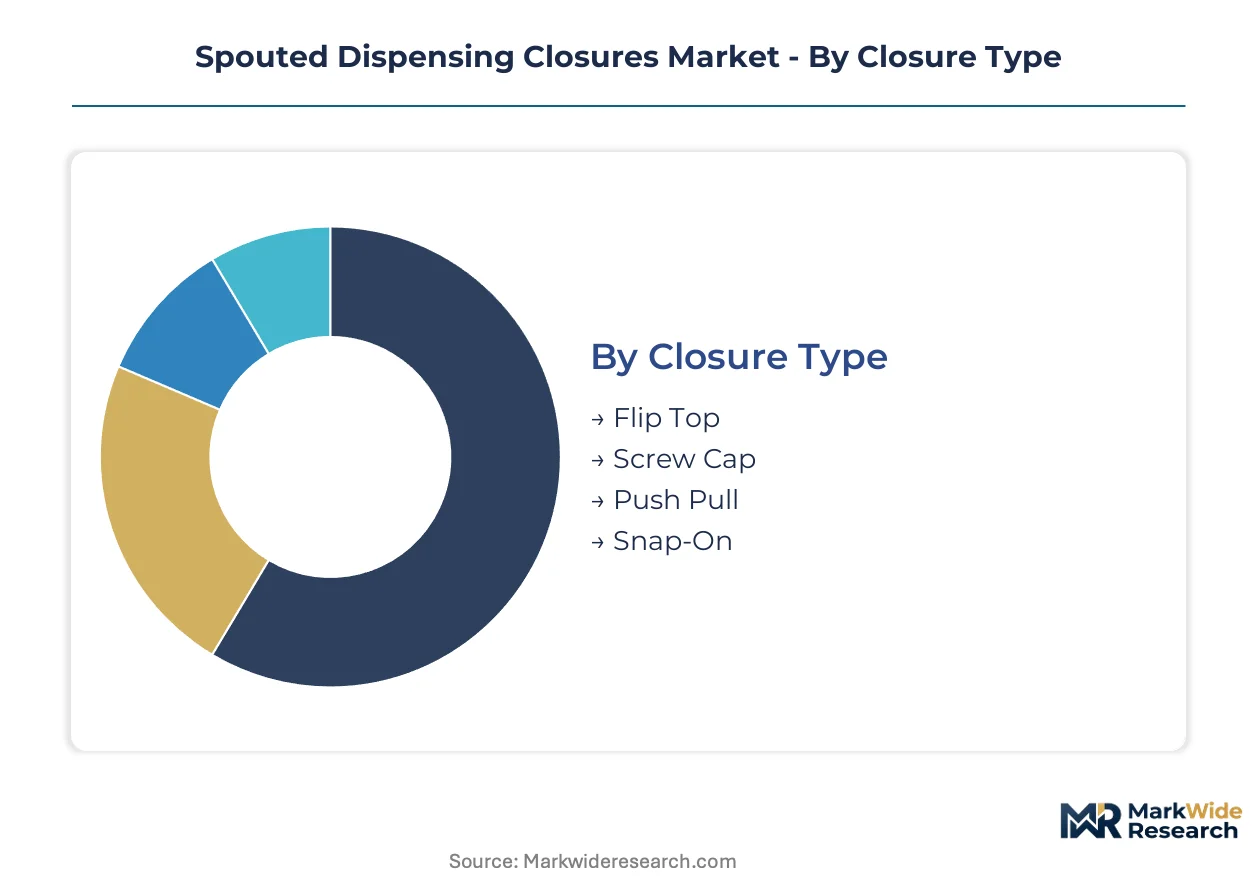
Spouted dispensing closures serve divergent performance requirements across food-contact, personal care, and industrial applications, with each segment imposing distinct migration testing protocols and mechanical durability specifications. Material selection and closure architecture must align with end-use viscosity ranges, resealability cycles, and recycling stream compatibility.
Closure Type:
FDA food-contact notifications and EU 10/2011 compliance timelines vary significantly across closure architectures, with living-hinge designs facing the most stringent fatigue-testing requirements.
- Flip Top:Living-hinge construction enables one-handed operation for sauces and condiments. German precision injection-molding clusters supply high-cavitation tooling for tethered-cap mandates in European sauce lines.
- Screw Cap:Threaded engagement delivers superior resealability for semi-liquid contents. Demand concentrates in North American household cleaner applications where leak-proof transport commands specification priority.
- Push Pull:Calibrated flow-rate control suits sports nutrition and ready-to-drink formats. California's extended producer responsibility frameworks accelerate tethered redesigns for this variant.
- Snap-On:Rapid assembly compatibility with high-speed filling equipment. Cost-sensitive industrial applications in India specify snap-on architectures for bulk chemical dispensing.
Leading the category by volume: Flip Top. Growing fastest: Push Pull.
Material:
Resin selection determines compliance pathways across REACH migration thresholds and mechanical recycling infrastructure compatibility.
- Plastic:Polypropylene dominates tonnage as converters abandon polystyrene for food-contact compliance. Southern Germany's brand owners now mandate mass-balance certified biobased grades for premium personal care launches.
- Metal:Aluminum and steel closures penetrate personal care where barrier performance and aesthetic differentiation support margin pools. French cosmetics lines specify metal-over-plastic for luxury positioning.
- Glass:Borosilicate and soda-lime constructions serve high-temperature sauce applications. Limited volume due to weight and fragility constraints in on-the-go formats.
- Composite:Multi-layer laminates combine barrier polymers with structural substrates. EU mechanical recycling incompatibility forces redesign toward mono-material alternatives.
Plastic commands volume leadership. Composite faces steepest substitution pressure.
Application:
End-use viscosity and acidity levels dictate antioxidant formulation and migration testing intensity.
- Food & Beverage:Acidic sauces and condiments accelerate additive migration rates, demanding reformulated slip-agent packages. FSSAI packaging code formalization in India creates compliance entry barriers.
- Personal Care:Premium cosmetics lines in France and Germany require ISCC PLUS chain-of-custody documentation for biobased resin sourcing.
- Household:Chemical resistance specifications favor polypropylene over polystyrene for bleach and surfactant compatibility.
- Industrial:Bulk lubricant and adhesive dispensing prioritizes cost minimization over recyclability claims.
Food & Beverage generates highest unit volumes. Personal Care captures premium pricing.
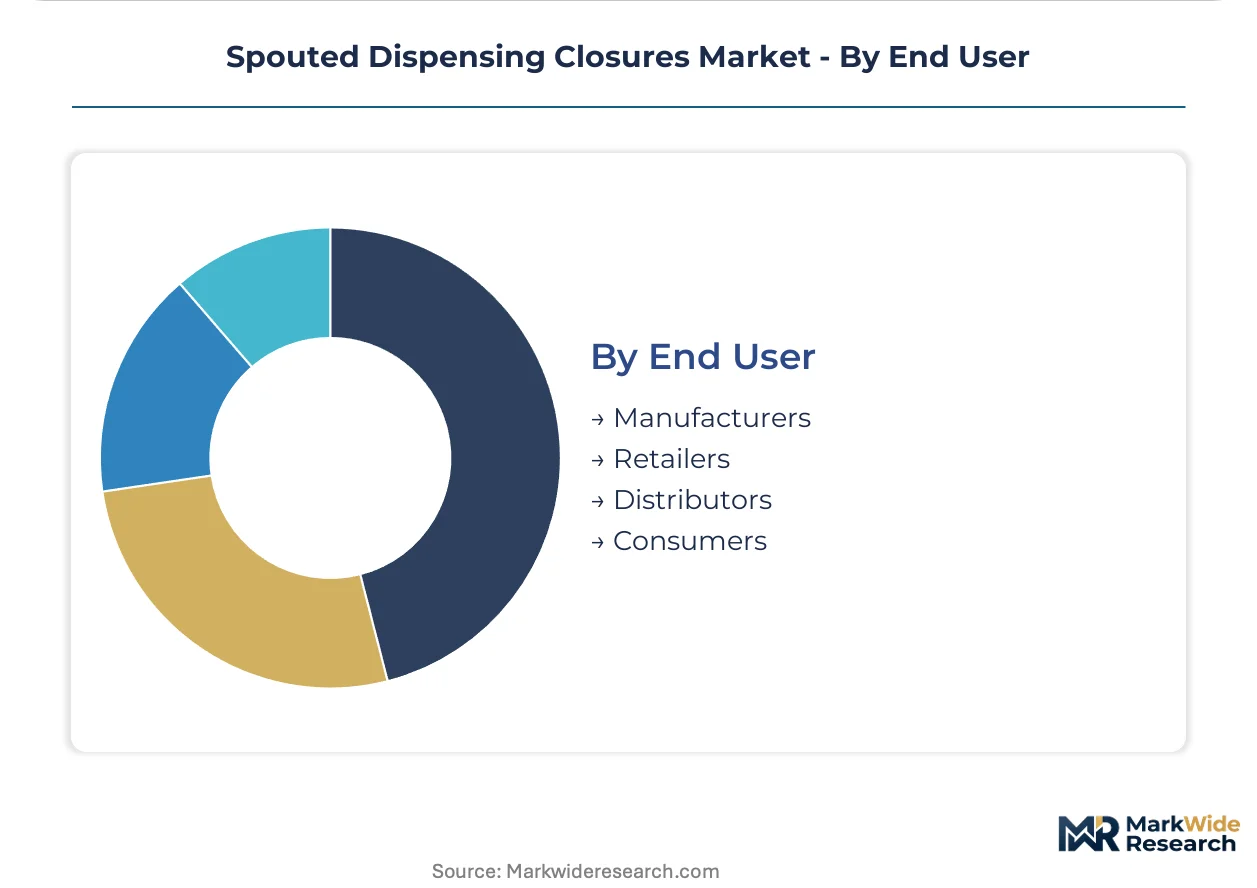
End User:
Procurement authority concentrates with direct-to-retail technical teams in consolidated European grocery chains.
- Manufacturers:Brand owners specify performance metrics and sustainability credentials through centralized packaging engineering functions.
- Retailers:German and Dutch private-label chains now mandate tethered-cap compliance and recycled content minimums.
- Distributors:Inventory risk exposure to polypropylene price volatility compresses working capital flexibility.
- Consumers:One-handed operation preference drives flip-top adoption in convenience-oriented formats.
Retailers exert fastest-growing procurement influence. Manufacturers retain specification authority for premium lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision injection-molding corridors in Baden-Württemberg and Bavaria operate as Europe's dominant tax-advantaged manufacturing zone for advanced closure systems, pulling brand-owner R&D investment and specialized tooling capacity into concentrated clusters.
Germany
Southern Germany's living-hinge expertise supplies tethered-cap mandates for premium sauce and condiment lines. REACH migration thresholds on plastic food-contact materials force polypropylene substitution for legacy polystyrene formulations. Stuttgart and Munich anchor high-cavitation tooling fabrication for EU-compliant closure architectures.
United States
California's extended producer responsibility frameworks accelerate redesign timelines for push-pull sports nutrition closures. FDA food-contact notifications govern additive packages for acidic sauce applications. Chicago and New Jersey manufacturing corridors concentrate integrated resin-to-closure production for North American household cleaner specifications.
India
FSSAI packaging code formalization creates compliance entry barriers for imported closure systems in food and beverage applications. Acidic condiment migration testing demands reformulated antioxidant packages distinct from Western formulations. Gujarat and Maharashtra plastic processing clusters scale snap-on architectures for cost-sensitive industrial chemical dispensing.
France
Premium cosmetics lines in Île-de-France require ISCC PLUS chain-of-custody documentation for mass-balance certified biobased polypropylene sourcing. ANSM oversight of personal care packaging materials shapes barrier performance specifications. Lyon and Paris basin converters supply metal-over-plastic luxury positioning for high-margin fragrance applications.
China
SAMR implementation of GB standards for food-contact plastics tightens migration testing protocols for export-oriented closure manufacturers. Yangtze River Delta injection-molding clusters supply high-volume flip-top formats for regional ready-to-drink beverage brands. Shanghai and Zhejiang tooling corridors compete on cost-positioning for tethered-cap redesigns serving European private-label demand.
Spouted Dispensing Closures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium personal care lines consolidating around design-integrated suppliers while food and beverage procurement concentrates with scale-driven converters. The vendor base organizes into three functional tiers: integrated resin-to-closure manufacturers, precision molding specialists, and regional fabrication shops serving cost-sensitive industrial applications. Strategic archetypes include European precision-engineering houses, North American integrated packaging conglomerates, and Asian high-volume exporters. Capacity expansion and tethered-cap compliance redesign represent the dominant competitive moves as regulatory deadlines compress development cycles.
Within the precision-engineering tier, AptarGroup and Weener Plastics Group exemplify European specialists leveraging living-hinge expertise for premium sauce and condiment specifications. Berry Global anchors North American supply through backward integration into resin production and captive closure manufacturing. Silgan Dispensing Systems occupies a position calibrated to high-speed capping equipment compatibility, serving major filling platform specifications across multiple beverage categories.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Berry Global Inc. |
| Silgan Dispensing Systems |
| Mold-Rite Plastics |
| Weener Plastics Group |
| BERICAP |
| O.Berk Company, LLC |
| Closure Systems International |
| Albea Group |
| Others |
Value Network & Pricing Analysis
Tethered-cap mandates from EU Regulation 10/2011 and California's extended producer responsibility frameworks force converters to absorb high-cavitation tooling premiums and reformulation costs, compressing margins on legacy flip-top architectures while creating pricing power for compliant living-hinge specialists.
Pricing Analysis
Short lead-time premiums command pricing power for German precision injection-molding clusters serving urgent tethered-cap redesigns ahead of regulatory deadlines. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS-certified biobased grades from fossil-based polypropylene and spot-market resin. Pricing pressure stems from propylene monomer volatility and concentrated mold fabrication bottlenecks among Austrian and German tooling suppliers. Private-label grocery chains in Germany and the Netherlands exert the sharpest price sensitivity through centralized technical procurement teams, while premium cosmetics brand owners in France show least sensitivity to mass-balance certified resin premiums.
Supply Chain Analysis
Polypropylene resin supply rests on propylene cracker capacity concentrated in Germany, Belgium, and the Netherlands, with biobased feedstock certification anchoring emerging differentiation. High-cavitation mold fabrication draws from specialized tooling corridors in Baden-Württemberg and Upper Austria, while antioxidant and slip-agent additive packages source from Swiss and German specialty chemical producers. Single-source vulnerability concentrates in living-hinge fatigue-testing expertise among aging specialist technicians in southern Germany. Distribution runs through integrated resin-to-closure manufacturers for North American household specifications, with direct-to-retail procurement consolidating European food and beverage volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation 10/2011 migration testing protocols and tethered-cap mandates erect compliance moats that favor incumbent converters with validated dual-cavity FDA-EU qualification timelines, raising capital barriers for undercapitalized entrants lacking parallel regulatory expertise.
For Market Incumbents: Acquire high-cavitation tooling fabrication capacity in Baden-Württemberg to secure living-hinge expertise ahead of EU regulatory deadlines. Build backward integration into mass-balance certified biobased polypropylene sourcing to defend margin position against fossil-based resin volatility and capture premium personal care specifications in France and Germany. For New Entrants and Emerging Players: Capture FSSAI packaging code compliance positioning in India's Gujarat and Maharashtra processing clusters before formalized standards harden entry barriers. Target cost-sensitive industrial chemical dispensing applications with snap-on architectures, leveraging lower regulatory burden and faster qualification timelines than food-contact segments. For Investors and Strategic Acquirers: Re-rating potential sits with precision-engineering specialists possessing validated tethered-cap architectures given accelerating EU and California regulatory deadlines. Long-term viability favors converters with integrated design-to-delivery capabilities serving consolidated private-label retail procurement. Watch for chemical recycling partnership announcements as inflection signal for circularity-claim differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biobased Resin Sourcing | ISCC PLUS certification secures premium positioning for French and German cosmetics launches. |
| High-Cavitation Tooling Capacity Expansion | Baden-Württemberg fabrication clusters capture EU tethered-cap mandate pull-through demand. |
| Chemical Recycling Partnership Formation | Pyrolysis of mixed polypropylene waste enables circularity claims without sort-purity requirements. |
| Connected Packaging Integration | QR-embedded tethered caps bridge physical dispensing with digital loyalty platforms for brand owners. |
| FSSAI Compliance-First Market Entry | Early positioning in India's formalizing food-grade standards creates sustainable competitive positioning. |
Research Methodology
Trade association filings from PlasticsEurope, customs data from Eurostat and USITC, and regulatory submissions to FDA and ECHA formed the secondary backbone for resin flow and compliance pathway mapping. Primary interviews with injection-molding plant managers, procurement leads at German private-label grocery chains, technical R&D directors at closure converters, and brand owner packaging engineers combined with secondary validation. Bottom-up capacity modeling and top-down demand triangulation anchored market sizing across closure type, material grade, and application segments.
Historical trendline analysis of polypropylene substitution patterns and living-hinge adoption rates informed projection frameworks across the analysis window. Segmentation modeling captured closure architecture, resin certification tier, end-use viscosity requirements, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating EU 10/2011 amendment timelines and California extended producer responsibility implementation phases. Industry-specific inputs included propylene monomer price volatility indices and high-cavitation tooling capacity utilization rates from German mold fabrication corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mechanical recycling infrastructure buildout pace and chemical recycling technology cost curves. Assumptions reflect current regulatory trajectories for tethered-cap mandates and migration threshold tightening. A small set of triggers warrants ongoing watch: FSSAI code formalization acceleration, REACH substance authorization list expansion, and biobased polypropylene mass-balance certification fraud detection protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Spray Caps Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Cap Seals Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Box Latch Market
Caps and Closures
Crown Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Plastic Tamper Evident Closures Market