
 Pharmaceutical Bottles Market | 2026-2036
Pharmaceutical Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Bottles Market Outlook
Subscription-based compliance tracking and software-defined lot verification is rebalancing how pharmaceutical bottle contracts are structured. Gerresheimer AG leverages its glass-forming expertise to anchor high-value vial and bottle supply for injectable drugs. Amcor plc sustains global polymer capacity that competes across multiple pharmaceutical packaging tiers. Berry Global Inc. specializes in child-resistant closure systems that differentiate its integrated bottle-plus-cap offerings.
Pharmaceutical bottles are rigid primary packaging vessels, typically manufactured from borosilicate glass or pharmaceutical-grade polymers such as polyethylene and polypropylene, designed to protect drug products from moisture, oxygen, and light ingress while ensuring patient safety through functional closure systems. Glass bottles retain dominance in parenteral and high-sensitivity drug applications where inertness and barrier performance are non-negotiable, while plastic bottles are capturing volume in oral solid dose and over-the-counter segments where cost and logistics efficiency matter more. Dropper bottles represent a concentrated margin pool within the closure-type landscape, as precise dosing requirements for ophthalmic and pediatric formulations command premium positioning.
The FDA enforces current Good Manufacturing Practice standards that dictate material compatibility, child-resistant performance, and tamper-evidence for all pharmaceutical primary packaging sold in the United States. The European Medicines Agency applies the EU Medical Device Regulation and F-Gas restrictions that shape material selection and barrier specifications for bottles distributed across EU member states. India's Central Drugs Standard Control Organization enforces packaging integrity rules under its pharmaceutical quality framework, tightening standards as domestic manufacturing scales. Stakeholders must monitor how diverging national serialization timelines and evolving sustainability mandates for polymer recyclability will reshape supplier qualification criteria and capital allocation across material platforms.
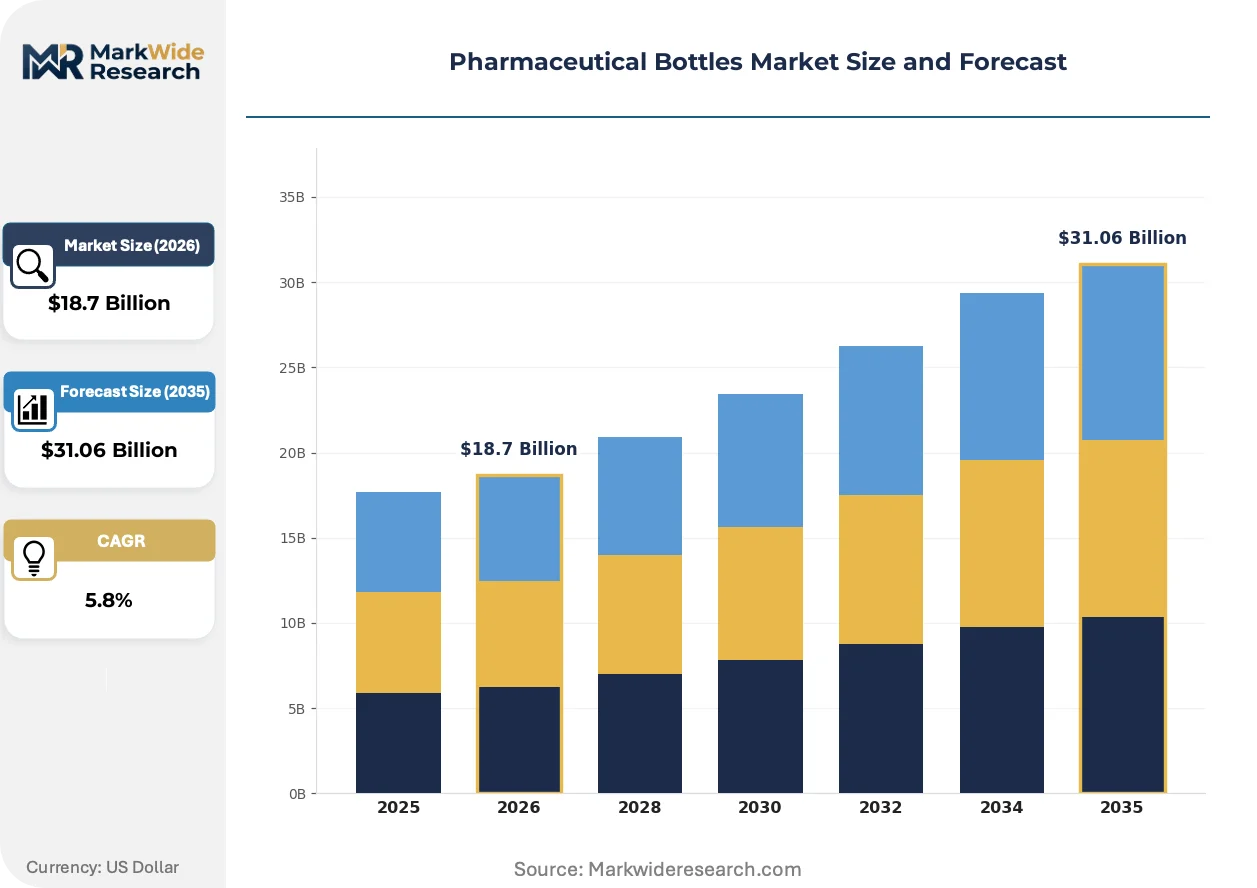
Market Dynamics
Serialization mandates from the FDA and EU MDR are compressing supplier qualification timelines while biologics proliferation concentrates demand for high-barrier packaging formats. Manufacturers must now synchronize material science capabilities with track-and-trace infrastructure investments.
Growth Catalysts
- Biologics Storage Expansion:Cell and gene therapy pipelines require specialized cyclic olefin polymer bottles with moisture barriers below 0.5% water vapor transmission rate.
- EU MDR Compliance Deadlines:European pharmaceutical manufacturers are retrofitting packaging lines to meet device regulation traceability requirements ahead of enforcement milestones.
- India CDSCO Quality Enforcement:Domestic manufacturers upgrading from basic polyethylene to multilayer barrier bottles to meet tightened export-grade packaging integrity standards.
Market Restraints
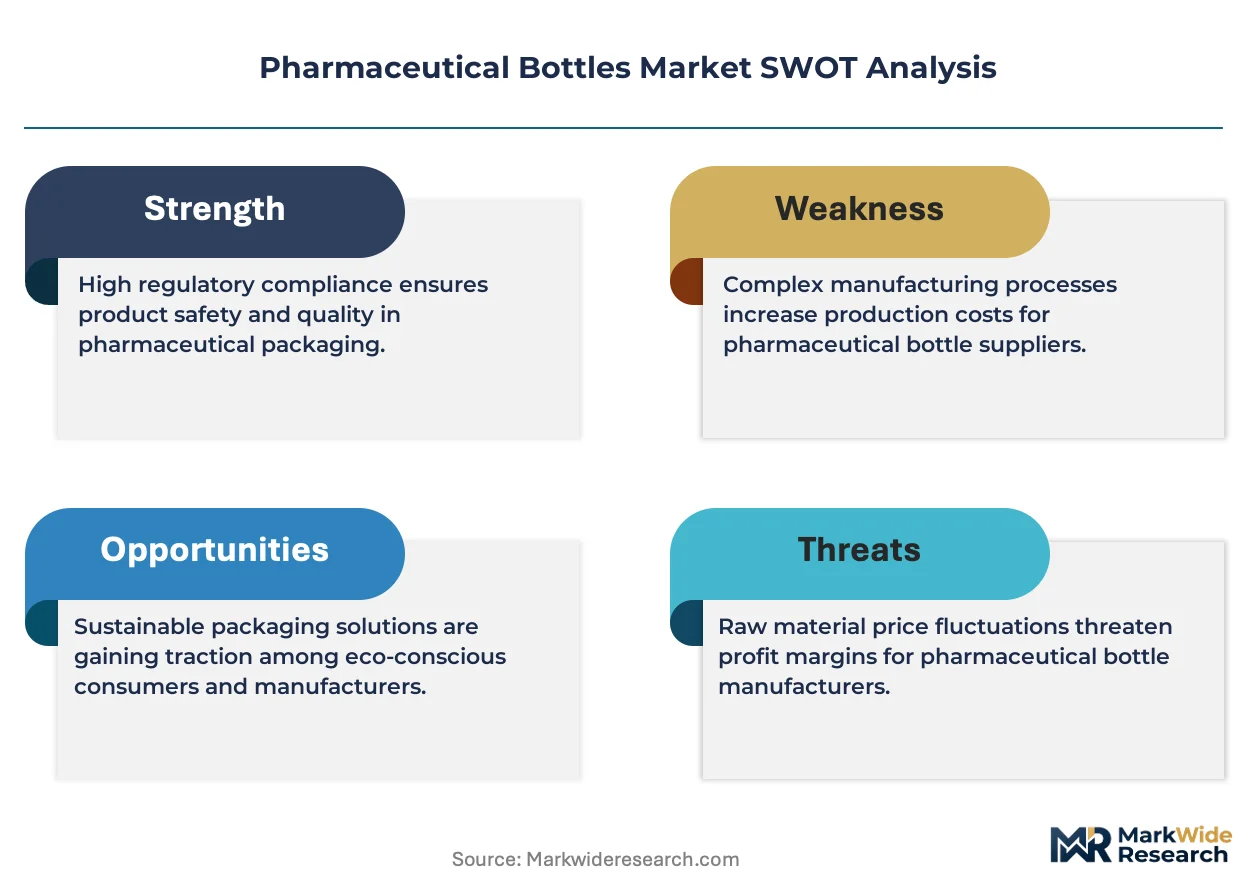
- Raw Material Concentration:Pharmaceutical-grade borosilicate glass supply concentrates among three European and Japanese manufacturers, creating vulnerability to energy cost spikes.
- Fluoropolymer Restrictions:EU F-Gas Regulation limits perfluorinated barrier coatings, forcing reformulation of high-performance multilayer structures.
- Substitution Pressure:Blow-fill-seal ampoules capture parenteral volume from traditional glass vials in single-dose ophthalmic and emergency medicine applications.
Strategic Opportunities
- German Serialization Infrastructure:Contract packaging organizations serving EU markets seek qualified bottle suppliers with integrated aggregation and verification systems.
- Connected Packaging Convergence:Near-field communication chips embedded in bottle closures enable patient adherence monitoring and cold chain verification.
- United States IRA Manufacturing Incentives:Domestic production credits for active pharmaceutical ingredients extend to qualifying primary packaging operations.
Industry Challenges
- Validation Timeline Compression:FDA current Good Manufacturing Practice changes require re-qualification of existing polymer grades, extending new product introduction cycles.
- Legacy Equipment Retrofit Costs:Glass-to-plastic format conversions demand capital-intensive mold and handling system modifications at contract filler sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Bottles Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Bottles, Plastic Bottles, Aerosol Containers, Dropper Bottles Closure Type: Child-Resistant Closures, Tamper-Evident Caps, Screw Caps, Dropper Caps End User: Pharmacies, Hospitals, Clinics, Biopharmaceutical Companies Material: Polyethylene, Polypropylene, PVC, Borosilicate Glass |
| Companies Covered | Gerresheimer AG, Amcor plc, Berry Global Inc., SGD Pharma, AptarGroup, Inc., Schott AG, Bormioli Pharma, DWK Life Sciences, O-I Glass, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Bottles Market Strategic Shifts
Material science advances and regulatory digitization are converging to redefine barrier performance standards and supply chain transparency expectations across pharmaceutical packaging tiers.
Cyclic olefin polymers with silicon oxide coatings are expanding into parenteral applications previously reserved for borosilicate glass. Biopharmaceutical companies adopting these materials for protein-based injectables cite reduced breakage rates and weight-based logistics savings. The technology is expanding into high-value orphan drug segments where distribution cost sensitivity intersects with stringent stability requirements.
EU Medical Device Regulation serialization mandates now require unique device identifiers on primary packaging for certain drug-device combination products. German and French pharmaceutical manufacturers are consolidating supplier bases to reduce qualification burden. Parenteral bottle categories face the steepest compliance ramps as aggregation requirements extend from case to individual unit level.
Biopharmaceutical procurement departments are consolidating annual bottle contracts around suppliers with integrated track-and-trace capabilities. Large molecule drug sponsors in the United States now specify serialization-ready packaging in early-phase development agreements. This specification pattern compresses the supplier selection window and elevates technical service capabilities above unit cost in vendor scoring.
Pharmaceutical Bottles Market Segmentation
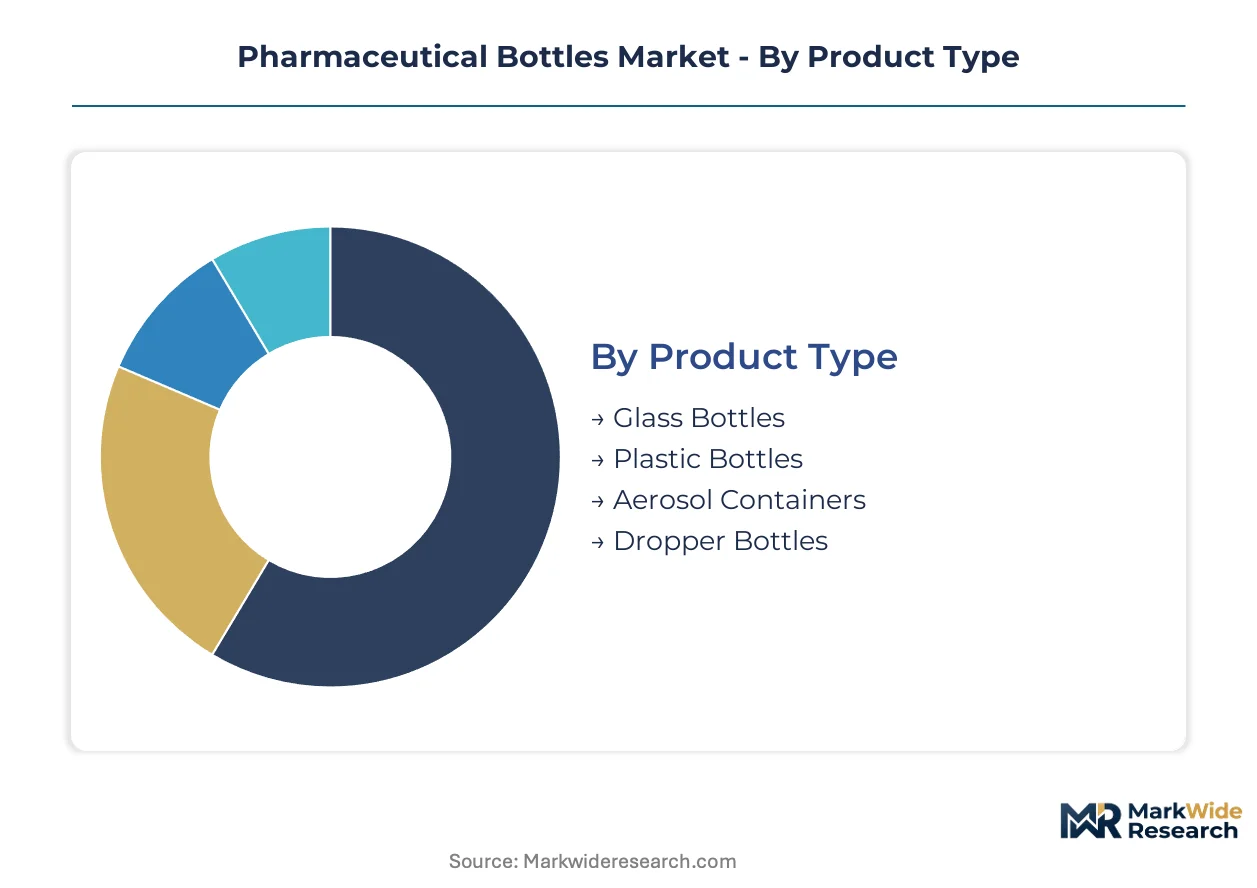
Segmentation in pharmaceutical bottles reveals how material science, regulatory compliance, and end-use requirements stratify supply capabilities. Suppliers configure production assets around specific barrier performance tiers rather than pursuing undifferentiated volume.
Product Type:
Glass-forming capacity concentrates in European and Japanese manufacturing clusters, while polymer conversion scales across distributed regional plants.
- Glass Bottles:Borosilicate and soda-lime formulations dominate parenteral and high-sensitivity drug applications where inertness is mandatory. Demand concentrates in Germany and Switzerland for injectable biologics, with CDSCO tightening import specifications for Indian-market glass containers.
- Plastic Bottles:High-density polyethylene and polypropylene structures capture oral solid dose and over-the-counter volume where logistics efficiency outweighs barrier premium. United States contract fillers are expanding HDPE lines for generic tablet packaging under IRA domestic production incentives.
- Aerosol Containers:Pressurized aluminum and coated glass systems serve topical foam and inhalation therapies with specialized valve integration.
- Dropper Bottles:Precision-dosing formats for ophthalmic and pediatric formulations command formulation-specific closure engineering.
Today's leader: Glass Bottles. Tomorrow's challenger: Plastic Bottles.
Closure Type:
Cost tiers separate commodity screw caps from engineered child-resistant and tamper-evident systems that require dedicated mold investments and regulatory certification.
- Child-Resistant Closures:Push-and-turn or squeeze-and-turn mechanisms meeting ISO 8317 and US 16 CFR 1700.20 standards. United States OTC analgesic manufacturers specify these closures as default, with FDA enforcement driving universal adoption for household-risk medications.
- Tamper-Evident Caps:Ring-break or shrink-band designs providing visual integrity assurance. European pharmaceutical manufacturers retrofit lines for EU MDR traceability integration with tamper-evidence verification.
- Screw Caps:Standard threaded closures for prescription vials and bulk hospital containers where cost minimization dominates.
- Dropper Caps:Bulb-and-pipette assemblies requiring dimensional precision for microliter dosing accuracy in ophthalmic applications.
Regulatory mandates elevate Child-Resistant Closures. Technical differentiation favors Dropper Caps.
End User:
Customer type determines order scale, specification stringency, and supplier technical service intensity.
- Biopharmaceutical Companies:Large molecule drug sponsors demand cyclic olefin polymer bottles with sub-0.5% moisture vapor transmission rates for protein stability. United States cell therapy developers are qualifying specialized barrier bottles with integrated NFC-enabled adherence monitoring.
- Pharmacies:Retail dispensaries drive high-volume demand for standard amber glass and white HDPE prescription vials with rapid replenishment cycles.
- Hospitals:Institutional purchasers prioritize unit-dose and compliance-prompting packaging for medication administration safety.
- Clinics:Outpatient facilities require mid-scale orders with flexible labeling for multi-site distribution networks.
Volume concentrates in Pharmacies. Value creation shifts toward Biopharmaceutical Companies.
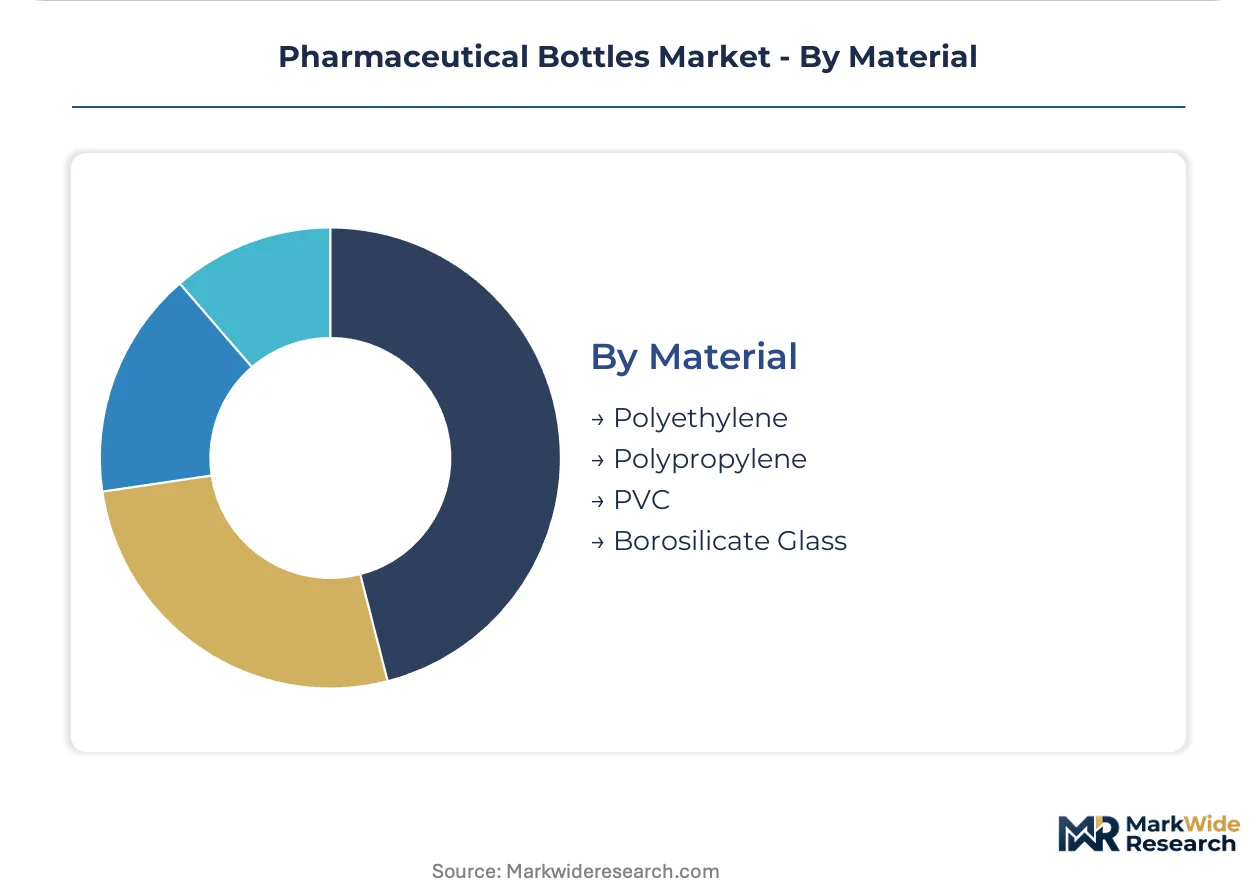
Material:
Margin structures diverge sharply between commodity polymer grades and pharmaceutical-certified glass with documented batch traceability.
- Borosilicate Glass:Thermal shock resistance and chemical inertness make this mandatory for parenteral and lyophilized drug storage. German and Japanese suppliers control premium tubular and molded glass capacity, with energy cost spikes transmitting directly to pharmaceutical packaging procurement budgets.
- Polyethylene:HDPE and LDPE grades dominate oral solid dose bottles where moisture barrier requirements permit polymer economics. Indian domestic manufacturers are upgrading from basic PE to multilayer structures for export-grade compliance.
- Polypropylene:Higher temperature tolerance suits hot-fill and sterilization protocols for liquid formulations.
- PVC:Remaining applications concentrate in specific blister and container formats with established drug compatibility profiles.
Barrier performance anchors Borosilicate Glass. Cost-driven substitution elevates Polyethylene.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium glass-forming capacity for parenteral applications while India scales polymer conversion for export-grade oral solid dose packaging, revealing how material specialization divides geographic roles in pharmaceutical bottle supply chains.
United States
Cell and gene therapy developers drive demand for cyclic olefin polymer bottles with sub-0.5% moisture vapor transmission rates. The FDA's Drug Supply Chain Security Act serialization mandates compress supplier qualification timelines for domestic manufacturers. New Jersey and Massachusetts biopharma clusters are retrofitting packaging lines to integrate track-and-trace infrastructure ahead of enforcement milestones.
Germany
Injectable biologics manufacturers concentrate demand for borosilicate glass vials with documented batch traceability. The EU Medical Device Regulation's unique device identifier requirements reshape packaging line investments across Bavarian and North Rhine-Westphalian facilities. Gerresheimer AG anchors high-value tubular glass supply from its Mainz and Essen manufacturing sites.
India
Domestic pharmaceutical exporters upgrade from basic polyethylene to multilayer barrier bottles for regulated markets. CDSCO packaging integrity enforcement under its pharmaceutical quality framework tightens specifications for containers bound to the United States and European Union. Gujarat and Maharashtra polymer conversion clusters expand capacity to capture contract manufacturing organization volume.
Japan
Specialty glass manufacturers serve domestic biopharmaceutical sponsors with thermal shock-resistant containers for lyophilized drug storage. PMDA stability guidelines elevate barrier performance requirements for protein-based injectables. Osaka and Tokyo pharmaceutical packaging corridors concentrate molding and forming expertise for high-sensitivity drug applications.
Switzerland
Orphan drug developers source premium barrier bottles with integrated adherence monitoring capabilities. Swissmedic serialization alignment with EU MDR traceability standards drives supplier consolidation among Basel-area biopharmaceutical procurement departments. The country's packaging specification patterns influence contract filler requirements across neighboring EU member states.
Pharmaceutical Bottles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with glass-forming expertise concentrating among European and Japanese incumbents while polymer conversion scales through distributed regional networks. The market structures around three archetypes: integrated material science platforms, specialized barrier technology developers, and high-volume commodity converters. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers synchronize material capabilities with serialization infrastructure investments.
Among European glass-forming specialists, Gerresheimer AG and Schott AG exemplify the premium-tier archetype anchored by pharmaceutical-certified borosilicate capacity. Amcor plc occupies a position spanning multiple material platforms and geographic markets. These three entities represent how supplier consolidation around integrated track-and-trace capabilities is compressing vendor selection windows for biopharmaceutical procurement departments.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Amcor plc |
| Berry Global Inc. |
| SGD Pharma |
| AptarGroup, Inc. |
| Schott AG |
| Bormioli Pharma |
| DWK Life Sciences |
| O-I Glass, Inc. |
| Others |
Value Chain & Pricing Dynamics
Biopharmaceutical procurement departments consolidating annual contracts around serialization-ready suppliers are compressing vendor selection windows and elevating technical service premiums above unit cost in contract negotiations. This buyer-driven consolidation forces supply-side specialization and reshapes margin distribution across material platforms.
Pricing Analysis
Capacity additions in India's Gujarat and Maharashtra polymer conversion clusters are reshaping price floors for oral solid dose packaging tiers. Three-tier pricing structure across premium barrier, standard multilayer, and economy polyethylene levels separates biopharmaceutical sponsors from generic tablet manufacturers from domestic Indian dispensaries. Cost compression in standard HDPE bottles is intensifying because of IRA domestic production incentives attracting new entrants. Generic contract fillers exhibit highest price sensitivity; cell therapy developers show lowest.
Supply Chain Analysis
Specialized glass-forming technicians concentrate in Germany's Mainz-Essen corridor and Japan's Osaka-Tokyo pharmaceutical packaging belt, constraining rapid capacity scaling. Pharmaceutical-grade borosilicate glass supply rests on German and Japanese manufacturers, while polymer conversion feeds from Indian and United States regional plants. Raw material dependencies span energy-intensive silica processing, pharmaceutical-certified resin grades, and specialized closure mold tooling. Single-source vulnerability concentrates in European tubular glass capacity. Distribution runs through contract packaging organizations serving biopharmaceutical sponsors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as biopharmaceutical sponsors specify sub-0.5% moisture vapor transmission barrier bottles in early-phase development agreements, locking in premium supply relationships before manufacturing scale.
For Market Incumbents: Acquire specialized cyclic olefin polymer forming capacity to anchor high-barrier supply relationships with cell therapy developers. Consolidate track-and-trace infrastructure investments ahead of EU MDR aggregation deadlines to defend against contract packaging organizations backward integrating into bottle supply. Certification investment in FDA current Good Manufacturing Practice compliance creates switching costs for biopharmaceutical procurement departments. For New Entrants and Emerging Players: CDSCO quality enforcement in India opens a window for multilayer barrier bottle specialists serving domestic exporters upgrading from basic polyethylene. Target oral solid dose contract manufacturing organization volume in Gujarat and Maharashtra polymer conversion corridors. Go-to-market through integrated serialization-ready packaging bundles rather than commodity per-unit pricing. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized barrier technology developers possessing cyclic olefin polymer coating expertise and existing biopharmaceutical sponsor relationships. Five-to-ten-year viability hinges on material science differentiation rather than undifferentiated volume scale. Watch for FDA serialization enforcement milestones as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Integration | EU MDR aggregation requirements compress vendor qualification timelines for German contract fillers. |
| Barrier Technology Licensing | Cyclic olefin polymer coating patents enable premium positioning in protein-based injectables storage. |
| Backward Integration into Resin Supply | Pharmaceutical-grade polyethylene captive production secures margin control for Indian generic packaging. |
| Joint Venture with Track-and-Trace Platform | NFC-enabled closure partnerships capture adherence monitoring value in Swiss orphan drug segments. |
| Capacity Expansion in Cyclic Olefin Polymers | United States cell therapy clusters demand localized sub-0.5% moisture vapor transmission rate supply. |
Study Parameters
Bottom-up biopharmaceutical sponsor modeling reconciled against top-down polymer conversion capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, pharmaceutical procurement managers, contract packaging organization executives, and CDSCO compliance officers combined with secondary validation against FDA Drug Supply Chain Security Act filings, EMA Medical Device Regulation guidance documents, Indian pharmaceutical export databases, and SEC 10-K disclosures from listed packaging manufacturers. Triangulation between demand-side specification patterns and supply-side asset deployment ensures consistency across material platform forecasts.
Historical trendline analysis of glass-forming and polymer conversion capacity utilization established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, closure mechanism, end-user archetype, material platform, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of disclosed capacity expansions, sponsor pipeline progression, and enforcement milestone timing. Industry-specific inputs included biologics pipeline stage transitions and serialization infrastructure investment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy cost spikes affecting European borosilicate glass production and FDA current Good Manufacturing Practice revision timing. Forecasts reflect documented assumptions regarding regulatory enforcement adherence and sponsor specification evolution. Material deviation in EU MDR aggregation deadlines or CDSCO export-grade packaging integrity enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Injectable Drug Packaging Market