
 Pharmaceutical Container Market | 2026-2036
Pharmaceutical Container Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Container Market Analytics
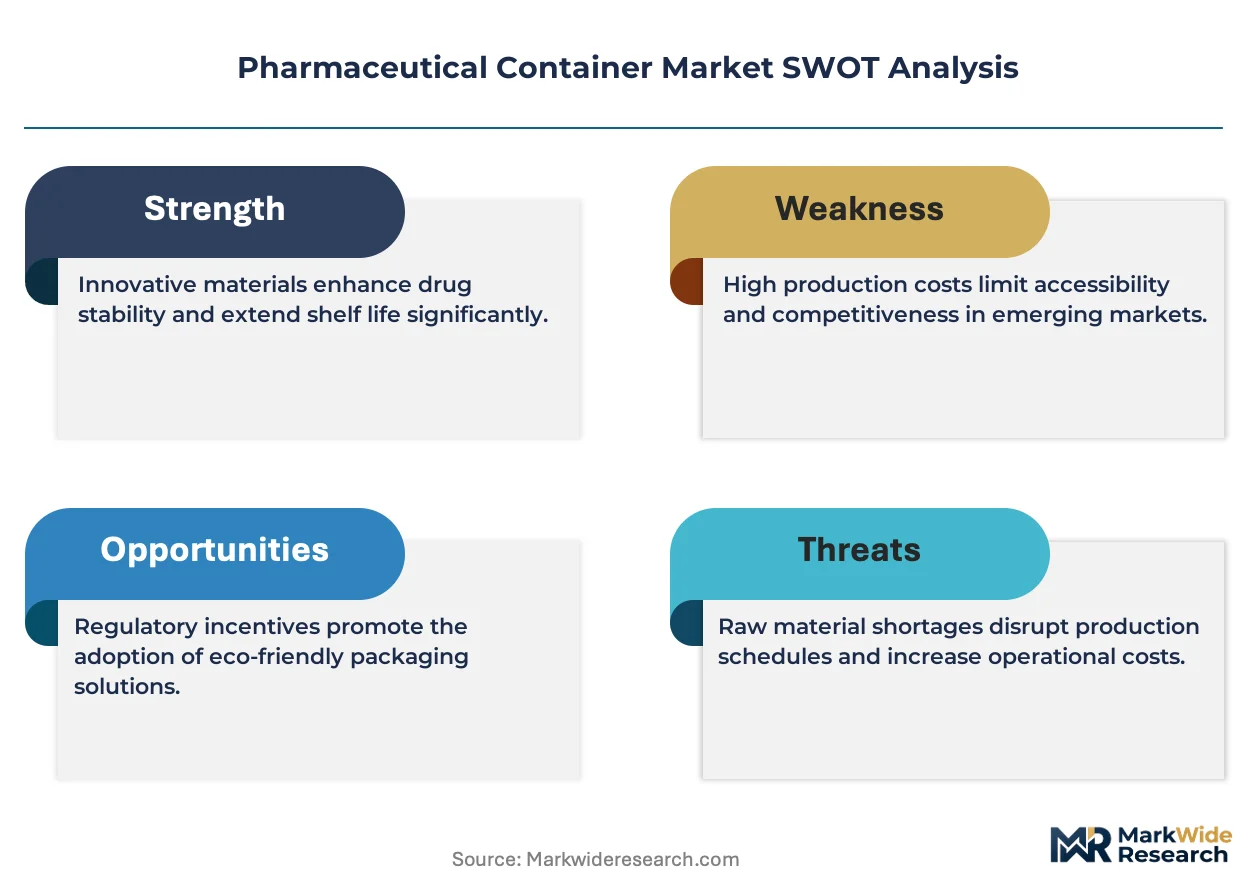
The performance gap between premium pharmaceutical containers and commodity packaging is broadening. High-value biologics demand borosilicate glass and cyclic olefin polymer with validated extractables profiles, while generic oral solids tolerate lower-specification resins. Gerresheimer AG anchors European supply of prefillable glass syringes through captive mold technology. Schott AG dominates tubular glass vial production for mRNA cold-chain applications. Berry Global Group competes in plastic container segments with multi-layer barrier structures for moisture-sensitive formulations.
Pharmaceutical containers are engineered enclosures designed to maintain drug stability, prevent contamination, and enable accurate dosing across storage and administration cycles. Borosilicate glass Type I offers hydrolytic resistance below 0.7 ml for parenteral biologics, while multi-layer co-extruded plastics achieve oxygen transmission rates below 0.1 cc per day for oxygen-sensitive APIs. Glass vials retain the largest volume share in parenteral applications where USP <660> compliance is mandatory. Plastic bottles are expanding fastest in oral solid dispensing as pharmacies adopt child-resistant, senior-friendly closure systems. Primary packaging commands the deepest margin pool because qualification cycles with drug sponsors extend three to five years and create switching costs.
FDA container closure guidance, EU MDR Annex I general safety requirements, and USP <1661> evaluation criteria collectively elevate barrier performance and documentation burdens for suppliers. EMA's tightened nitrosamine risk assessments now extend to elastomeric closure formulations, forcing reformulation of rubber stoppers and plungers. Stakeholders must monitor how pharmacopeial harmonization between USP, EP, and JP chapters reshapes global qualification pathways.
Market Dynamics
Biologic drug manufacturers are forcing container specifications upward as mRNA vaccines and cell therapies demand validated extractables profiles and cold-chain integrity. Suppliers now face three-to-five-year qualification cycles that lock in sourcing relationships and compress margin competition to technical performance.
Growth Catalysts
- EMA nitrosamine assessments:Tightened scrutiny of elastomeric closures is forcing reformulation of rubber stoppers and plungers, creating upgrade demand across installed base.
- Glass molding automation:Captive mold technology is lowering unit costs for prefillable syringes while tightening dimensional tolerances below 0.1 millimeters.
- German production clustering:Specialized glass manufacturing concentrates around Mainz and Mitterteich, anchoring European supply security for parenteral applications.
Market Restraints
- Borosilicate sand scarcity:High-purity silica feedstock faces extraction limits in select mining jurisdictions, creating input cost volatility for Type I glass.
- Qualification timeline compression:USP <1661> evaluation criteria extend validation protocols, delaying revenue recognition for eighteen to thirty-six months post-contract.
- Plastic barrier substitution:Multi-layer co-extruded polymers achieve oxygen transmission rates below 0.1 cc per day, displacing glass in oral solid segments.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are localizing container sourcing for export markets.
- Connected packaging integration:Near-field communication tags and temperature loggers are converging with primary containers for cold-chain verification.
- EU MDR Annex I compliance:General safety requirements for device-like drug delivery systems create premium positioning for validated container-closure systems.
Industry Challenges
- Extractables chemist scarcity:Analytical toxicologists capable of designing USP <1664> compliant study protocols command salary premiums exceeding forty percent above standard quality assurance roles.
- Legacy inspection equipment:Automated visual inspection systems for glass particulate detection require capital outlays exceeding two million dollars per line, straining mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Container Market |
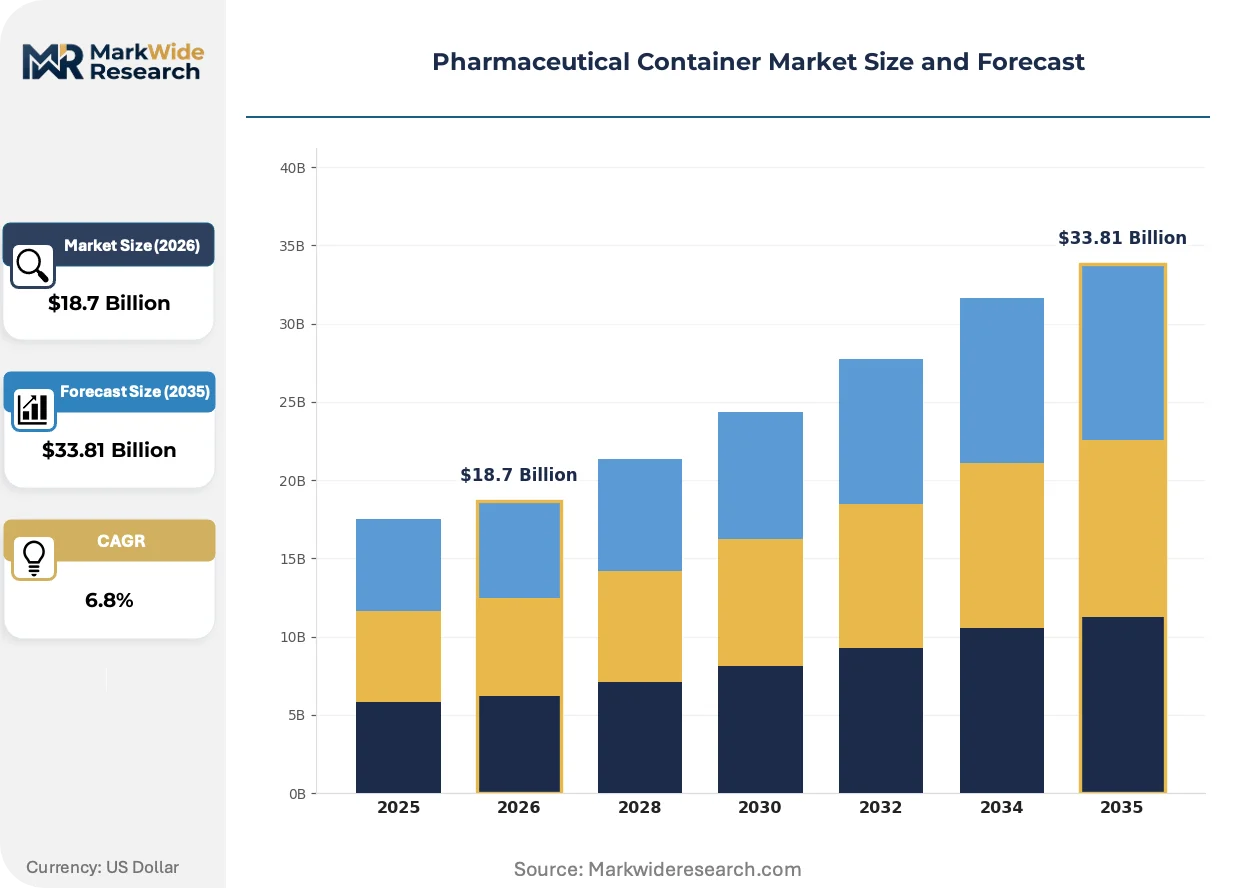
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Bottles, Syringes Material: Glass, Plastic, Aluminum, Composite End User: Pharmacies, Hospitals, Clinics, Research Laboratories Packaging Type: Primary, Secondary, Tertiary, Eco-Friendly |
| Companies Covered | Amcor Plc, Gerresheimer AG, Schott AG, Berry Global Group Inc., West Pharmaceutical Services Inc., Ardagh Group S.A., Becton Dickinson and Company, AptarGroup, Inc., Piramal Glass Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Container Market Evolving Landscape
Container engineering is pivoting from passive protection to active functional integration. Suppliers now embed sensing, dosing, and connectivity directly into primary enclosures, transforming packaging from cost center to data-generating clinical asset.
Cyclic olefin polymer is rewriting material selection criteria for biologic storage. The resin delivers glass-like barrier performance with polymer processability, enabling blow-fill-seal integration at line speeds exceeding four hundred units per minute. Biologic drug sponsors in oncology and autoimmune segments are adopting COP vials for protein formulations previously restricted to borosilicate glass.
FDA container closure guidance revisions are elevating documentation burdens for all parenteral applications. The updated chemistry and toxicology recommendations now mandate extractables screening across accelerated aging protocols. Suppliers serving the US market are expanding analytical laboratories to maintain submission readiness.
Self-administration trends are reshaping container form factors and user-interface design. Prefilled pens and autoinjectors are displacing traditional vial-and-syringe formats in chronic disease management. Rheumatology and endocrinology practices in North American and Western European markets are driving preference for single-use delivery systems that reduce clinic visits.
Pharmaceutical Container Market Segmentation
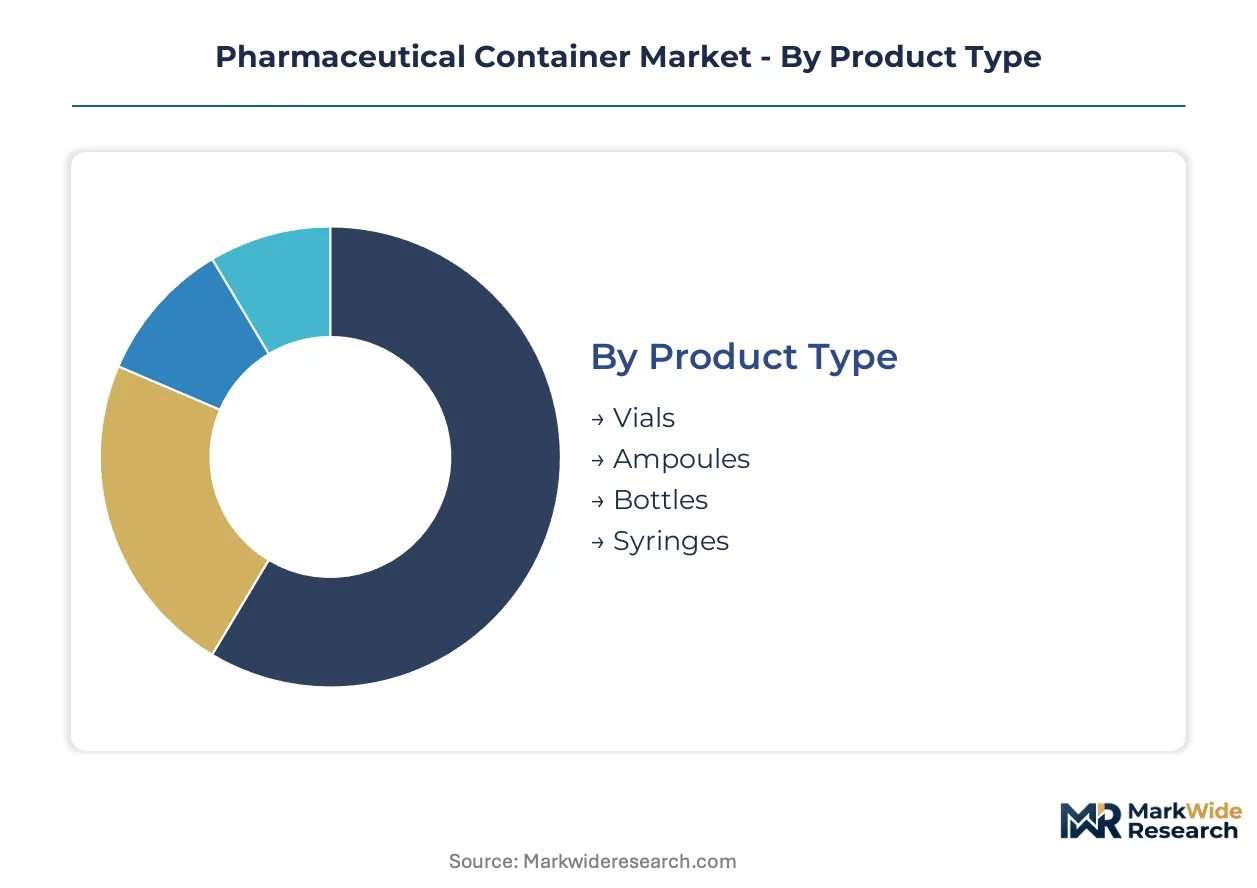
Pharmaceutical container selection hinges on drug stability requirements, administration routes, and regulatory compliance tiers. Segmentation reveals how material science and packaging hierarchy create divergent margin pools across the value chain.
Product Type:
End-user administration convenience drives purchasing decisions across injectable and oral formats.
- Vials:Borosilicate glass enclosures dominate parenteral biologics storage with validated extractables profiles under USP <660>. mRNA cold-chain applications in Germany and Massachusetts concentrate demand for tubular glass with dimensional tolerances below 0.1 millimeters.
- Syringes:Prefillable glass syringes integrate staked needles and lubricated barrels for single-use administration. Rheumatology and endocrinology practices in North American markets are displacing traditional vial-and-syringe formats with autoinjector-compatible designs.
- Ampoules:Single-dose glass containers seal via tip-flame fusion for emergency and anesthetic applications requiring absolute tamper evidence.
- Bottles:Wide-mouth and narrow-neck designs serve oral solid dispensing with child-resistant, senior-friendly closure systems.
Vials lead on scale; syringes lead on momentum.
Material:
Barrier performance specifications stratify procurement budgets across glass, polymer, and metal substrates.
- Glass:Type I borosilicate delivers hydrolytic resistance below 0.7 ml for parenteral applications. High-purity silica feedstock extraction limits in select mining jurisdictions create input cost volatility for European and North American manufacturers.
- Plastic:Cyclic olefin polymer achieves glass-like barrier performance with blow-fill-seal processability exceeding four hundred units per minute. Oncology and autoimmune biologic sponsors are adopting COP vials for protein formulations previously restricted to borosilicate.
- Aluminum:Collapsible tubes and aerosol cans protect topical and inhalation formulations from light and oxygen ingress.
- Composite:Multi-layer co-extruded structures combine polymer processability with metal-foil barrier performance for moisture-sensitive APIs.
Glass commands the deepest margin pool; plastic is expanding most quickly.
End User:
Regulatory sophistication and volume scale differentiate procurement patterns across the care continuum.
- Pharmacies:Retail and hospital outpatient dispensaries drive demand for unit-dose compliance packaging with senior-friendly opening features. German pharmacy chains are localizing sourcing through Mainz-based glass production clusters.
- Hospitals:Inpatient facilities prioritize bulk sterile containers with validated sterilization-in-place protocols for parenteral compounding.
- Clinics:Ambulatory settings favor prefilled delivery systems reducing medication preparation time and dosing error risk.
- Research Laboratories:Clinical trial supply demands small-batch flexibility with comprehensive extractables documentation for IND submissions.
Hospitals lead on volume concentration; research laboratories lead on specification intensity.
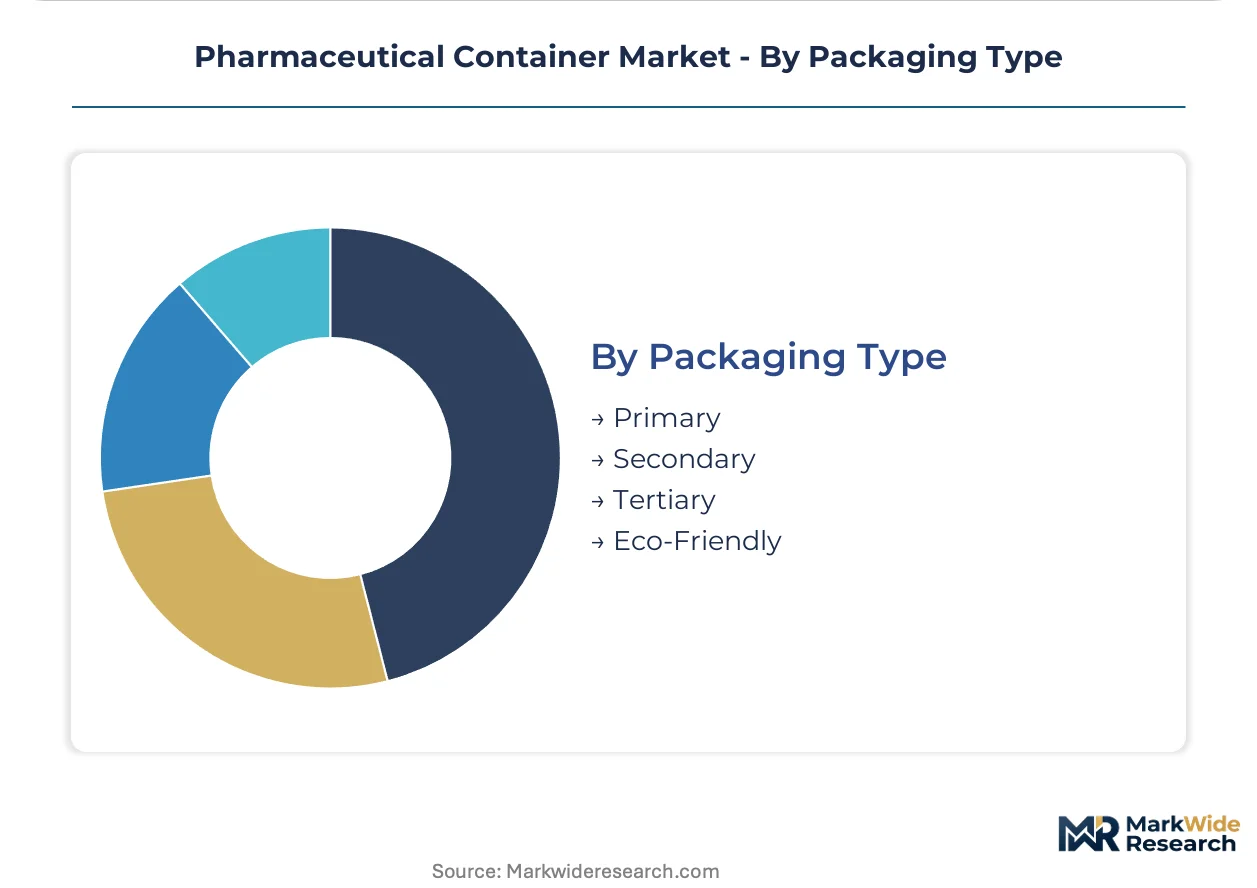
Packaging Type:
Proximity to drug product determines qualification burden and switching cost magnitude.
- Primary:Direct-contact containers face three-to-five-year qualification cycles with drug sponsors, creating locked sourcing relationships. FDA container closure guidance and EMA nitrosamine assessments elevate chemistry and toxicology documentation burdens.
- Secondary:Cartons and labels provide tamper evidence and regulatory information display with faster procurement cycles.
- Tertiary:Shipping cases and pallets protect cold-chain integrity through distribution, integrating temperature loggers for mRNA vaccine transport.
- Eco-Friendly:Bio-based polymers and recyclable glass formats respond to EU Green Deal packaging waste directives and corporate sustainability commitments.
Primary packaging leads on margin depth; eco-friendly formats lead on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glassblowers and polymer chemists cluster around Mainz and Mitterteich in Germany, anchoring European pharmaceutical container production. This workforce concentration shapes supply security for parenteral applications across the continent.
United States
mRNA vaccine cold-chain requirements drive demand for tubular glass vials with dimensional tolerances below 0.1 millimeters. FDA container closure guidance revisions mandate extractables screening across accelerated aging protocols. Massachusetts biomanufacturing corridors concentrate fill-finish operations requiring validated container-closure systems.
Germany
Gerresheimer AG and Schott AG anchor specialized borosilicate glass production for prefillable syringes and vials. EMA nitrosamine risk assessments force reformulation of rubber stoppers and plungers across the installed base. Mainz and Mitterteich production clusters supply European parenteral markets with captive mold technology.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad localize container sourcing for export markets. CDSCO alignment with USP chapters streamlines qualification pathways for US-bound drug products. Piramal Glass operations in Gujarat supply Type I borosilicate vials to domestic biologics manufacturers.
China
NMPA implementation of ICH Q3D elemental impurity guidelines elevates documentation burdens for imported container materials. Yangtze River Delta pharmaceutical manufacturing hubs demand cyclic olefin polymer vials for protein formulations. Domestic glass producers expand borosilicate capacity to reduce dependence on European imports.
Switzerland
Swissmedic oversight of device-like drug delivery systems creates premium positioning for validated container-closure combinations. Basel-based biologics manufacturers specify glass-like barrier performance with polymer processability for oncology formulations. Precision molding specialists serve Roche and Novartis with dimensional tolerances exceeding pharmacopeial standards.
Pharmaceutical Container Market Competitive Landscape
Top-tier vendors anchor premium glass and polymer segments, while mid-cap specialists occupy niche barrier technology positions. The vendor base stratifies across three tiers: integrated multinationals with captive mold capabilities, regional glass specialists with pharmacopeial certifications, and polymer converters with blow-fill-seal integration. Two strategic archetypes dominate: German glasshouses leveraging generational molding expertise, and North American packaging conglomerates diversifying through multi-layer co-extrusion. Competitive moves concentrate on backward integration into high-purity silica feedstock and technology licensing for extractables testing protocols.
Within the European glass specialist tier, Gerresheimer AG and Schott AG exemplify captive production models. Gerresheimer AG represents the prefillable syringe archetype through mold technology ownership. Schott AG occupies a position in tubular glass vial supply for mRNA applications. Among diversified packaging conglomerates, Berry Global Group Inc. exemplifies multi-layer barrier expansion into moisture-sensitive oral solid segments.
| Leading Market Players |
|---|
| Amcor Plc |
| Gerresheimer AG |
| Schott AG |
| Berry Global Group Inc. |
| West Pharmaceutical Services Inc. |
| Ardagh Group S.A. |
| Becton Dickinson and Company |
| AptarGroup, Inc. |
| Piramal Glass Private Limited |
| Others |
Value Network & Pricing Analysis
High-purity silica feedstock indices cascade through Type I borosilicate glass production into three distinct pricing tiers: validated extractables-profile containers for mRNA biologics, standard USP <660> compliant vials for generic parenterals, and commodity resin bottles for oral solids. German production clusters around Mainz and Mitterteich concentrate supply-side leverage, compressing margins for mid-tier converters while premium glasshouses capture qualification-premium pricing.
Pricing Analysis
Unbundled extractables testing and validation services separate from base container pricing, creating hybrid contract structures where drug sponsors pay separately for USP <1664> compliant study protocols. Price differentiation hinges on pharmacopeial certification grade and captive mold technology ownership, with German glasshouses commanding premiums against Asian competitors. Cost compression in standard-grade oral solid containers intensifies as multi-layer co-extruded polymers achieve glass-like barrier performance. Generic drug manufacturers exhibit highest price sensitivity; biologic sponsors prioritize technical performance over unit cost.
Supply Chain Analysis
Reverse logistics for temperature-excursion mRNA vaccines drives specialized cold-chain return flows, with tertiary packaging integrating data loggers that feed back into supplier quality systems. Manufacturing concentrates in Germany, China, and India, with each geography serving distinct regulatory export markets. The chain rests on high-purity silica sand, cyclic olefin polymer resin, and elastomeric closure formulations as critical inputs. Single-source vulnerability concentrates in German tubular glass vial production for cold-chain applications. Distribution runs through drug sponsor fill-finish facilities and contract manufacturing organizations rather than wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA nitrosamine compliance costs in Europe exceed CDSCO-aligned qualification expenses in India, creating margin expansion opportunities for suppliers with dual-hemisphere certification capabilities.
For Market Incumbents: Hedge against cyclic olefin polymer substitution by deepening captive mold capabilities in prefillable syringe formats where dimensional tolerances below 0.1 millimeters create technical moats. Acquire extractables testing laboratories to internalize USP <1664> protocol revenue streams and defend against analytical toxicologist scarcity. Prioritize backward integration into high-purity silica feedstock to buffer borosilicate sand extraction limits. For New Entrants and Emerging Players: Contract development and manufacturing organizations in Hyderabad and Ahmedabad represent the most penetrable channel partner type for localized container sourcing. Target mid-tier biologics manufacturers seeking alternatives to German glasshouse pricing premiums. Pursue blow-fill-seal integration partnerships with oncology-focused drug sponsors adopting COP vials for protein formulations previously restricted to borosilicate glass. For Investors and Strategic Acquirers: Asymmetric upside sits with regional glass specialists possessing pharmacopeial certifications but lacking extractables testing infrastructure. Long-term viability centers on suppliers with demonstrated qualification cycle completion alongside drug sponsors. Monitor FDA container closure guidance revision timing as inflection indicator for documentation burden expansion and laboratory capacity investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Extractables Testing Laboratory Acquisition | Internalizes USP <1664> protocol revenue and reduces toxicologist hiring premiums. |
| Captive Mold Technology Expansion | Gerresheimer AG demonstrates how mold ownership tightens dimensional tolerances below 0.1 millimeters. |
| Dual-Certification Manufacturing Footprint | CDSCO and FDA alignment streamlines qualification pathways for US-bound Indian drug products. |
| Cyclic Olefin Polymer Blow-Fill-Seal Integration | Oncology biologic sponsors adopt COP vials for protein formulations at line speeds exceeding four hundred units per minute. |
| Connected Packaging Sensor Embedding | Near-field communication tags converge with primary containers for mRNA cold-chain verification. |
Research Methodology
Bottom-up biologic drug sponsor modeling reconciled against top-down glass and polymer production tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, fill-finish operations directors, extractables testing laboratory managers, and hospital procurement specialists combined with secondary validation from FDA container closure guidance documents, EMA nitrosamine assessment reports, USP pharmacopeial chapters, and CDSCO regulatory alignment circulars. Triangulation between demand-side qualification cycle data and supply-side capacity announcements ensures cross-verified volume and value estimates.
Historical trendline analysis across material substitution patterns and qualification timeline compression shaped the projection framework. Segmentation dimensions modeled include administration route, material substrate, packaging hierarchy tier, and regional regulatory cluster. CAGRs were derived from regression analysis of sponsor procurement cycles and supplier capacity expansion announcements. Industry-specific forecast inputs incorporated EMA nitrosamine risk assessment implementation pace and FDA guidance revision timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial harmonization between USP, EP, and JP chapters and borosilicate sand extraction limit enforcement. Practitioners should monitor FDA container closure guidance revision schedules and EMA nitrosamine assessment expansion scope for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market