
 Pet Food Packaging Market | 2026-2036
Pet Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Packaging Market Intelligence
The EU Green Deal is hardening material compliance requirements for pet food packaging across European supply chains. Amcor Plc leverages its global film manufacturing network to supply high-barrier laminates for wet food applications. Berry Global Group anchors North American production with extensive blow-molding capacity for rigid containers. Mondi Plc differentiates through kraft-paper-based flexible solutions that target fiber-reduction mandates.
Pet food packaging encompasses primary and secondary containment systems engineered to preserve nutritional integrity, prevent oxidation, and withstand distribution stress. Multi-layer coextruded films with ethylene vinyl alcohol barriers achieve oxygen transmission rates below 0.5 cc/m²/day, critical for shelf-stable wet formulations. Pouches capture the fastest-growing share of packaging type demand as brands convert from metal cans to lightweight flexible formats. Plastic sustains dominance across material categories, though paperboard segments are gaining traction in dry food cartons where moisture sensitivity permits fiber substitution.
FDA food contact regulations in the United States, EU REACH chemical restrictions, and EFSA migration limits collectively define permissible substances and testing protocols for packaging substrates. Compliance with these frameworks determines market access, with non-compliant materials facing border detention or reformulation costs. Stakeholders must monitor evolving extended producer responsibility schemes and state-level recycling mandates that will reshape material selection and end-of-life economics.
Market Dynamics
Pet food packaging is restructuring around e-commerce fulfillment requirements as direct-to-consumer subscription models force shorter production runs and smaller pack sizes. The shift compresses traditional economies of scale in converter operations.
Growth Catalysts
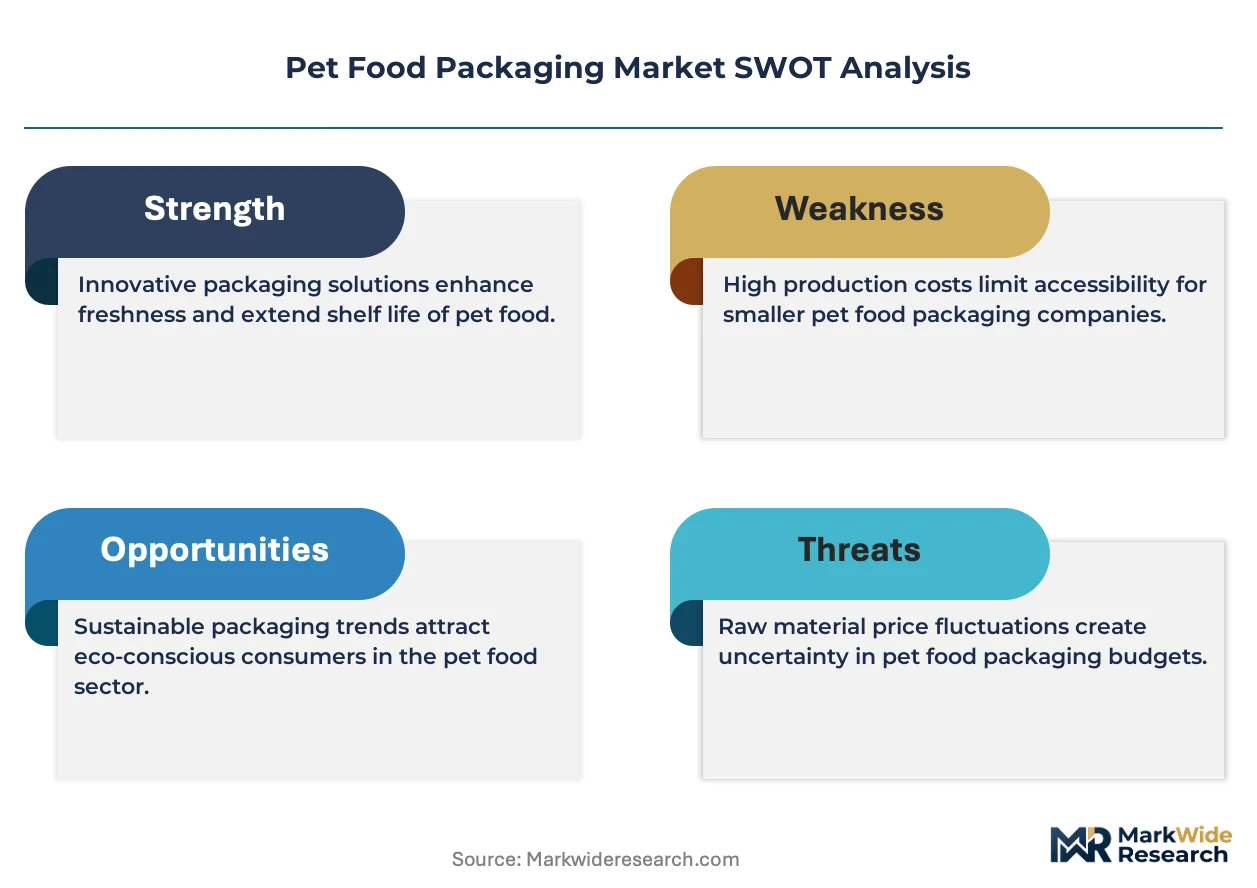
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants accelerates conversion to mechanical foaming and nitrogen dosing systems in barrier foam trays.
- Wet food premiumization:High-moisture formulations require oxygen transmission rates below 0.5 cc/m²/day, pulling demand for ethylene vinyl alcohol laminates and metallized films.
- United States pet humanization:Human-grade ingredient claims necessitate retort-compatible pouches with food-contact compliance stricter than traditional pet food standards.
Market Restraints
- Resin supply concentration:Ethylene vinyl alcohol production clusters in Japan and Belgium expose converters to logistics disruptions and currency volatility.
- Multi-layer incompatibility:Current mechanical recycling infrastructure cannot separate polyamide-ethylene vinyl alcohol-polyethylene laminates, limiting post-consumer feedstock availability.
- Aluminum foil substitution limits:Metallized polyethylene terephthalate achieves only 60-70% of aluminum's barrier performance, forcing thicker films and higher material costs.
Strategic Opportunities
- Monomaterial flexible packaging:Single-polymer polyethylene pouches with plasma-enhanced barrier coatings unlock Design for Recycling certification and extended producer responsibility credits.
- Veterinary prescription channels:Therapeutic diets for renal and diabetic conditions require child-resistant, senior-friendly closure systems with tamper-evident features.
- California SB 54 mandates:State-level recycled content requirements and producer responsibility frameworks create first-mover advantages for compliant packaging formats.
Industry Challenges
- Migration testing capacity:EU REACH and FDA food contact notification backlogs extend new material qualification timelines to 18-24 months.
- Retort pouch conversion:Legacy canning lines require capital-intensive retrofits for horizontal form-fill-seal pouch equipment, straining mid-tier brand budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Packaging Market |
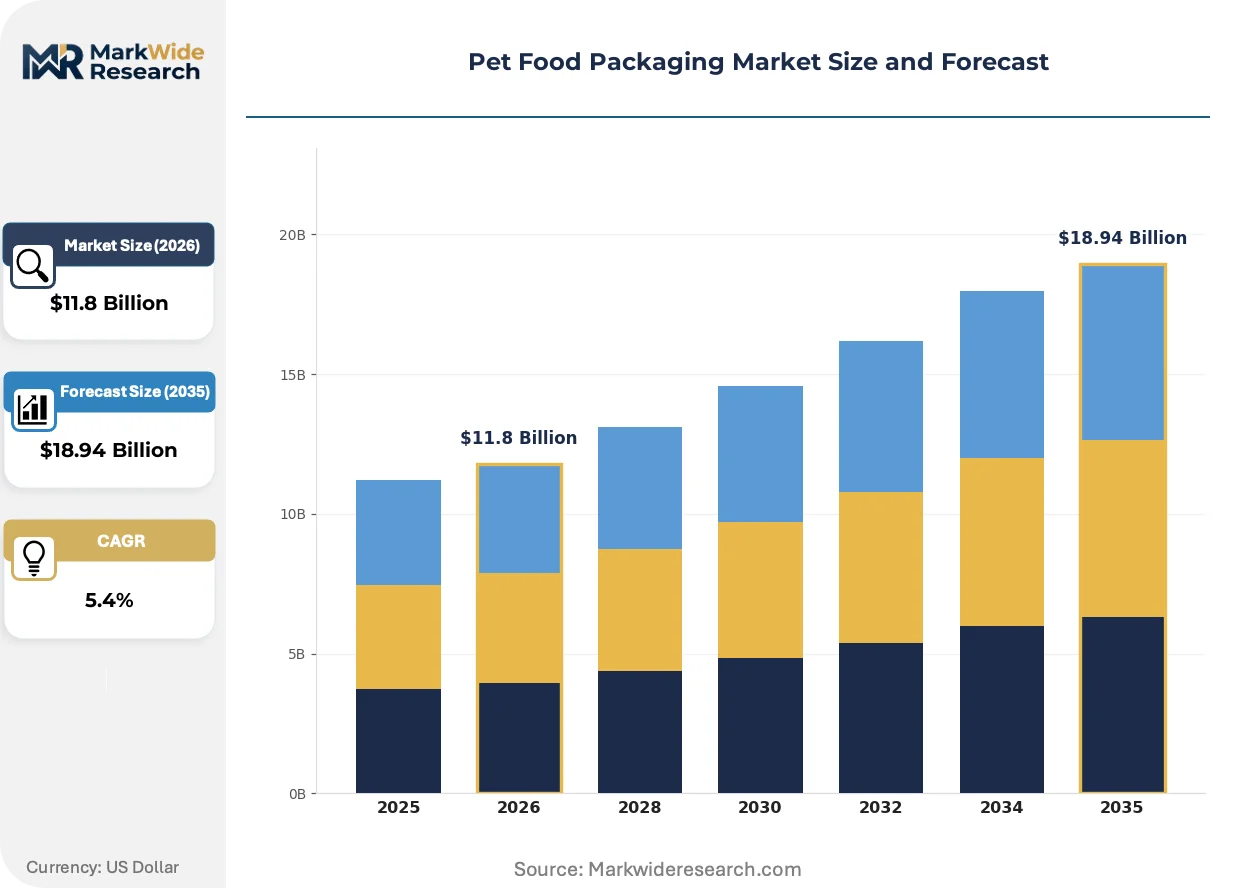
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Cans, Pouches, Boxes Material: Plastic, Metal, Paperboard, Glass Closure Type: Seal, Screw Cap, Zipper, Easy Open End User: Retail, Online Sales, Wholesale, Distributors |
| Companies Covered | Berry Global Group, Crown Holdings, Amcor Plc, ProAmpac LLC, Sonoco Products Company, Mondi Plc, Ardagh Group, Constantia Flexibles, Huhtamäki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging functionalities are migrating from human food into pet applications as brands seek differentiation in subscription channels. These technologies address shelf-life anxiety and supply chain transparency simultaneously.
High-barrier transparent films are integrating silicon oxide and aluminum oxide coatings through plasma-enhanced chemical vapor deposition. Premium wet food brands in Germany and the United Kingdom adopt these materials to showcase product texture while maintaining 12-month shelf stability. The technology is integrating quality perception directly into packaging aesthetics, collapsing the trade-off between visibility and preservation.
The EU Green Deal's Packaging and Packaging Waste Regulation tightens recyclability definitions and mandates extended producer responsibility fees based on material complexity. Converters face reformulation deadlines for non-recyclable multi-layer structures by 2030. Flexible packaging segments in France and Italy accelerate pilot programs for paper-based barriers with heat-sealable coatings to preempt compliance costs.
Direct-to-consumer brands compress traditional wholesale-distributor-retail chains, eliminating pallet-scale packaging requirements. Smaller batch sizes and variable data printing for subscription personalization strain conventional rotogravure economics. Digital printing adoption concentrates in the United States Pacific Northwest and Netherlands logistics hubs where e-commerce penetration in pet supplies exceeds general retail averages.
Pet Food Packaging Market Segmentation
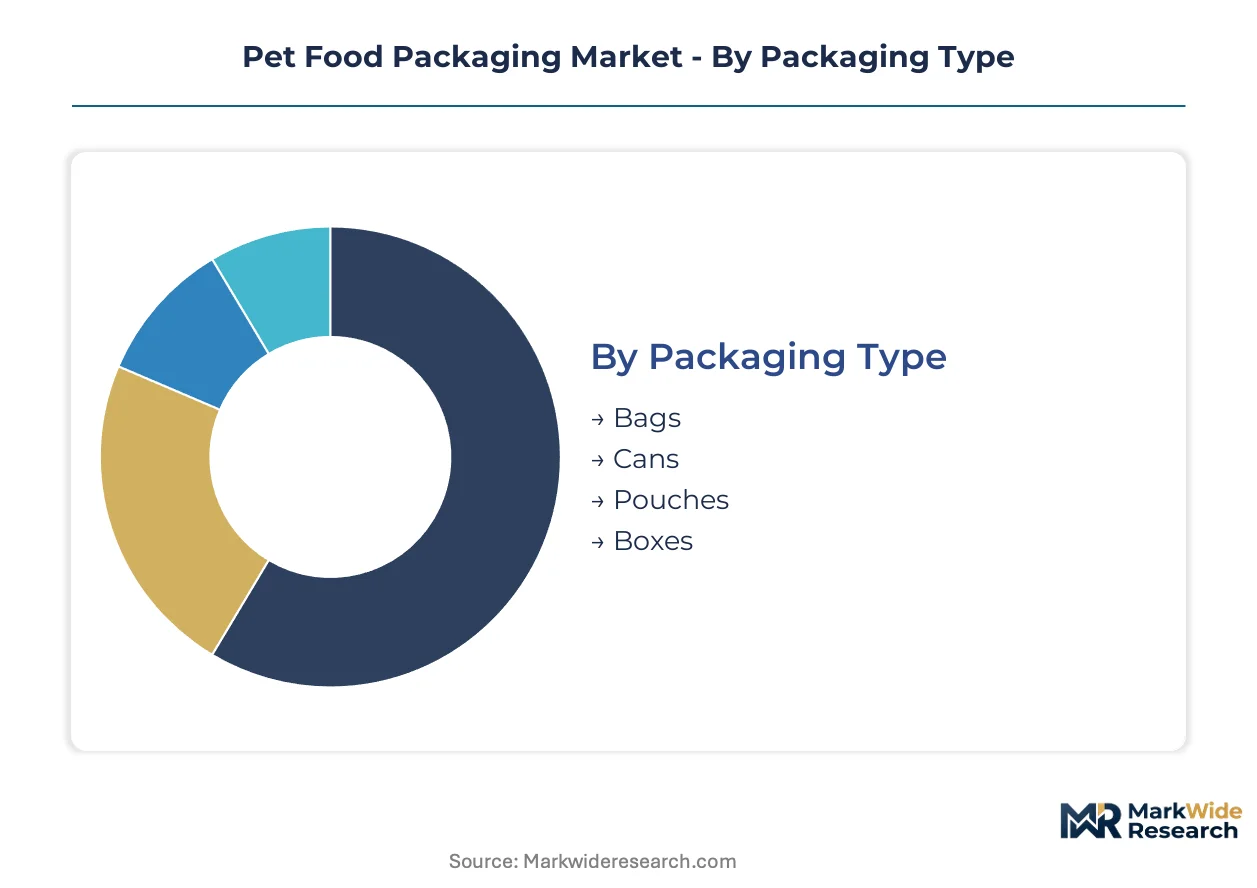
Segmentation in pet food packaging reveals how format choices cascade through supply chain economics and regulatory exposure. Material selection and closure complexity determine which converters capture volume versus margin.
Packaging Type:
Standalone formats dominate shelf-stable applications while embedded systems integrate into automated feeding hardware.
- Pouches:Multi-layer laminates with ethylene vinyl alcohol barriers achieve oxygen transmission below 0.5 cc/m²/day for wet food preservation. Premium brands in Germany and the United Kingdom convert from metal cans to reduce shipping weight and enable product visibility through transparent windows.
- Cans:Three-piece steel or aluminum construction with double-seamed ends provides hermetic sealing for retort sterilization. Legacy infrastructure in the United States Midwest maintains volume concentration despite capital-intensive line retrofits for pouch conversion.
- Bags:Gusseted polyethylene or woven polypropylene formats with linear low-density seal layers serve dry food bulk distribution.
- Boxes:Folding carton and corrugated formats function as secondary containment for multi-unit retail presentation.
Volume placements concentrate in Cans; the faster expansion belongs to Pouches.
Material:
Cost tier separation tracks barrier performance requirements and end-of-life compliance burdens across regulatory jurisdictions.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate substrates dominate flexible formats through coextrusion and metallization capabilities. California SB 54 mandates and EU Green Deal recyclability definitions are forcing reformulation toward monomaterial structures by 2030.
- Paperboard:Kraft-based cartons with heat-sealable barrier coatings target fiber-reduction mandates in France and Italy pilot programs. Dry food applications where moisture sensitivity permits substitution are gaining share fastest.
- Metal:Tinplate and aluminum substrates retain dominance in retort applications requiring thermal processing compatibility.
- Glass:Borosilicate and soda-lime formats serve niche premium positioning with reusable closure systems.
Plastic commands absolute volume; paperboard climbs the fastest under regulatory pressure.
Closure Type:
Application context dictates resealability requirements versus tamper evidence and child resistance priorities.
- Zipper:Press-to-close interlocking profiles in polyethylene or polypropylene enable multi-serve convenience for large-format dry food bags. Direct-to-consumer subscription brands specify zippers for pantry storage after delivery.
- Screw Cap:Injection-molded polypropylene or polyethylene terephthalate closures with induction seals provide hermetic resealability for wet food tubs. Veterinary prescription channels require child-resistant senior-friendly variants for therapeutic diets.
- Seal:Heat-sealed peelable films offer lowest unit cost for single-serve portions.
- Easy Open:Laser-scored or tear-notch features reduce consumer effort without reseal functionality.
Seal formats anchor commodity volume; screw cap systems expand fastest in prescription and premium segments.
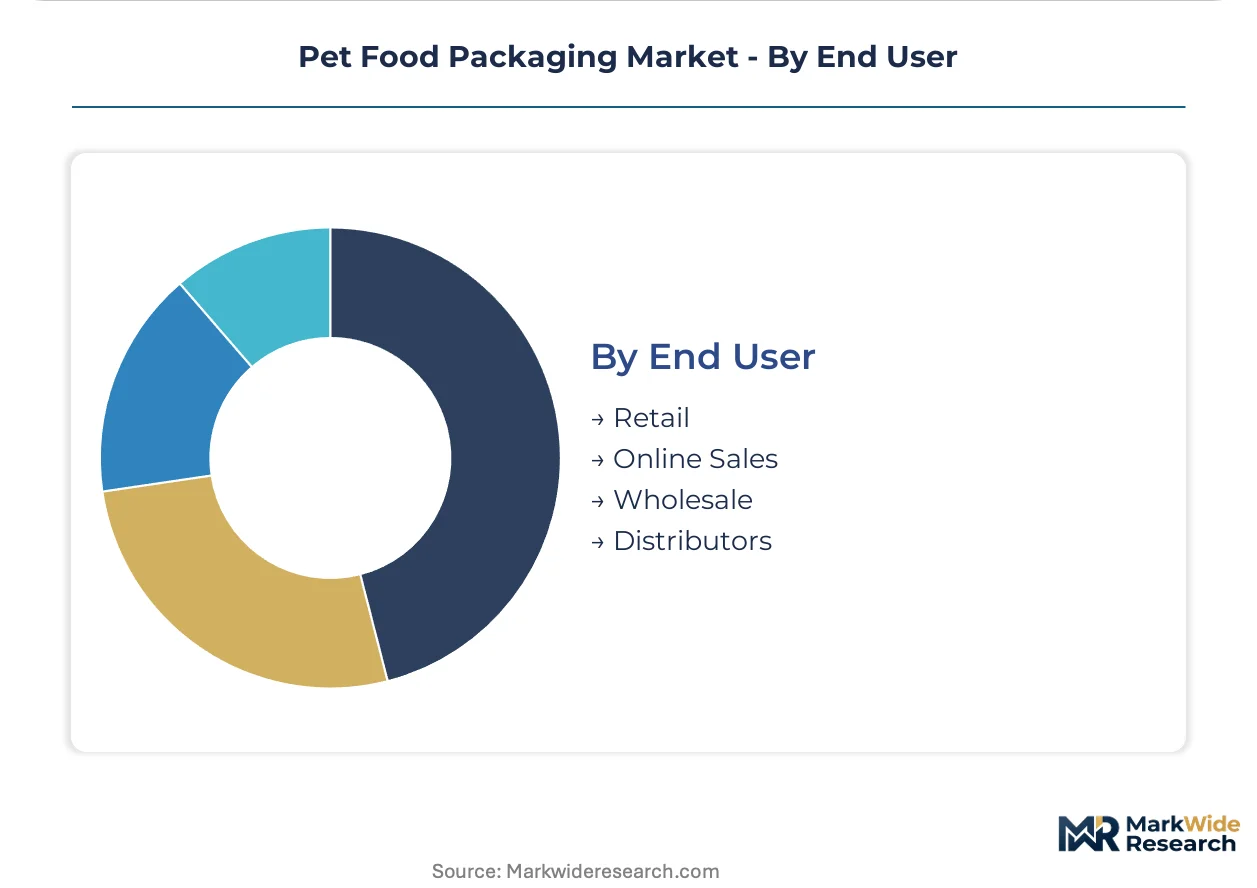
End User:
Customer type determines batch size economics, personalization requirements, and palletization specifications.
- Online Sales:Direct-to-consumer subscription models force shorter production runs and variable data printing for personalization. Logistics hubs in the United States Pacific Northwest and Netherlands concentrate digital printing adoption where e-commerce penetration exceeds general retail.
- Retail:Mass merchandisers and specialty pet chains demand pallet-scale packaging with shelf-ready secondary containment. United States big-box specifications drive standardization in case counts and display dimensions.
- Wholesale:Club store formats require bulk sizing and multi-pack configurations.
- Distributors:Foodservice and veterinary clinic channels need intermediate batch flexibility.
Retail maintains volume dominance; online sales gain share fastest as subscription models disintermediate traditional wholesale-distributor chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Belgium and Japan for ethylene vinyl alcohol resins while consumption concentrates in the United States and Germany where premium wet food brands drive format conversion. This geographic mismatch shapes logistics costs and currency exposure for converters.
United States
Pet humanization trends and direct-to-consumer subscription models reshape packaging specifications for e-commerce channels. FDA food contact regulations enforce stricter compliance than traditional pet food standards. The Pacific Northwest logistics hub concentrates digital printing adoption where e-commerce penetration in pet supplies exceeds general retail averages.
Germany
Premium wet food brands convert from metal cans to lightweight flexible formats with transparent windows. The EU Green Deal and F-Gas Regulation tighten material compliance requirements across supply chains. The Düsseldorf-Cologne industrial corridor hosts pilot programs for paper-based barriers with heat-sealable coatings.
United Kingdom
High-barrier transparent films with silicon oxide coatings gain adoption among premium wet food brands seeking 12-month shelf stability. EFSA migration limits define permissible substances and testing protocols for packaging substrates. The Midlands packaging belt concentrates flexible converter operations serving subscription brands.
Japan
Ethylene vinyl alcohol production clusters expose converters to logistics disruptions and currency volatility. METI standards govern food-contact material safety in barrier laminate applications. The Osaka-Kobe industrial zone maintains resin manufacturing capacity critical for oxygen transmission rate specifications.
Netherlands
E-commerce fulfillment requirements force shorter production runs and smaller pack sizes for direct-to-consumer brands. EU REACH chemical restrictions determine market access for imported substrates. The Rotterdam logistics hub serves as a distribution nexus for European pet food packaging supply chains.
Pet Food Packaging Market Key Industry Players
The competitive structure tilts toward diversified packaging conglomerates with integrated film manufacturing and rigid container capabilities. Three archetypes dominate: global film specialists with barrier laminate expertise, blow-molding leaders anchoring North American rigid production, and fiber-based innovators targeting recyclability mandates. M&A activity concentrates on digital printing assets for e-commerce personalization, while capacity expansion focuses on monomaterial flexible lines for Design for Recycling certification.
Among diversified packaging conglomerates, Berry Global Group, Amcor Plc, and Mondi Plc occupy distinct strategic positions. Berry Global Group exemplifies the rigid container archetype through blow-molding capacity concentration. Amcor Plc represents the global film specialist model with high-barrier laminate supply networks. Mondi Plc anchors the fiber-based innovation vector targeting kraft-paper solutions for regulatory compliance.
| Leading Market Players |
|---|
| Berry Global Group |
| Crown Holdings |
| Amcor Plc |
| ProAmpac LLC |
| Sonoco Products Company |
| Mondi Plc |
| Ardagh Group |
| Constantia Flexibles |
| Huhtamäki Oyj |
| Others |
Cost & Logistics Intelligence
Ethylene vinyl alcohol resin pricing indices cascade through converter operations into three-tier pricing structures across premium, standard, and economy levels. Wet food barrier laminates command premiums tied to oxygen transmission specifications below 0.5 cc/m²/day, while dry food polyethylene formats compete on volume scale.
Pricing Analysis
Oxygen transmission rate performance anchors value-based pricing tiers in wet food applications. Premium pouches with ethylene vinyl alcohol barriers separate from metallized polyethylene terephthalate mid-tier formats and uncoated polyethylene economy grades. Cost compression in standard tiers intensifies because resin supply clusters in Japan and Belgium expose converters to currency volatility. Mass-market dry food brands exhibit highest price sensitivity; prescription veterinary channels show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements for ethylene vinyl alcohol resins force converters to qualify suppliers in both Japan and Belgium. Raw material dependencies center on ethylene vinyl alcohol, polyamide, and metallized polyethylene terephthalate films. Single-source vulnerability concentrates around Osaka-Kobe resin manufacturing capacity critical for barrier specifications. Distribution runs through Rotterdam and Pacific Northwest logistics hubs serving direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive film manufacturing determines margin capture. Players are pursuing upstream control over ethylene vinyl alcohol laminate production to secure barrier specifications and volume commitments.
For Market Incumbents: Hedge resin supply exposure by securing long-term offtake agreements with Osaka-Kobe and Belgian manufacturers. Diversify format portfolios into monomaterial polyethylene structures to preempt EU Green Deal recyclability mandates and capture extended producer responsibility credits. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable entry vector for mid-tier brands. Target wet food pouch conversion demand from legacy canning operations in the United States Midwest and German industrial corridors. Lead with digital printing capabilities for variable data personalization at Rotterdam and Pacific Northwest logistics hubs. For Investors and Strategic Acquirers: Distressed-cycle entries favor monomaterial flexible packaging specialists with California SB 54 compliance certification. Long-term viability over the next decade hinges on Design for Recycling accreditation and plasma-enhanced barrier coating intellectual property. Watch for EU Packaging and Packaging Waste Regulation enforcement dates as inflection triggers for converter consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Line Conversion | Design for Recycling certification unlocks extended producer responsibility credits under EU Green Deal frameworks. |
| Digital Printing Acquisition | Variable data capabilities capture direct-to-consumer subscription personalization demand in Netherlands and Pacific Northwest hubs. |
| Barrier Coating R&D Partnership | Plasma-enhanced silicon oxide technology collapses the visibility-preservation trade-off for premium wet food brands. |
| Resin Supply Integration | Captive ethylene vinyl alcohol laminate production hedges currency volatility from Japanese and Belgian supply clusters. |
| Prescription Channel Certification | Child-resistant closure systems for veterinary therapeutic diets command margin premiums in renal and diabetic formulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with flexible packaging converters, pet food brand procurement directors, and veterinary distribution channel managers combined with FDA food contact notifications, EU REACH substance registrations, and EFSA migration limit databases. Bottom-up volume modeling triangulated against top-down value estimates from resin production and converter capacity disclosures.
Data-stream reconciliation across supply-side capacity and demand-side format conversion trends shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, closure complexity, and end-user channel with regulatory jurisdiction overlays. CAGRs derived from elasticity-adjusted volume projections incorporating wet food premiumization rates and e-commerce penetration differentials.
The model holds under stable resin supply and regulatory phase-in schedules; deviation in EU Packaging and Packaging Waste Regulation enforcement timing or ethylene vinyl alcohol production disruptions would shift trajectory. A model refresh is warranted upon material change in California SB 54 implementation guidance or FDA food contact notification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Food Punnets Market
Food Packaging
Foam Food Container Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Sugar Packaging Market