
 Sugar Packaging Market | 2026-2036
Sugar Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Packaging Market Analytics
Aftermarket technical service revenue is reconfiguring how packaging converters capture lifetime value from installed filling equipment bases. Mondi Group leverages its European kraft paper network to anchor flexible bag supply for industrial sugar buyers. Amcor plc sustains global R&D intensity in high-barrier laminates that extend shelf stability in tropical climates. Smurfit Westrock competes through integrated containerboard-to-box operations that control cost positions across rigid formats.
Sugar packaging encompasses primary and secondary enclosures engineered to protect crystalline or liquid sucrose from moisture ingress, physical damage, and contamination during storage, transport, and retail display. Specifications typically target moisture vapor transmission rates below specified thresholds and seal integrity under compression loads common in palletized distribution. Flexible bags lead volume share in bulk industrial channels where 25-50 kg formats dominate procurement patterns. Paper-based materials are displacing conventional plastic in European retail sachets as brand owners navigate EFSA-aligned sustainability commitments. Rigid containers concentrate margin pools in premium confectionery segments where reclosability and shelf aesthetics command price premiums.
FDA food contact substance notifications govern barrier coating chemistries in US-bound sugar packaging, while EU REACH restricts certain phthalate plasticizers in flexible films serving European retail channels. India's BIS certification mandates migration testing for plastic containers holding edible commodities, shaping import qualification timelines for foreign suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which material platforms retain channel access across major consuming markets.
Market Dynamics
EU F-Gas Regulation and REACH compliance are compressing converter margins while accelerating material platform transitions toward bio-based barrier films across European sugar packaging supply chains.
Growth Catalysts
- Bakery sector portion-control demand:Industrial bakeries in India and Brazil are scaling procurement of single-serve sugar sachets to reduce waste and standardize recipes, pulling film laminates into high-throughput filling lines.
- BIS certification expansion:India's mandatory migration testing for edible commodity containers is qualifying domestic converters for import substitution contracts with multinational food processors.
- Tropical barrier R&D:High-humidity storage conditions in Southeast Asian distribution corridors are forcing adoption of metallized and oxide-coated films that extend shelf stability beyond conventional polyethylene specifications.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices swing with naphtha-cracker economics, compressing flexible bag converters' margin predictability on annual procurement contracts.
- Aluminum foil supply concentration:Metallized barrier film production depends on rolling capacity concentrated in Chinese and Russian primary aluminum smelters, exposing converters to geopolitical supply disruptions.
- Recyclability technical ceiling:Multi-layer laminates combining PET, aluminum, and polyethylene defy mechanical recycling streams, creating stranded asset risk as extended producer responsibility schemes advance in Germany and France.
Strategic Opportunities
- Sub-Saharan African underpenetration:Packaged sugar consumption per capita in Nigeria and Kenya remains below Southeast Asian benchmarks, creating first-mover advantage for converters establishing localized pouch printing and filling partnerships.
- Cellulose nanofiber convergence:Integration of wood-derived nanocellulose with existing kraft paper infrastructure is enabling oxygen barriers competitive with plastic laminates without fossil-derived coatings.
- EU Green Deal procurement mandates:Public sector food service tenders across Netherlands and Denmark now require bio-based or recyclable packaging, redirecting volume toward certified paper-based sachet suppliers.
Industry Challenges
- Migration testing capacity bottleneck:BIS-certified laboratories in India face six-month queues for plastic container qualification, delaying foreign supplier market entry and domestic line expansions.
- Legacy filling equipment incompatibility:Paper-based sachet materials exhibit different heat-seal profiles and tensile elongation than incumbent plastic films, requiring line retrofit investments that mid-size converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Packaging Market |
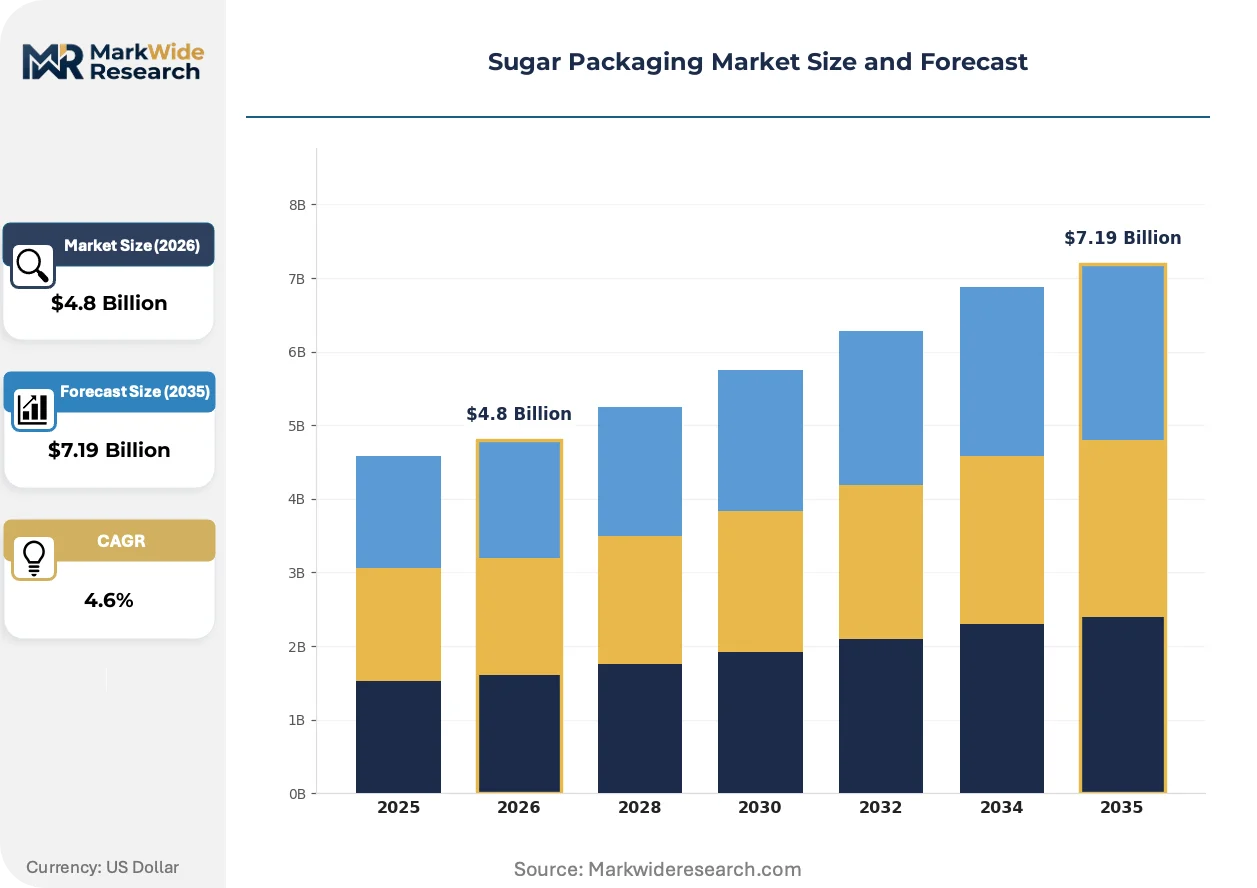
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Bags, Rigid Containers, Sachets, Boxes Material: Plastic, Paper, Metal, Glass End User: Beverage Industry, Confectionery, Bakery, Food Processing Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Mondi Group, Amcor plc, Smurfit Westrock, Sealed Air Corporation, International Paper Company, WestRock Company, Huhtamaki Oyj, Sonoco Products Company, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Packaging Market Evolving Landscape
Active and intelligent packaging systems are migrating from pharmaceutical and fresh-food applications into sugar protection, driven by humidity-sensitive supply chains and brand-owner traceability mandates.
Printed electronics incorporating humidity sensors and time-temperature indicators are digitizing supply chain visibility for bulk sugar shipments. Large Brazilian and Thai exporters are piloting RFID-enabled bulk bags that transmit moisture ingress alerts to port logistics operators. This digitizing of cargo monitoring is compressing insurance premiums and dispute resolution timelines in maritime sugar trade.
EU F-Gas Regulation bans hydrofluorocarbon blowing agents in expanded polystyrene insulation, indirectly pressuring cold-chain packaging adjacent to sugar distribution. European converters are reformulating thermal box liners with bio-based aerogels and vacuum-insulated panels. Rigid container suppliers serving premium confectionery segments face accelerated R&D timelines to maintain temperature performance without regulated materials.
Food service operators in US institutional channels are consolidating sugar procurement through group purchasing organizations that unbundle packaging specification authority from ingredient sourcing. This procurement consolidation concentrates volume with converters offering certified compostable sachets and transparent origin labeling. The shift is most visible in California and New York school nutrition programs where state-level plastic reduction mandates intersect with federal procurement scale.
Sugar Packaging Market Segmentation
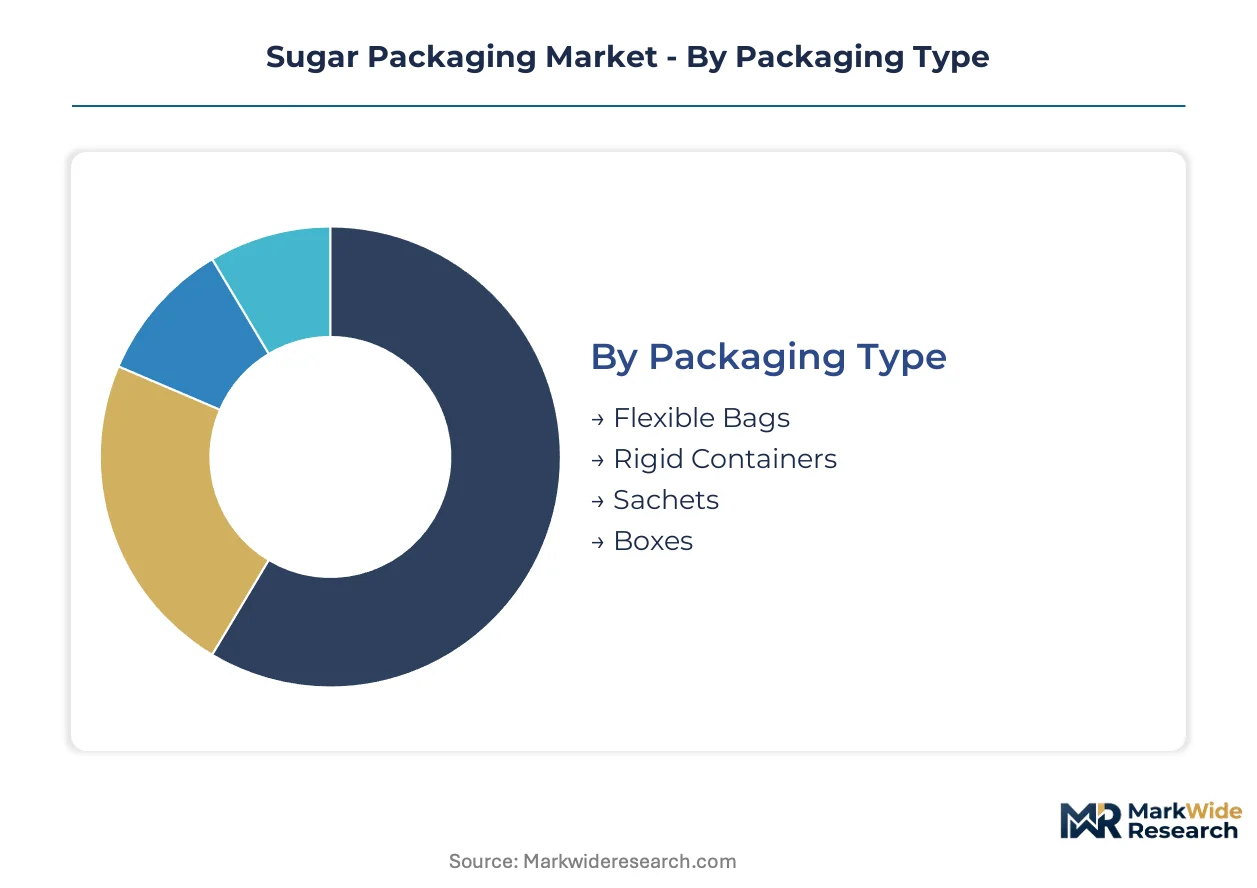
Sugar packaging segmentation reveals how material science, portion control economics, and channel logistics intersect to determine converter profitability. Each dimension carries distinct regulatory burdens and capital intensity requirements that reshape competitive positioning across supply chains.
Packaging Type:
Flexible formats dominate industrial procurement where throughput speed and freight cube efficiency determine total cost of ownership.
- Flexible Bags:Multi-layer polyethylene and metallized laminates protect 25-50 kg bulk shipments from moisture ingress during tropical storage. Indian industrial bakeries are pulling high-barrier films into automated filling lines as BIS certification tightens import substitution timelines.
- Rigid Containers:Injection-molded polypropylene and glass jars serve premium confectionery segments where reclosability and shelf aesthetics command price premiums. EU Green Deal procurement mandates in Netherlands and Denmark are redirecting public sector volume toward certified paper-based alternatives.
- Sachets:Single-serve paper and plastic laminates reduce waste in food service portion control. Brazil and Thailand exporters pilot RFID-enabled sachet lines for maritime traceability.
- Boxes:Corrugated containerboard enclosures protect retail multipacks and institutional bulk formats. Integrated board-to-box operations control cost positions across rigid secondary packaging.
The dominant share belongs to Flexible Bags, while Sachets are gaining share fastest as portion-control demand accelerates in emerging food processing clusters.
Material:
Platform selection hinges on barrier performance requirements, recyclability mandates, and feedstock cost volatility exposure.
- Plastic:Polyethylene, polypropylene, and PET laminates deliver moisture vapor transmission rates below tropical distribution thresholds. REACH restrictions on phthalate plasticizers compress flexible film formulations in European retail channels.
- Paper:Kraft-based sachets and bags displace conventional plastic as EFSA-aligned sustainability commitments reshape brand owner procurement. Heat-seal profile incompatibility with legacy filling equipment creates retrofit bottlenecks for mid-size converters.
- Metal:Aluminum foil and metallized films provide oxygen and moisture barriers for extended shelf stability. Rolling capacity concentrated in Chinese and Russian primary smelters exposes converters to geopolitical supply disruptions.
- Glass:Premium confectionery and gift segments leverage transparency and inertness for product visibility. Weight and fragility limit penetration beyond premium price tiers.
Plastic retains volume leadership, though Paper is expanding most quickly as EU F-Gas Regulation and extended producer responsibility frameworks accelerate material transitions.
End User:
Downstream demand fragmentation creates diverging specification requirements across moisture sensitivity, portion precision, and regulatory exposure.
- Beverage Industry:Liquid sugar and syrup packaging demands aseptic barrier performance and bulk logistics optimization. Tropical distribution corridors force metallized and oxide-coated film adoption beyond conventional polyethylene specifications.
- Confectionery:Premium chocolate and candy segments prioritize reclosability, shelf aesthetics, and temperature stability. Rigid container suppliers face compressed R&D timelines to maintain performance without regulated blowing agents.
- Bakery:Industrial scale procurement of single-serve sachets standardizes recipes and reduces waste. India and Brazil bakeries are scaling film laminate volumes into high-throughput filling lines.
- Food Processing:Ingredient sugar for manufactured foods requires bulk flexible formats with traceability certification. Group purchasing organizations are consolidating procurement authority and unbundling packaging specifications from ingredient sourcing.
Bakery applications command the largest volume share, while Beverage Industry specifications are climbing the fastest as tropical supply chain digitization accelerates.
Distribution Channel:
Channel selection determines pack size, labeling requirements, and sustainability certification burdens that filter back to converter specifications.
- Online Retail:E-commerce shipments demand compression-resistant secondary packaging and consumer-friendly unboxing experiences. California and New York school nutrition programs intersect state plastic reduction mandates with federal procurement scale.
- Supermarkets:Retail shelf presence requires transparent origin labeling and certified compostable formats for premium placement. EU Green Deal tenders in Netherlands and Denmark mandate bio-based or recyclable packaging.
- Convenience Stores:Impulse-oriented pack sizes and grab-and-go formats favor sachet and small rigid configurations. Portion control economics align with food service operator waste reduction targets.
- Wholesale:Industrial and institutional bulk procurement concentrates volume in 25-50 kg flexible bags with palletized distribution optimization. Aftermarket technical service revenue is reconfiguring how converters capture lifetime value from installed filling equipment bases.
Wholesale channels dominate volume throughput, though Online Retail is expanding most quickly as direct-to-consumer sugar brands proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between industrial bulk procurement in tropical processing hubs and retail portion-control demand in European food service channels, with regulatory frameworks accelerating material transitions in each geography.
India
Domestic food processing expansion and bakery sector automation are pulling high-barrier film laminates into BIS-certified packaging lines. India's mandatory migration testing for edible commodity containers is qualifying domestic converters for import substitution contracts with multinational processors. Maharashtra and Gujarat host the densest concentration of certified flexible bag operations serving industrial sugar buyers.
Germany
EU F-Gas Regulation and REACH compliance are compressing converter margins while accelerating transitions toward bio-based barrier films across flexible packaging supply chains. Extended producer responsibility frameworks in Germany and France are creating stranded asset risk for multi-layer laminate producers. The Rhine-Ruhr industrial corridor anchors integrated containerboard-to-box operations controlling cost positions across rigid formats.
Brazil
Industrial bakeries are scaling procurement of single-serve sugar sachets to standardize recipes and reduce waste, pulling film volumes into high-throughput filling lines. RFID-enabled bulk bag pilots for maritime traceability are digitizing supply chain visibility for large sugar exporters. São Paulo state concentrates flexible packaging conversion capacity serving both domestic food processing and export logistics.
United States
FDA food contact substance notifications govern barrier coating chemistries while group purchasing organizations consolidate procurement authority in institutional channels. California and New York school nutrition programs intersect state plastic reduction mandates with federal procurement scale. The Midwest industrial belt houses legacy filling equipment bases where aftermarket technical service revenue is reconfiguring converter lifetime value capture.
Netherlands
EU Green Deal procurement mandates now require bio-based or recyclable packaging in public sector food service tenders, redirecting volume toward certified paper-based sachet suppliers. Port logistics operators in Rotterdam are receiving moisture ingress alerts from sensor-enabled bulk sugar shipments. The Randstad cluster anchors European kraft paper network operations supplying industrial sugar buyers with flexible bag alternatives.
Sugar Packaging Market Competitive Landscape
Capability concentration sits with integrated material science specialists; scale advantage sits with diversified packaging conglomerates operating across multiple substrate platforms. The market structures around three tiers: global converters with captive R&D infrastructure, regional specialists exploiting local certification barriers, and commodity producers competing on throughput economics. Two dominant competitive moves are reshaping positioning: backward integration into pulp and resin supply chains to control feedstock volatility, and strategic partnerships with filling equipment OEMs to lock in aftermarket service revenue streams.
Within the integrated material science tier, Mondi Group exemplifies European kraft paper network leverage for flexible industrial supply, while Amcor plc occupies a position anchoring global R&D intensity in high-barrier laminates. Smurfit Westrock represents the containerboard-to-box integration archetype, controlling cost positions across rigid formats through captive paperboard supply. These three entities collectively illustrate how geographic production clustering and substrate specialization determine competitive moats in sugar packaging conversion.
| Leading Market Players |
|---|
| Mondi Group |
| Amcor plc |
| Smurfit Westrock |
| Sealed Air Corporation |
| International Paper Company |
| WestRock Company |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Berry Global Inc. |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr industrial corridor anchors European containerboard supply, and its captive pulp integration grants rigid packaging converters pricing power over Asian import-dependent competitors serving the same bakery and confectionery accounts.
Pricing Analysis
Long-term offtake contracts dominate industrial sugar packaging procurement, with annual volume commitments locking in polyethylene resin pricing for 25-50 kg flexible bag converters. Price differentiation hinges on BIS certification tier and after-sales technical service bundling. Cost compression in standard-grade laminates is intensifying because ethylene feedstock volatility transfers naphtha-cracker margin swings directly to converter P&Ls. Mid-size bakeries in India exhibit highest price sensitivity, while premium confectionery brands in Netherlands absorb sustainability premiums for EU Green Deal-compliant formats.
Supply Chain Analysis
Extended payment terms from Brazilian and Thai sugar exporters are forcing flexible film converters to carry 90-120 day working capital cycles, amplifying financing risk during resin price spikes. Raw material supply draws from Chinese aluminum rolling capacity, Saudi ethylene cracker output, and Nordic kraft pulp networks. Single-source vulnerability concentrates in metallized barrier films tethered to Russian and Chinese primary aluminum smelters. Distribution runs through Rotterdam and São Paulo port logistics clusters before final-mile palletization to industrial bakeries and food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation bans on hydrofluorocarbon blowing agents are disrupting thermal packaging performance standards, creating a high-growth disruption window for bio-based aerogel and vacuum-insulated panel suppliers serving premium confectionery cold chains.
For Market Incumbents: Insulate margin positions through backward integration into Nordic kraft pulp supply and captive metallized film coating capacity, neutralizing aluminum foil supply concentration risk from Chinese and Russian smelters while securing REACH-compliant barrier formulations against regulatory tightening. For New Entrants and Emerging Players: Sub-Saharan African packaged sugar consumption per capita in Nigeria and Kenya trails Southeast Asian benchmarks by substantial margins, creating white-space opportunity for localized pouch printing partnerships and BIS-certification-adjacent migration testing services targeting pan-African food processor expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core sugar-facing flexible film operations; mid-size converters with certified BIS laboratory relationships and installed base service contracts represent priority acquisition profiles. Watch for cellulose nanofiber barrier commercialization timelines as inflection signal for paper-based laminate displacement of plastic films.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp | Rhine-Ruhr and Nordic captive fiber supply locks in containerboard cost positions against Asian import volatility. |
| BIS Certification Laboratory Investment | Six-month qualification queues in India create bottleneck arbitrage for domestic converters seeking multinational food processor contracts. |
| Cellulose Nanofiber R&D Partnership | Wood-derived oxygen barriers enable EFSA-aligned paper sachets without fossil-derived coating chemistries. |
| RFID-Enabled Bulk Bag Pilot Expansion | Brazilian and Thai maritime exporters compress insurance premiums through moisture ingress digitization. |
| EU Green Deal Tender Qualification | Netherlands and Denmark public sector mandates redirect volume toward certified bio-based sachet suppliers. |
Research Methodology
Cross-validation between converter production data and downstream procurement disclosures anchors the qualitative findings, combining primary interviews with flexible packaging plant managers, bakery procurement leads, BIS laboratory directors, and port logistics operators with secondary validation through customs trade records, SEC packaging segment filings, and EU F-Gas regulatory impact assessments. Bottom-up capacity modeling triangulates against top-down sugar consumption forecasts.
Calibration against historical polyethylene resin price elasticity and aluminum rolling capacity utilization shapes the analytical framework across the projection horizon. Segmentation dimensions include packaging format, material platform, end-use industry, and regional regulatory cluster. CAGRs derive from trend-line extrapolation of BIS certification expansion rates and EU extended producer responsibility adoption curves, with cellulose nanofiber commercialization timelines and RFID sensor cost curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cellulose nanofiber specialists or Gulf-state ethylene cracker expansions would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
North America PET Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Cereal Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
PET Food Trays Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Food Green Packaging Market