
 Corrugated Octabins Market | 2026-2036
Corrugated Octabins Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Octabins Market Outlook
Direct-to-manufacturer channels is narrowing as corrugated octabin suppliers consolidate relationships with bulk agricultural and chemical buyers. Smurfit Kappa leverages its European mill network to control substrate supply for heavy-duty octabin grades. Mondi Group anchors its position through integrated kraftliner production that sustains consistent board caliper across large-format octabin runs. DS Smith competes on design-to-cost optimization, using parametric engineering to reduce material usage without sacrificing stack strength.
Corrugated octabins are eight-sided bulk containers fabricated from multiwall corrugated board, typically combining triple-wall or double-wall constructions with laminated liners to achieve dynamic load capacities exceeding one metric ton; they function primarily as collapsible, stackable shipping vessels for dry flowable goods. Standard octabins occupy the volume base across grain and resin applications where cost-per-unit-shipped dominates procurement criteria, while custom octabins command margin premiums through die-cut apertures, internal baffles, and branded exteriors tailored to pharmaceutical cleanroom protocols. Eco-friendly octabins are gaining fastest traction as FSC-certified liners and water-based adhesives displace conventional petroleum-derived coatings in European retail supply chains.
EPA guidelines on recycled content thresholds and REACH restrictions on heavy-metal inks shape material selection and print chemistry across North American and European production. FDA food-contact regulations and EU 10/2011 migration limits govern octabin deployment in edible oil and pharmaceutical powder applications, compelling linerboard upgrades and extractable testing protocols. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or partner with third-party recovery operators.
Market Dynamics
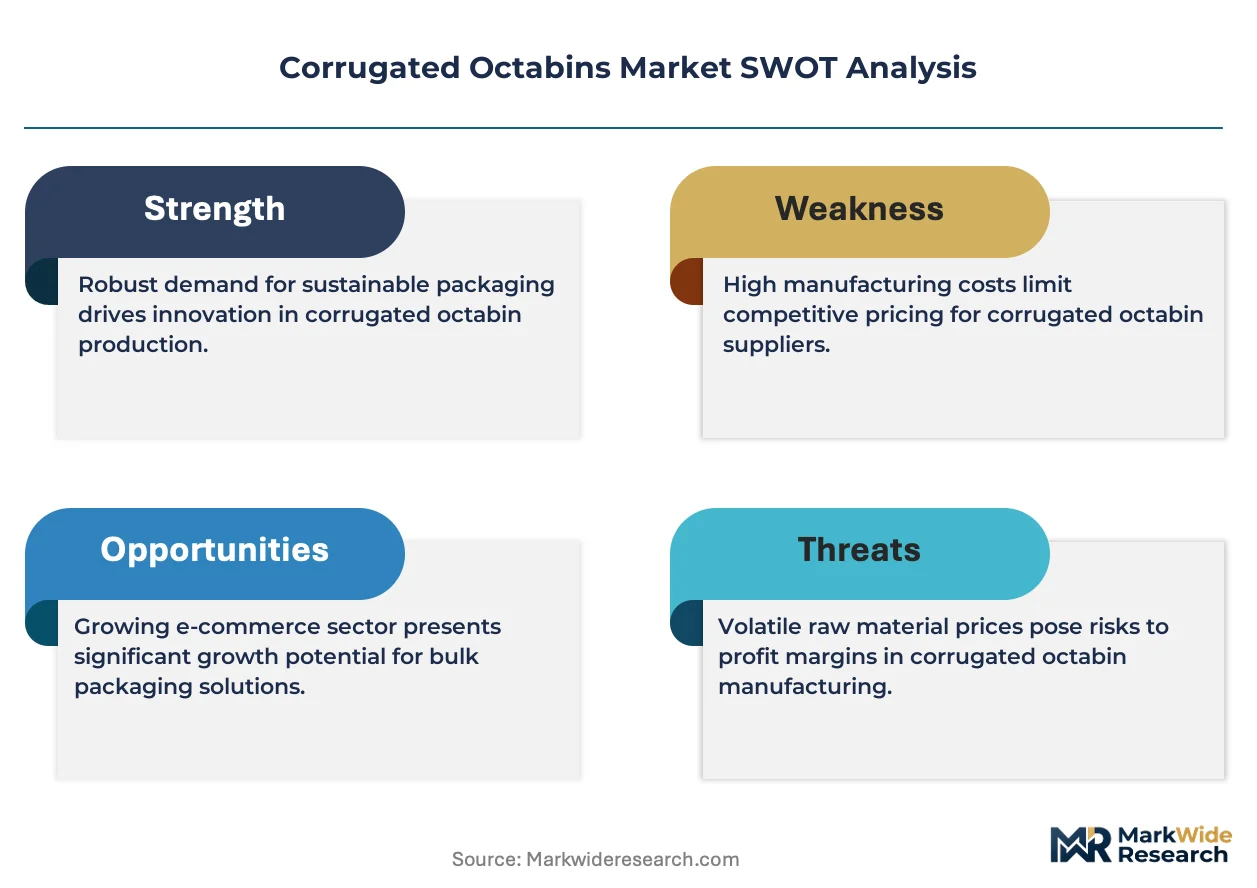
REACH compliance deadlines and EPA recycled-content mandates are compressing formulation timelines for corrugated octabin producers, forcing simultaneous linerboard upgrades and adhesive chemistry overhauls across European and North American supply chains.
Growth Catalysts
- REACH chemical restrictions:Heavy-metal ink prohibitions in Europe accelerate water-based coating adoption, opening premium positioning for FSC-certified octabin suppliers serving pharmaceutical cleanroom protocols.
- Soybean export logistics:Brazilian agricultural commodity handlers favor collapsible octabins over rigid bulk containers for intermodal grain transport, cutting return-haul deadweight.
- Parametric design software:Automated structural optimization reduces material usage in heavy-duty grades without sacrificing stack strength, lowering per-unit substrate costs.
Market Restraints
- Old corrugated container price volatility:OCC recovery rates fluctuate with municipal recycling program disruptions, squeezing margins for triple-wall board producers dependent on post-consumer fiber.
- Kraftliner supply concentration:Nordic pulp mill consolidation limits substrate availability for large-format octabin runs during Q4 peak demand windows.
- Rigid intermediate bulk container substitution:Reusable plastic totes retain cost advantage in closed-loop chemical distribution, blocking octabin penetration in solvent handling.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO packaging compliance requirements for active pharmaceutical ingredient bulk shipments create demand for migration-tested octabin liners.
- EU Green Deal procurement mandates:Public-sector packaging tenders now weight carbon footprint scores, advantaging recyclable corrugated over plastic alternatives in agricultural tenders.
- Digital print integration:Inline flexographic systems enable lot-code serialization and brand customization without plate-change delays, collapsing minimum order quantities for specialty chemical runs.
Industry Challenges
- Structural engineer scarcity:Finite-element analysis expertise for dynamic load modeling concentrates among legacy packaging design firms, slowing in-house capability builds.
- Extractable testing bottlenecks:EU 10/2011 migration studies for food-contact octabins queue at third-party laboratories, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Octabins Market |
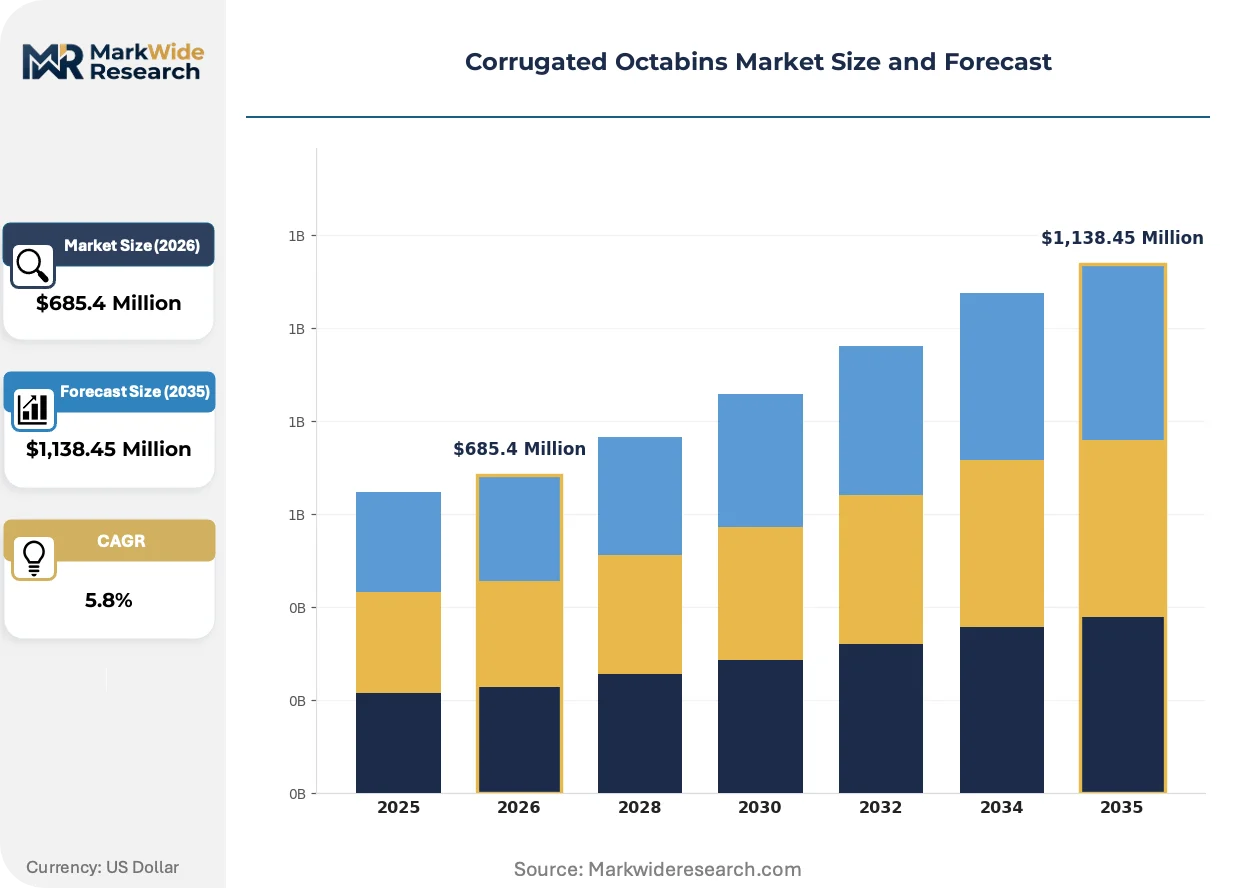
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Octabins, Printed Octabins, Custom Octabins, Eco-friendly Octabins End User: Food & Beverage, Pharmaceuticals, Chemicals, Retail Size: Small, Medium, Large, Extra Large Distribution Channel: Direct Sales, Online Sales, Retail Outlets, Distributors |
| Companies Covered | Smurfit Kappa, DS Smith, Mondi Group, International Paper, WestRock, Rengo Co. Ltd., Saica Group, Tri-Wall, VPK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Octabins Market Strategic Shifts
Digital manufacturing integration and regulatory chemistry shifts are compressing traditional octabin development cycles, collapsing the gap between substrate specification and finished container qualification.
Water-based barrier coatings are collapsing the performance gap between petroleum-derived polyethylene liners and recyclable alternatives in moisture-sensitive resin applications. German automotive parts distributors now specify these coatings for just-in-time component delivery, eliminating separate disposal streams while maintaining humidity protection during multi-modal transit.
EPA recycled-content thresholds for federal procurement are forcing linerboard suppliers to recalibrate furnish mixes, prioritizing post-consumer fiber over virgin kraft in heavy-duty grades. The industrial packaging corridor across the US Midwest faces the steepest compliance curve, with automotive and chemical buyers now auditing supplier certificates of analysis.
Consolidated procurement desks at multinational agricultural traders are compressing supplier rosters, favoring octabin vendors with integrated mill-to-box production control. Argentina's grain export cooperatives exemplify this concentration, awarding multi-year contracts to single-source providers capable of guaranteeing caliper consistency across ocean-container quantities.
Corrugated Octabins Market Segmentation
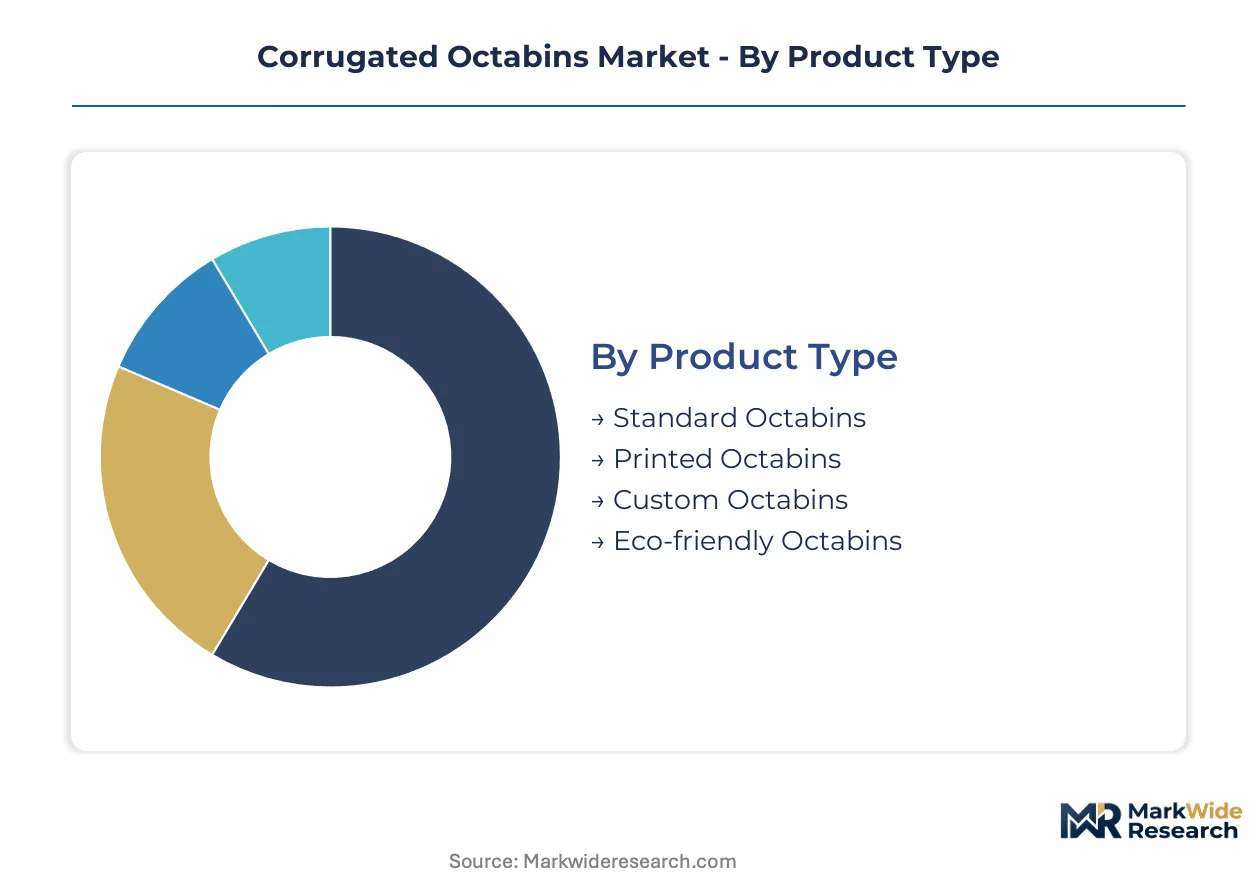
Corrugated octabin segmentation reflects divergent procurement priorities across bulk commodity handlers and precision industries. Material specification, regulatory compliance, and logistics integration shape how buyers navigate product categories and channel structures.
Product Type:
Mature segments dominate volume throughput while emerging variants capture sustainability premiums and customization value.
- Standard Octabins:Triple-wall or double-wall corrugated board constructions with laminated liners deliver dynamic load capacities exceeding one metric ton for dry flowable goods. Grain handlers in Brazil and Argentina specify these for soybean export logistics where cost-per-unit-shipped governs procurement decisions and collapsible designs eliminate return-haul deadweight.
- Eco-friendly Octabins:FSC-certified liners and water-based adhesives displace petroleum-derived coatings to meet EU Green Deal procurement mandates and REACH chemical restrictions. German automotive parts distributors now specify these recyclable alternatives for just-in-time component delivery, eliminating separate disposal streams while maintaining humidity protection.
- Printed Octabins:Inline flexographic systems enable lot-code serialization and brand customization without plate-change delays.
- Custom Octabins:Die-cut apertures, internal baffles, and branded exteriors tailored to pharmaceutical cleanroom protocols command margin premiums.
Standard octabins handle the majority of throughput; eco-friendly octabins are climbing the fastest on share.
End User:
Application-driven requirements separate commodity bulk handlers from regulated precision industries demanding migration-tested liners.
- Food & Beverage:FDA food-contact regulations and EU 10/2011 migration limits govern deployment in edible oil applications, compelling linerboard upgrades and extractable testing protocols. Third-party laboratory queues for qualification studies extend timelines for suppliers serving this segment.
- Pharmaceuticals:CDSCO packaging compliance requirements for active pharmaceutical ingredient bulk shipments in India create demand for certified octabin liners with documented extractable profiles. Cleanroom protocols and heavy-metal ink prohibitions accelerate water-based coating adoption.
- Chemicals:REACH compliance deadlines and EPA recycled-content mandates compress formulation timelines for chemical-contact packaging.
- Retail:Public-sector agricultural tenders now weight carbon footprint scores, advantaging recyclable corrugated alternatives.
Food & beverage anchors volume demand; pharmaceuticals posts the steepest expansion trajectory on compliance-driven upgrades.
Size:
Dimensional selection tracks payload density and intermodal compatibility across ocean-container and truckload configurations.
- Large:Optimized for grain and resin applications where Argentina's export cooperatives award multi-year contracts to single-source providers guaranteeing caliper consistency across ocean-container quantities.
- Extra Large:Heavy-duty grades with parametric-engineered structures reduce material usage without sacrificing stack strength for automotive and chemical buyers in the US Midwest industrial corridor.
- Small:Compact footprints suit specialty chemical runs with collapsed minimum order quantities via digital print integration.
- Medium:Versatile dimensions bridge bulk commodity and precision component applications.
Large sizes move the bulk of agricultural tonnage; extra large formats gain fastest on industrial automation and just-in-time delivery requirements.
Distribution Channel:
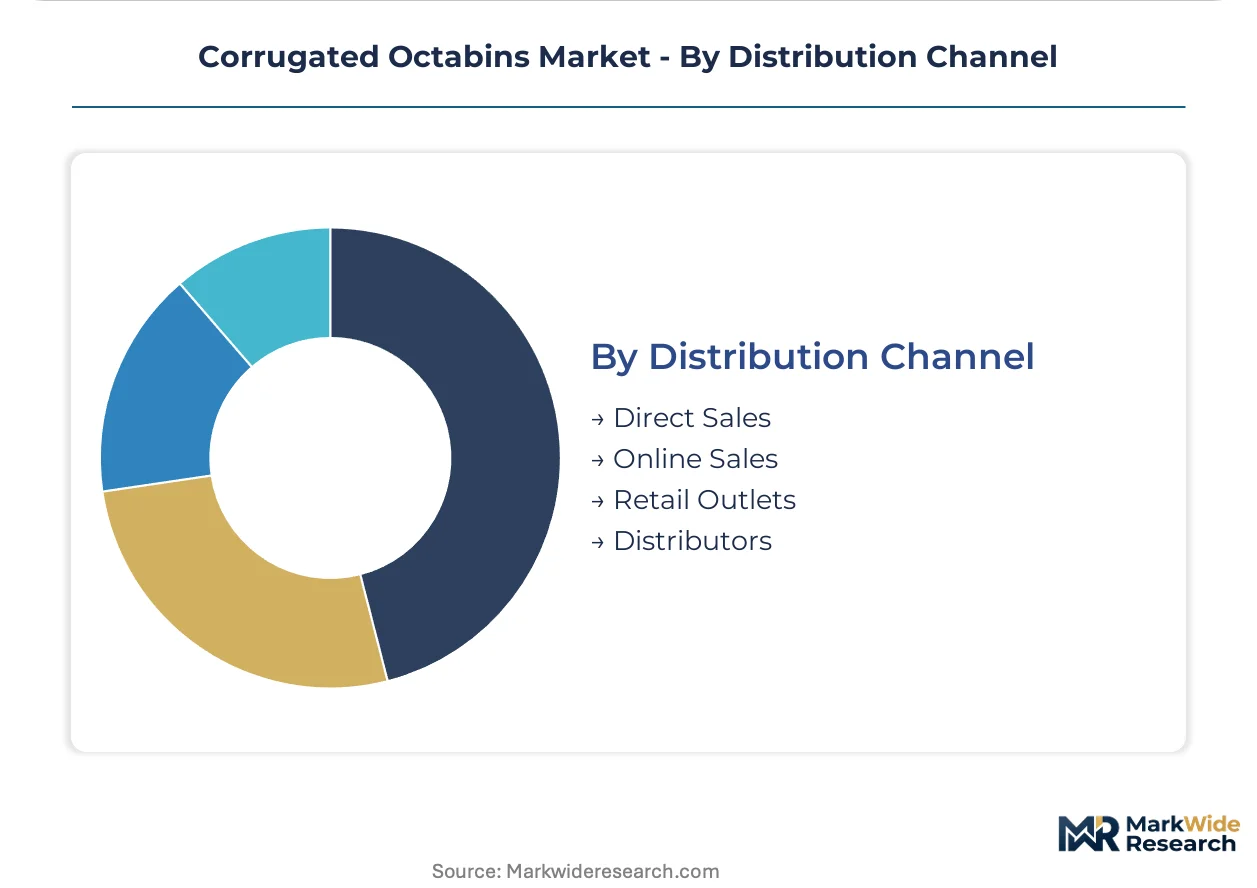
Channel structure concentrates around direct procurement relationships as consolidated buying desks compress supplier rosters.
- Direct Sales:Integrated mill-to-box production control enables Smurfit Kappa and Mondi Group to guarantee substrate supply and caliper consistency for multinational agricultural traders. These relationships dominate heavy-duty octabin procurement for bulk commodity handlers.
- Distributors:Regional stocking points serve fragmented chemical and pharmaceutical buyers requiring rapid qualification turnaround and smaller lot sizes. DS Smith competes through design-to-cost optimization delivered via distributor networks.
- Online Sales:Digital platforms collapse minimum order quantities for specialty chemical runs with serialized lot codes.
- Retail Outlets:Limited penetration given bulk industrial orientation of octabin applications.
Direct sales channels capture the dominant share of contract volume; distributor relationships expand fastest on qualification flexibility and smaller lot servicing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA recycled-content mandates and REACH chemical restrictions anchor regulatory intensity across the United States and Germany, the two largest demand centers for heavy-duty corrugated octabins. Brazil and India emerge as high-growth corridors where agricultural export expansion and pharmaceutical compliance upgrades drive specification shifts.
United States
Automotive parts distributors in the Midwest industrial corridor specify parametric-engineered octabins for just-in-time component delivery. EPA guidelines on recycled content thresholds for federal procurement force linerboard suppliers to recalibrate furnish mixes toward post-consumer fiber. Heavy-duty grade producers face compliance audits from buyers in Michigan and Ohio.
Germany
The industrial packaging corridor between Cologne and Hamburg favors eco-friendly octabins with water-based barrier coatings for humidity-sensitive resin shipments. EU Green Deal procurement mandates weight carbon footprint scores in public-sector agricultural tenders. REACH heavy-metal ink prohibitions accelerate water-based coating adoption among suppliers serving pharmaceutical cleanroom protocols.
Brazil
Agricultural commodity handlers in Mato Grosso and Paraná favor collapsible octabins over rigid bulk containers for soybean export logistics. ANVISA food-contact regulations govern edible oil packaging specifications for shipments to European buyers. Port terminals in Santos report rising intermodal containerization rates for grain exports.
India
Active pharmaceutical ingredient bulk shipments from Gujarat and Maharashtra drive demand for migration-tested octabin liners. CDSCO packaging compliance requirements compel extractable testing protocols at third-party laboratories. Export-oriented pharmaceutical clusters in Hyderabad and Mumbai queue for qualification studies.
Argentina
Grain export cooperatives in Buenos Aires province award multi-year contracts to single-source octabin providers guaranteeing caliper consistency across ocean-container quantities. Municipal recycling program disruptions create OCC price volatility for triple-wall board producers. Rosario's agricultural trading desks consolidate procurement rosters around integrated mill-to-box suppliers.
Corrugated Octabins Market Competitive Environment
Integrated paperboard producers and specialized packaging engineers split the market between substrate control and design optimization. The vendor base concentrates among European and North American multinationals with captive kraftliner supply, while regional specialists compete on qualification flexibility and smaller lot servicing. Three archetypes dominate: mill-integrated giants controlling furnish supply, design-to-cost optimizers leveraging parametric software, and sustainability-focused suppliers capturing FSC-certified premiums. Consolidated procurement desks at agricultural traders compress supplier rosters, while digital print integration enables shorter runs for specialty chemical buyers.
Among mill-integrated European producers, Smurfit Kappa, Mondi Group, and DS Smith anchor the competitive structure. Smurfit Kappa exemplifies the substrate-control archetype through its European mill network. Mondi Group occupies a position defined by integrated kraftliner production sustaining board caliper consistency. DS Smith represents the design-optimization vector, competing through parametric engineering approaches that reduce material usage without sacrificing stack strength.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| Mondi Group |
| International Paper |
| WestRock |
| Rengo Co. Ltd. |
| Saica Group |
| Tri-Wall |
| VPK Group |
| Others |
Value Chain & Pricing Dynamics
Rhineland-Palatinate's kraftliner mill cluster controls substrate availability for European heavy-duty octabin production, translating furnish scarcity into sustained pricing leverage for integrated producers serving automotive and chemical buyers.
Pricing Analysis
German-Dutch price spreads for triple-wall board exceed southern European benchmarks by double-digit margins, reflecting Nordic pulp concentration and transport cost differentials. Three-tier pricing structure across FSC-certified premium, REACH-compliant standard, and economy grades separates pharmaceutical cleanroom protocols from bulk grain applications. Price compression in standard grades stems from OCC volatility and Brazilian agricultural trader consolidation. Commodity handlers in Argentina exhibit highest price sensitivity; pharmaceutical buyers in India accept premiums for migration-tested liners.
Supply Chain Analysis
Integrated mill operators Smurfit Kappa and Mondi Group hold captive capacity across Germany, Sweden, and the Netherlands, limiting third-party substrate access during Q4 peak windows. Kraftliner supply draws from Nordic pulp mills, recycled OCC streams, and water-based adhesive chemistries. Single-source vulnerability concentrates in linerboard furnish during municipal recycling disruptions. Distribution runs through direct procurement relationships with multinational agricultural traders and regional distributor networks for pharmaceutical qualification flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated octabin procurement is consolidating around platform-scale suppliers capable of integrating digital print serialization with substrate consistency guarantees, compressing the viable vendor base to mill-integrated ecosystems.
For Market Incumbents: Harden substrate control through backward integration into kraftliner furnish or long-term pulp offtake agreements with Nordic suppliers. Defend against rigid intermediate bulk container substitution by embedding humidity-protective water-based coatings into standard specifications. Prioritize parametric design software deployment to compress material usage without sacrificing stack strength certification.
For New Entrants and Emerging Players: Indian pharmaceutical export corridors represent the most penetrable entry point, where CDSCO compliance requirements and third-party laboratory queues delay incumbent qualification timelines. Target mid-size chemical distributors in the US Midwest seeking flexible lot sizes with serialized lot codes. Lead with digital print integration enabling rapid customization without plate-change delays.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mill-integrated suppliers with multi-year agricultural export contracts; these command valuation premiums over design-only competitors. Long-term viability over a five-to-ten-year horizon favors suppliers with FSC-certified substrate access and REACH-compliant coating chemistry already deployed. Monitor EU Green Deal procurement mandate expansion into public-sector agricultural tenders as inflection signal for sustainability-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraftliner Production | Captive substrate supply insulates margin pressure from Nordic pulp mill consolidation and OCC volatility. |
| Water-Based Barrier Coating Certification | REACH-compliant chemistry opens pharmaceutical cleanroom protocols and German automotive just-in-time contracts. |
| Parametric Design Software Deployment | Automated structural optimization reduces material usage while maintaining dynamic load capacities exceeding one metric ton. |
| Digital Print Serialization Integration | Inline flexographic systems collapse minimum order quantities for specialty chemical runs with lot-code traceability. |
| Multi-Year Agricultural Export Contracts | Argentina's grain cooperatives consolidate procurement rosters around single-source providers guaranteeing caliper consistency. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with agricultural commodity traders, automotive parts procurement managers, pharmaceutical packaging compliance officers, corrugated board plant engineers, and chemical distribution channel heads. Secondary validation drew from EPA recycled-content guidelines, REACH substance restriction databases, EU 10/2011 migration limit protocols, customs trade data for kraftliner imports, and SEC filings of integrated paperboard producers. Bottom-up volume estimates triangulated against top-down industry association capacity data.
Calibration against historical price points for triple-wall board and OCC spot markets anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, size format, and distribution channel structure. CAGRs were derived from trend extrapolation of agricultural export volumes, pharmaceutical shipment growth, and regulatory compliance upgrade cycles. Industry-specific forecast inputs incorporated linerboard furnish mix shifts and water-based coating adoption curves.
Macroeconomic conditions sit as an overlay; deviation in ocean freight rates, pulp commodity pricing, and Brazilian harvest yields would shift the trajectory. Quarterly review of OCC recovery rates, Nordic mill operating rates, and EU Green Deal tender announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Industrial Pails Market