
 Foodservice Paper Bags Market | 2026-2036
Foodservice Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Foodservice Paper Bags Market Analysis
The EU Single-Use Plastics Directive is pivoting European foodservice procurement toward fiber-based packaging. Novolex Holdings Inc. leverages its North American manufacturing footprint to supply quick-service chains with grease-resistant formats. Mondi Group anchors its position through integrated kraft paper production and converting operations across Central Europe. Huhtamaki Oyj differentiates via compostable barrier coatings that meet EN 13432 certification requirements.
Foodservice paper bags are multiwall or single-ply fiber containers, typically constructed from unbleached or bleached kraft pulp with basis weights ranging from 40 to 120 grams per square meter, designed to transport prepared foods while resisting oil migration and moisture loss. Brown Kraft Bags dominate volume due to lower pulp costs and established recycling infrastructure, while Greaseproof Paper Bags capture expanding margin pools as quick-service chains specify fluorochemical-free barriers. Handle Bags represent the fastest-growing design category as third-party delivery platforms mandate secure transport formats.
FDA food contact substance regulations govern barrier coatings in the United States, while REACH and the EU Packaging and Packaging Waste Directive shape material compliance across Europe. China's GB standards for food contact paper and board, administered by SAMR, dictate import specifications for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling certifications as procurement criteria tighten across major foodservice channels.
Market Dynamics
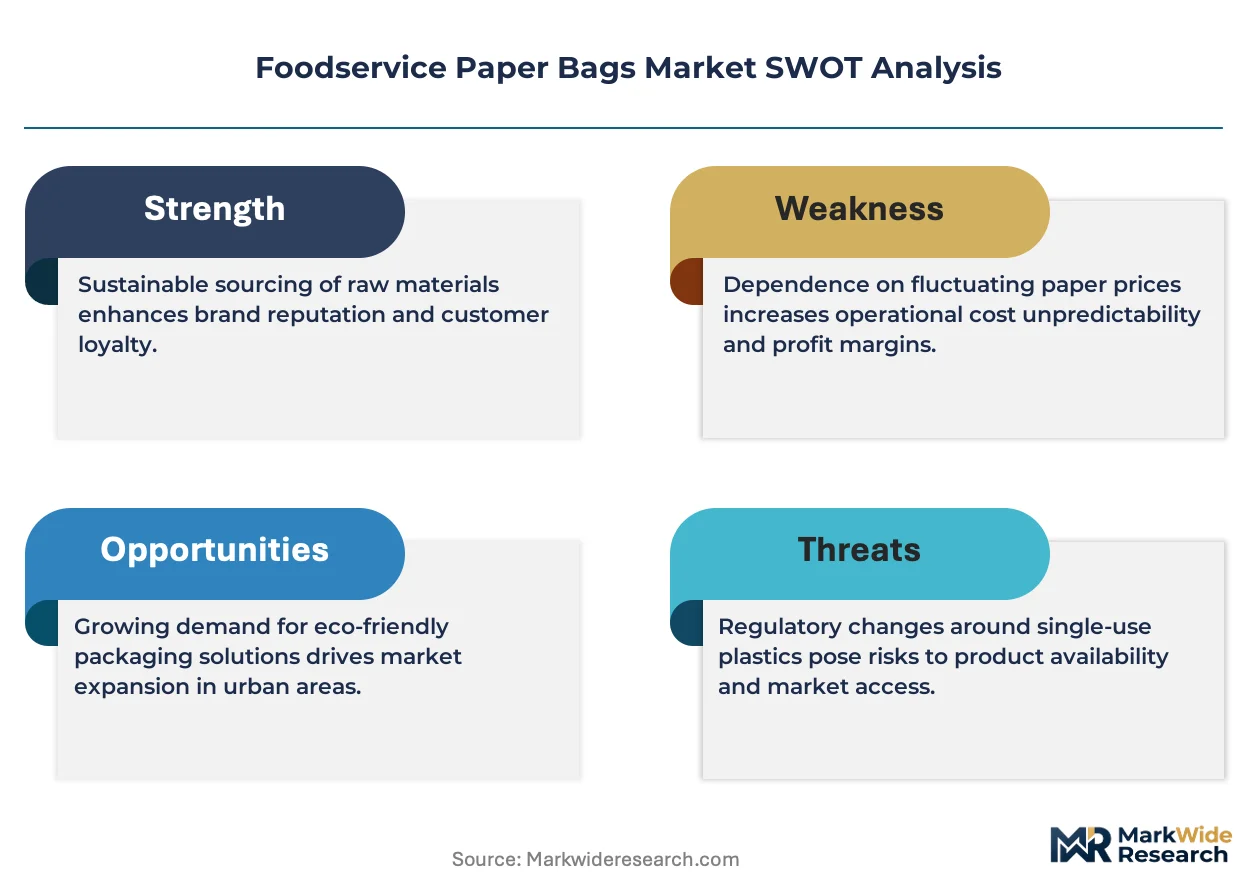
The EU Single-Use Plastics Directive is eliminating plastic alternatives across European foodservice channels, forcing a wholesale substrate migration toward fiber-based packaging formats with certified grease barriers.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework bans select plastic foodservice items across member states, redirecting quick-service restaurant procurement toward compliant paper alternatives with proven oil resistance.
- Quick-service restaurant expansion:Chains in the United States and Germany are accelerating specifications for custom-printed, greaseproof formats to support branded delivery experiences.
- Third-party delivery platform requirements:Food delivery aggregators now mandate handle-equipped, spill-resistant packaging designs that secure transport integrity across urban logistics networks.
Market Restraints
- Pulp cost volatility:Unbleached kraft pulp prices fluctuate with energy and fiber input costs, compressing converter margins on standard brown bag formats.
- Barrier coating supply concentration:Fluorochemical-free greaseproof chemistry production concentrates among specialty chemical suppliers in Germany and the United States, creating single-source risk for EN 13432-certified formulations.
- Performance limitations in high-moisture applications:Fiber-based structures face technical constraints against extended hot-food holding compared to plastic alternatives, restricting adoption in certain ready-meal segments.
Strategic Opportunities
- Compostable barrier coating convergence:Water-based polymers combined with bio-wax formulations are opening certification pathways for home-compostable food bags under emerging municipal standards.
- Direct-to-restaurant distribution platforms:Digital procurement channels are disintermediating traditional paper merchant networks, enabling converter-direct relationships with mid-size restaurant groups.
- China food delivery market:Platform packaging requirements in tier-one Chinese cities are creating demand for high-basis-weight handle bags with Mandarin-language branding capabilities.
Industry Challenges
- EN 13432 certification timeline:Compostable validation requires extended laboratory and field testing periods, delaying product launches by 12-18 months for new barrier formulations.
- Legacy printing equipment retrofitting:Converters must reconfigure flexographic lines for water-based inks compatible with compostable substrates, demanding capital deployment without guaranteed volume commitments.
- Cross-border compliance complexity:Multinational suppliers navigate divergent FDA food contact substance rules, REACH chemical registrations, and China's GB standards simultaneously, fragmenting product specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foodservice Paper Bags Market |
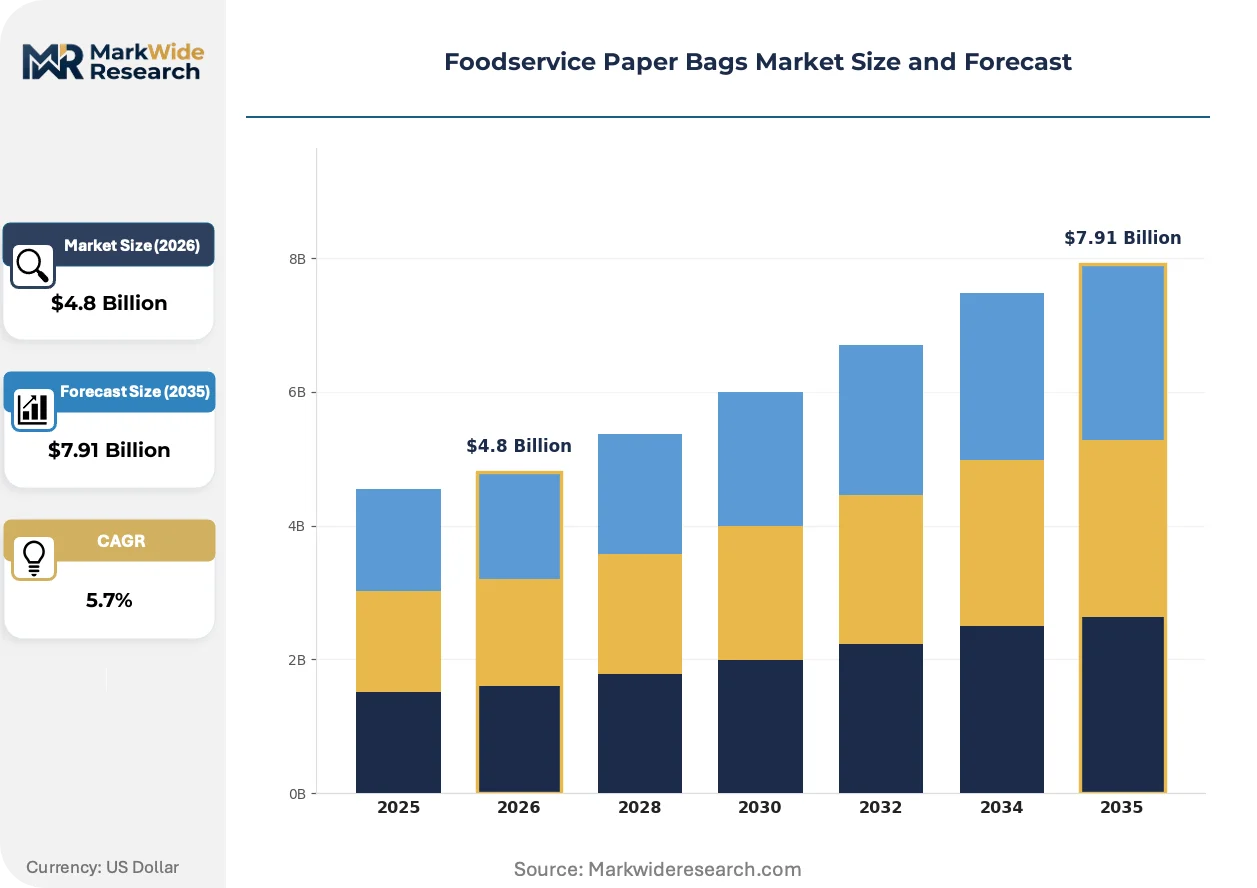
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Kraft Bags, White Kraft Bags, Recycled Paper Bags, Greaseproof Paper Bags End User: Restaurants, Cafés, Food Trucks, Catering Services Size: Small Bags, Medium Bags, Large Bags, Extra-Large Bags Design Type: Plain Bags, Printed Bags, Custom Bags, Handle Bags |
| Companies Covered | Novolex Holdings Inc., Mondi Group, International Paper Company, WestRock Company, Smurfit Kappa Group, Genpak LLC, Huhtamaki Oyj, Vegware Ltd., Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foodservice Paper Bags Market Emerging Trajectories
Barrier coating chemistry and digital printing integration are converging to redefine performance specifications and brand customization capabilities across foodservice packaging procurement.
Fluorochemical-free greaseproof treatments using plant-derived wax emulsions and bio-based polymers are unifying oil resistance with compostability certification. Quick-service chains in Germany and France are specifying these formats for fried food applications. The technology is unifying previously separate performance and sustainability procurement criteria into single-source supplier relationships.
REACH chemical registration requirements are tightening disclosure obligations for food contact substances across European converting operations. Manufacturers must now document full material composition down to 0.1% concentration thresholds for intentional additives. Small and mid-size converters without dedicated regulatory affairs functions are outsourcing compliance verification to specialized consulting firms.
Restaurant procurement departments are consolidating supplier rosters from fragmented local paper merchants toward national distribution agreements with integrated converter networks. Third-party delivery platforms in the United States are mandating approved packaging vendor lists, effectively pre-selecting substrates for their restaurant partners. This concentration is most visible in California and New York, where municipal plastic bans have compressed switching timelines.
Foodservice Paper Bags Market Segmentation
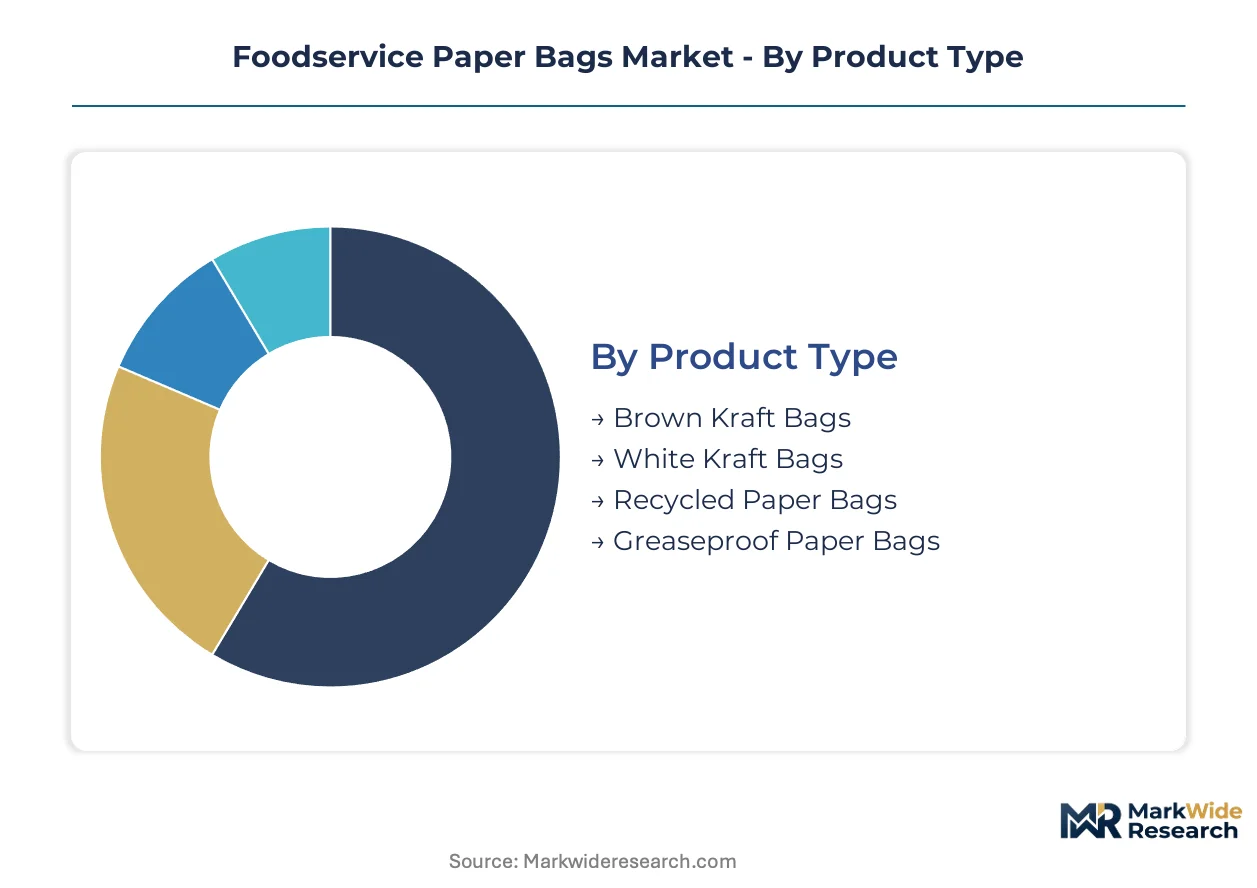
Foodservice paper bag procurement splits sharply between commodity volume plays and premium specification formats. Quick-service chains negotiate brown kraft tonnage on price indices while boutique operators commission custom-printed greaseproof constructions. Understanding these tier dynamics exposes where margin pools concentrate versus where scale economies dominate.
Product Type:
Brown Kraft Bags command the volume tier through lower pulp input costs and established North American recycling streams. Greaseproof Paper Bags anchor the premium tier where fluorochemical-free barrier specifications justify supplier consolidation.
- Brown Kraft Bags:Unbleached kraft pulp constructions with basis weights from 40 to 80 grams per square meter serve high-volume quick-service chains. United States procurement concentrates here as national restaurant groups optimize unit economics across thousands of locations.
- Greaseproof Paper Bags:Fluorochemical-free barrier coatings resist oil migration in fried food applications while meeting FDA food contact substance regulations. German quick-service chains specify these formats under EU Single-Use Plastics Directive compliance mandates, consolidating supplier relationships around certified converters.
- White Kraft Bags:Bleached pulp substrates enable sharper print registration for branded retail applications.
- Recycled Paper Bags:Post-consumer fiber content satisfies municipal procurement requirements in California and New York.
Today's leader: Brown Kraft Bags. Tomorrow's challenger: Greaseproof Paper Bags.
End User:
Restaurant procurement departments wield the largest order books and longest contract tenors. Food truck operators drive format innovation through space-constrained logistics requirements.
- Restaurants:Full-service and quick-service establishments generate the majority of tonnage demand through national distribution agreements. United States chains specify custom-printed formats to reinforce brand identity across third-party delivery platforms.
- Food Trucks:Mobile operators require compact, handle-equipped designs that secure transport integrity in variable urban environments. New York and Los Angeles food truck density creates concentrated demand for spill-resistant formats.
- Cafés:Beverage-forward operations prioritize small-format bags for pastry and retail merchandise.
- Catering Services:Event-based procurement favors extra-large constructions for bulk transport.
Volume concentrates with Restaurants. Format innovation originates from Food Trucks.
Size:
Medium Bags capture the operational sweet spot for standard meal combinations. Extra-Large Bags serve catering and family-format applications where unit economics differ.
- Medium Bags:Dimensional specifications accommodate standard quick-service meal combinations with beverage and side items. German restaurant procurement standardizes here to minimize SKU complexity across multi-brand operators.
- Extra-Large Bags:High-basis-weight constructions support bulk catering orders and family meal formats. United States catering operators specify reinforced handles for transport integrity at volume.
- Small Bags:Compact formats serve single-item pastry and retail merchandise.
- Large Bags:Intermediate capacity fills gaps between standard meal and bulk applications.
Procurement standardizes on Medium Bags. Catering expansion elevates Extra-Large Bags.
Design Type:
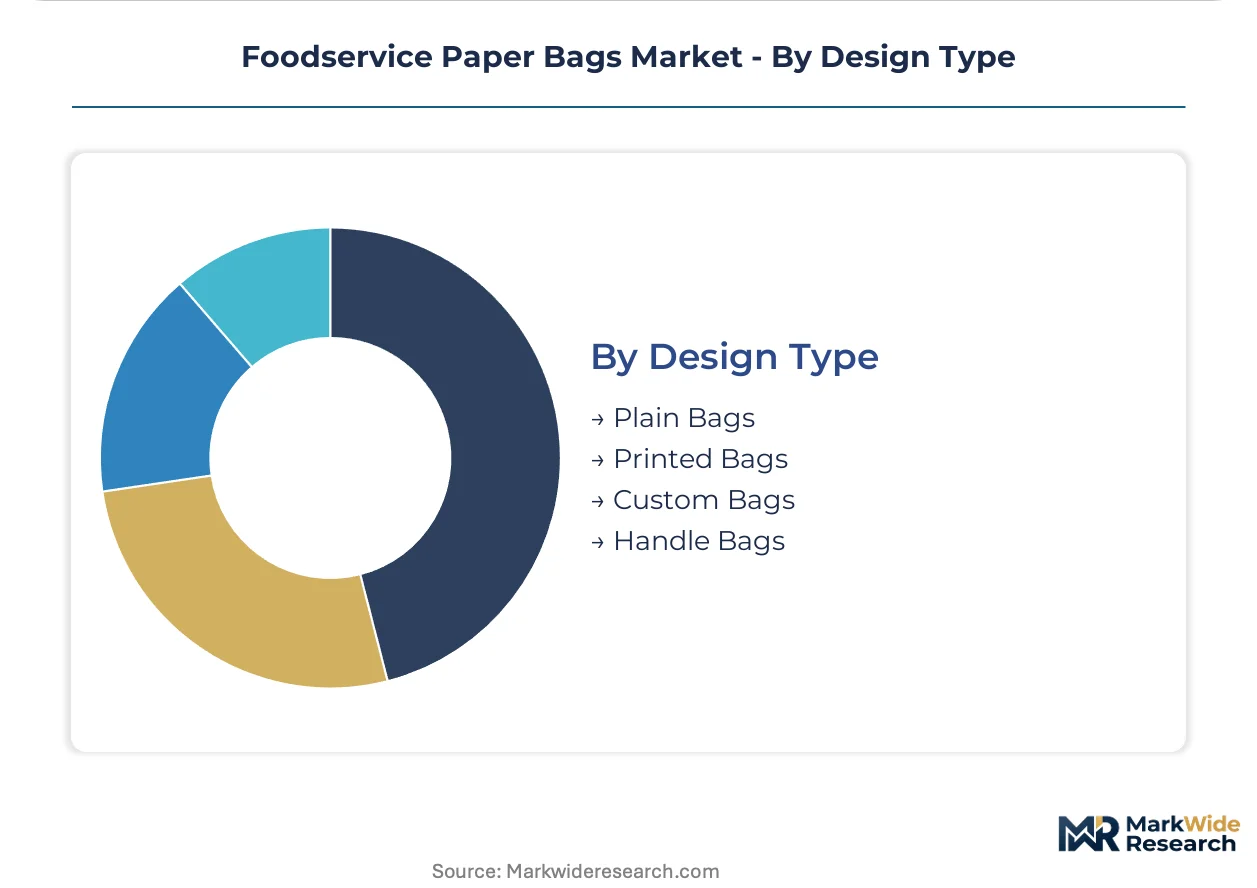
Handle Bags are expanding most quickly as delivery platforms mandate secure transport. Custom Bags concentrate margin through brand-specific print requirements.
- Handle Bags:Twisted paper or die-cut handle constructions satisfy third-party delivery platform packaging mandates. China's tier-one city food delivery networks specify Mandarin-language branded handle bags for urban logistics compliance.
- Custom Bags:Flexographic or digital print capabilities enable restaurant-specific branding with variable data for promotional campaigns. Quick-service chains in France commission these formats to differentiate unboxing experiences.
- Printed Bags:Standard graphic templates serve mid-size restaurant groups without custom origination costs.
- Plain Bags:Unprinted substrates minimize unit cost for price-sensitive independent operators.
Handle Bags climb the fastest. Custom Bags defend margin position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice paper bag manufacturing originated in Germany's industrialized Rhineland during the early twentieth century, where kraft pulp processing and converting operations first achieved commercial scale. Production networks subsequently expanded across North America and Asia-Pacific as quick-service restaurant chains internationalized their supply chains.
United States
Quick-service restaurant chains and third-party delivery platforms drive procurement volumes across California, Texas, and New York. FDA food contact substance regulations govern barrier coating compliance, while municipal plastic bans in California and New York compress switching timelines. Chicago and Los Angeles anchor converting capacity for grease-resistant formats serving national distribution networks.
Germany
Integrated kraft paper producers and specialty chemical suppliers cluster around industrial zones in North Rhine-Westphalia and Bavaria. REACH chemical registration requirements mandate full material composition disclosure down to 0.1% concentration thresholds for intentional additives. Düsseldorf and Munich concentrate EN 13432-certified compostable barrier development for quick-service fried food applications.
China
Food delivery platform expansion in tier-one cities creates demand for high-basis-weight handle bags with Mandarin-language branding capabilities. SAMR-administered GB standards for food contact paper and board dictate import specifications for multinational suppliers. Shanghai and Beijing manufacturing clusters supply domestic quick-service chains while serving as export hubs for Asia-Pacific markets.
France
Boutique restaurant operators and catering services commission custom-printed formats to differentiate unboxing experiences in Paris and Lyon. EU Packaging and Packaging Waste Directive compliance shapes material selection criteria across national procurement channels. The Île-de-France region concentrates flexographic printing capacity for premium branded applications.
United Kingdom
Mid-size restaurant groups consolidate supplier rosters toward national distribution agreements with integrated converter networks. Extended producer responsibility frameworks tighten post-consumer recycling requirements for foodservice packaging substrates. Greater London anchors demand for spill-resistant handle formats serving dense urban delivery logistics.
Foodservice Paper Bags Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier certification and custom print capabilities. The vendor base separates into three tiers: integrated pulp-to-bag producers commanding scale advantages, specialty converters focused on greaseproof certifications, and regional merchants serving independent restaurant operators. Strategic moves concentrate on M&A-driven geographic expansion and backward integration into kraft pulp production to secure fiber supply.
Among North American integrated producers, Novolex Holdings Inc. and WestRock Company exemplify scale-driven archetypes with captive converting networks. European specialists including Mondi Group and Huhtamaki Oyj occupy positions emphasizing certified compostable barrier development. These named entities represent divergent competitive vectors—geographic coverage versus sustainability certification—without implying specific strategic actions or market positions.
| Leading Market Players |
|---|
| Novolex Holdings Inc. |
| Mondi Group |
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| Genpak LLC |
| Huhtamaki Oyj |
| Vegware Ltd. |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EN 13432-certified compostable formats and commodity brown kraft constructions manifests in divergent margin structures and supply chain configurations across the foodservice paper bags market. Premium-tier procurement concentrates around German and French converters with validated barrier chemistry, while volume-tier sourcing flows through North American integrated producers with captive pulp supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with EN 13432 certification and fluorochemical-free barrier chemistry commanding 15-30 point spreads over commodity brown kraft. Price differentiation rests on barrier performance grade and custom print capability, with quick-service chains in Germany and France least sensitive to unit cost. Cost compression in standard brown kraft is intensifying because unbleached pulp price volatility transfers directly to converter margins, while independent restaurant operators in the United States exhibit highest price elasticity.
Supply Chain Analysis
Workforce availability constraints in Germany's North Rhine-Westphalia and Bavaria industrial zones limit specialty chemical production capacity for certified barrier formulations. Geographic supply concentration centers on Germany, the United States, and China, with kraft pulp, bio-wax emulsions, and water-based polymer coatings anchoring raw material dependencies. Single-source vulnerability runs through German specialty chemical suppliers for EN 13432-certified greaseproof chemistry. Distribution runs through national converter networks and direct-to-restaurant digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Single-Use Plastics Directive compliance costs in Germany and France exceed North American regulatory burdens, creating margin capture opportunities for converters with dual-continent certification capabilities.
For Market Incumbents: To counter pulp cost volatility and specialty chemical supply concentration, backward integration into unbleached kraft pulp production secures fiber supply for volume-tier operations, while exclusive partnerships with German barrier chemistry developers lock in EN 13432 certification pathways for premium-tier positioning. For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany and France opens a window for compostable barrier coating specialists to capture quick-service restaurant procurement migrating from plastic alternatives. White-space targets include mid-size restaurant groups in California and New York seeking direct converter relationships, and food delivery platforms mandating approved vendor lists. A digital-first go-to-market approach bypasses traditional paper merchant networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty converters possessing validated compostable barrier technology and established quick-service chain relationships. Long-term viability hinges on regulatory tailwinds extending plastic bans across additional US states and EU member countries. Acquisition targets should demonstrate EN 13432 certification completion and flexographic line retrofitting for water-based inks. The signal to watch is municipal procurement mandates shifting toward home-compostable standards beyond industrial composting certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Production | Captive fiber supply insulates Novolex and WestRock from spot pulp volatility in US South. |
| EN 13432 Certification Investment | Validated compostable barriers unlock German quick-service procurement under EU Directive mandates. |
| Digital Procurement Platform Launch | Direct-to-restaurant channels disintermediate traditional paper merchants in California and New York. |
| Water-Based Ink Line Retrofitting | Flexographic reconfiguration enables compostable substrate compatibility for French custom print demand. |
| China Tier-One City Distribution Buildout | Mandarin-language branding capabilities capture food delivery platform requirements in Shanghai and Beijing. |
Methodological Framework
Direct dialogue with paper mill operations managers, quick-service restaurant procurement directors, food delivery platform packaging compliance officers, and specialty chemical R&D leads grounded qualitative findings, validated against FDA food contact substance filings, EU ECHA REACH registrations, Chinese SAMR GB standards, trade association technical reports, and SEC converter filings. Bottom-up volume modeling triangulated with top-down market sizing across product type, end user, size, and design type dimensions.
Segmented volume and value projections across the analysis window reflect demand elasticity modeling by quick-service chain expansion rates, pulp price index correlations, and regulatory compliance cost pass-through assumptions. CAGRs derived from historical growth pattern analysis adjusted for plastic ban implementation timelines and food delivery platform packaging mandate adoption curves. Forecast inputs incorporated barrier coating technology substitution rates and digital procurement channel penetration.
Revisions become necessary when EU member state implementation timelines for Single-Use Plastics Directive provisions accelerate or delay, when unbleached kraft pulp prices exhibit sustained volatility beyond historical bands, or when municipal home-compostable standards diverge from EN 13432 industrial composting specifications. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
North America Foodservice Packaging Market