
 Frozen Food Packaging Market | 2026-2036
Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Food Packaging Market Intelligence
China is rewriting frozen food packaging capacity dynamics as domestic cold-chain infrastructure scales. Amcor Plc leverages its Asia-Pacific manufacturing network to supply multi-layer barrier films for seafood and dumpling applications. Sealed Air Corporation anchors North American demand through Cryovac vacuum-sealed systems optimized for protein preservation. Crown Holdings dominates metal can formats for frozen juice concentrates and prepared vegetables.
Frozen food packaging encompasses engineered barrier structures—typically multi-layer coextruded films, aluminum-laminated paperboard, or thermoformed polyethylene terephthalate—designed to prevent moisture loss, oxidation, and freezer burn across temperatures reaching minus 18 degrees Celsius. Flexible pouches lead volume in retail frozen fruit and vegetable segments due to material efficiency and cube utilization advantages, while rigid containers command margin pools in premium ready-meal applications where microwave-ability and stackability drive purchase decisions. Vacuum sealed bags represent the fastest-growing format as sous-vide and flash-frozen protein brands expand direct-to-consumer channels.
The FDA governs indirect food additive migration limits under 21 CFR, while EPA regulations on per- and polyfluoroalkyl substances are forcing substrate reformulation across US suppliers. REACH compliance in Europe restricts certain phthalates and heavy metals in plasticized films, redirecting R&D spend toward bio-based sealant layers. Stakeholders must monitor evolving state-level extended producer responsibility laws and their impact on multi-material laminate recyclability economics.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing substrate transitions across the value chain, redirecting R&D spend from multi-material laminates toward mono-material and bio-based barrier structures that satisfy recyclability mandates without compromising minus 18 degrees Celsius performance.
Growth Catalysts
- Quick-service restaurant expansion:Chains are broadening frozen menu portfolios, pulling specialized pouches and rigid trays designed for rapid thaw and cook applications.
- REACH compliance redirection:European restrictions on phthalates and heavy metals in plasticized films are accelerating sealant layer innovation toward bio-based alternatives.
- German cold-chain density:Private-label frozen food penetration in Germany generates premium packaging demand for high-barrier, stackable formats.
Market Restraints
- Aluminum price volatility:Laminated paperboard and foil-dependent structures face margin compression when commodity aluminum spikes.
- Multi-material recyclability economics:Extended producer responsibility laws in multiple US states render complex laminate disposal costs prohibitive for mid-tier brands.
- PFAS regulatory friction:EPA restrictions on per- and polyfluoroalkyl substances force reformulation of grease-resistant coatings with limited commercial substitutes.
Strategic Opportunities
- Direct-to-consumer protein channels:Sous-vide and flash-frozen brands are expanding vacuum-sealed bag demand outside traditional retail.
- China cold-chain scale:Domestic infrastructure investment creates capacity for multi-layer barrier films serving seafood and dumpling processors.
- Microwave-ability premium:Ready-meal brands are specifying thermoformed polyethylene terephthalate with susceptor patches for browning performance.
Industry Challenges
- Migration testing timelines:FDA 21 CFR indirect food additive compliance requires 12-18 month validation cycles that delay substrate launches.
- Legacy equipment retrofit costs:Converting from rigid to flexible formats demands capital expenditure on form-fill-seal lines that smaller converters cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Food Packaging Market |
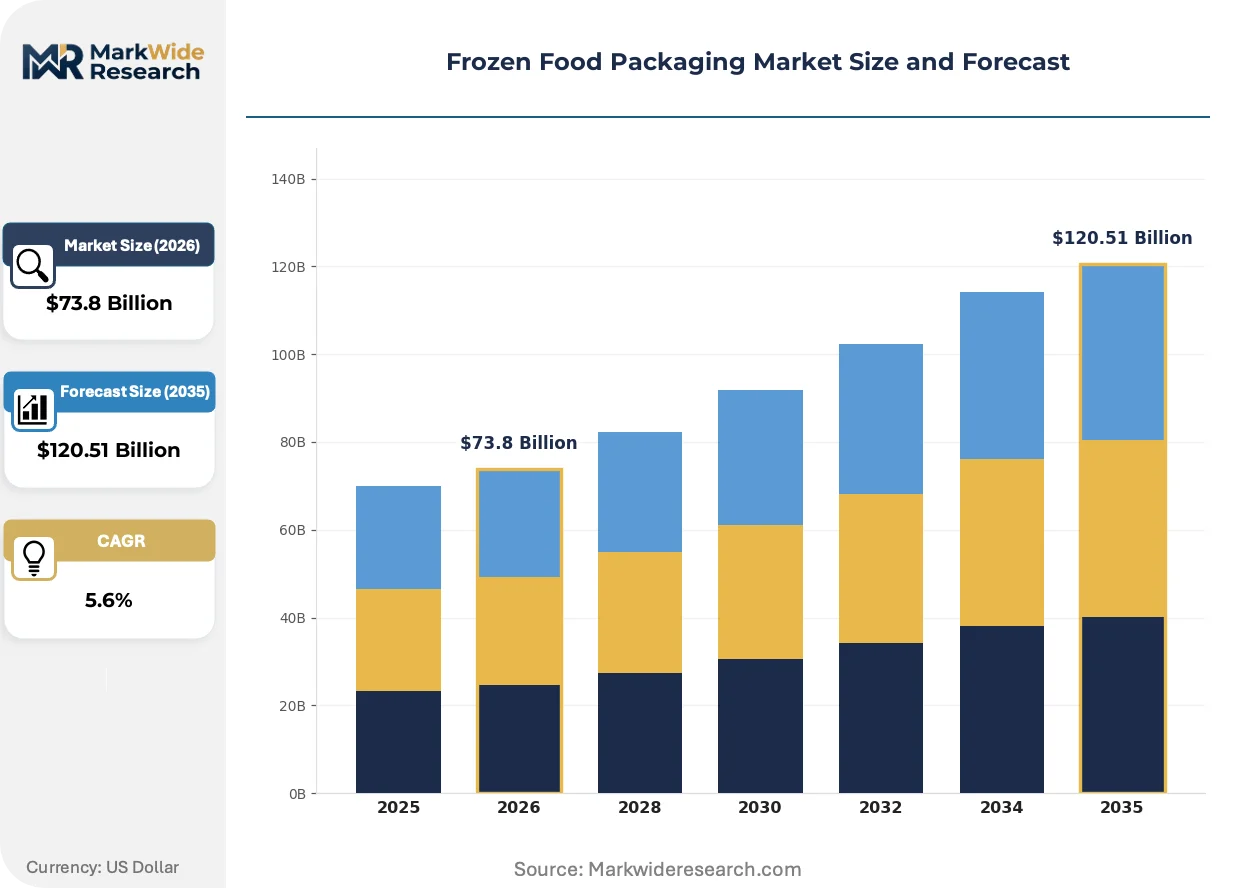
| Market Size in 2026 | $73.8 Billion |
| Market Size in 2035 | $120.51 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Pouches, Rigid Containers, Metal Cans, Vacuum Sealed Bags Material: Plastic, Aluminum, Paperboard, Glass End User: Retail Chains, Food Service, Online Grocery, Supermarkets Closure Type: Screw Caps, Zipper, Snap-on Lids, Heat Sealed |
| Companies Covered | Crown Holdings Inc., Pactiv Evergreen, Amcor Plc, Graham Packaging Company, Genpak LLC, Sealed Air Corporation, Ball Corporation, Tetra Pak International, Smurfit WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Food Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging systems are penetrating frozen food applications, embedding temperature logging and freshness indicators directly into barrier structures to reduce supply chain waste and liability exposure.
Printed electronics integration into flexible pouches is digitizing cold-chain verification. Retailers and foodservice distributors are piloting RFID-enabled films that log thermal excursions from processing through last-mile delivery. This capability is digitizing insurance and quality assurance workflows, compressing dispute resolution cycles from weeks to hours.
The EU F-Gas Regulation is accelerating hydrofluoroolefin adoption in insulated shipping containers. Manufacturers of temperature-controlled packaging are reformulating foam-in-place systems to meet GWP thresholds, with German logistics providers leading fleet conversion. Seafood exporters to European markets now specify low-carbon cold-chain packaging to satisfy procurement mandates.
Flash-frozen direct-to-consumer brands are compressing traditional retail channel dominance. Protein subscription services specify vacuum-sealed formats optimized for home freezer density, bypassing conventional corrugated shipper requirements. This channel rotation is most visible in North American metropolitan markets where cold-chain last-mile infrastructure supports weekly delivery cadences.
Frozen Food Packaging Market Segmentation
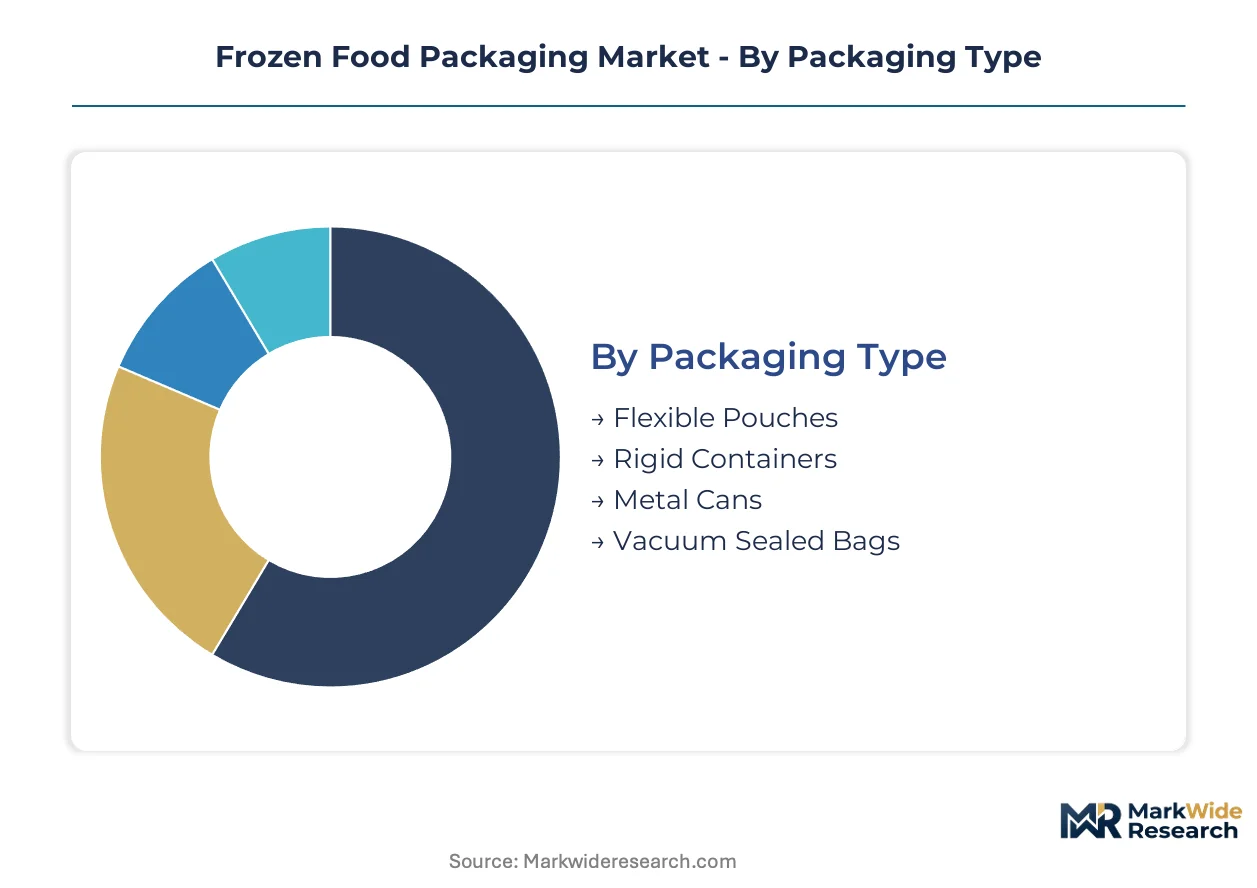
Frozen food packaging segments diverge sharply by thermal performance requirements and distribution channel economics. Format selection directly determines barrier specifications, equipment capital requirements, and compliance pathways across cold-chain networks.
Packaging Type:
Application use cases separate formats by thaw speed, shelf visibility, and freezer density optimization.
- Flexible Pouches:Multi-layer coextruded films with EVOH or nylon barrier layers deliver moisture and oxygen protection at material weights below 15 grams per unit. Retail chains in Germany specify these for private-label frozen vegetables where cube utilization drives logistics economics.
- Vacuum Sealed Bags:Cryovac-derived vacuum systems with seven-to-nine layer structures eliminate headspace oxidation for protein preservation. Flash-frozen direct-to-consumer brands in North American metropolitan markets are rotating volume toward this format as subscription delivery cadences compress traditional retail channels.
- Rigid Containers:Thermoformed PET or PP structures with modified atmosphere capabilities serve ready-meal segments requiring microwave-ability and stackability.
- Metal Cans:Three-piece or drawn aluminum formats dominate frozen juice concentrates and prepared vegetables where hermetic integrity spans multi-year shelf lives.
Flexible pouches hold installed capacity. Vacuum sealed bags are rotating up the share rankings.
Material:
Cost tier positioning and recyclability mandates are forcing substrate transitions across the value chain.
- Plastic:Polyethylene, polypropylene, and polyester resins form the base for coextruded films and thermoformed trays. REACH compliance in Europe is redirecting R&D spend from phthalate-plasticized films toward bio-based sealant layers that maintain minus 18 degrees Celsius performance.
- Aluminum:Foil laminates and metalized films provide near-zero oxygen transmission rates for premium protein applications. Commodity price volatility compresses margins for laminated paperboard structures when LME aluminum spikes.
- Paperboard:Polyethylene-coated or aluminum-laminated board serves frozen pizza and dessert cartons where printability and retail shelf presence justify material cost premiums.
- Glass:Borosilicate and tempered glass containers occupy niche premium segments for frozen desserts and specialty sauces where thermal shock resistance and reusability drive consumer willingness to pay.
Plastic dominates unit volume. Aluminum is gaining share fastest in barrier-intensive protein applications.
End User:
Customer type determines order scale, specification complexity, and cold-chain integration depth.
- Food Service:Quick-service restaurant chains specify bulk formats—ten-to-twenty kilogram pouches and rigid totes—optimized for rapid thaw and cook workflows. Expansion of frozen menu portfolios across US and European QSR networks is pulling specialized high-barrier structures.
- Online Grocery:Direct-to-consumer platforms require primary packaging that substitutes for corrugated shipper protection, driving vacuum-sealed and insulated pouch specifications.
- Retail Chains:Private-label penetration in Germany concentrates demand for stackable, high-graphics formats that maximize freezer case facing efficiency.
- Supermarkets:Conventional grocery channels balance material cost against theft deterrence and handling durability for high-velocity frozen SKUs.
Food service holds installed capacity. Online grocery is climbing the fastest among end-user channels.
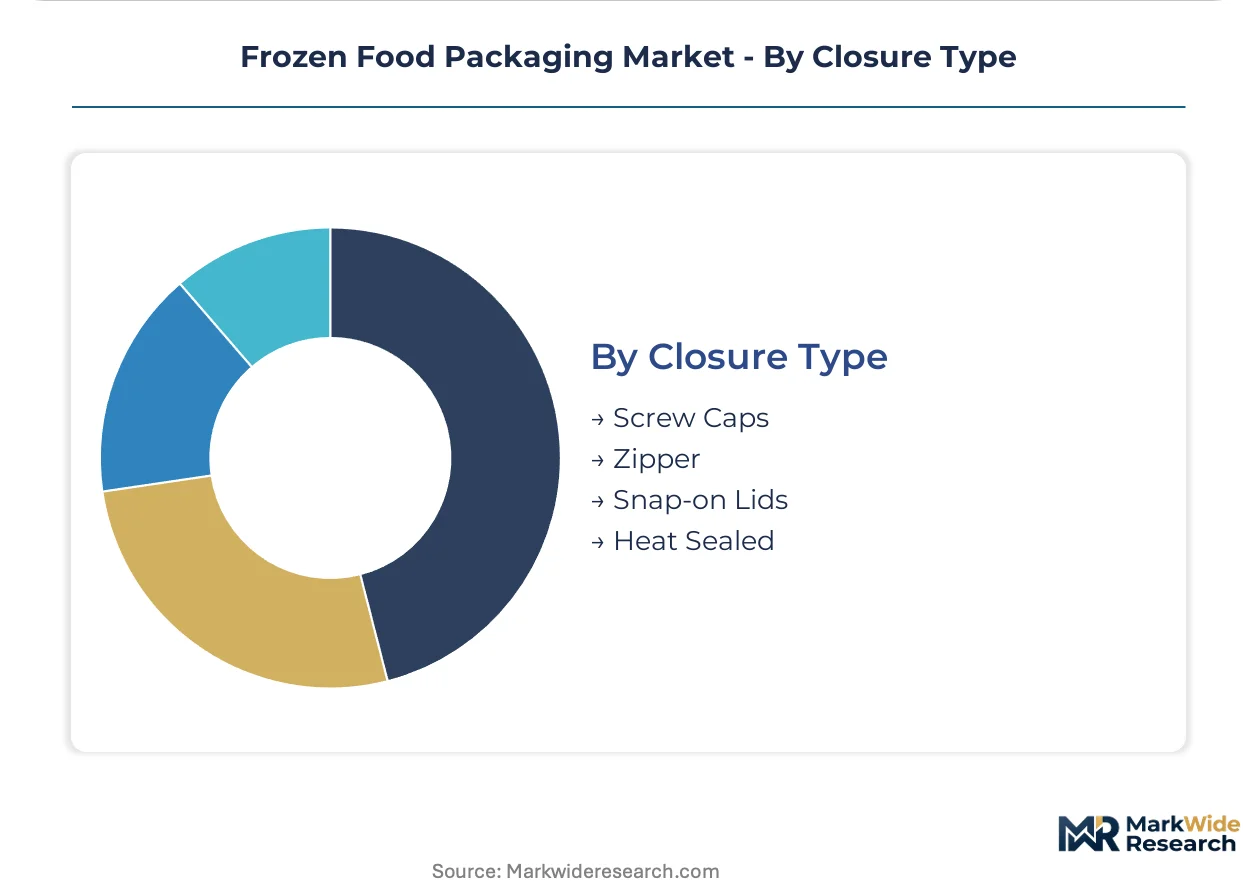
Closure Type:
Resealability and tamper evidence requirements vary by consumption pattern and regulatory jurisdiction.
- Heat Sealed:Impulse or constant heat sealing of multilayer films delivers hermetic integrity for vacuum and modified atmosphere applications. FDA 21 CFR indirect food additive compliance requires twelve-to-eighteen month validation cycles that delay substrate launches.
- Zipper:Press-to-close interlocking profiles in polyethylene or polypropylene enable consumer resealability for multi-serve frozen fruit and vegetable pouches.
- Screw Caps:Injection-molded HDPE or PP closures with induction seals serve frozen juice concentrates and sauces in rigid containers.
- Snap-on Lids:Polypropylene lids with perimeter locking beads provide microwave venting and stack stability for ready-meal trays.
Heat sealed closures hold installed capacity. Zipper formats are expanding most quickly in retail frozen produce segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for frozen food packaging clusters in Germany, China, and the United States, with specialized converter networks in each market serving distinct cold-chain infrastructure densities and regulatory environments.
United States
Quick-service restaurant chains drive specialized pouch demand for rapid-thaw workflows. EPA restrictions on per- and polyfluoroalkyl substances force substrate reformulation across domestic suppliers. Chicago-area converters supply multi-material laminates to Midwest protein processors.
Germany
Private-label frozen food penetration generates premium packaging pull for high-barrier, stackable formats. REACH compliance redirects R&D spend from phthalate-plasticized films toward bio-based sealant layers. Bavarian logistics providers lead fleet conversion under EU F-Gas Regulation mandates.
China
Domestic cold-chain infrastructure scales create capacity for multi-layer barrier films serving seafood and dumpling processors. SAMR food contact material standards tighten migration testing requirements. Yangtze River Delta manufacturing clusters supply flexible pouches to regional frozen food brands.
Japan
Flash-frozen direct-to-consumer brands compress traditional retail channel dominance. METI carbon neutrality targets accelerate shifts toward mono-material recyclable structures. Osaka-based converters develop thermoformed PET with susceptor patches for premium ready-meal applications.
United Kingdom
Online grocery platforms require primary packaging substituting for corrugated shipper protection. Extended producer responsibility laws render complex laminate disposal costs prohibitive for mid-tier brands. London metropolitan logistics networks pilot RFID-enabled films for cold-chain verification.
Frozen Food Packaging Market Key Industry Players
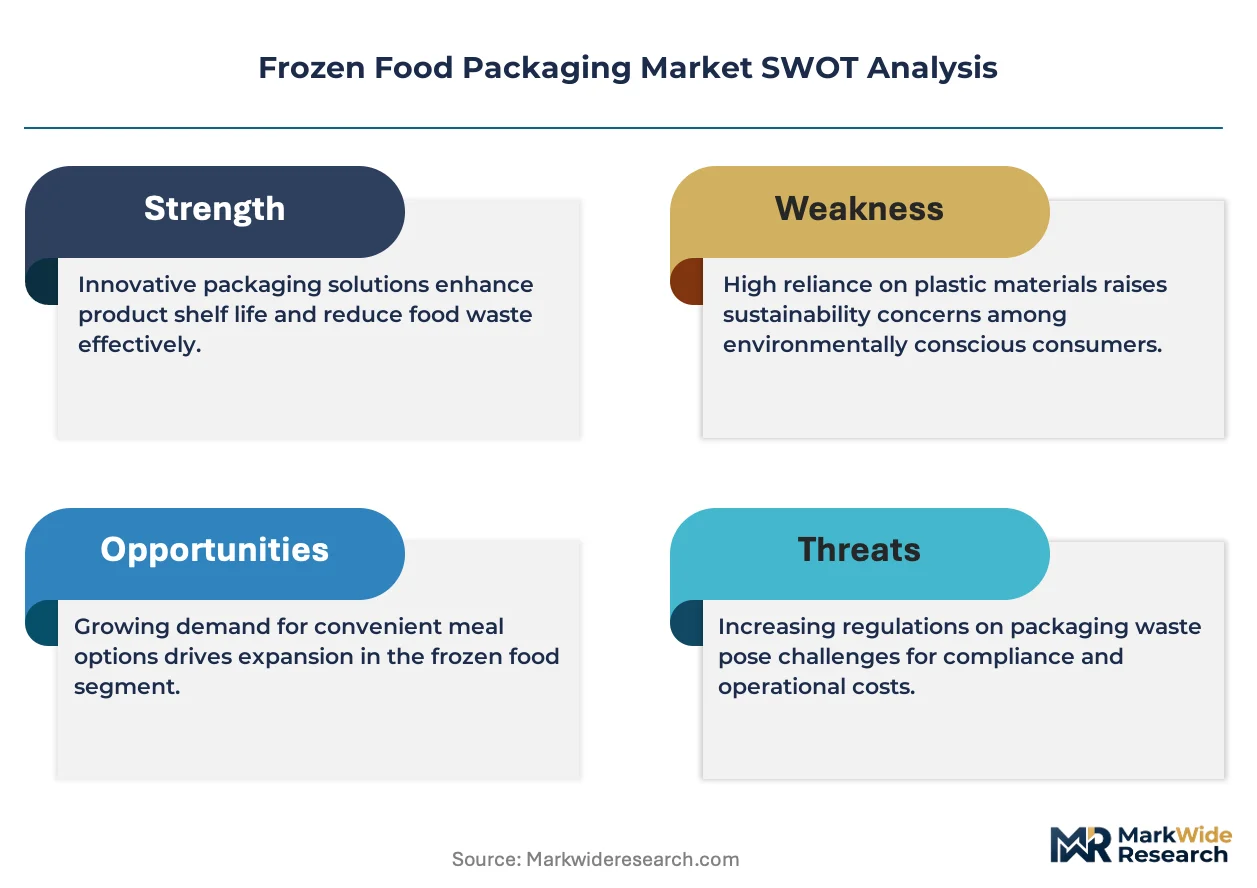
Platform integrators command the system tier; component specialists sit upstream in material and equipment supply. The vendor base spans three tiers: multinational converters with integrated film extrusion and printing capabilities, regional specialists focused on single-format dominance, and equipment suppliers capturing value through form-fill-seal line integration. Strategic moves concentrate on substrate portfolio diversification and geographic expansion into cold-chain growth markets.
Among diversified packaging conglomerates, Amcor Plc and Sealed Air Corporation exemplify platform-scale positioning across flexible and vacuum-sealed formats. Crown Holdings occupies a position within rigid metal packaging archetypes. These three anchors represent distinct competitive vectors: film-based barrier systems, vacuum-sealed protein preservation technologies, and hermetic metal can formats for long-shelf-life applications.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Pactiv Evergreen |
| Amcor Plc |
| Graham Packaging Company |
| Genpak LLC |
| Sealed Air Corporation |
| Ball Corporation |
| Tetra Pak International |
| Smurfit WestRock |
| Others |
Cost & Logistics Intelligence
Aluminum price volatility determines both pricing tier spreads and supply chain shape across frozen food packaging substrates. When LME aluminum spikes, laminated paperboard structures face immediate margin compression that forces converters toward plastic mono-material alternatives or long-term offtake contracts with smelters.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European markets. Three-tier pricing structure across premium, standard, and economy levels separates bio-based sealant laminates from conventional phthalate-plasticized films and commodity polyethylene structures. Certification tier under FDA 21 CFR migration testing creates additional differentiation for substrates validated for protein contact. Pricing pressure stems from extended producer responsibility laws in multiple US states that render complex laminate disposal costs prohibitive for mid-tier brands. Private-label retail chains in Germany demonstrate lowest price sensitivity due to cold-chain density advantages, while smaller US converters face acute margin compression.
Supply Chain Analysis
Polyethylene and polypropylene resin feedstock draws from petrochemical complexes concentrated in China, the United States, and Germany. EVOH barrier layer supply rests on ethylene vinyl alcohol production anchored in Japan and South Korea. Aluminum foil sourcing hinges on rolling mill capacity in China and Russia. Single-source vulnerability pervades specialized seven-to-nine layer coextrusion equipment, where German and Japanese machinery suppliers command lead times exceeding twelve months. Distribution runs through converter networks clustered near cold-chain infrastructure density in the Yangtze River Delta, Bavaria, and the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades frozen food packaging as direct-to-consumer protein channels displace traditional retail concentration. Flash-frozen subscription services create niche demand for vacuum-sealed formats that bypass established converter relationships.
For Market Incumbents: Insulate substrate portfolios from PFAS regulatory friction by accelerating bio-based sealant layer R&D before EPA restrictions harden. Lock in long-term aluminum offtake agreements to neutralize commodity volatility. Acquire regional specialists in vacuum-sealed bag formats to defend against direct-to-consumer channel rotation. For New Entrants and Emerging Players: Southeast Asian cold-chain infrastructure gaps present white-space entry points for flexible pouch converters serving seafood processors. Target online grocery platforms in UK metropolitan markets with insulated pouch specifications that substitute for corrugated shipper protection. Pursue equipment partnerships with second-hand form-fill-seal line dealers to compress capital requirements. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape toward low-carbon cold-chain packaging specialists with hydrofluoroolefin-compliant foam-in-place capabilities. Five-to-ten year viability favors converters with backward integration into film extrusion and printing. Monitor state-level extended producer responsibility enactment velocity as the signal for laminate-to-mono-material transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captures margin pools from EVOH barrier layer supply in Germany and Japan. |
| Bio-Based Sealant Layer Development | Anticipates REACH phthalate restrictions while maintaining minus 18 degrees Celsius performance. |
| Vacuum-Sealed Format Capacity Expansion | Serves flash-frozen direct-to-consumer protein brands in North American metropolitan markets. |
| Mono-Material Recyclable Structure Launch | Addresses extended producer responsibility compliance across California and New York state mandates. |
| Cold-Chain Logistics Partnership | Integrates RFID-enabled temperature logging films with German fleet conversion under EU F-Gas Regulation. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with packaging converters, quick-service restaurant procurement directors, and cold-chain logistics operators; and secondary validation through FDA 21 CFR filings, REACH substance restriction updates, EU F-Gas Regulation implementation timelines, and customs trade data on aluminum and resin imports. Bottom-up triangulation across converter capacity disclosures and top-down reconciliation against frozen food production volumes anchored market sizing.
Forecast inputs include packaging type segmentation by thermal performance requirements, material substrate transitions under recyclability mandates, end-user channel rotation toward direct-to-consumer delivery, and closure type adoption curves. CAGRs derive from elasticity modeling against cold-chain infrastructure investment trajectories in China, Germany, and the United States. Segmentation dimensions span format flexibility, barrier intensity, and microwave-ability specifications across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian petrochemical conglomerates would shift outcomes. Cross-checking against SAMR food contact material standard enforcement timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Cupcake Containers Market
Food Packaging
Produce Packaging Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Coffee Capsules and Pod Packaging Market