
 Fast Food Containers Market | 2026-2036
Fast Food Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Food Containers Market Foresight
Cloud kitchen and third-party delivery verticals are rebalancing the buyer mix away from traditional dine-in channels. Pactiv Evergreen leverages its integrated fiber and foam manufacturing footprint to serve both legacy and emerging formats. Huhtamaki anchors its position through molded fiber innovation for hot-food applications. Dart Container specializes in insulated foam solutions while navigating regulatory phase-outs in multiple state-level jurisdictions.
Fast food containers are engineered receptacles—typically constructed from paperboard, expanded polystyrene, polypropylene, or molded pulp—designed to maintain food temperature, structural integrity, and portability during transit from preparation to consumption. Paper-based formats now lead in volume across burger and salad applications as operators respond to consumer preference for perceived sustainability, while plastic clamshells retain dominance in dessert segments where moisture barrier performance commands premium placement. The distribution channel dimension shows food service direct procurement consolidating purchasing power, though online retail intermediaries are gaining traction among independent operators seeking smaller lot sizes.
The EPA oversees municipal solid waste classifications affecting container disposal pathways, while FDA regulations govern food-contact substance migration limits that constrain material substitutions. The EU F-Gas Regulation and REACH chemical restrictions further constrain certain polymer formulations exported into European markets. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification standards to secure compliant supply positions before mandates tighten.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polystyrene foam adoption timelines while fiber-based alternatives scale manufacturing capacity to capture displaced volume. Quick-service operators now face material substitution decisions that ripple through supply contracts and capital allocation.
Growth Catalysts
- Cloud kitchen proliferation:Dark kitchen facilities in India, China, and the United States generate container demand detached from dine-in footprint constraints. These operators prioritize stackability and thermal retention over brand aesthetics.
- REACH chemical restrictions:The EU framework accelerates fluorinated compound phase-outs in grease-resistant coatings. Fiber molders investing in PFAS-free barrier technologies secure preferential supplier status with pan-European chains.
- Dual carbon goals:China's national emissions targets pressure domestic quick-service brands to document packaging lifecycle impacts. Molded pulp suppliers with verified carbon accounting gain procurement priority.
Market Restraints
- Fluctuating pulp feedstock costs:Softwood and recycled fiber prices swing with energy and logistics inputs. Container converters lack pricing power to pass through volatility to locked quick-service contracts.
- Barrier performance gaps:Fiber-based formats struggle with extended hot-hold applications exceeding twenty minutes. Operators retain plastic clamshells for fried protein segments where structural integrity under steam pressure matters.
- Extended producer responsibility mandates:France, Germany, and Italy impose per-container fees funding waste infrastructure. Compliance costs compress margins for exporters serving multiple national schemes.
Strategic Opportunities
- Underpenetrated rural India:Tier-three and tier-four cities lack organized quick-service presence. First-mover container suppliers establishing distribution partnerships with emerging regional chains capture formative procurement relationships.
- Smart packaging integration:QR-enabled containers linking to traceability data and reordering interfaces. Early deployments by premium burger operators in the United States test consumer engagement lift against unit cost premiums.
- Compostable certification alignment:BPI and OK Compost HOME standards unlock municipal composting access. Suppliers achieving dual certification expand addressable market beyond industrial composting infrastructure limits.
Industry Challenges
- Thermal engineering talent scarcity:Fiber insulation design for hot-food applications requires materials science expertise concentrated in packaging engineering programs. Quick-service procurement teams struggle to evaluate competing thermal performance claims.
- Legacy equipment retrofit costs:Converting foam-forming lines to fiber molding demands capital outlay and extended downtime. Mid-scale operators defer transitions despite regulatory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Food Containers Market |
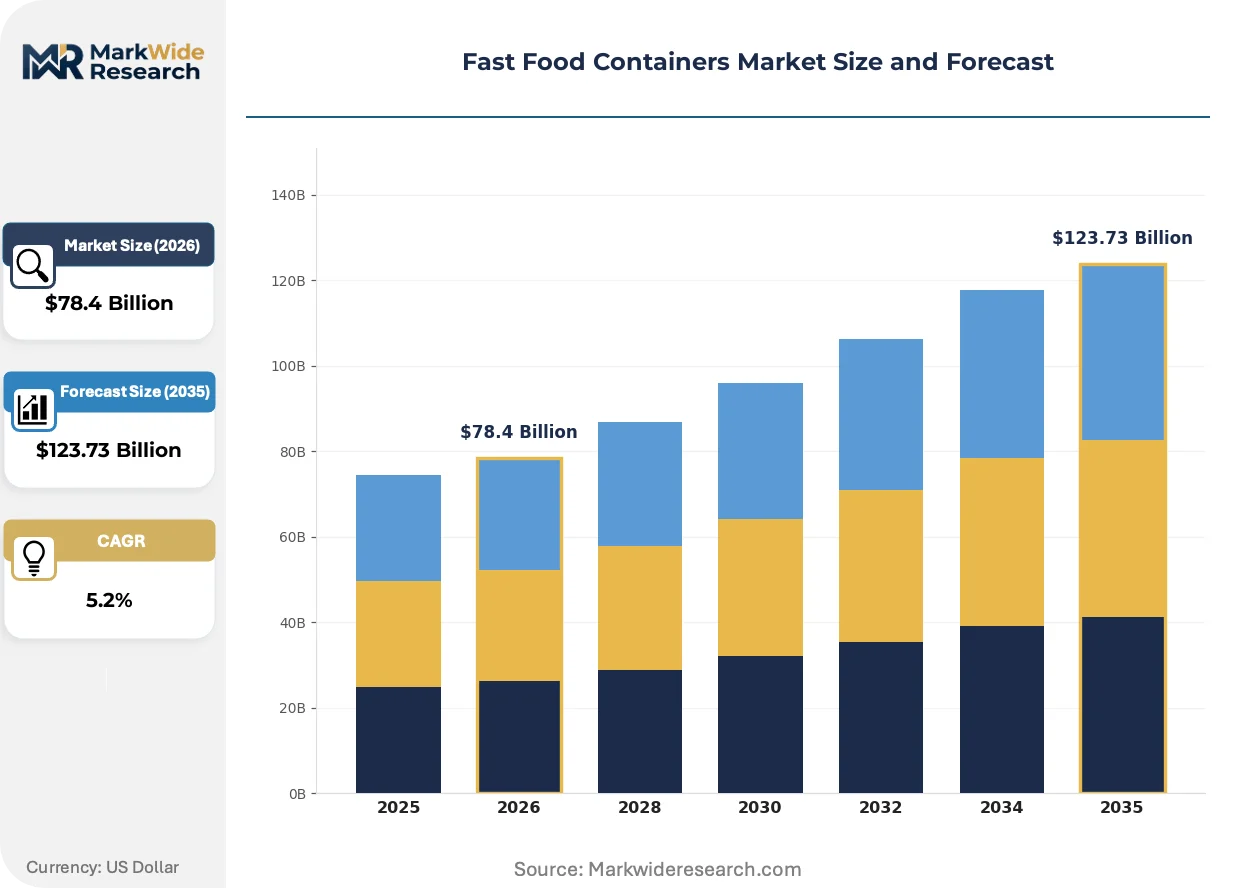
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Burgers, Salads, Wraps, Desserts Material: Plastic, Paper, Foam, Aluminum Size: Small, Medium, Large, Extra Large Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Amcor plc, International Paper, WestRock Company, Pactiv Evergreen, Dart Container, Graphic Packaging International, Berry Global, Sealed Air, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Food Containers Market Shifts & Advancements
Material science breakthroughs and regulatory enforcement timelines are compressing product development cycles. Container suppliers now prototype barrier coatings and structural designs in parallel rather than sequential phases.
Barrier coating automation is automating precision application of water-based and bio-wax formulations onto molded fiber surfaces. Quick-service chains in Germany and the Netherlands specify these formats for burger and sandwich applications where grease resistance previously mandated plastic liners. The technology is automating quality consistency that previously required manual inspection, reducing defect rates and enabling thinner substrate weights without performance sacrifice.
The EU F-Gas Regulation constrains certain polymer blowing agents used in insulated foam production. Manufacturers serving European export markets reformulate with hydrocarbon alternatives or pivot capacity toward fiber-based thermal solutions. Cold-chain dessert and beverage segments feel the strongest pressure, as operators balance regulatory compliance against established cold-retention performance benchmarks.
Digital procurement platforms are fragmenting buyer power across independent quick-service operators. Smaller chains and franchisees in Brazil and Mexico bypass traditional distributor relationships to source containers through B2B marketplaces offering lot-size flexibility. This channel shift concentrates price transparency and compresses switching costs, forcing incumbent suppliers to defend position through logistics integration rather than relationship tenure.
Fast Food Containers Market Segmentation
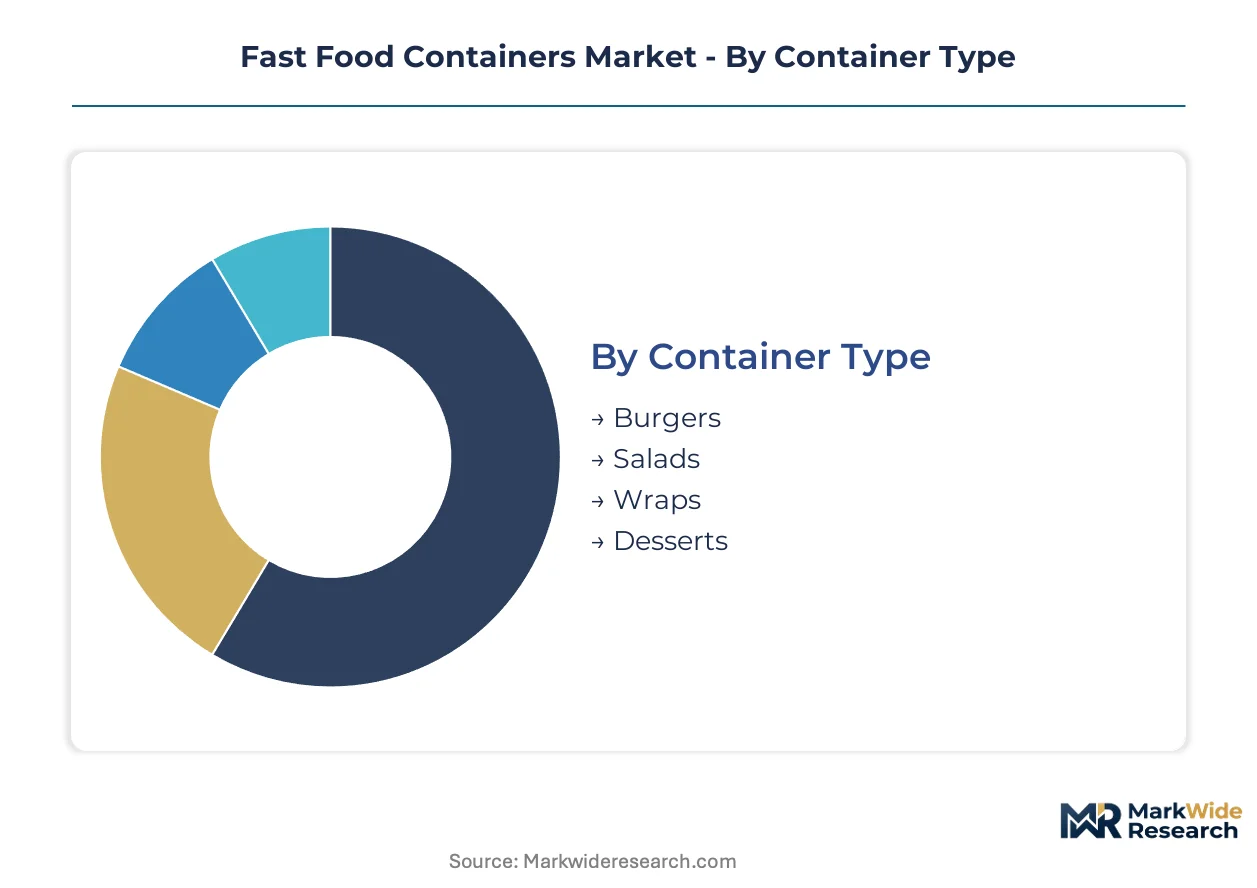
Container specifications diverge sharply across food formats, with thermal retention requirements and grease resistance dictating material selection. Procurement patterns cluster around format-specific performance benchmarks rather than commodity pricing.
Container Type:
Structural rigidity requirements vary dramatically by food category, driving capital allocation toward specialized forming equipment and barrier coating lines.
- Burgers:Engineered for stacked presentation and grease containment, these containers integrate vented lids and absorbent liners. Quick-service chains in the United States specify molded pulp formats with PFAS-free coatings to meet state-level disclosure mandates.
- Salads:Clear-view windows dominate premium positioning, though fiber-based alternatives with cellulose film windows are displacing plastic clamshells in European markets subject to EPP fees.
- Wraps:Flat, fold-resistant designs prioritize stackability for delivery aggregation. Cloud kitchen operators in India favor lightweight paperboard sleeves with minimal structural reinforcement.
- Desserts:Moisture barrier performance commands plastic retention in frozen and cream-based applications despite regulatory pressure on polystyrene foam in dessert cup formats.
Most installed capacity flows through Burgers. Expansion is steepest in Wraps.
Material:
Feedstock price volatility and regulatory phase-out timelines determine manufacturing margin stability across substrate categories.
- Plastic:Polypropylene and PET dominate dessert and cold-chain segments where clarity and moisture barrier are non-negotiable. FDA migration limits constrain recycled content integration, limiting circularity claims.
- Paper:Recycled fiber and virgin kraft grades lead burger and sandwich applications. EU REACH restrictions on fluorinated grease barriers accelerate investment in bio-wax and clay coating alternatives.
- Foam:Expanded polystyrene retains cost advantage in insulated applications though state-level bans in California, New York, and Maine compress addressable geography.
- Aluminum:Premium hot-hold formats for catering and airline channels leverage thermal conductivity and reusability credentials. Higher unit costs restrict penetration in value-oriented quick-service.
Paper commands the largest production footprint. Aluminum is climbing the fastest as premium positioning accelerates.
Size:
Equipment tooling amortization favors standardized dimension runs, though customization pressure from branded meal bundles complicates capacity planning.
- Small:Side dish and condiment portions. High velocity, low margin, minimal differentiation.
- Medium:Standard single-serve entrees. Volume concentration enables longest production runs and lowest unit conversion costs.
- Large:Family-size and combo meal formats. Demand concentrates in suburban and drive-through channels.
- Extra Large:Catering and group ordering. Seasonal demand spikes require flexible scheduling or outsourced fulfillment.
Medium formats absorb the majority of machine-hour allocation. Large formats are gaining share fastest through bundled meal promotions.
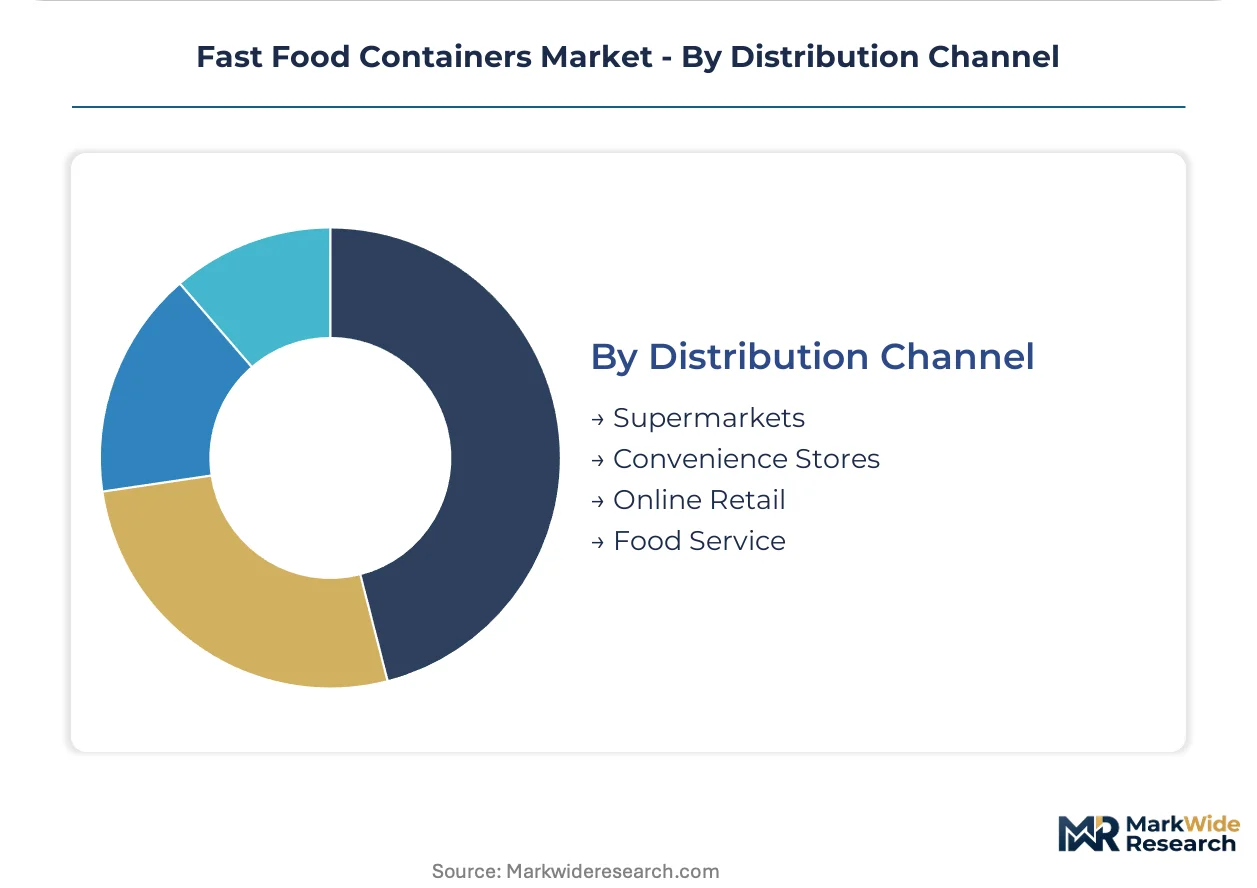
Distribution Channel:
Channel selection determines lot-size economics, with direct food service procurement consolidating volumes that independent operators fragment across intermediaries.
- Supermarkets:Retail-ready formats for deli and prepared food counters. Packaging must withstand shelf-facing durability standards and consumer handling.
- Convenience Stores:Grab-and-go specifications prioritize one-handed opening and microwave compatibility. Smallest lot sizes per SKU challenge supplier minimums.
- Online Retail:B2B marketplaces in Brazil and Mexico aggregate fragmented independent demand. Price transparency compresses switching costs and relationship premiums.
- Food Service:Direct procurement by quick-service chains and contract foodservice operators. Specifications lock in multi-year with penalty structures for non-compliance.
Food Service channels concentrate the heaviest contract volumes. Online Retail is expanding most quickly as digital procurement penetrates tier-two and tier-three markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity as producers seek jurisdictions with favorable compliance costs and feedstock access. Container converters now site facilities to minimize exposure to extended producer responsibility fees and carbon border adjustments.
United States
Quick-service chains in Texas and Florida are expanding drive-through formats that demand stackable, thermally efficient packaging. The FDA governs food-contact substance migration limits that constrain material substitutions in burger and fried protein segments. Atlanta and Dallas-Fort Worth anchor the strongest procurement clusters as regional chains consolidate distribution through foodservice direct channels.
China
Cloud kitchen proliferation in Shanghai and Shenzhen generates container demand detached from dine-in footprint constraints. The country's dual carbon goals pressure domestic quick-service brands to document packaging lifecycle impacts. The Yangtze River Delta concentrates molded pulp manufacturing capacity as suppliers invest in verified carbon accounting to secure procurement priority.
Germany
Quick-service operators face REACH chemical restrictions accelerating fluorinated compound phase-outs in grease-resistant coatings. The EU F-Gas Regulation constrains certain polymer blowing agents used in insulated foam production. The Rhine-Ruhr industrial corridor hosts fiber molders investing in PFAS-free barrier technologies to secure preferential supplier status with pan-European chains.
India
Tier-three and tier-four cities lack organized quick-service presence, creating formative procurement opportunities for first-mover container suppliers. The FSSAI oversees food packaging safety standards that emerging regional chains must navigate. Bangalore and Hyderabad anchor cloud kitchen density as digital food ordering platforms penetrate deeper into southern markets.
Brazil
Independent quick-service operators bypass traditional distributor relationships to source containers through B2B marketplaces offering lot-size flexibility. The country's national pharmaceutical regulator analog sets baseline safety expectations for food-contact materials. São Paulo and Rio de Janeiro concentrate demand as price transparency compresses switching costs and relationship premiums.
Fast Food Containers Market Competitive Landscape
Capacity expansion dominates the current landscape as fiber-based alternatives scale manufacturing to capture volume displaced by polystyrene foam phase-outs. The vendor base clusters around three tiers: integrated multinational converters with captive pulp supply, regional specialists in molded fiber forming, and commodity traders serving price-sensitive independents. Strategic archetypes include sustainability-forward innovators pursuing compostable certification alignment and scale-driven operators defending position through logistics integration. M&A activity concentrates on acquiring PFAS-free coating capabilities, while geographic expansion targets underpenetrated tier-three and tier-four markets in India and Southeast Asia.
Among integrated multinational converters, Pactiv Evergreen and Huhtamaki exemplify archetypes balancing legacy foam manufacturing with emerging fiber capacity. Pactiv Evergreen leverages its integrated fiber and foam footprint to serve both formats. Huhtamaki anchors its position through molded fiber innovation for hot-food applications. Dart Container occupies a distinct tier specializing in insulated foam solutions while navigating regulatory phase-outs in multiple state-level jurisdictions.
| Leading Market Players |
|---|
| Amcor plc |
| International Paper |
| WestRock Company |
| Pactiv Evergreen |
| Dart Container |
| Graphic Packaging International |
| Berry Global |
| Sealed Air |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
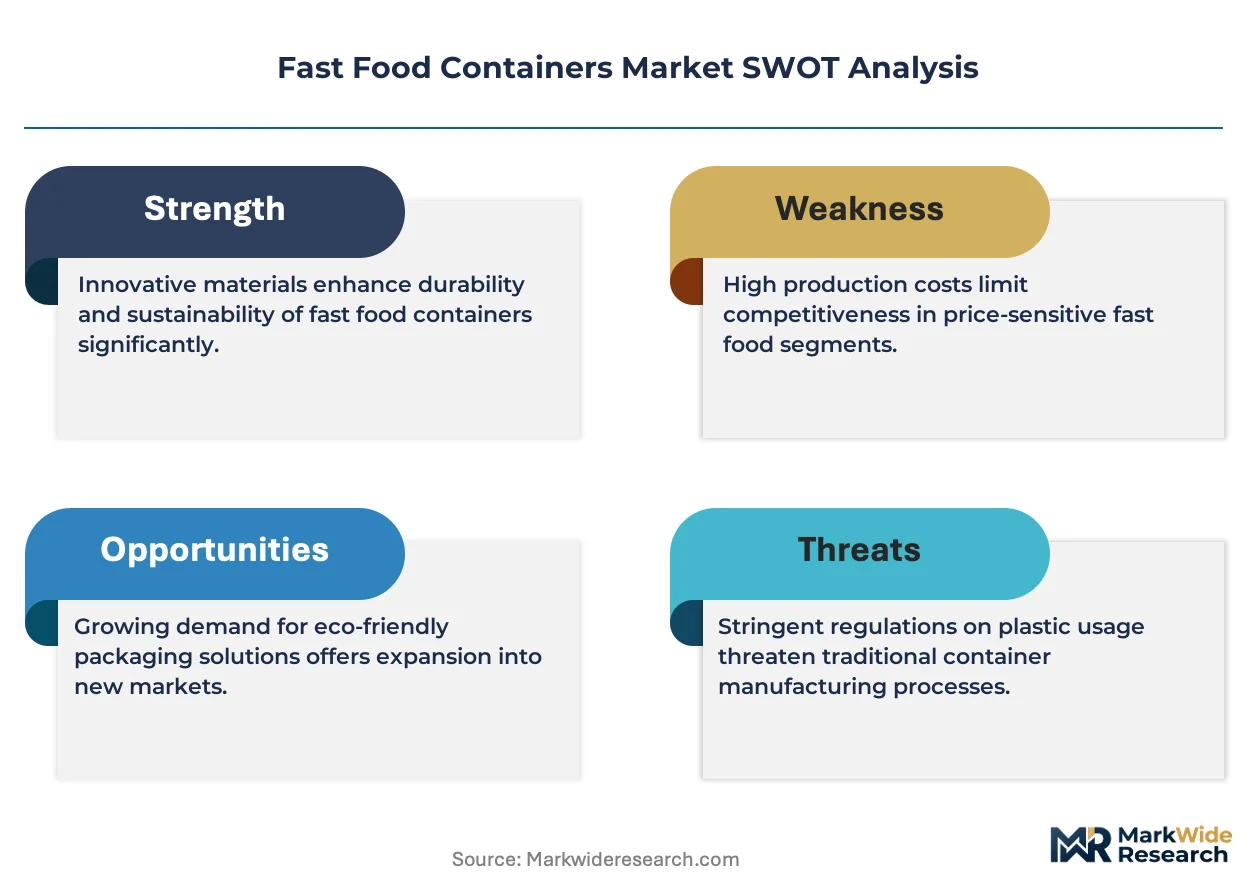
Captive pulp supply integration anchors both manufacturing resilience and contract pricing power for container converters serving multi-year quick-service agreements. Fiber molders with backward control over recycled feedstock streams buffer margin erosion from pulp price volatility that converters locked into spot purchasing cannot pass through.
Pricing Analysis
Distributor margin compression in the food service direct channel intensifies as digital procurement platforms fragment buyer power among independent operators. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance tier, with BPI-certified compostable formats commanding placement premiums. Cost compression in fiber-based segments is intensifying because quick-service chains consolidate purchasing through multi-year contracts with penalty structures. Franchisees and cloud kitchen operators exhibit the highest price sensitivity, while pan-European chains prioritize PFAS-free barrier compliance over unit cost.
Supply Chain Analysis
Returns and post-consumer fiber recovery flows remain underdeveloped for food-contact applications, constraining closed-loop feedstock access. Manufacturing concentration centers on China, the United States, and Germany, with the Yangtze River Delta and Rhine-Ruhr corridor hosting specialized molded pulp capacity. Feedstock supply draws from softwood pulp, recycled OCC grades, and agricultural residue streams. Single-source vulnerability in PFAS-free barrier coating chemistries threatens format substitution timelines. Distribution runs through foodservice direct procurement for large chains, while B2B marketplaces fragment independent operator demand in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications in thermal retention and grease resistance are displacing commodity purchasing as cloud kitchen operators prioritize performance consistency over lowest-unit-cost sourcing.
For Market Incumbents: Extend PFAS-free coating capabilities through acquisition or in-house R&D before REACH enforcement timelines harden. Add molded pulp capacity in the Yangtze River Delta to capture procurement priority from Chinese quick-service brands documenting carbon lifecycle impacts. Defend against fiber-based entrants by locking multi-year contracts with penalty structures that freeze switching economics. For New Entrants and Emerging Players: Begin with tier-three and tier-four Indian cities where organized quick-service presence remains sparse and procurement relationships are formative. Target cloud kitchen operators in Bangalore and Hyderabad who prioritize stackability and thermal retention over brand aesthetics. Pursue BPI and OK Compost HOME dual certification to unlock municipal composting access beyond industrial infrastructure limits. For Investors and Strategic Acquirers: Roll-up economics work for regional molded fiber specialists because extended producer responsibility mandates in France, Germany, and Italy are compressing margins for exporters serving multiple national schemes. The five-to-ten-year viability window favors suppliers with verified carbon accounting and captive pulp supply. Watch for EU F-Gas Regulation enforcement tightening as the inflection signal for hydrocarbon-blown foam capacity obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier Technology Investment | REACH chemical restrictions accelerate fluorinated compound phase-outs in European markets. |
| Cloud Kitchen Distribution Partnership | Dark kitchen facilities in India and China generate demand detached from dine-in constraints. |
| Dual Compostable Certification Alignment | BPI and OK Compost HOME standards unlock municipal composting infrastructure access. |
| Backward Integration into Recycled Fiber Supply | Captive pulp supply buffers margin erosion from softwood and OCC price volatility. |
| Smart Packaging QR Integration | Premium burger operators in the United States test consumer engagement lift against unit cost premiums. |
Research Methodology
Direct dialogue with quick-service procurement directors, molded fiber plant managers, foodservice distribution channel heads, and sustainability compliance officers grounded qualitative findings. Secondary validation drew from FDA food-contact substance filings, EPA municipal solid waste classifications, EU ECHA REACH substance restrictions, and customs trade data for pulp and container imports. Bottom-up volume builds across container type, material, and size segments triangulated against top-down market sizing from foodservice expenditure flows.
Segment-level demand projections across the analysis window incorporate container specifications by food format, regulatory phase-out timelines for polystyrene foam, and cloud kitchen penetration rates by metropolitan cluster. CAGRs derive from weighted average growth across material substitution scenarios and geographic demand concentration. Modeled inputs include pulp feedstock price elasticity, extended producer responsibility fee structures by jurisdiction, and thermal performance benchmarking for fiber-based alternatives.
Several conditions sit outside the modeled scope, including abrupt shifts in FDA migration limits, unilateral state-level foam bans ahead of federal alignment, and breakthrough barrier coatings that eliminate thermal performance gaps. Forecasts reflect assumptions about enforcement consistency for EU Single-Use Plastics Directive timelines and Chinese dual carbon goal implementation pacing. Practitioners should monitor pulp futures volatility, composting infrastructure buildout rates, and quick-service chain consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Cereal Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Meal Kit Packaging Market