
 Burger Boxes Market | 2026-2036
Burger Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Burger Boxes Market Intelligence
Buyer concentration among quick service restaurants is expanding as global chains consolidate procurement under centralized sustainability mandates. Huhtamaki Group leverages its molded fiber technology leadership to supply biodegradable formats for major QSR accounts. WestRock Company anchors North American supply through integrated containerboard and converting assets. Smurfit Kappa Group competes with regional corrugated specialization across European foodservice channels.
Burger boxes are rigid or semi-rigid containers engineered from corrugated board, solid bleached sulfate, or molded pulp with grease-resistant coatings, designed to maintain structural integrity and food temperature during transport from kitchen to consumer. Cardboard and paper materials dominate volume due to established recycling infrastructure and cost efficiency, while eco-friendly segments attract premium positioning as QSR chains adopt plastic reduction commitments. Custom print designs command higher margins through brand differentiation, whereas standard formats remain the volume baseline for value-oriented operators.
The EU Single-Use Plastics Directive and FDA food contact substance regulations shape material compliance requirements across major markets, with REACH and GB standards adding chemical safety layers for coating and adhesive components. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling certifications as procurement criteria tighten across multinational restaurant chains.
Market Dynamics
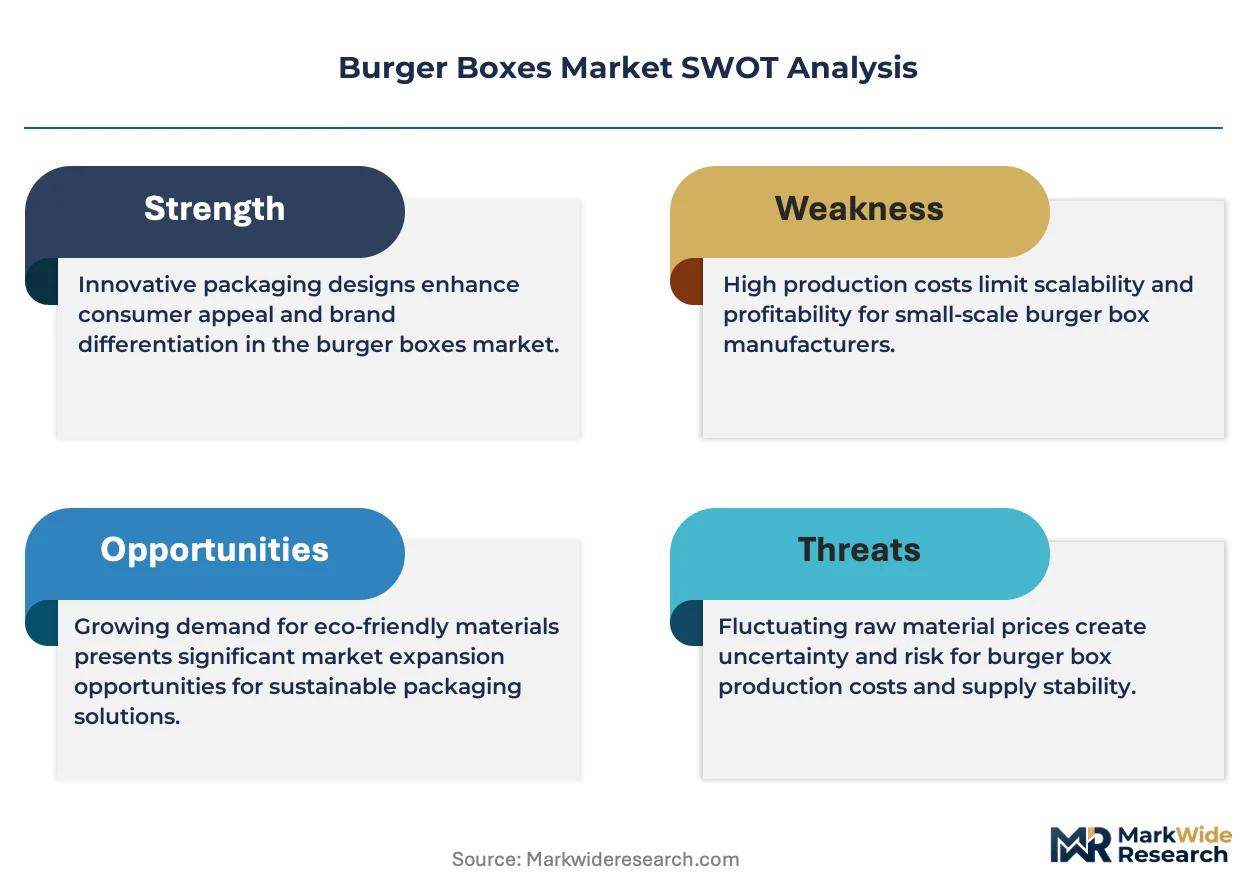
Quick service restaurant procurement consolidation is compressing supplier margins while mandating biodegradable material transitions, forcing converters to retool coating and forming lines for grease-resistant molded fiber at industrial scale.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on expanded polystyrene food containers is redirecting QSR volume toward corrugated and molded pulp alternatives, with Germany and France enforcing the strictest compliance timelines.
- Molded fiber thermoforming:Advances in high-speed fiber molding are cutting unit costs for biodegradable boxes, enabling price parity with plastic-coated paperboard in high-volume contracts.
- QSR sustainability mandates:Global chains including McDonald's and Burger King have committed to 100% renewable packaging by 2025, creating guaranteed offtake for certified compostable formats.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft pulp contracts swing 15-30% annually, squeezing converter margins on fixed-price QSR supply agreements.
- Barrier coating supply concentration:PFAS-free grease-resistant chemistries rely on three dominant specialty chemical suppliers in the US and Germany, creating bottleneck risk for compliant material.
- Composting infrastructure gaps:Industrial composting facilities remain sparse in Eastern Europe and rural North America, undermining the end-of-life value proposition for biodegradable boxes.
Strategic Opportunities
- India QSR expansion:Domino's and KFC are adding 500+ outlets annually in tier-2 cities, creating first-mover advantage for local corrugated converters with FSSAI-certified food contact materials.
- Reusable container programs:Loop-style circular packaging pilots in France and the UK are testing deposit-return burger boxes for dine-in and delivery aggregation platforms.
- Digital print integration:Single-pass inkjet on corrugated is enabling micro-batch customization for limited-time menu promotions, opening premium pricing tiers previously reserved for flexo-printed folding carton.
Industry Challenges
- Food contact migration testing:Validating PFAS-free barrier coatings for FDA and EFSA compliance requires 12-18 month certification cycles, delaying product launches for reformulated substrates.
- Legacy forming asset obsolescence:Converters with 1980s-era die-cutters and folder-gluers face $2-4 million replacement costs to handle thinner, lower-basis-weight molded fiber stocks without cracking.
- Cross-functional sustainability talent:Shortage of packaging engineers with simultaneous expertise in polymer chemistry, pulp mechanics, and life-cycle assessment is throttling R&D throughput at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burger Boxes Market |
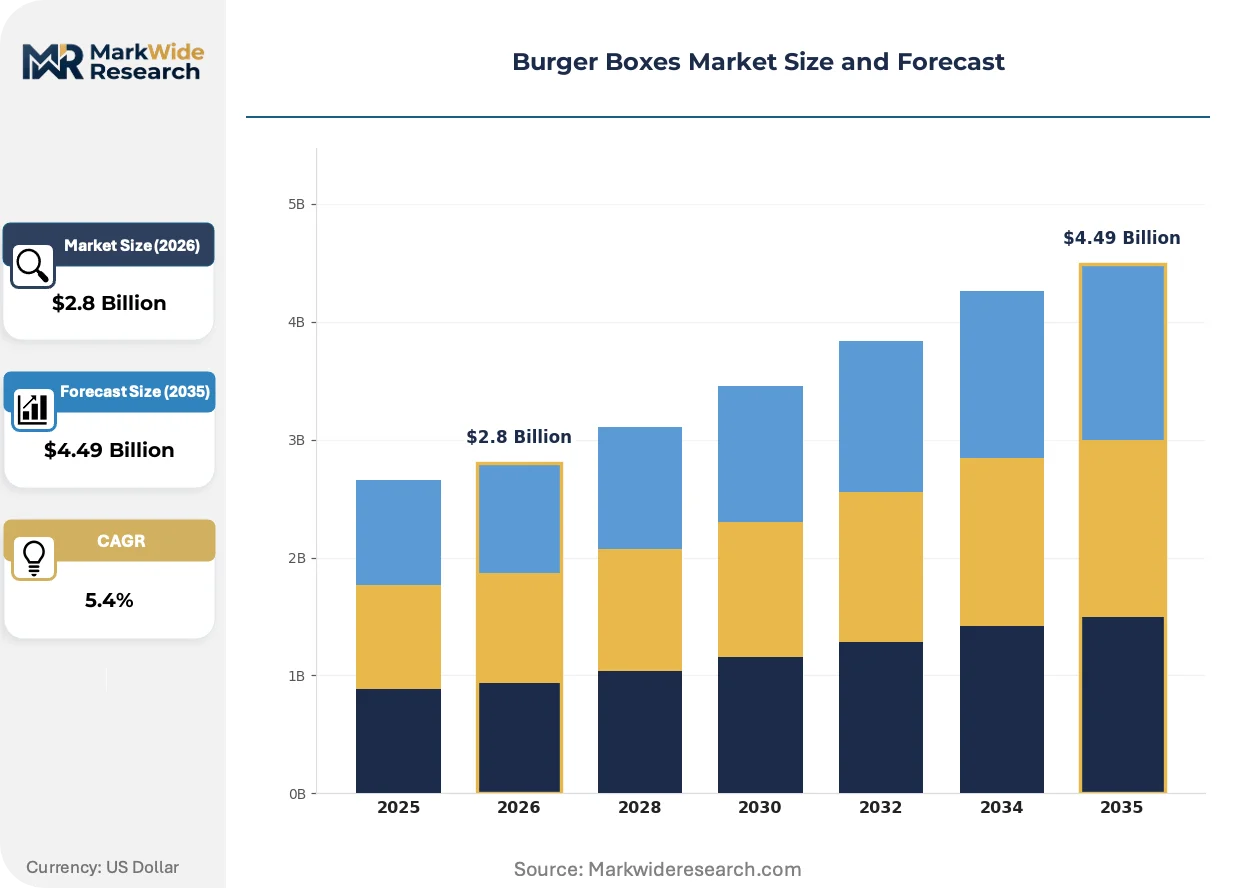
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Paper, Plastic, Eco-friendly Product Size: Small, Medium, Large, Jumbo End User: Quick Service Restaurants, Food Trucks, Catering Services, Retail Outlets Design Type: Standard, Custom Print, Biodegradable, Insulated |
| Companies Covered | Huhtamaki Group, WestRock Company, Smurfit Kappa Group, Graphic Packaging International, Sealed Air Corporation, International Paper Company, Georgia-Pacific LLC, Dart Container Corporation, Novolex Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burger Boxes Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory enforcement are compressing the transition timeline from plastic-dependent foodservice packaging to fiber-based systems, with coating innovation outpacing forming equipment capacity.
Barrier-coated molded fiber is unifying grease resistance and structural rigidity in single-material burger boxes, eliminating the polyethylene lamination that blocks standard recycling streams. QSR procurement teams in Germany and the Netherlands are specifying this format for 60% of new packaging contracts. The technology is unifying previously separate supply chains for paperboard and plastic into integrated fiber converting operations.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy fluorinated grease barriers from European food contact materials by 2026. Industrial consequence includes accelerated R&D spending on bio-wax and clay-based alternatives by coating chemical suppliers. Burger box converters in Poland and Spain are most affected, with many scrambling to qualify alternative barriers before the sunset clause activates.
Centralized sustainability procurement is consolidating purchasing authority from regional QSR operators to global headquarters, compressing supplier rosters from dozens to three-to-five approved partners per region. Regional distributors and independent converters are being displaced by direct contracts between multinational chains and tier-one packaging groups. This pattern is most visible in the Nordics, where McDonald's and Max Hamburgers have consolidated 80% of burger box volume under two suppliers.
Burger Boxes Market Segmentation
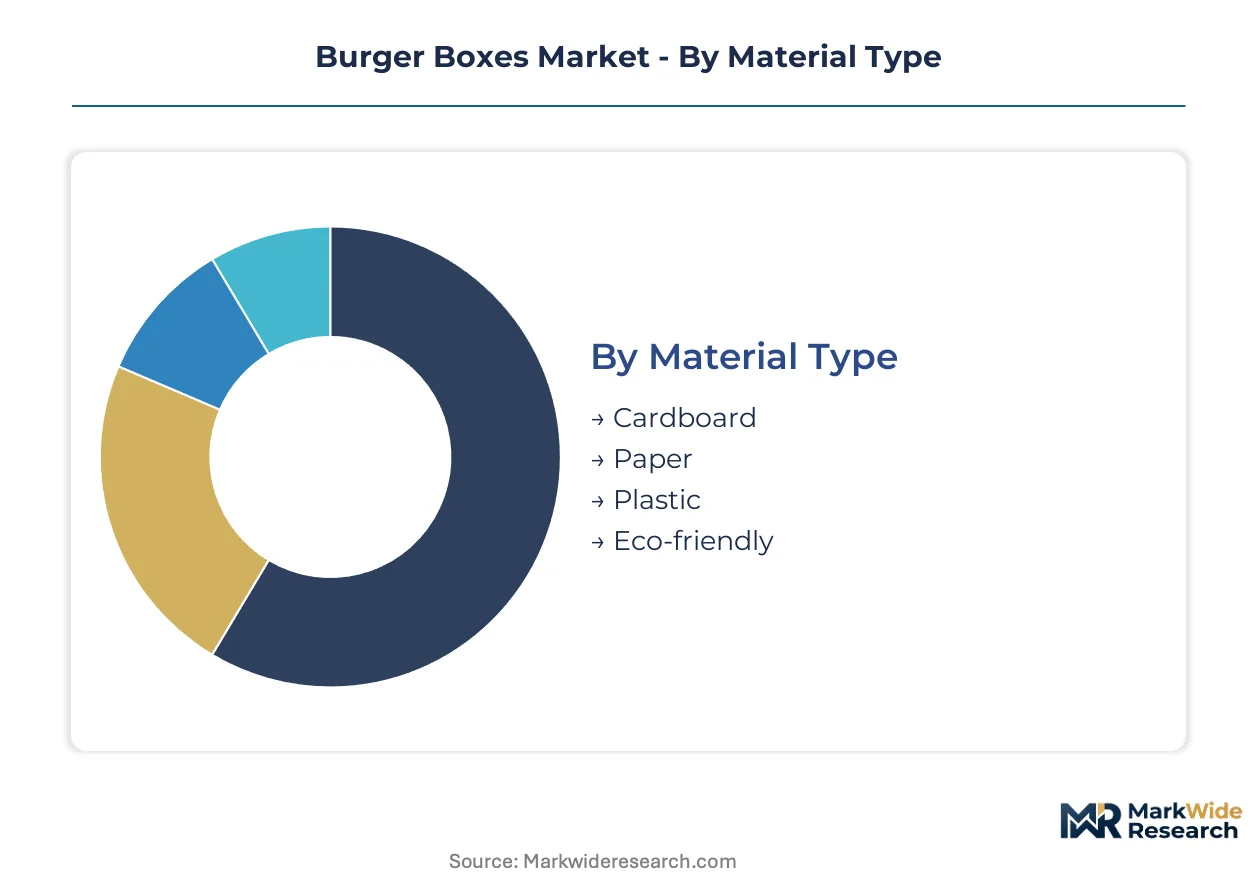
Burger box procurement patterns diverge sharply by material performance and operational scale. Quick service restaurants calibrate specifications across multiple dimensions simultaneously—thermal retention, grease resistance, unit economics, and brand visibility—to match kitchen throughput and delivery logistics.
Material Type:
Upgrade cycles in material specification are accelerating as chains phase out legacy formats ahead of regulatory deadlines. Converters must requalify coating chemistries and forming processes for each substrate transition.
- Cardboard:Corrugated board with clay-coated or polyethylene-laminated surfaces dominates high-volume QSR contracts. Germany and France are enforcing the strictest compliance timelines under the EU Single-Use Plastics Directive, redirecting volume toward fiber alternatives.
- Paper:Solid bleached sulfate and folding carton grades serve premium positioning with superior print fidelity. McDonald's and Burger King have committed to renewable packaging mandates, creating guaranteed offtake for certified paper-based formats.
- Plastic:Expanded polystyrene and polypropylene containers persist in markets with weaker enforcement infrastructure. REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy fluorinated barriers from European food contact materials.
- Eco-friendly:Molded pulp with bio-wax or clay-based grease barriers commands premium positioning in sustainability-led procurement. Industrial composting facilities remain sparse in Eastern Europe and rural North America, undermining end-of-life value propositions.
Volume placements concentrate in cardboard; the faster expansion belongs to eco-friendly.
Product Size:
Menu engineering and portion standardization drive size mix across operator types. Chains optimize box dimensions for kitchen line speed, delivery bag density, and waste minimization.
- Small:Single-patty and slider formats for value-menu positioning and children's meals. Food trucks in dense urban clusters favor compact sizes for handheld consumption.
- Medium:Standard sandwich configurations represent the procurement baseline for most QSR systems. Catering services specify medium boxes for mixed-portion buffet layouts.
- Large:Double-patty and premium builds require structural reinforcement against compression. Quick service restaurants in India are adding outlets in tier-2 cities, scaling large-format demand for localized portion preferences.
- Jumbo:Family-sharing and combo-meal configurations with partitioned interiors. Limited-time promotional campaigns drive intermittent jumbo-volume spikes.
Procurement volume clusters in medium; large formats are climbing the fastest on international expansion.
End User:
Customer operational model dictates durability requirements, order frequency, and customization depth. Each channel imposes distinct constraints on supply chain configuration.
- Quick Service Restaurants:Centralized procurement mandates from global headquarters compress supplier rosters to three-to-five approved partners per region. McDonald's and Max Hamburgers in the Nordics have consolidated 80% of burger box volume under two suppliers.
- Food Trucks:Mobile operators prioritize space-efficient nesting and rapid turnover compatibility. FDA food contact substance regulations shape material compliance for imported formats.
- Catering Services:Event-based demand requires batch flexibility and short-run customization capability. Digital print integration is enabling micro-batch production for limited-time menu promotions.
- Retail Outlets:Grocery and convenience channels specify retail-ready packaging with shelf-appeal graphics. Extended producer responsibility frameworks are tightening procurement criteria across multinational retail chains.
Supply concentration sits with quick service restaurants; catering services are gaining share fastest on event-volume recovery.
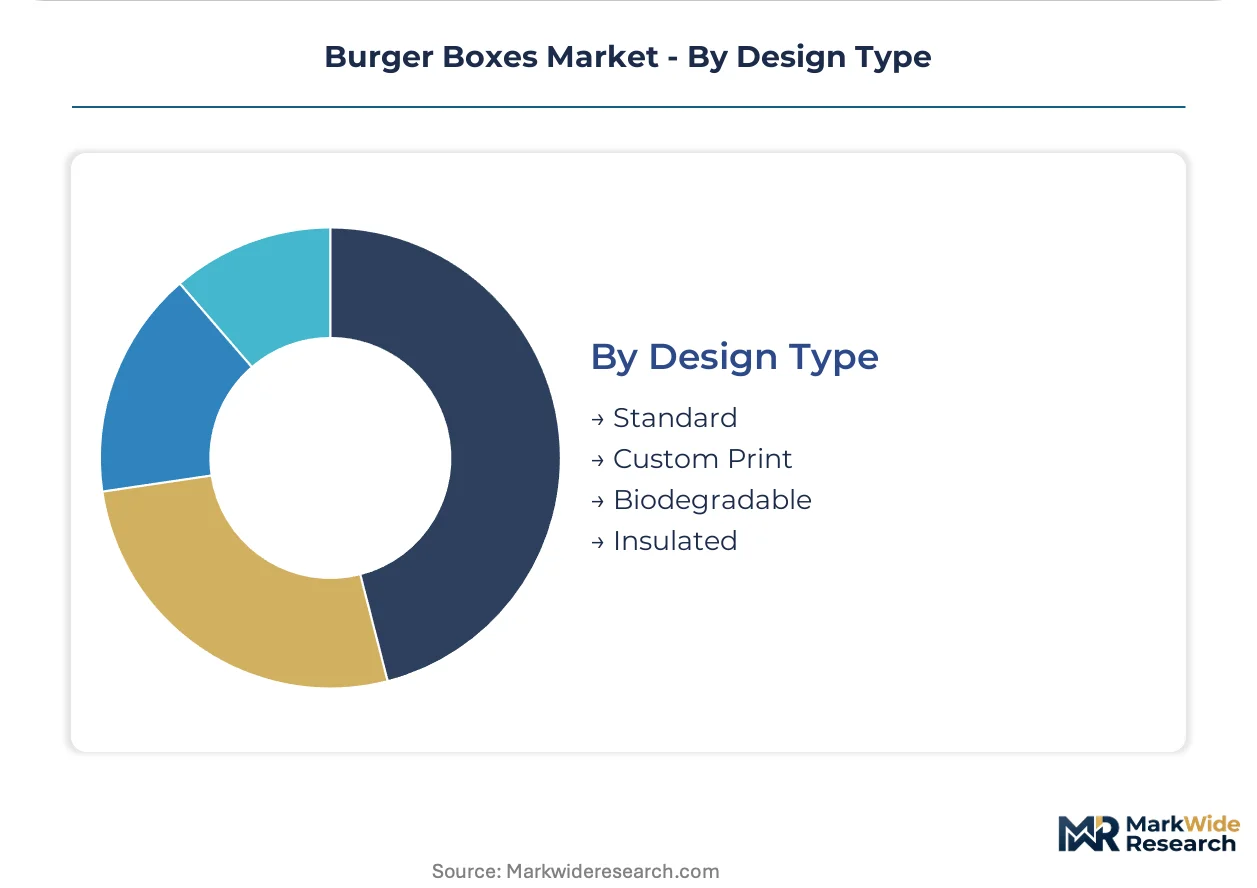
Design Type:
Functional specification and brand expression trade off against unit cost in design selection. Chains balance operational standardization against promotional differentiation.
- Standard:Unprinted or generic-print formats minimize inventory complexity for value-oriented operators. Standard designs remain the volume baseline across price-sensitive markets.
- Custom Print:Flexo and single-pass inkjet decoration enable brand storytelling and limited-edition campaigns. Custom designs command higher margins through differentiation previously reserved for folding carton.
- Biodegradable:Certified compostable formats with PFAS-free barriers satisfy sustainability procurement mandates. Food contact migration testing for FDA and EFSA compliance requires 12-18 month certification cycles, delaying launches.
- Insulated:Double-wall or foam-lined constructions maintain temperature for extended delivery windows. Insulated formats attract premium positioning in third-party delivery aggregation channels.
Standard designs anchor volume; biodegradable formats show the steepest expansion trajectory on regulatory enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick service restaurant chains concentrate procurement authority in Germany, compressing supplier rosters and accelerating sustainable packaging transitions. Regulatory enforcement varies sharply across national jurisdictions, creating divergent compliance timelines for material substitutions.
Germany
McDonald's Deutschland and Burger King have consolidated 80% of burger box volume under two approved suppliers. The country's national packaging regulator enforces the EU Single-Use Plastics Directive with the strictest compliance timelines in Europe. Hamburg anchors molded fiber converting capacity as Huhtamaki Group and Smurfit Kappa Group retool lines for grease-resistant biodegradable formats.
France
Max Hamburgers and Quick chain operators are specifying barrier-coated molded fiber for 60% of new packaging contracts. ECHA restrictions on per- and polyfluoroalkyl substances are eliminating legacy fluorinated barriers by 2026. Paris hosts Loop-style circular packaging pilots testing deposit-return burger boxes for delivery aggregation platforms.
United States
WestRock Company anchors North American supply through integrated containerboard assets serving McDonald's and Wendy's centralized procurement. FDA food contact substance regulations shape migration testing requirements for PFAS-free barrier coatings. Chicago and Atlanta concentrate QSR headquarters procurement teams mandating renewable packaging commitments.
India
Domino's and KFC are adding 500+ outlets annually in tier-2 cities, scaling demand for FSSAI-certified food contact materials. The national food safety regulator mandates compliance certification for imported packaging substrates. Mumbai and Bangalore clusters attract first-mover corrugated converters establishing localized supply relationships.
Poland
Converters scramble to qualify alternative grease barriers before REACH sunset clauses activate. The national chemical regulator enforces ECHA restrictions on fluorinated coatings affecting legacy forming assets. Warsaw and Krakow industrial zones concentrate mid-tier suppliers facing $2-4 million equipment replacement costs for molded fiber compatibility.
Burger Boxes Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biodegradable specialization and digital print integration. The vendor base compresses around three-to-five approved partners per regional QSR procurement zone. Two strategic archetypes dominate: integrated paperboard conglomerates with captive pulp supply, and molded fiber specialists with thermoforming scale. Competitive moves concentrate on coating chemistry partnerships and high-speed forming asset acquisitions.
Within the integrated conglomerate tier, WestRock Company and International Paper Company exemplify scale-driven positioning through containerboard and converting assets. Among European specialists, Smurfit Kappa Group occupies a position anchored by regional corrugated specialization across foodservice channels. Huhtamaki Group represents the molded fiber technology leadership archetype supplying biodegradable formats for major QSR accounts.
| Leading Market Players |
|---|
| Huhtamaki Group |
| WestRock Company |
| Smurfit Kappa Group |
| Graphic Packaging International |
| Sealed Air Corporation |
| International Paper Company |
| Georgia-Pacific LLC |
| Dart Container Corporation |
| Novolex Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Quick service restaurant procurement consolidation concentrates buying power among three-to-five approved suppliers per region, forcing contract-based long-term offtake agreements with fixed-price clauses that expose converters to raw material volatility. This buyer concentration shifts pricing power upstream to pulp and coating chemical suppliers while compressing converter margins on biodegradable format transitions.
Pricing Analysis
Volume placements cluster in standard cardboard formats at economy pricing tiers, while custom-print and biodegradable segments command premium-mid-economy pricing differentiation based on certification grade and customization depth. Pricing pressure stems from fixed-price QSR contracts confronting 15-30% annual pulp price swings, squeezing converter margins most acutely on molded fiber lines. Value-oriented operators exhibit highest price sensitivity, whereas sustainability-committed chains absorb premiums for PFAS-free certified formats.
Supply Chain Analysis
Dual-sourcing requirements from McDonald's and Burger King procurement teams mandate multi-supplier qualification across molded fiber and corrugated categories, preventing single-source dependence despite vendor roster compression. Manufacturing concentrates in Germany, the United States, and India, with raw material supply anchored in Nordic bleached softwood kraft pulp and specialty barrier coatings from German and US chemical suppliers. Single-source vulnerability sits with PFAS-free grease-resistant chemistry suppliers, while distribution runs through direct contracts between multinational chains and tier-one packaging groups, displacing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The burger box market occupies a technology-transition phase as barrier-coated molded fiber displaces polyethylene-laminated paperboard, driven by EU regulatory enforcement and QSR sustainability mandates.
For Market Incumbents: Cement coating chemistry partnerships with PFAS-free barrier suppliers to lock in compliant material access before REACH sunset clauses activate. Add thermoforming capacity in Germany and India to capture QSR procurement consolidation. Defend against emerging molded fiber specialists by acquiring high-speed forming assets and qualifying multiple barrier chemistries simultaneously. For New Entrants and Emerging Players: Begin with tier-2 Indian cities where Domino's and KFC expansion outpaces local corrugated converter capacity, creating first-mover advantage for FSSAI-certified operations. Target catering services and food trucks as least penetrated channels with batch-flexibility requirements ill-served by mass-scale incumbents. Pursue digital print integration as the go-to-market angle for micro-batch limited-time promotions. For Investors and Strategic Acquirers: The window for entry favors molded fiber specialists with qualified PFAS-free barriers and existing QSR supplier relationships. Long-term viability hinges on coating chemistry access and thermoforming scale rather than legacy paperboard assets. Watch for ECHA enforcement acceleration as the inflection signal that compresses non-compliant supplier timelines and triggers distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Partnership | Secures PFAS-free grease resistance access ahead of REACH restrictions affecting European converters. |
| Thermoforming Capacity Expansion | Enables industrial-scale molded fiber production at cost parity with plastic-coated paperboard. |
| Digital Print Integration | Opens micro-batch customization for QSR limited-time promotions previously reserved for flexo. |
| India Localized Supply | Captures FSSAI-certified demand from 500+ annual outlet additions by Domino's and KFC. |
| Reusable Container Pilot | Tests Loop-style deposit-return systems for delivery aggregation platforms in France and UK. |
Research Approach
Document review covered trade association filings, customs records, and regulatory enforcement databases, complemented by interviews with QSR procurement directors, packaging converter plant managers, and barrier coating R&D leads. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, ECHA restriction timelines, and FSSAI certification records. Bottom-up volume modeling triangulated against top-down market sizing across material type, product size, and end user segments.
Output projections span the analysis window across cardboard, paper, plastic, and eco-friendly material categories, with further disaggregation by small through jumbo product sizes and quick service restaurant, food truck, catering, and retail end users. CAGRs derive from regression against QSR outlet expansion rates, regulatory phase-in schedules, and pulp price elasticity coefficients. Forecast inputs incorporate molded fiber thermoforming yield improvements and PFAS-free barrier coating adoption curves.
Underlying measurement precision varies by segment; established cardboard and paper categories carry tighter precision than emerging biodegradable formats where composting infrastructure gaps create demand uncertainty. Forecasts reflect assumptions on EU enforcement consistency and QSR sustainability commitment durability. Deviation in ECHA restriction timelines or pulp price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Produce Packaging Market