
 Drink Carrier and Trays Market | 2026-2036
Drink Carrier and Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Drink Carrier and Trays Market Analytics
Modular multi-cup configurations is consolidating as the dominant design pattern across foodservice procurement, replacing simple single-cup sleeves with stackable, handle-integrated carriers that reduce delivery spillage and improve brand visibility. Huhtamaki leverages its molded fiber expertise to supply major European and North American quick-service accounts with compostable carrier lines. WestRock Company anchors the North American corrugated segment through integrated containerboard-to-converted-product operations. Graphic Packaging competes aggressively in the printed, retail-ready carrier niche with high-speed converting assets.
Drink carriers and trays are rigid or semi-rigid packaging structures engineered to secure, transport, and present multiple beverage containers simultaneously, typically fabricated from corrugated paperboard, molded pulp, or thermoformed plastics with specified load-bearing capacities of two to six cups and integrated handles or apertures for manual portability. Their primary commercial purpose is to enable safe, efficient beverage distribution in away-from-home consumption channels while serving as a mobile branding surface. Cardboard dominates unit volume across most geographies due to cost parity and established recycling infrastructure, though eco-friendly materials represent the fastest-expanding material class as foodservice operators face mounting Scope 3 emissions scrutiny. Multi-compartment carriers command premium positioning relative to single-served trays, reflecting their operational efficiency in delivery-centric formats where consolidation reduces per-delivery packaging counts and labor handling.
The U.S. Food and Drug Administration governs food-contact substances in drink carrier substrates through 21 CFR regulations, while the EPA's recycled content guidelines shape procurement specifications for federal foodservice contracts; in Europe, EFSA food-contact material opinions and the EU Packaging and Packaging Waste Regulation collectively mandate recyclability and recycled content thresholds that redirect R&D spending toward fiber-based formulations. Stakeholders must monitor evolving extended producer responsibility fee structures and substrate-specific bans, as these mechanisms will determine which material technologies achieve scalable cost competitiveness against incumbent plastic formats.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand toward fiber-based substrates, forcing converters to retool lines and foodservice operators to requalify suppliers across their procurement portfolios.
Growth Catalysts
- Quick-service delivery expansion:Major coffeehouse and fast-casual chains are scaling takeout operations, driving high-volume procurement of branded, handle-integrated carriers designed for spillage reduction during transport.
- Compostable material mandates:The EU Packaging and Packaging Waste Regulation is redirecting R&D spending toward molded pulp formulations that meet recyclability thresholds across member states.
- Scope 3 emissions scrutiny:Foodservice operators face mounting pressure from corporate sustainability targets to displace conventional plastics with certified fiber alternatives in beverage packaging.
Market Restraints
- Pulp fiber cost volatility:Recycled containerboard and molded pulp feedstock prices fluctuate with OCC collection rates and energy costs, compressing converter margins during supply tightness.
- Extended producer responsibility fees:Emerging EPR structures in European and North American jurisdictions impose per-unit levies that disadvantage smaller converters lacking scale to absorb compliance costs.
- Performance limitations of fiber substrates:Molded pulp carriers exhibit inferior moisture resistance versus thermoformed plastics, restricting adoption in high-humidity climates and extended delivery routes.
Strategic Opportunities
- Underpenetrated Indian foodservice:Organized quick-service chains in India are expanding drive-through and delivery formats, creating first-mover positioning for compostable carrier suppliers meeting BIS packaging standards.
- Retail-ready printed carriers:Supermarket and convenience store channels are adopting branded beverage carriers as impulse-display vehicles, opening volume outside traditional foodservice procurement.
- Smart packaging integration:RFID-enabled carriers for order tracking and temperature monitoring are converging with last-mile logistics platforms, enabling premium pricing in high-value delivery segments.
Industry Challenges
- Food-contact certification timelines:FDA 21 CFR and EFSA opinion processes for novel fiber formulations extend 18-24 months, delaying product launches and locking capital in unqualified inventory.
- Legacy equipment reconfiguration:Converters must retrofit thermoforming and die-cutting assets originally engineered for plastic substrates to handle variable-thickness molded pulp without yield degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drink Carrier and Trays Market |
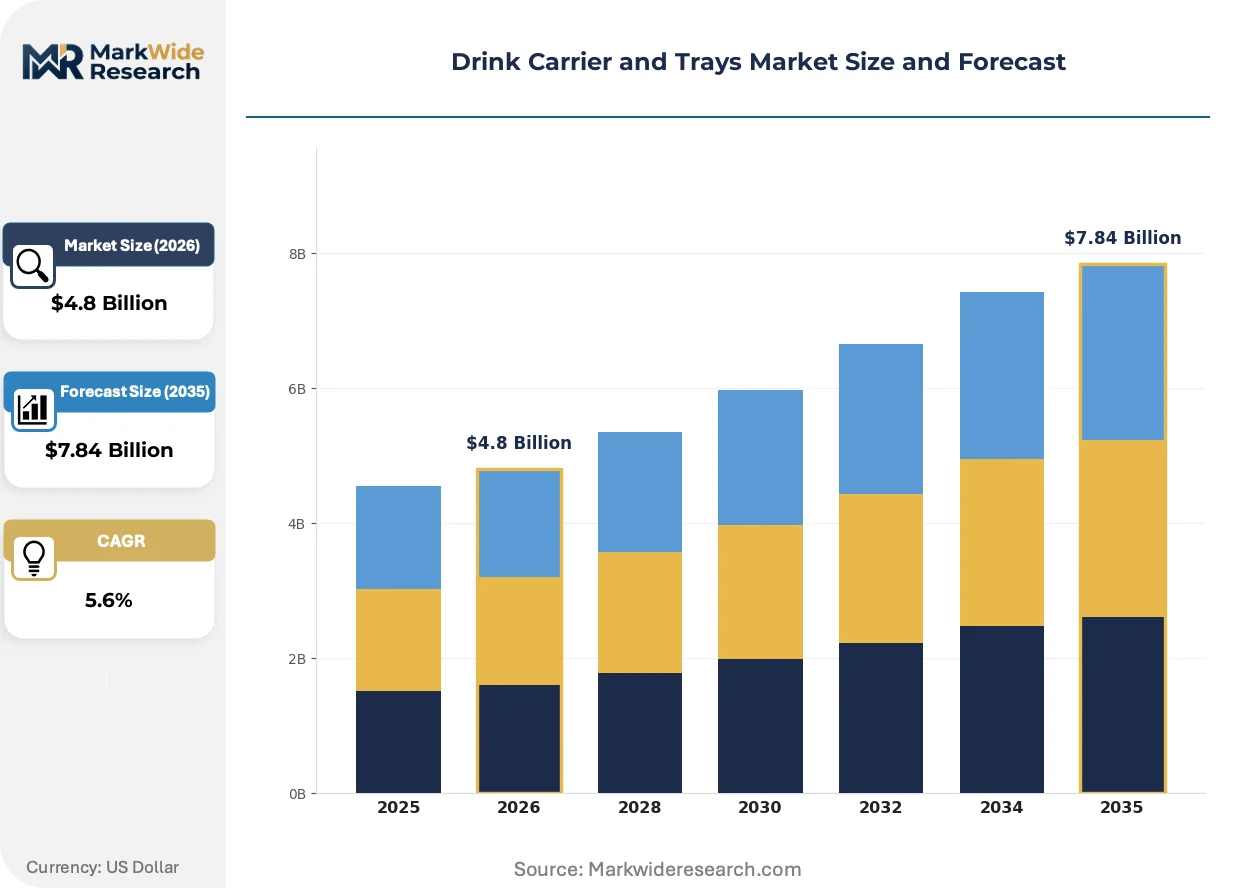
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cardboard, Plastic, Wood, Eco-friendly Materials Design Type: Single-Served Trays, Multi-Compartment Carriers, Stackable Trays, Custom Designs End User: Cafes, Restaurants, Fast Food Chains, Event Caterers Distribution Channel: Online Retailers, Wholesale Distributors, Supermarkets, Direct Sales |
| Companies Covered | Huhtamaki, WestRock Company, Graphic Packaging, Amcor plc, Genpak, Pactiv, Mondi Group, Crown Holdings, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drink Carrier and Trays Market Evolving Landscape
Active innovation clusters center on material science breakthroughs, regulatory compliance automation, and procurement model restructuring that together redefine competitive positioning in beverage transport packaging.
Molded fiber production technology is converging with advanced water-removal pressing systems that enable thinner-wall, higher-strength carriers without sacrificing compostability. European quick-service chains are adopting these platforms at pilot scale. The structural consequence is compressing cost parity timelines between fiber and incumbent plastic formats by eliminating drying-energy penalties.
REACH substance restrictions and the EU Single-Use Plastics Directive are forcing reformulation of barrier coatings and adhesive systems in fiber-based carriers. Industrial consequence includes supplier consolidation as only integrated pulp-to-converted-product operations can certify full-chain compliance. The printed, retail-ready carrier segment is responding fastest, leveraging high-speed converting assets to offset compliance-driven cost premiums.
Consolidated procurement by multi-brand restaurant groups is displacing fragmented, outlet-level purchasing. National account managers at major chains now mandate standardized carrier specifications across franchise networks, compressing supplier rosters. This concentration is most visible in the United States, where three coffeehouse and fast-casual holding companies account for disproportionate volume allocation.
Drink Carrier and Trays Market Segmentation
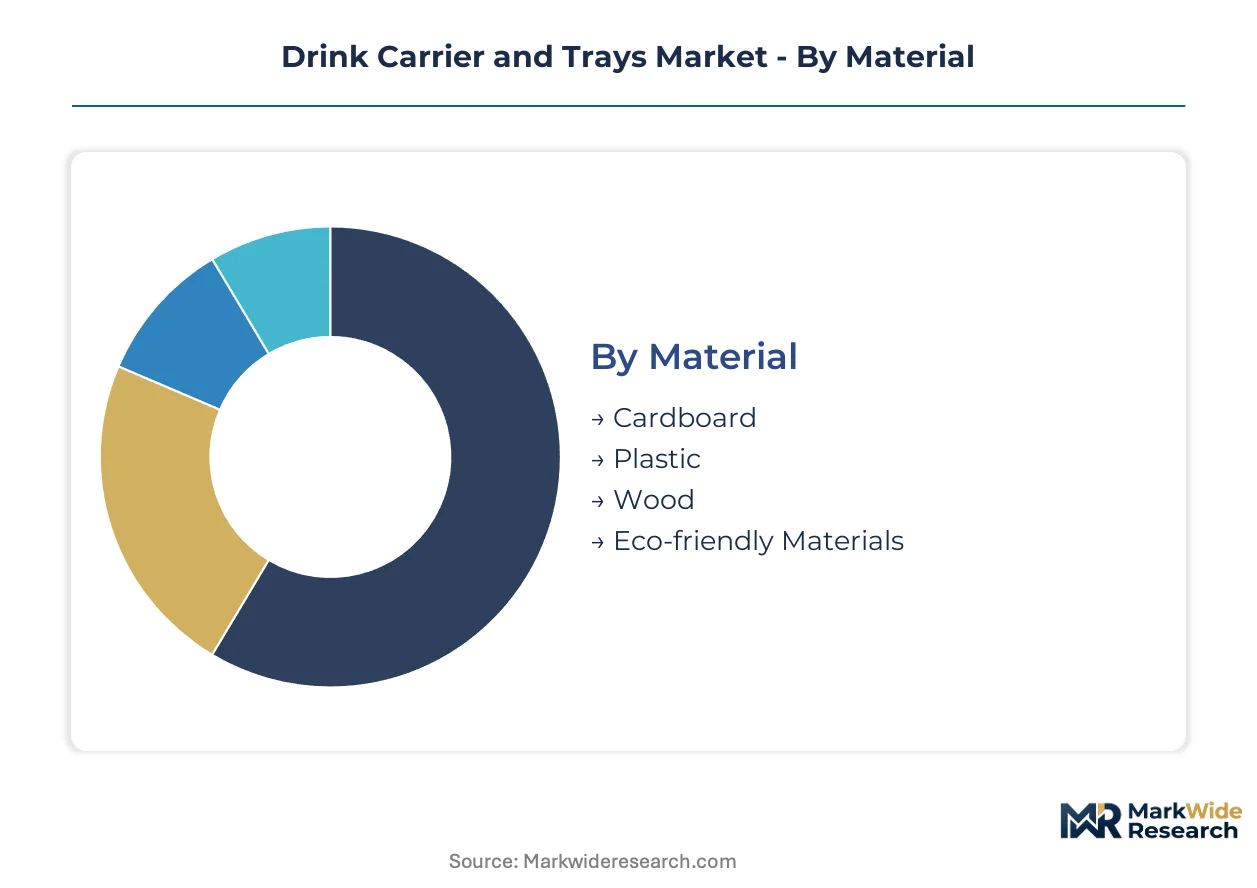
Material composition determines regulatory compliance pathways and cost structures for drink carriers, while design architecture shapes operational efficiency in delivery-centric foodservice formats. Procurement patterns diverge sharply across end-user channels, with quick-service chains prioritizing volume-standardized specifications against event caterers seeking seasonal flexibility.
Material:
Converters differentiate buyers by their sustainability certification requirements and tolerance for substrate cost volatility.
- Cardboard:Corrugated paperboard and solid bleached sulfate grades dominate unit volumes through established recycling infrastructure and FDA 21 CFR food-contact compliance. Quick-service chains in the United States specify this substrate for branded carrier programs, though OCC collection rate fluctuations compress converter margins during supply tightness.
- Eco-friendly Materials:Molded pulp and agricultural fiber formulations are redirecting R&D spending as the EU Single-Use Plastics Directive accelerates fiber-based adoption. European quick-service accounts now mandate compostable lines, with EFSA food-contact opinions required for novel formulations extending qualification timelines.
- Plastic:Thermoformed PET and PP carriers retain moisture resistance advantages in high-humidity climates, though REACH substance restrictions and extended producer responsibility fees disadvantage smaller converters lacking scale.
- Wood:Specialty hardwood and bamboo derivatives serve premium café and catering segments requiring tactile differentiation, with limited scalable supply constraining mass-market penetration.
Cardboard leads volumes today; eco-friendly materials are gaining share fastest.
Design Type:
Operational format—delivery versus on-premise consumption—determines structural load-bearing and handle-integration priorities.
- Multi-Compartment Carriers:Stackable configurations with integrated handles and four-to-six cup capacities command premium positioning in delivery-centric formats. Major coffeehouse chains specify these for spillage reduction during transport, consolidating procurement around standardized aperture spacing.
- Single-Served Trays:Simple sleeve structures with minimal material throughput serve cost-sensitive outlets and individual beverage transactions. Fast-casual chains deploy these for grab-and-go counters where consolidation efficiency matters less than unit economics.
- Stackable Trays:Nesting geometries optimize storage density for high-volume catering operations and centralized commissary distribution.
- Custom Designs:Die-cut retail-ready carriers with high-resolution printing serve supermarket impulse-display channels outside traditional foodservice procurement.
Multi-compartment carriers anchor foodservice procurement; custom designs are expanding most quickly into retail channels.
End User:
Volume scale and brand standardization intensity separate national account opportunities from fragmented outlet-level purchasing.
- Fast Food Chains:Consolidated procurement by multi-brand holding companies mandates standardized carrier specifications across franchise networks, compressing supplier rosters. Three coffeehouse and fast-casual operators in the United States account for disproportionate volume allocation.
- Cafes:Independent and small-chain coffeehouses prioritize tactile branding and premium material differentiation, accepting higher per-unit costs for custom-printed, handle-integrated carriers.
- Restaurants:Full-service operators with takeout expansion programs are requalifying suppliers for fiber-based alternatives under corporate Scope 3 emissions targets.
- Event Caterers:Seasonal demand spikes and format variability favor flexible sourcing relationships over long-term supply contracts.
Fast food chains concentrate procurement volumes; cafes are driving specification innovation fastest.
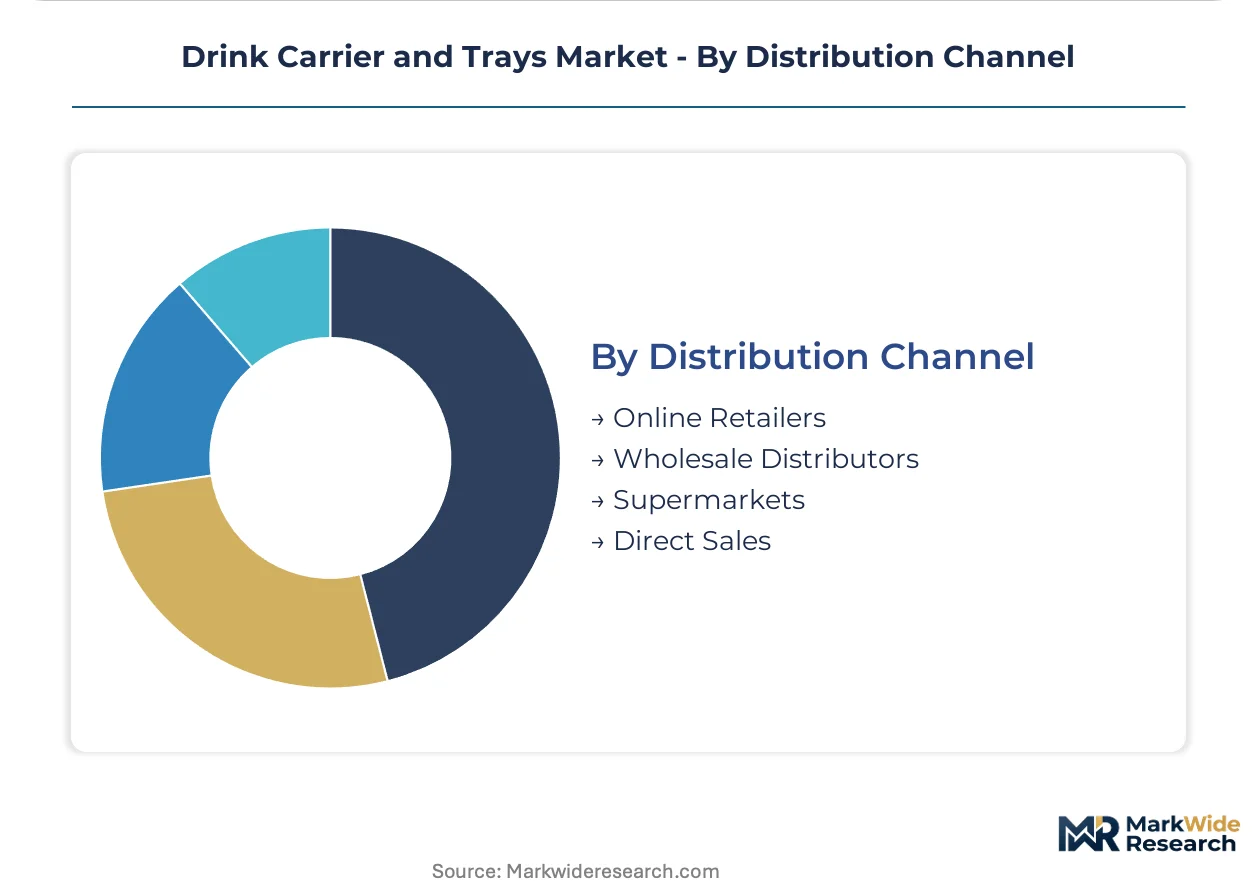
Distribution Channel:
Buyer technical sophistication and order fragmentation determine margin capture and service model requirements.
- Wholesale Distributors:Broadline foodservice distributors aggregate fragmented outlet demand, capturing volume through inventory availability and logistics integration rather than technical specification support.
- Direct Sales:National account managers at major converters engage directly with multi-brand restaurant groups, mandating standardized specifications and locking in multi-year supply agreements.
- Online Retailers:E-commerce platforms serve small-format operators and event caterers with minimum-order-quantity flexibility, though shipping costs erode competitiveness against local distribution.
- Supermarkets:Retail channels are adopting branded beverage carriers as impulse-display vehicles, opening volume outside traditional foodservice procurement with printed, retail-ready specifications.
Wholesale distributors move the highest unit volumes; direct sales channels are climbing the fastest as procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The molded fiber drink carrier industry traces its commercial origins to mid-20th century North American foodservice packaging innovation, with corrugated paperboard carriers first achieving scale through quick-service restaurant expansion in the United States. From this foundation, production expertise diffused to Europe and Asia-Pacific through converter licensing agreements and equipment exports. Today, regulatory divergence and supply chain localization have created distinct regional competitive dynamics.
United States
Major coffeehouse chains and fast-casual holding companies drive high-volume procurement of branded, handle-integrated carriers for delivery operations. FDA 21 CFR regulations govern food-contact substrates, while EPA recycled content guidelines shape federal foodservice contract specifications. The Southeast manufacturing corridor—spanning Georgia and the Carolinas—hosts integrated containerboard-to-converted-product operations serving national quick-service accounts.
Germany
Quick-service chains are requalifying suppliers for compostable carrier lines under corporate Scope 3 emissions targets and EPR fee structures. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that redirect procurement toward molded pulp formulations. The North Rhine-Westphalia industrial cluster around Düsseldorf and Cologne concentrates converter operations with EFSA-certified food-contact capabilities.
China
Export-oriented molded fiber equipment manufacturers supply pressing and drying systems to converters worldwide, while domestic demand concentrates in tier-one city coffeehouse expansion. GB standards and SAMR food-contact regulations govern substrate compliance for both domestic use and export production. The Yangtze River Delta region—Shanghai, Jiangsu, Zhejiang—hosts the densest concentration of molded pulp machinery fabricators and substrate suppliers.
India
Organized quick-service chains are expanding drive-through and delivery formats, creating first-mover positioning for compostable carrier suppliers meeting BIS packaging standards. FSSAI food-contact regulations and DGFT import substitution policies favor domestic substrate production over imported alternatives. The Maharashtra-Gujarat industrial corridor anchors emerging converter capacity serving quick-service accounts in Mumbai, Pune, and Ahmedabad.
Japan
Premium café segments prioritize tactile branding and material differentiation in carrier procurement, accepting higher per-unit costs for custom specifications. METI circular economy guidelines and JIS standards shape substrate selection toward domestically recyclable fiber formulations. The Kanto region—Tokyo and surrounding prefectures—concentrates specialty converter operations serving high-end coffeehouse and convenience store channels.
Drink Carrier and Trays Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-converted-product operations with multi-jurisdictional compliance certification. Tier-one converters with captive molded fiber production and high-speed printing assets capture disproportionate share in consolidated national account procurement. Three archetypes dominate: integrated fiber specialists with full-chain certification, corrugated converters leveraging containerboard integration, and diversified packaging multinationals with cross-substrate portfolios. Capacity expansion and geographic licensing agreements constitute the dominant competitive moves as converters seek to replicate EFSA- and FDA-qualified production across regions.
Among integrated fiber specialists, Huhtamaki and WestRock Company exemplify the scale-driven archetype with established quick-service supply relationships. Graphic Packaging occupies a position within the printed, retail-ready carrier segment where high-speed converting assets offset compliance-driven cost premiums. These three anchors demonstrate how regulatory certification breadth and equipment scale separate tier-one suppliers from fragmented regional competitors.
| Leading Market Players |
|---|
| Huhtamaki |
| WestRock Company |
| Graphic Packaging |
| Amcor plc |
| Genpak |
| Pactiv |
| Mondi Group |
| Crown Holdings |
| DS Smith |
| Others |
Value Network & Pricing Analysis
Consolidated procurement by multi-brand restaurant groups is forcing converters to absorb compliance-driven cost premiums while maintaining contract competitiveness, compressing margins across fiber-based production lines and accelerating supplier roster consolidation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with EFSA-certified compostable carriers commanding substantial premiums over conventional corrugated alternatives. Price differentiation hinges on certification grade and volume scale, with national quick-service accounts extracting favorable terms through multi-year offtake commitments. Cost compression in the standard tier is intensifying because OCC collection rate volatility feeds directly into containerboard input costs. Event caterers and small-format cafes exhibit highest price sensitivity, while fast-casual chains with consolidated procurement tolerate premium positioning for branded, handle-integrated specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese molded fiber equipment manufacturers who supply pressing and drying systems to converters across North America and Europe. Production gravity centers on the United States, Germany, and China, with the Yangtze River Delta anchoring machinery fabrication and the Southeast US manufacturing corridor hosting integrated containerboard-to-converted-product operations. Raw material dependencies draw from OCC collection networks, virgin pulp supply, and barrier coating formulations. Tariff exposure on imported machinery and substrate inputs constitutes the dominant structural risk. Distribution runs through wholesale foodservice distributors aggregating fragmented outlet demand alongside direct national account channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPR fee differentials between European and North American jurisdictions create cost-advantaged positioning for converters with multi-jurisdictional compliance certification.
For Market Incumbents: Extend EFSA- and FDA-qualified production footprints through geographic licensing agreements rather than greenfield capacity, defending against emerging fiber-specialist entrants by locking multi-brand restaurant groups into standardized specification contracts. Backward integration into captive molded pulp production secures margin control during OCC supply tightness. For New Entrants and Emerging Players: Capture first-mover positioning in India's organized quick-service expansion by meeting BIS packaging standards ahead of multinational converter licensing, targeting drive-through and delivery format growth in Mumbai and Pune. A direct sales model engaging national account managers at holding companies outperforms distributor-dependent approaches. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated fiber specialists possessing full-chain certification and high-speed printing assets, as procurement consolidation favors tier-one suppliers with regulatory breadth. The long-term viability window favors acquisition targets with established quick-service relationships and multi-region compliance infrastructure. Watch EPR fee implementation timelines in North American jurisdictions as the inflection signal for fiber-substrate cost parity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molded Pulp Production | Captive fiber supply insulates margins from OCC volatility and accelerates EFSA qualification timelines. |
| Geographic Licensing Agreement | Replication of FDA-certified production across Southeast Asia addresses tariff exposure on Chinese equipment imports. |
| Multi-Jurisdictional Compliance Certification | Dual EFSA-FDA capabilities unlock consolidated procurement by multi-brand restaurant groups spanning Europe and North America. |
| High-Speed Converting Asset Deployment | Advanced die-cutting and printing infrastructure offsets compliance-driven cost premiums in retail-ready carrier segments. |
| Direct National Account Engagement | Bypassing wholesale distributors captures margin and locks standardized specifications across franchise networks. |
Research Methodology
Direct dialogue with converter operations managers, national account procurement leads at quick-service chains, foodservice distributor category buyers, and regulatory affairs specialists at packaging multinationals grounded the qualitative assessment. Secondary validation drew from FDA 21 CFR filings, EFSA food-contact material opinions, EU Packaging and Packaging Waste Regulation implementation documents, and trade data on OCC collection rates. Bottom-up volume modeling triangulated against top-down market sizing across material, design type, end user, and distribution channel dimensions.
Segment-level value outputs across the projection horizon reflect differential growth assumptions for fiber-based versus plastic substrates under evolving EPR structures. The analytical framework modeled material composition, design architecture, end-user channel, and geographic regulatory cluster as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating quick-service delivery expansion rates and compostable mandate implementation timelines. Forecast inputs included pulp fiber cost indices and quick-service outlet count trajectories by region.
OCC collection rate volatility, EPR fee structure revisions, and food-contact certification timeline extensions are the dominant revision risks that could alter substrate adoption curves and converter margin assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Seafood Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market