
 Food Punnets Market | 2026-2036
Food Punnets Market Size, Share, and Industry Trends Forecast 2026-2036
Food Punnets Market Foresight
France is reshaping European food punnet manufacturing through investments in thermoforming and molded fiber capacity near its major agricultural zones. Smurfit Kappa Group Plc leverages its integrated paperboard supply chain to dominate sustainable tray production across the continent. Groupe Guillin SA anchors its position through deep specialization in rigid plastic and biopolymer clamshells for soft fruit. Berry Global competes by extending its North American extrusion expertise into European dairy and ready-to-eat meal formats.
Food punnets are rigid or semi-rigid containers, typically manufactured through thermoforming, injection molding, or pressed fiber processes, with wall thicknesses ranging from 0.3 mm to 1.2 mm depending on produce weight and stacking requirements. Their primary commercial purpose is to protect, display, and ventilate perishable foods through retail distribution while enabling barcode labeling and automated handling. Plastic punnets still occupy the largest value share but face margin compression from regulatory fees, while biodegradable polymers represent the fastest-expanding material category as brand owners commit to packaging reduction targets. Within applications, fresh produce generates the dominant volume flow, though ready-to-eat meals command higher per-unit prices due to multi-compartment tray complexity and extended shelf-life barrier requirements.
The EU Green Deal and its Packaging and Packaging Waste Regulation, enforced through national agencies such as France's ANSES and Germany's UBA, are mandating recycled content minimums and extended producer responsibility fees that directly alter material selection economics. REACH compliance and emerging microplastic restrictions from ECHA further constrain conventional polymer formulations, pushing converters toward certified compostable alternatives or fiber-based structures. Stakeholders must monitor how rapidly evolving national implementation timelines for reuse and recycling targets will force capital reallocation between retrofitting existing thermoforming lines and building entirely new pulp molding capacity.
Market Dynamics
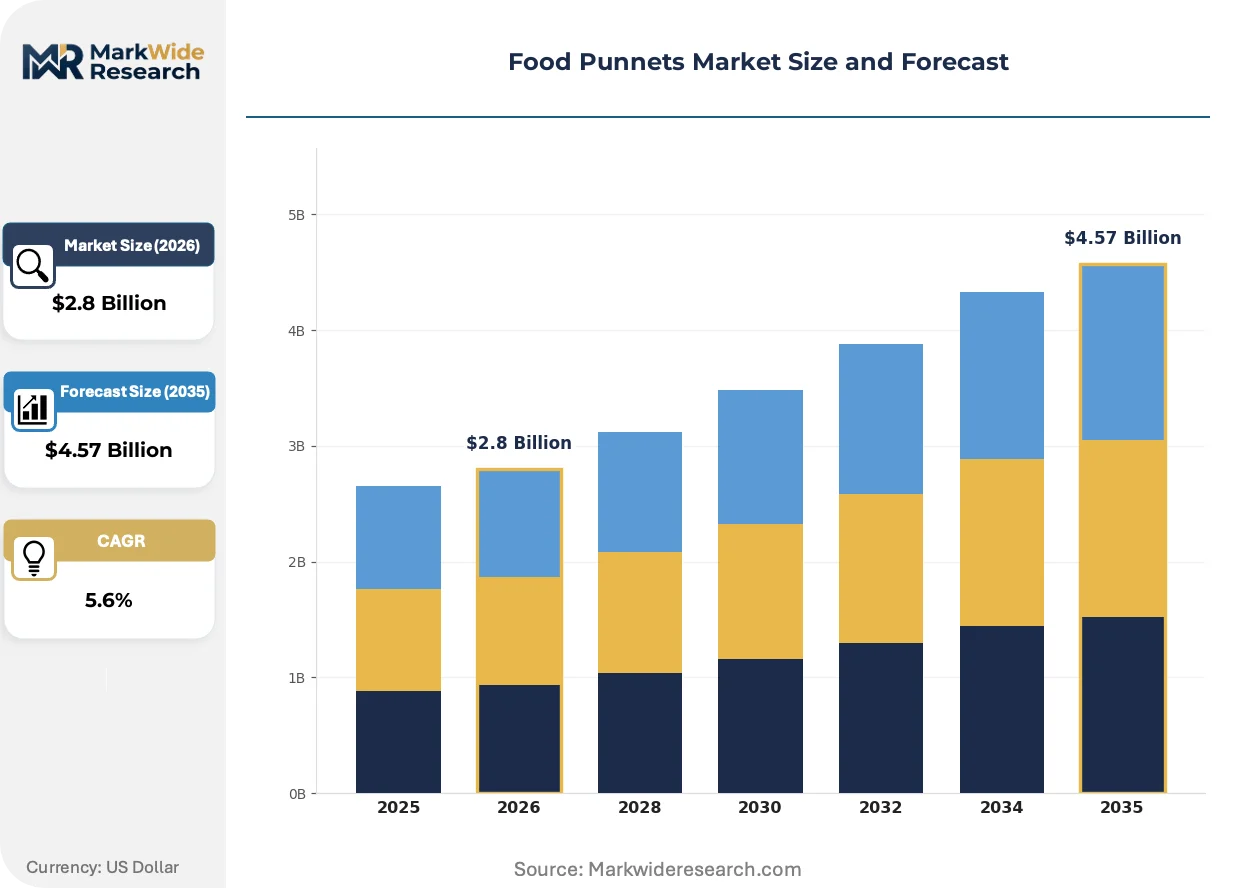
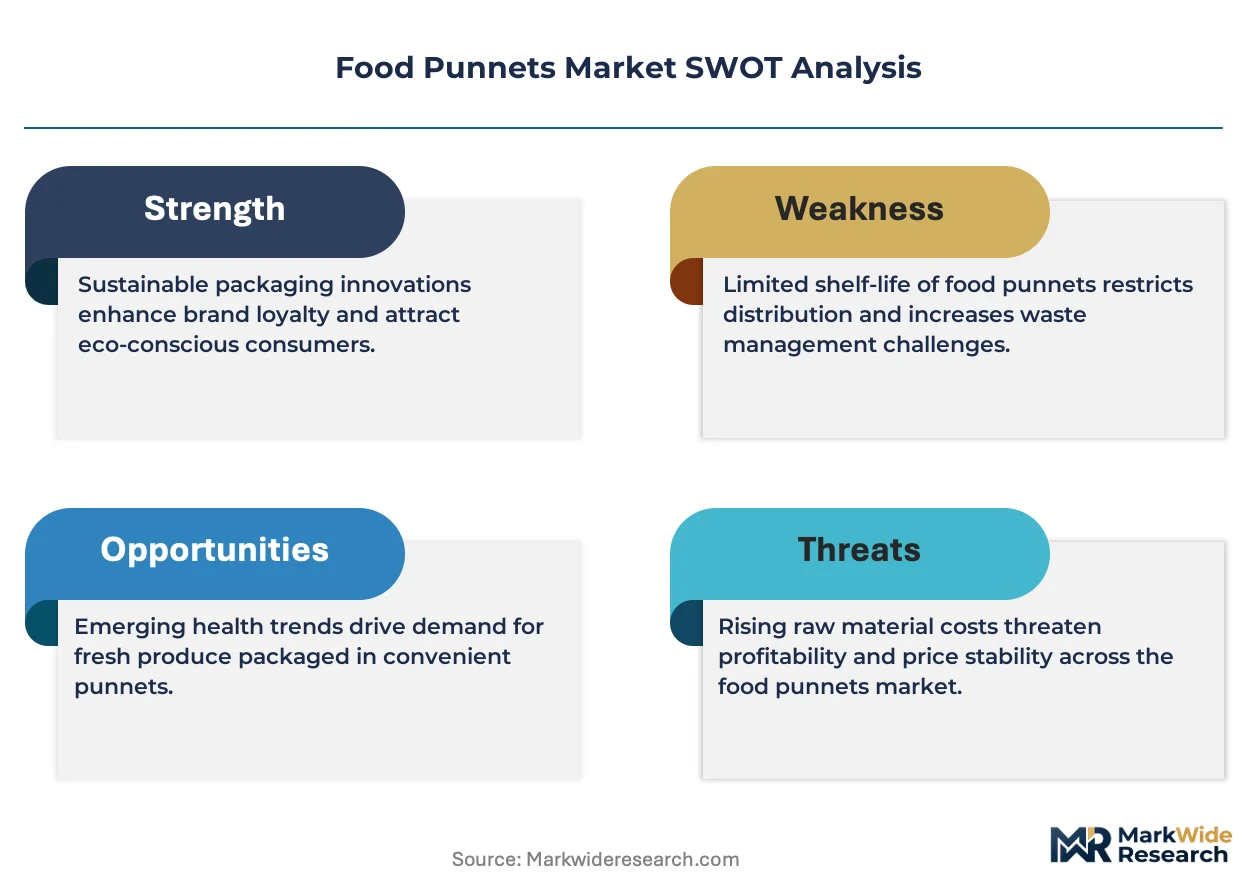
The EU Green Deal's Packaging and Packaging Waste Regulation is compressing margins on conventional thermoformed plastic punnets while redirecting capital toward molded fiber and certified compostable alternatives. This regulatory pressure is the dominant structural force reshaping material selection economics across European fresh produce supply chains.
Growth Catalysts
- Extended Producer Responsibility schemes:Germany's UBA enforces packaging waste fees that make biodegradable polymers cost-competitive with virgin plastic, accelerating converter investment in compostable lines.
- Berry export concentration:France's Loire Valley agrifood cluster is consolidating demand for ventilated rigid containers, pulling capacity expansion toward Atlantic port logistics corridors.
- Barrier coating advances:Water-based oxygen barrier technologies for molded fiber are extending shelf-life parity with plastic clamshells in soft fruit applications.
Market Restraints
- Pulp feedstock volatility:Recycled paperboard input costs fluctuate with European packaging waste collection rates, squeezing molded fiber converter margins.
- Thermoforming equipment lock-in:Existing PET and PP extrusion lines in Spain and Italy face stranded asset risk under tightening recycled content mandates.
- Composting infrastructure gaps:Industrial composting facility scarcity in Eastern Europe limits market penetration of certified biodegradable punnets despite regulatory preference.
Strategic Opportunities
- Ready-to-eat meal format expansion:Multi-compartment barrier trays for chilled prepared foods command premium pricing and remain underpenetrated by fiber alternatives.
- Netherlands distribution hub leverage:Rotterdam's cold chain logistics concentration offers scale economies for exporters serving Nordic and German retail chains.
- Digital watermark integration:Covert recycling-sorting codes embedded during thermoforming enable compliance with France's ANSES traceability requirements.
Industry Challenges
- Pulp molding technical talent scarcity:Wet-forming process engineering expertise concentrates in Scandinavian packaging groups, constraining new entrant capacity buildout.
- Recycled food-contact certification timelines:EFSA novel material approvals for post-consumer recycled content in direct food contact extend 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Punnets Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Cardboard, Foam, Wood Pulp, Biodegradable Polymers Application: Fresh Produce, Bakery Goods, Dairy Products, Confectionery, Ready-to-Eat Meals Packaging Type: Clamshell, Sleeve, Tray, Box, Bag End User: Supermarkets, Food Service Providers, Wholesalers, Specialty Stores |
| Companies Covered | Smurfit Kappa Group Plc, Coveris Holdings SA, Berry Global, LC Packaging International BV, Groupe Guillin SA, INFIA S.r.l., Leeways Packaging Services Ltd., Paccor Netherlands BV, AVI Global Plast Pvt Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Punnets Market Shifts & Advancements
Material science breakthroughs and regulatory compliance automation are converging to redefine punnet performance standards. These forces are compressing the innovation cycle from laboratory validation to retail shelf deployment.
High-speed robotic fiber molding with precision vent hole punching is rendering obsolete conventional thermoforming for sub-500g berry applications. Dutch and Belgian equipment suppliers are shipping turnkey lines to French co-packers. The technology is rendering obsolete the historical trade-off between fiber-based sustainability and plastic-grade ventilation precision.
REACH microplastic restriction proposals from ECHA are forcing reformulation of conventional polymer additive packages. Masterbatch suppliers are accelerating mineral filler and bio-based impact modifier development. Soft fruit clamshells with intentionally added microplastics face the steepest compliance timeline, pushing converters toward additive-free base resins or fiber migration.
Retail private-label consolidation is compressing supplier qualification cycles and unbundling legacy packaging specification inertia. Central European discount chains now mandate single-material recyclability or certified compostability in core produce categories. This pattern is most visible in Germany's Aldi and Lidl supply bases, where approved vendor lists have halved since 2023 while technical requirements have tightened.
Food Punnets Market Segmentation
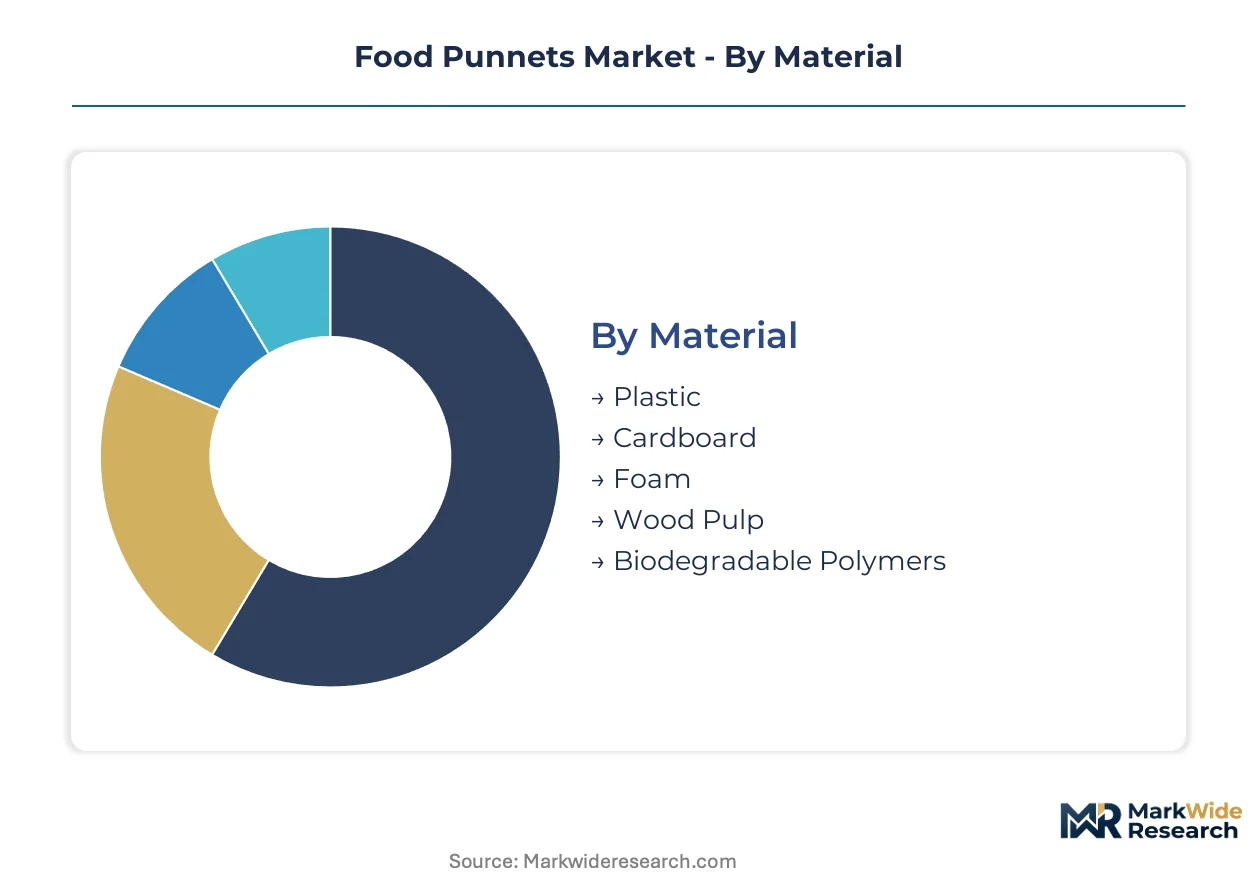
Food punnet segmentation reveals how material science, retail channel requirements, and regulatory pressure intersect to reshape supplier portfolios. Each dimension carries distinct margin profiles and capital intensity thresholds that determine competitive positioning.
Material:
Mature thermoformed polymers dominate installed capacity while emerging alternatives capture regulatory-driven replacement cycles.
- Plastic:PET and PP thermoformed punnets retain cost efficiency for high-throughput berry packing. Germany's UBA packaging fees are compressing margins on virgin resin formats, accelerating converter exits from conventional extrusion.
- Biodegradable Polymers:PLA and PHA blends achieve certified compostability under EU Green Deal standards. France's Loire Valley exporters are consolidating procurement around these materials to preempt ANSES extended producer responsibility penalties.
- Cardboard:Recycled paperboard structures serve dry bakery and confectionery applications with lower barrier demands.
- Foam:Expanded polystyrene trays persist in cost-sensitive wholesale channels despite REACH microplastic scrutiny.
- Wood Pulp:Molded fiber from Scandinavian pulp sources targets premium organic produce positioning.
Plastic retains volume leadership; biodegradable polymers hold the steepest expansion curve.
Application:
Perishability gradients and shelf-life requirements stratify the application landscape into high-frequency commodity flows and precision-engineered premium segments.
- Fresh Produce:Ventilated rigid containers for berries, grapes, and stone fruits generate the dominant volume flow. France's Atlantic port logistics corridors concentrate demand for stackable, barcode-ready punnets with 0.4-0.8 mm wall thickness.
- Ready-to-Eat Meals:Multi-compartment barrier trays with oxygen-scavenging films command premium unit economics. Netherlands cold chain hubs are pulling capacity toward chilled prepared food formats with 14-21 day shelf-life specifications.
- Bakery Goods:Grease-resistant fiber or PET structures balance visibility with moisture protection.
- Dairy Products:Yogurt and cheese punnets prioritize tamper-evident sealing and refrigeration compatibility.
- Confectionery:Rigid clarity requirements favor transparent PET or RPET for gift-oriented presentation.
Fresh produce anchors volume scale; ready-to-eat meals deliver the highest per-unit margin capture.
Packaging Type:
Structural formats map directly to automation compatibility and retail display economics across European distribution networks.
- Clamshell:Hinged rigid containers dominate soft fruit protection with integrated lid security. Belgium and Dutch equipment suppliers are shipping high-speed thermoforming lines optimized for 200-400g berry formats.
- Tray:Open-top structures serve prepared meals and bakery with film-sealing compatibility. Germany's discount retail chains mandate single-material tray formats to simplify consumer sorting under national packaging waste rules.
- Sleeve:Paperboard wraps provide secondary branding surfaces for premium confectionery.
- Box:Corrugated or solid board structures handle bulk wholesale distribution.
- Bag:Flexible films retain cost advantage for pre-cut salad and commodity produce.
Clamshell formats retain the broadest retail penetration; tray configurations are gaining fastest in prepared food automation.
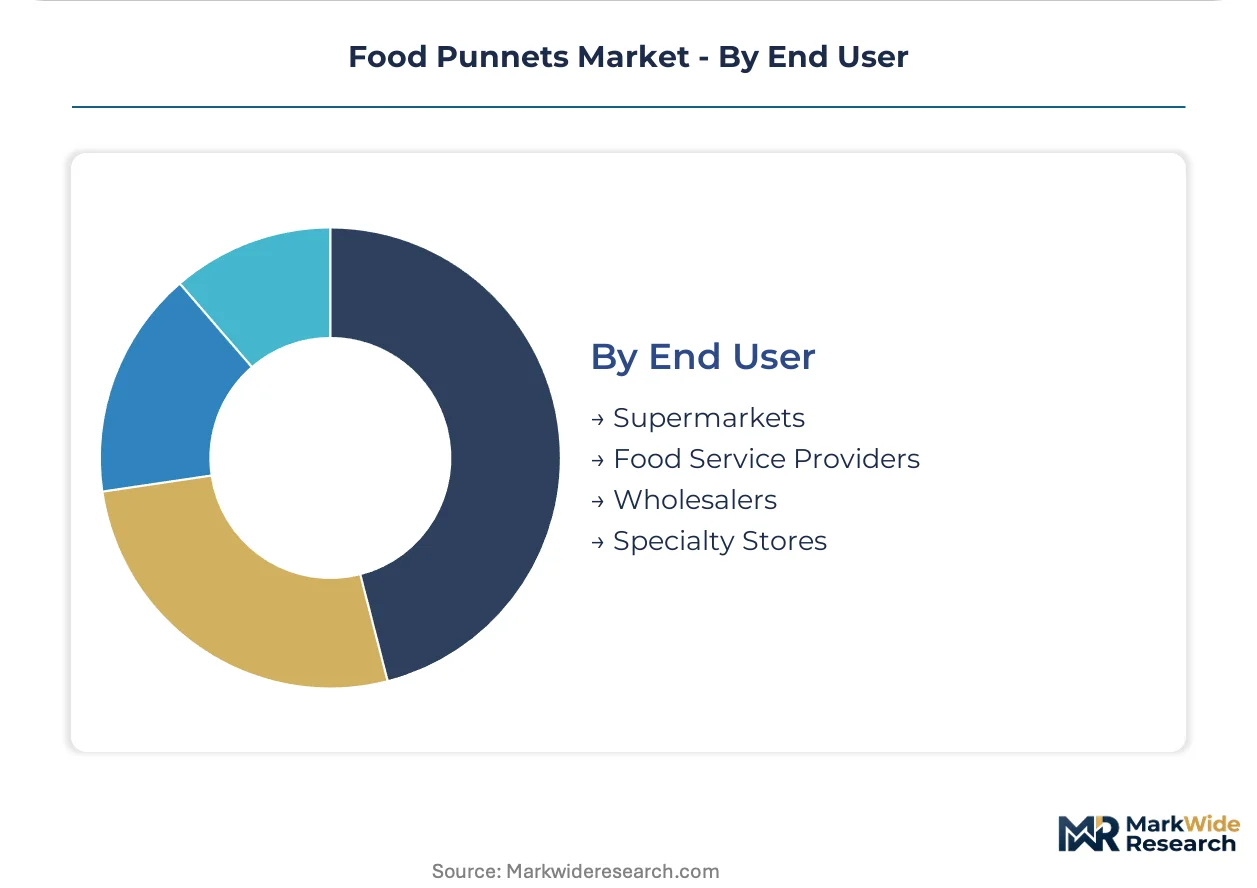
End User:
Procurement concentration and technical specification authority vary sharply across channel types.
- Supermarkets:Central European Aldi and Lidl supply bases have halved approved vendor lists since 2023 while mandating single-material recyclability. Private-label consolidation compresses qualification cycles to 12-18 months.
- Food Service Providers:Contract caterers and meal-kit operators prioritize stackability and microwave compatibility. Netherlands distribution hubs aggregate fragmented demand into scale-efficient procurement pools.
- Wholesalers:Volume-driven buyers favor standardized formats with minimal customization overhead.
- Specialty Stores:Organic and farm-shop channels absorb premium pricing for certified compostable or fiber-based presentation.
Supermarkets command specification authority; food service providers are expanding most quickly as meal delivery penetrates Northern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's UBA anchors European packaging waste enforcement, redirecting converter investment toward compostable formats across the continent's fresh produce corridors.
Germany
Discount retail chains Aldi and Lidl have compressed approved vendor lists by half since 2023 while mandating single-material recyclability. The UBA's packaging waste fees now make biodegradable polymers cost-competitive with virgin plastic. North Rhine-Westphalia's Ruhr industrial belt hosts thermoforming retrofit programs converting legacy PET lines to recycled-content formats.
France
Loire Valley berry and grape exporters are consolidating procurement around certified compostable punnets to preempt ANSES extended producer responsibility penalties. The EU Green Deal's Packaging and Packaging Waste Regulation tightens recycled content minimums through national implementation. Atlantic port logistics corridors near Nantes concentrate demand for ventilated rigid containers with automated barcode compatibility.
Netherlands
Rotterdam's cold chain logistics concentration offers scale economies for exporters serving Nordic and German retail chains. EFSA novel material approval timelines extend 18-24 months for post-consumer recycled content in direct food contact. Dutch equipment suppliers are shipping high-speed robotic fiber molding lines to French co-packers, displacing conventional thermoforming for sub-500g applications.
Italy
Existing PET and PP extrusion lines face stranded asset risk under tightening recycled content mandates from Brussels. INFIA S.r.l. and other domestic converters occupy positions within the rigid plastic specialization tier. Emilia-Romagna's agrifood packaging cluster is piloting water-based oxygen barrier coatings for molded fiber to extend soft fruit shelf-life parity.
Belgium
High-speed thermoforming equipment optimized for 200-400g berry formats ships from Belgian suppliers to French and German packers. The country's central European location enables just-in-time delivery to discount retail distribution centers. Flanders' packaging technology corridor concentrates wet-forming process engineering expertise that constrains new entrant capacity buildout elsewhere.
Food Punnets Market Competitive Landscape
Integrated paperboard suppliers and rigid plastic specialists split the market between sustainable fiber dominance and thermoforming legacy retention. The vendor base concentrates around three strategic archetypes: pulp-integrated multinationals, polymer-focused converters, and equipment-technology licensors. Consolidation pressure is accelerating through M&A activity targeting compostable certification capabilities and geographic expansion into Atlantic port logistics corridors.
Among Ireland-based pulp-integrated multinationals, Smurfit Kappa Group Plc exemplifies the fiber-format dominance archetype through captive paperboard supply chains. Within rigid plastic specialization, Groupe Guillin SA and INFIA S.r.l. occupy positions representing deep format expertise in clamshell and tray configurations. Berry Global anchors the North American extrusion extension archetype, leveraging scale economies across dairy and ready-to-eat meal applications.
| Leading Market Players |
|---|
| Smurfit Kappa Group Plc |
| Coveris Holdings SA |
| Berry Global |
| LC Packaging International BV |
| Groupe Guillin SA |
| INFIA S.r.l. |
| Leeways Packaging Services Ltd. |
| Paccor Netherlands BV |
| AVI Global Plast Pvt Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Italian PET thermoforming lines is compressing converter margins while simultaneously pushing pricing power toward pulp-integrated suppliers in Scandinavia and France. This utilization asymmetry rewards backward-integrated fiber molders with captive pulp supply while stranding legacy plastic extruders under tightening EU Green Deal recycled content mandates.
Pricing Analysis
Geographic price spreads between German discount retail chains and French organic specialty channels now exceed the underlying material cost differentials. Three-tier pricing structure across premium molded fiber, standard recycled-content plastic, and economy virgin resin formats reflects certification grade and volume scale. Cost compression in conventional thermoformed segments is intensifying because Germany's UBA packaging waste fees erode margin on non-compostable formats. Central European Aldi and Lidl supply bases exhibit highest price sensitivity, while Netherlands-based meal-kit operators absorb premiums for barrier-coated fiber trays.
Supply Chain Analysis
Export-control regimes on pulping technology from Scandinavian equipment suppliers are constraining new entrant capacity buildout in Southern Europe. Supply concentrates in Belgium for high-speed thermoforming equipment, Germany for recycled resin compounding, and France for molded fiber finishing. Raw material dependencies span Scandinavian wood pulp, post-consumer PET flake from German collection systems, and PLA resin from Netherlands biopolymer plants. Single-source vulnerability concentrates in wet-forming process engineering expertise anchored in Flanders. Distribution runs through Rotterdam's cold chain logistics concentration for Nordic and German retail chain fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in composting infrastructure partnerships and extended producer responsibility compliance management are expanding faster than hardware sales. Recurring revenue from certification maintenance and regulatory filing support now outpaces unit-margin capture on punnet production.
For Market Incumbents: Harden barrier coating R&D programs to extend molded fiber shelf-life parity with plastic clamshells. Defensive consolidation through acquisition of certified compostable resin suppliers preempts ANSES penalty exposure. Vertical integration into Scandinavian pulp sourcing secures feedstock against collection rate volatility.
For New Entrants and Emerging Players: Establish a beachhead in Netherlands-ready-to-eat meal barrier trays, where fiber alternatives remain underpenetrated and premium pricing persists. White-space targets include Italian dairy converters seeking retrofit partnerships and Eastern European composting infrastructure gaps. Go-to-market through equipment-technology licensing to stranded PET extruders offers fastest qualification.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across molded fiber capacity buildout as wet-forming line costs escalate. Long-term viability over the next decade favors pulp-integrated multinationals with captive supply chains over polymer-specialist converters facing stranded asset risk. Acquisition target archetype: Belgian or Dutch equipment-technology licensors with turnkey robotic fiber molding capabilities. The signal to monitor is EFSA approval timelines for post-consumer recycled content in direct food contact.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Scandinavian fiber sourcing insulates margins from collection rate volatility. |
| Barrier Coating R&D Partnership | Water-based oxygen barriers extend molded fiber shelf-life parity with plastic clamshells. |
| Composting Infrastructure Joint Venture | Eastern European facility buildout unlocks certified biodegradable punnet penetration. |
| Equipment-Technology Licensing | Turnkey robotic fiber molding lines displace thermoforming for sub-500g berry applications. |
| Extended Producer Responsibility Compliance Service | Recurring regulatory filing revenue outpaces hardware margin capture. |
Research Methodology
The analysis maps thermoformed plastic, molded fiber, and biodegradable polymer sub-sectors, each validated through converter plant managers, retail category buyers, and regulatory affairs leads at national packaging agencies. Primary interviews with equipment-technology licensors and secondary validation through EU Green Deal implementation documents, EFSA novel material approval records, and ANSES extended producer responsibility filings anchored the assessment. Bottom-up capacity utilization surveys and top-down trade flow analysis provided triangulation.
Assumption-sets held EU Green Deal enforcement timelines and ECHA microplastic restriction proposals as fixed boundary conditions while varying pulp feedstock cost scenarios and composting infrastructure penetration rates. The analytical framework models material type, application shelf-life requirement, packaging format automation compatibility, and end-user channel concentration across the projection horizon. CAGRs derive from segment-level demand elasticity and substitution rate modeling, with inputs including berry export volume concentration in France's Loire Valley and Netherlands cold chain hub throughput.
Macroeconomic conditions sit as an overlay; deviation in European packaging waste collection rates or pulp commodity price volatility would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in EFSA approval timelines for post-consumer recycled content or ANSES penalty enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Ice Cream Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Pie Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Food Packaging Market