
 Sealed Wax Packaging Market | 2026-2036
Sealed Wax Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sealed Wax Packaging Market Outlook
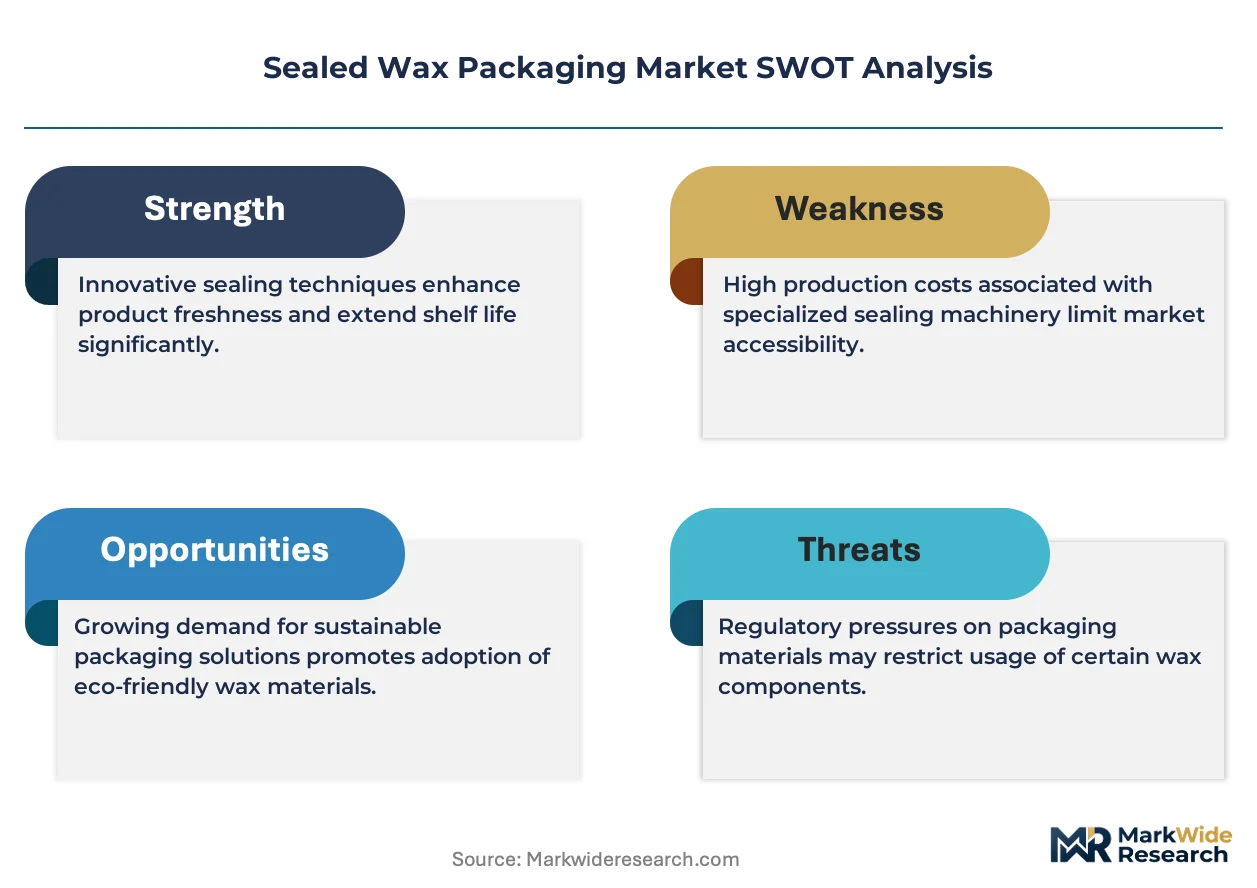
Barrier-coating technology is narrowing the performance gap between petroleum-derived paraffin and plant-based wax alternatives, forcing reformulation across the supply base. Calwax, LLC leverages its California refining infrastructure to sustain consistent paraffin supply for North American food packagers. The British Wax Refining Company Ltd anchors European production through specialized blends that navigate REACH chemical restrictions. Blended Waxes Inc. differentiates via custom beeswax-paraffin ratios targeting premium cosmetic brands.
Sealed wax packaging denotes materials and containers employing wax barrier layers—typically 15–40 gsm coating weights—to impart moisture resistance, grease impermeability, and seal integrity against oxygen ingress. The primary commercial purpose centers on extending shelf stability for perishables while enabling heat-sealed closure without synthetic polymer films. Waxed paper occupies the largest volume position due to legacy adoption in bakery wrapping and butcher applications, though wax resist films represent the fastest-expanding category as frozen food processors convert from multilayer plastics. Natural waxes command premium positioning in cosmetic and pharmaceutical segments where end-users reject petrochemical content, while paraffin waxes dominate industrial and chemical packaging on cost efficiency.
FDA food-contact substance notifications govern wax composition for U.S. edible goods, while REACH and the EU Packaging and Packaging Waste Directive constrain additive chemistries across European supply chains. China's GB standards for food packaging materials impose additional migration testing that shapes export-oriented formulation decisions. Stakeholders must monitor regulatory divergence between biodegradability mandates and performance requirements as bio-based wax coatings face scalability constraints against established paraffin infrastructure.
Market Dynamics
Barrier-coating technology is compressing the performance differential between petroleum-derived paraffin and plant-based wax alternatives, forcing simultaneous reformulation across raw material suppliers and converting packaging manufacturers.
Growth Catalysts
- FDA food-contact substance notifications:U.S. regulatory clarity on wax composition for edible goods accelerates brand adoption in bakery and dairy segments seeking compliant moisture-barrier solutions.
- Processed food exports from Germany:Premium sausage and cheese producers drive specialized wax-sealed formats that satisfy extended shelf-life requirements for cross-border distribution.
- Beeswax-paraffin blending technology:Custom ratio formulations enable cosmetic brands to meet clean-label claims while retaining heat-seal functionality previously restricted to synthetic films.
Market Restraints
- Crude oil price volatility:Paraffin wax cost structure ties directly to petroleum feedstock fluctuations, compressing margins for converters locked into long-term supply contracts.
- REACH additive restrictions:ECHA constraints on antioxidant chemistries limit formulation flexibility for European food-contact applications, forcing costly requalification cycles.
- Multilayer plastic substitution:Frozen food processors retain legacy polyethylene-EVOH structures where ultra-low oxygen transmission rates exceed current wax resist film capabilities.
Strategic Opportunities
- China's GB standards compliance:Export-oriented wax coaters capturing migration-tested formulations gain preferential access to processed food manufacturers serving domestic premium retail channels.
- Pharmaceutical cold-chain packaging:Temperature-stable wax barrier layers address stability requirements for biologics shipping, an application segment with minimal incumbent wax penetration.
- EU Packaging and Packaging Waste Directive:Biodegradability mandates create regulatory tailwind for bio-based wax coatings in single-use food service items across France, Italy, and Netherlands food-service supply chains.
Industry Challenges
- Coating weight precision engineering:Maintaining 15–40 gsm uniformity across high-speed paperboard lines requires specialized technician training scarce in converting labor markets.
- Dual certification timelines:Simultaneous FDA notification and REACH compliance documentation extends product launch cycles by 8–14 months for multinational food brands.
- Legacy heat-seal equipment retrofitting:Converting multilayer plastic lines to wax-compatible sealing jaws demands capital expenditure that mid-tier bakeries defer during margin compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sealed Wax Packaging Market |
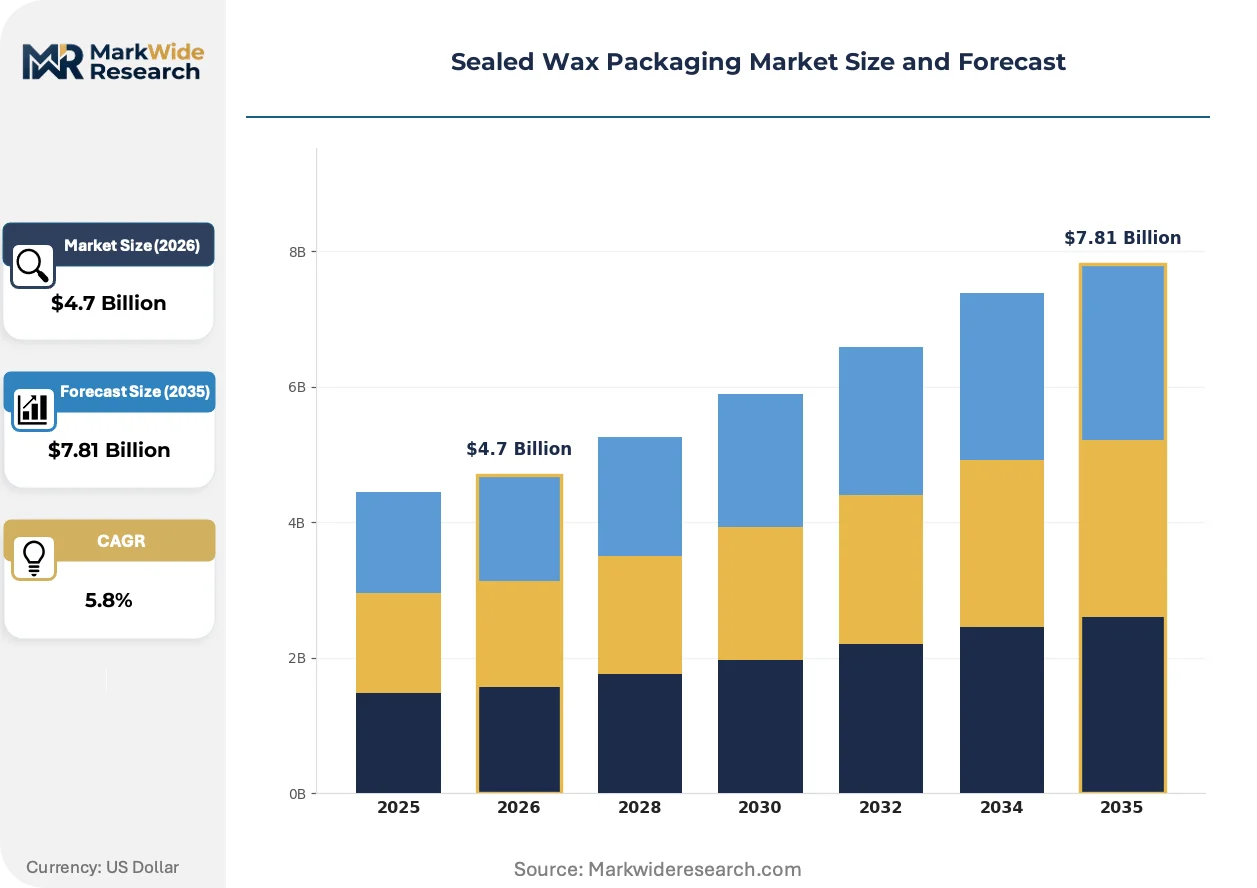
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
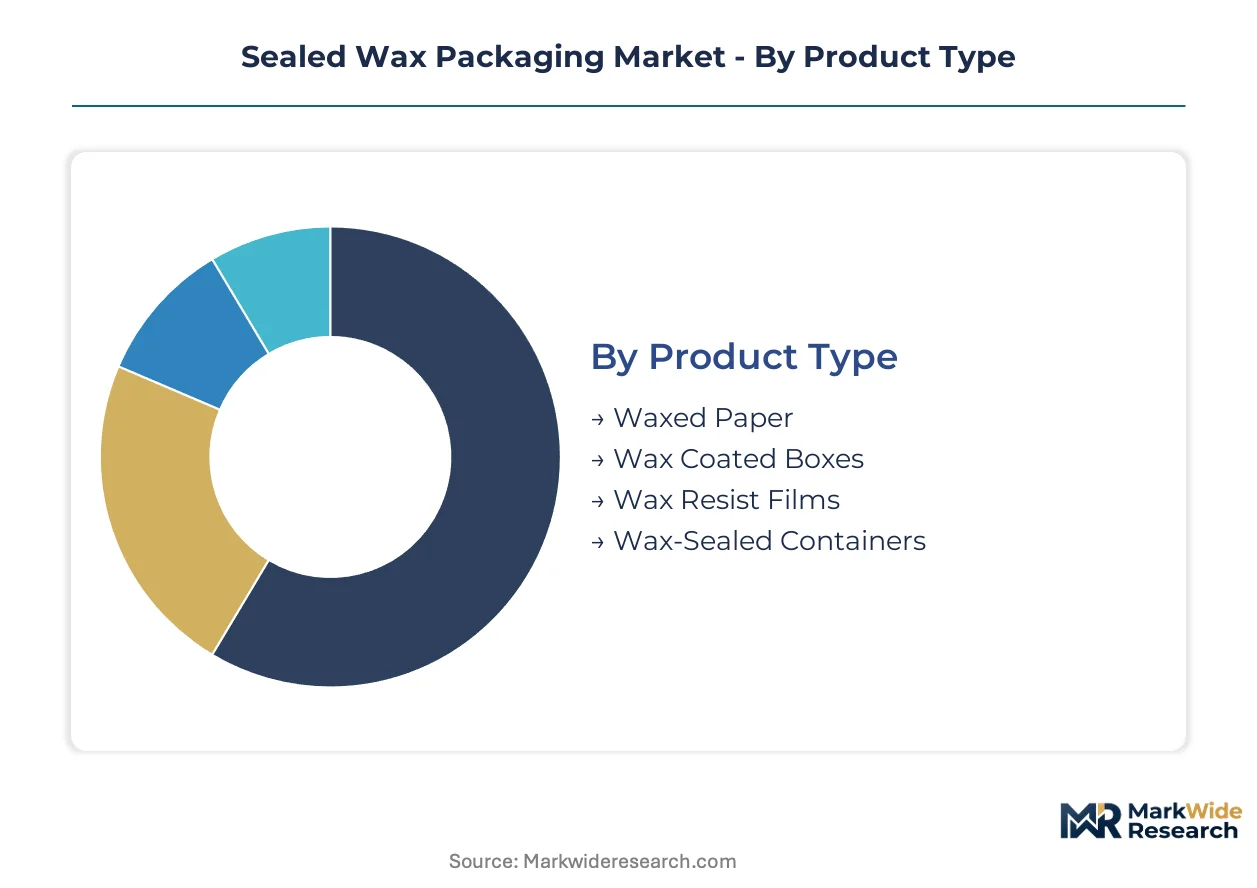
| Segmentation | Product Type: Waxed Paper, Wax Coated Boxes, Wax Resist Films, Wax-Sealed Containers End Use: Food Packaging, Cosmetic Packaging, Chemical Packaging, Industrial Packaging Material: Natural Waxes, Synthetic Waxes, Paraffin Waxes, Beeswax Application: Pharmaceuticals, Bakery Products, Dairy Items, Frozen Foods |
| Companies Covered | Australian Wax Co., Calwax, LLC, Blended Waxes Inc., Jax Wax Pty Ltd., City Company Seals Ltd, Southwest Wax LLC, Brick Packaging LLC, The British Wax Refining Company Ltd, Oakbank Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sealed Wax Packaging Market Strategic Shifts
Digital coating control systems and bio-based formulation advances are reconfiguring competitive advantage around precision application and regulatory pre-certification rather than commodity scale.
Micro-layer deposition technology is digitizing wax coating operations through real-time thickness monitoring and automated gsm adjustment. Frozen food processors in the United States adopt these systems to reduce over-application waste and maintain FDA-compliant migration limits. The technology is digitizing quality assurance workflows previously dependent on offline laboratory testing, compressing batch release cycles from hours to minutes.
REACH Annex XVII expansion on persistent organic pollutants tightens allowable antioxidant loadings in food-contact waxes across European supply chains. Blenders reformulate with tocopherol-based alternatives that sacrifice some oxidative stability but maintain regulatory clearance. German dairy exporters face the steepest compliance burden, as their extended distribution networks demand maximum shelf-life protection that legacy additive packages provided.
Consolidated procurement by multinational bakery chains now mandates pre-certified wax suppliers with dual FDA-REACH documentation. Regional converters without in-house regulatory affairs functions lose preferred vendor status to integrated coating specialists. This concentration is most visible in the United Kingdom, where supermarket private-label consolidation has reduced approved waxed paper suppliers from twelve to four since 2022.
Sealed Wax Packaging Market Segmentation
Sealed wax packaging serves divergent performance requirements across moisture-sensitive goods, with formulation choices and coating architectures calibrated to shelf-life demands, regulatory constraints, and heat-seal compatibility. Segment boundaries reflect trade-offs between barrier performance, biodegradability mandates, and conversion economics that reshape supplier positioning.
Product Type:
Wax barrier configurations span legacy paper saturation to precision-coated films, with each format commanding distinct capital intensity and end-use access.
- Waxed Paper:Saturated kraft substrates at 15–40 gsm coating weights deliver grease impermeability for direct food contact. German sausage exporters and U.S. butcher counters anchor volume demand despite slower line speeds versus synthetic alternatives.
- Wax Coated Boxes:Corrugated or solid fiberboard receiving curtain or cascade wax application for moisture resistance in cold-chain distribution. Frozen food processors in the United States favor this format for seafood and ice cream logistics where condensation protection governs case integrity.
- Wax Resist Films:Oriented substrates with micro-layer wax deposition achieving oxygen barrier performance approaching multilayer plastics. Expanding most quickly as European frozen food brands seek single-material recyclability under EU Packaging and Packaging Waste Directive mandates.
- Wax-Sealed Containers:Rigid formats with wax-dipped or sprayed closures for chemical and pharmaceutical applications requiring hermetic seals without induction sealing equipment. Niche positioning in specialty lubricant and adhesive packaging where metal closure compatibility is limited.
Established volume favors Waxed Paper; emerging adoption favors Wax Resist Films.
End Use:
Customer procurement patterns split between price-sensitive commodity converters and premium brands seeking regulatory pre-certification.
- Food Packaging:Bakery wrapping and dairy portion packs dominate tonnage, with FDA food-contact notifications and REACH compliance documentation now mandatory for multinational bakery chain approval. Migration-tested formulations command supplier consolidation toward integrated coating specialists.
- Cosmetic Packaging:Clean-label claims drive beeswax-paraffin blending ratios that sacrifice some oxidative stability for petrochemical-free positioning. Premium skincare lines in France and Germany specify custom wax formulations with ECHA-compliant tocopherol antioxidants.
- Chemical Packaging:Paraffin-dominant formulations prioritize cost efficiency and chemical inertness for industrial lubricants and agricultural inputs. REACH Annex XVII constraints on persistent organic pollutants force reformulation cycles among European suppliers.
- Industrial Packaging:Rust-inhibiting wax wraps and corrosion-preventive coatings for metal components in transit. Volume concentrates in German and Chinese manufacturing export corridors where humidity protection extends machinery shelf life.
Food Packaging commands current volume leadership; Cosmetic Packaging climbs the fastest on premium positioning and regulatory differentiation.
Material:
Feedstock selection balances petroleum cost exposure against bio-based scalability constraints and additive regulatory loadings.
- Natural Waxes:Plant-derived alternatives including carnauba and candelilla with restricted availability and higher melting points. Premium cosmetic and pharmaceutical segments in Germany absorb price premiums for petrochemical-free claims.
- Synthetic Waxes:Fischer-Tropsch and polyethylene waxes offering consistent melt profiles and oxidative stability. Industrial packaging applications favor this category for batch-to-batch uniformity in high-speed coating operations.
- Paraffin Waxes:Petroleum-derived standards dominating cost-sensitive food and industrial segments. Crude oil price volatility compresses converter margins and drives hedging complexity among North American suppliers with California refining infrastructure.
- Beeswax:Natural secretion with superior plasticity and adhesion properties enabling lower coating weights. Cosmetic brands specify custom ratios with paraffin to retain heat-seal functionality while meeting clean-label requirements.
Paraffin Waxes sustain volume dominance; Beeswax gains share fastest on cosmetic clean-label adoption.
Application:
Performance specifications diverge across temperature stability, oxygen transmission, and regulatory documentation intensity.
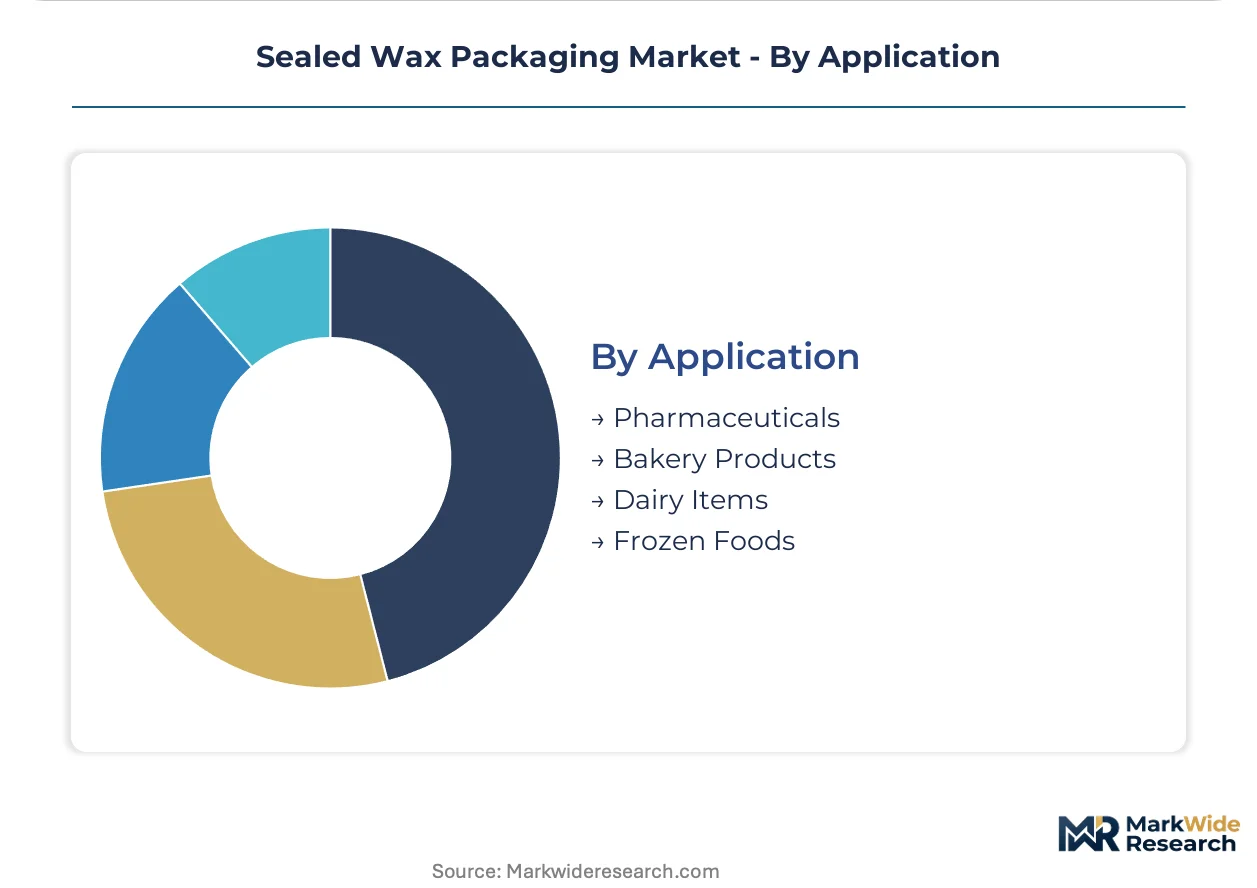
- Pharmaceuticals:Temperature-stable barrier layers for biologics cold-chain shipping with minimal incumbent wax penetration. FDA drug master file requirements and stability validation protocols extend qualification timelines beyond food-contact pathways.
- Bakery Products:Grease-resistant wraps for pastries and bread with established waxed paper infrastructure. U.S. and German bakery chains now mandate dual FDA-REACH certified suppliers, reducing approved vendor pools.
- Dairy Items:Cheese wax coatings and butter wraps requiring oxygen barrier and moisture regulation. Extended distribution networks for German premium cheese exports demand maximum shelf-life protection that legacy antioxidant packages provided.
- Frozen Foods:Wax resist films and coated board for seafood, ice cream, and prepared meals. China's GB standards compliance for migration testing shapes export-oriented formulation decisions for processors serving domestic premium retail channels.
Bakery Products anchor current volume; Pharmaceuticals represent the steepest expansion trajectory on underpenetrated cold-chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational bakery chains and premium cosmetic brands concentrate procurement among pre-certified suppliers in Germany, China, and the United States. These three markets anchor demand for migration-tested formulations and dual FDA-REACH compliance documentation.
Germany
Premium sausage and cheese exporters drive specialized wax-sealed formats for extended cross-border shelf life. ECHA's REACH Annex XVII restrictions on antioxidant chemistries force costly reformulation cycles among dairy coating specialists. The Baden-Württemberg industrial corridor hosts concentrated wax blending operations serving pharmaceutical cold-chain packaging.
China
Processed food manufacturers serving domestic premium retail channels demand GB standards-compliant migration testing for export-oriented wax coatings. SAMR's evolving food-contact material regulations shape formulation decisions for frozen food processors. The Yangtze River Delta clustering of converting operations supplies wax resist films to seafood and ice cream logistics networks.
United States
FDA food-contact substance notifications accelerate brand adoption in bakery and dairy segments seeking compliant moisture-barrier solutions. California refining infrastructure sustains consistent paraffin supply for North American food packagers. Midwest converting operations supply waxed paper to consolidated bakery chains mandating dual-certified suppliers.
United Kingdom
Supermarket private-label consolidation has reduced approved waxed paper suppliers from twelve to four since 2022. ECHA constraints apply post-Brexit through retained REACH law, maintaining additive restrictions on food-contact waxes. The Midlands packaging belt concentrates curtain-coating operations for corrugated cold-chain distribution.
France
Premium skincare lines specify custom beeswax-paraffin formulations with ECHA-compliant tocopherol antioxidants for clean-label positioning. ANSM oversight of pharmaceutical packaging materials extends qualification timelines for biologics cold-chain applications. The Île-de-France region anchors cosmetic brand headquarters driving specialized wax procurement.
Sealed Wax Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three archetypes: integrated refiners with captive paraffin supply, custom blenders serving premium cosmetic formulations, and regional converters lacking in-house regulatory affairs. Consolidation pressures favor coating specialists with dual FDA-REACH documentation over mid-tier bakeries deferring capital expenditure. Two dominant competitive moves are backward integration into refining infrastructure and geographic expansion through migration-tested formulation pre-certification.
Within the integrated refiner tier, Calwax, LLC and The British Wax Refining Company Ltd exemplify geographic anchoring strategies. Calwax, LLC occupies a position tied to California petroleum refining infrastructure. The British Wax Refining Company Ltd sits within European REACH compliance boundaries. Blended Waxes Inc. represents the custom blender archetype, occupying a niche defined by formulation flexibility rather than commodity scale.
| Leading Market Players |
|---|
| Australian Wax Co. |
| Calwax, LLC |
| Blended Waxes Inc. |
| Jax Wax Pty Ltd. |
| City Company Seals Ltd |
| Southwest Wax LLC |
| Brick Packaging LLC |
| The British Wax Refining Company Ltd |
| Oakbank Products Limited |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Rotterdam corridor's freight cost volatility compresses converter margins while amplifying price differentiation between REACH-certified European suppliers and uncertified Asian competitors. Petroleum feedstock exposure ties paraffin wax pricing to crude indexation, forcing dual-sourcing strategies among multinational food packagers seeking supply security.
Pricing Analysis
Cost-plus contracts indexed to crude oil benchmarks dominate long-term supply agreements between North American refiners and bakery chain converters. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels reflects dual FDA-REACH documentation costs. Pricing pressure stems from crude volatility and antioxidant reformulation expenses under ECHA Annex XVII. Mid-tier regional converters exhibit highest price sensitivity due to deferred capital expenditure on heat-seal equipment retrofitting.
Supply Chain Analysis
Upstream petroleum refining in the United States, Germany, and China anchors paraffin wax availability for coating operations. Crude oil, antioxidant additives, and kraft paper substrates constitute critical input dependencies. Single-source vulnerability concentrates in California refining infrastructure serving North American food packagers. Distribution runs through integrated coating specialists with captive regulatory affairs functions rather than fragmented regional converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision coating technicians capable of maintaining 15–40 gsm uniformity across high-speed lines represent the scarcest capability in this market, constraining expansion for converters lacking specialized training infrastructure.
For Market Incumbents: Entrench market position through backward integration into California or German refining infrastructure to secure captive paraffin supply against crude volatility. Accelerate dual FDA-REACH certification investment to capture consolidated procurement from multinational bakery chains, defending against custom blenders with formulation flexibility advantages. For New Entrants and Emerging Players: Pharmaceutical cold-chain packaging in Germany and the United States offers the most penetrable white-space, with minimal incumbent wax penetration and extended qualification timelines that favor patient capital. Target biologics stability validation as entry credential, leveraging temperature-stable barrier layer expertise to differentiate from commodity food-contact suppliers. For Investors and Strategic Acquirers: Custom formulation specialists with ECHA-compliant tocopherol antioxidant capabilities and existing cosmetic brand relationships represent the optimal acquisition archetype for premium segment exposure. Monitor REACH Annex XVII expansion announcements as inflection signal for reformulation cycle intensity and compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FDA notification and REACH compliance documentation accelerates multinational bakery chain approval cycles. |
| Backward Integration | Captive petroleum refining infrastructure insulates margin compression from crude oil benchmark volatility. |
| Micro-Layer Deposition Deployment | Digital coating control systems reduce over-application waste and compress batch release timelines. |
| Pharmaceutical Cold-Chain Qualification | FDA drug master file pathways open biologics shipping segments with minimal wax incumbent presence. |
| Custom Beeswax-Paraffin Formulation | Clean-label cosmetic positioning commands premium pricing from French and German skincare brands. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wax coating technicians, regulatory affairs directors at food packagers, procurement leads at multinational bakery chains, and technical sales managers at refining operations. Secondary validation drew from FDA food-contact substance notifications, ECHA REACH Annex XVII amendments, SAMR GB standards documentation, and customs trade data for paraffin and natural wax imports. Bottom-up segment sizing and top-down macro calibration ensured cross-verified demand estimates.
Calibration against historical volume trajectories and regulatory implementation timelines anchored projection modeling across the analysis window. Segmentation dimensions included product type, end-use application, material feedstock, and geographic regulatory cluster. CAGRs were derived from weighted average growth rates across segment-level demand curves, incorporating coating weight precision constraints and dual certification timeline impacts as industry-specific modifiers.
Practitioners should monitor ECHA persistent organic pollutant restriction proposals and SAMR food-contact material evolutions for early signals of reformulation cycle intensity. Forecasts reflect assumptions regarding crude oil price band stability and coating technology adoption curves. Cross-checking against ACC and Cefic wax industry production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Strip Pack Market
Packaging Materials
Asia - Pacific Disposable Tableware Market