
 United States Frozen Food Packaging Market | 2026-2036
United States Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frozen Food Packaging Market Analytics
Modular portion packs is decoupling bulk frozen formats into single-serve and multi-serve configurations, giving retailers flexibility to mix SKUs without committing to full case volumes. Amcor Plc leverages its film extrusion network to supply resealable lidding across the Midwest and Southeast. Pactiv Evergreen Inc. anchors the foodservice channel with hinged-lid containers for institutional buyers. Sealed Air Corporation differentiates through vacuum skin tray systems that extend protein shelf visibility.
United States frozen food packaging encompasses barrier structures, formed trays, and flexible enclosures engineered to maintain temperatures below freezing while blocking moisture vapor transmission and oxygen ingress, typically employing multi-layer coextrusions with ethylene vinyl alcohol or metallized films to preserve sensory quality through distribution. Cartons and clamshells lead volume in retail vegetable and pizza segments where shelf visibility and stackability drive placement economics. Polyethylene and polypropylene dominate material demand, though paperboard is gaining structural share in microwaveable applications where fiber-based barriers meet revised FDA food contact guidance.
The FDA and USDA jointly govern frozen food packaging through food contact notification rules and Hazard Analysis Critical Control Point mandates, with California's Safe Drinking Water and Toxic Enforcement Act adding state-level chemical disclosure requirements that reshape material selection for brands distributing nationally. The EPA's evolving recycled content standards for food-contact plastics are pressuring converters to validate post-consumer feedstock streams. Stakeholders must monitor how state-level extended producer responsibility legislation migrates from packaging waste bills into binding frozen food supply chain obligations.
Market Dynamics
Modular portion packs are fragmenting bulk frozen formats into single-serve and multi-serve configurations, forcing converters to retool extrusion lines for shorter runs while retailers demand SKU flexibility without full-case commitments. This decoupling of volume from variety is compressing converter margins and reshaping distributor relationships across the cold chain.
Growth Catalysts
- California's Safe Drinking Water and Toxic Enforcement Act:State-level chemical disclosure mandates are accelerating material transparency investments, pulling national brands into compliance frameworks that exceed baseline FDA food contact substance rules.
- Retailer private-label expansion:Grocery chains in the Midwest and Southeast are vertically integrating frozen ready-meal sourcing, creating captive demand for resealable lidding and printed cartons.
- Barrier coextrusion advances:Ethylene vinyl alcohol and metallized film structures are extending protein shelf visibility, enabling vacuum skin tray adoption in premium beef and seafood segments.
Market Restraints
- Post-consumer feedstock validation costs:EPA recycled content standards for food-contact plastics require converters to certify polymer streams, adding qualification overhead before volume deployment.
- Resin supply concentration:Polyethylene and polypropylene availability clusters along Gulf Coast petrochemical corridors, exposing converters to hurricane-season disruption and rail bottlenecks.
- Paperboard barrier performance gaps:Fiber-based alternatives struggle to match multi-layer film moisture vapor transmission rates in extended frozen storage, limiting microwaveable application penetration.
Strategic Opportunities
- Extended producer responsibility migration:State packaging waste bills in Oregon and Maine are creating binding frozen food supply chain obligations that favor early compliance investments.
- Foodservice channel automation:Institutional buyers in K-12 and healthcare are adopting hinged-lid containers compatible with automated dispensing systems, opening volume contracts outside retail.
- Central Valley processing corridor densification:California's frozen vegetable and fruit concentration supports on-site packaging integration, reducing transport-stage cold chain losses.
Industry Challenges
- Migration testing laboratory capacity:FDA tightened polyethylene migration limits are overwhelming third-party testing facilities, extending new product qualification timelines.
- Legacy thermoforming asset retrofit:Converters face capital intensity in upgrading formed tray lines for thinner-gauge, higher-barrier structures without sacrificing cycle speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frozen Food Packaging Market |
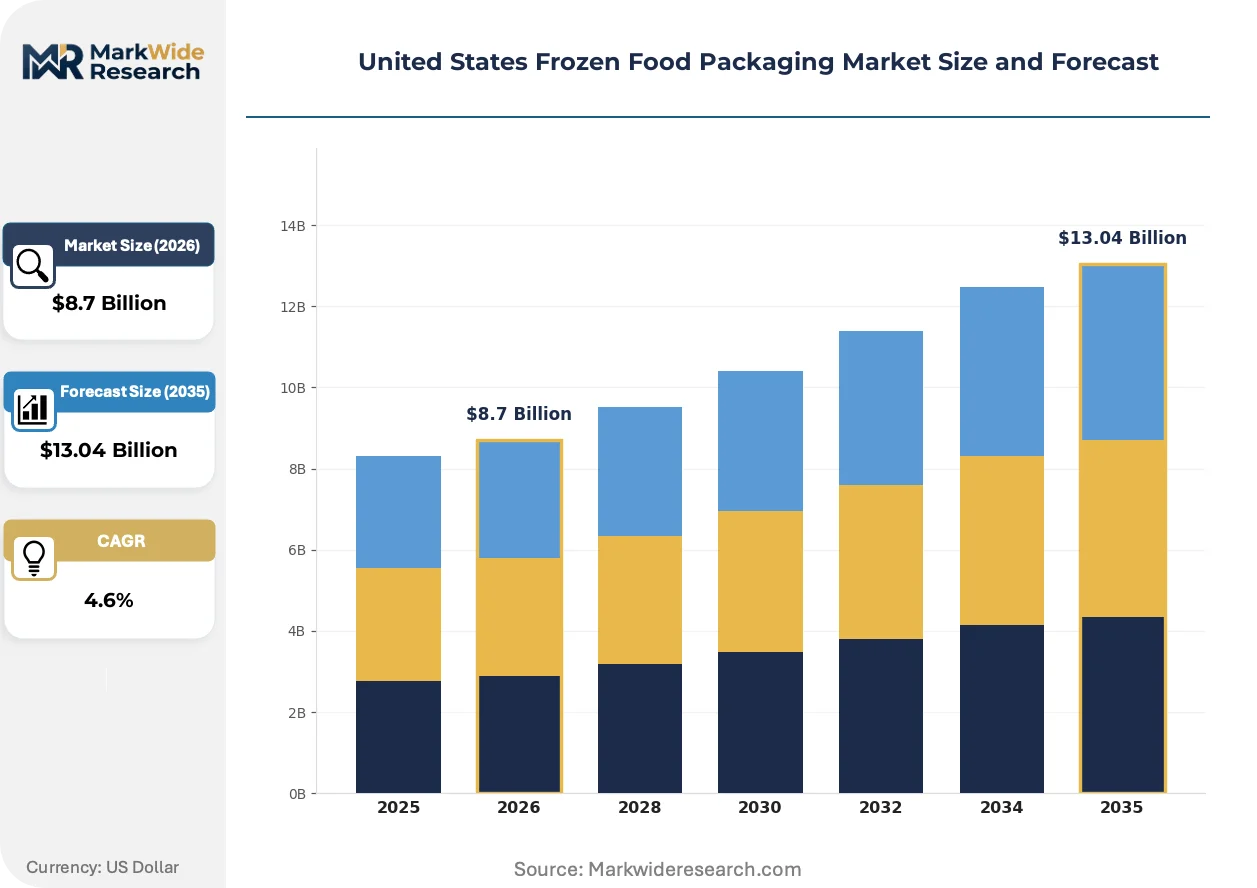
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Cartons, Clamshells, Trays Material: Polyethylene, Polypropylene, Aluminum, Paperboard Closure Type: Resealable, Heat-Sealed, Twist-Off, Snap-On Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice |
| Companies Covered | Amcor Plc, Pactiv Evergreen Inc., Sealed Air Corporation, Graphic Packaging International, Smurfit WestRock, Sonoco Products Company, Berry Global Inc., ProAmpac, WestRock Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frozen Food Packaging Market Evolving Landscape
Active packaging intelligence and material hybridization are compressing the traditional tradeoff between barrier performance and end-of-life options, forcing converters to engineer for simultaneous frozen durability and recycling stream compatibility.
Multi-layer coextrusion with ethylene vinyl alcohol cores is unifying oxygen barrier and mechanical durability in a single forming step, eliminating adhesive lamination stages. Frozen seafood processors in the Pacific Northwest are adopting these structures at pilot scale, compressing supply chain steps while maintaining sensory quality through distribution.
FDA food contact substance notification updates are tightening migration limits for polyethylene packaging, forcing converters to revalidate additive packages and polymer grades. Frozen dairy dessert producers face the most acute compliance pressure, responding with accelerated substitution of alternative barrier resins and expanded documentation protocols.
Retailers are consolidating frozen SKU assortment around shelf-ready formats that reduce back-of-store labor, displacing traditional corrugated shippers with printed cartons and display-ready cases. Grocery chains in Texas and Florida are driving this transition fastest, reconfiguring freezer aisle layouts to accommodate vertical stacking and front-facing graphics.
United States Frozen Food Packaging Market Segmentation
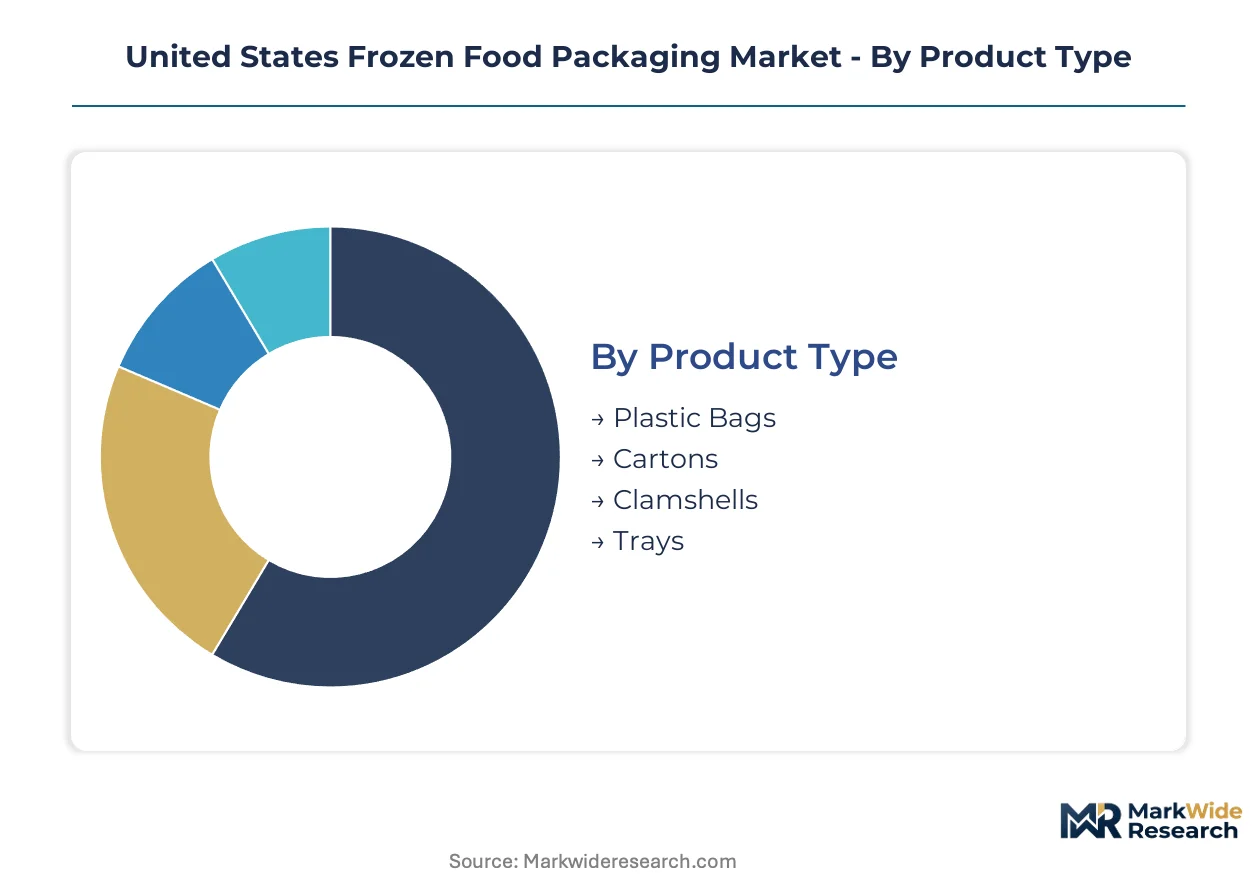
Frozen food packaging segments reflect divergent cold chain requirements and retail channel economics. Material selection and closure mechanics directly determine shelf visibility, resealability, and microwave compatibility across temperature-controlled distribution.
Product Type:
Customization versus standardization splits sharply across frozen formats, with retail-facing segments demanding graphic surface area while foodservice prioritizes stack density and dispensing automation.
- Plastic Bags:Multi-layer polyethylene or polypropylene coextrusions with ethylene vinyl alcohol barrier cores dominate bulk vegetable and protein applications. Demand concentrates in California's Central Valley processing corridor, where vertical form-fill-seal lines run continuously for frozen fruit export volumes.
- Cartons:Paperboard-based structures with polyethylene extrusion coatings or metallized films provide front-facing billboard space and freezer-case stackability. Grocery chains in Texas and Florida are displacing corrugated shippers with shelf-ready printed cartons to reduce back-of-store labor.
- Clamshells:Thermoformed polyethylene terephthalate or polypropylene hinged structures protect irregular geometries like frozen pizzas and prepared meals. The format struggles against thinner-gauge tray alternatives in freight cost optimization.
- Trays:Formed polypropylene or crystallized polyethylene terephthalate structures with lidding film compatibility anchor premium protein and ready-meal segments. Vacuum skin tray adoption is climbing fastest in Pacific Northwest seafood processing.
Most installed capacity flows through Plastic Bags. Expansion is steepest in Trays.
Material:
Cost tier stratification separates commodity resin grades from barrier-enhanced and fiber-based alternatives, with FDA migration limits and California chemical disclosure mandates reshaping qualification pipelines.
- Polyethylene:Linear low-density and high-density grades provide puncture resistance and seal integrity across bag and lidding applications. Frozen dairy dessert producers face acute compliance pressure from FDA tightened migration limits, forcing additive package revalidation.
- Polypropylene:Oriented and cast films plus injection-molded or thermoformed trays deliver higher temperature tolerance for microwaveable applications. Gulf Coast petrochemical corridor concentration exposes converters to hurricane-season disruption and rail bottlenecks.
- Aluminum:Foil laminations and formed trays deliver absolute oxygen and light barriers for extended frozen storage of premium proteins. Recyclability challenges limit retail adoption outside specialty channels.
- Paperboard:Fiber-based structures with extruded polyethylene or bio-based barrier coatings are gaining structural share in microwaveable segments where revised FDA food contact guidance validates fiber alternatives. Moisture vapor transmission rate gaps against multi-layer films constrain extended storage applications.
Polyethylene and Polypropylene together anchor volume throughput. Paperboard is gaining share fastest in microwaveable segments.
Closure Type:
Application context dictates resealability requirements, with retail convenience segments paying premiums for multi-use functionality while single-serve formats prioritize tamper evidence and line speed.
- Resealable:Zipper profiles and adhesive-based peel-and-reseal structures extend product usable life across multi-serve frozen vegetables and proteins. Midwest and Southeast grocery chains are vertically integrating private-label sourcing, creating captive demand for resealable lidding.
- Heat-Sealed:Induction or conduction sealing of lidding film to formed trays provides hermetic integrity for vacuum skin and modified atmosphere applications. Pacific Northwest seafood processors are adopting heat-sealed barrier structures at pilot scale.
- Twist-Off:Threaded closures on rigid containers for frozen concentrates and desserts allow measured dispensing. The format is losing share to flexible alternatives in freight efficiency optimization.
- Snap-On:Press-fit lids on hinged containers serve institutional foodservice channels where automated dispensing systems require dimensional consistency. K-12 and healthcare buyers are driving specification standardization.
Heat-Sealed closures dominate protein tray applications. Resealable formats are expanding most quickly in private-label retail.
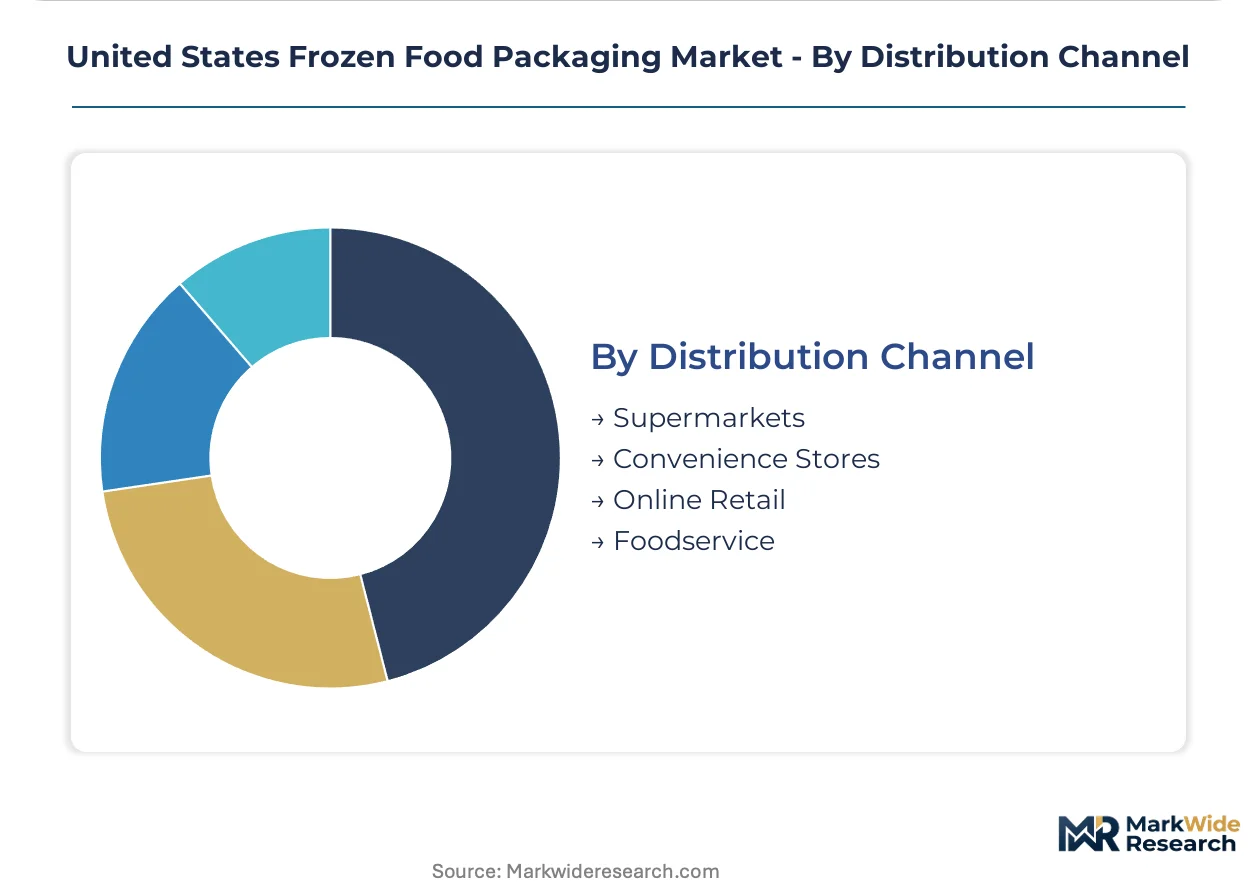
Distribution Channel:
Customer type segmentation separates high-volume institutional procurement from fragmented retail assortment complexity, with channel-specific packaging formats diverging on graphics, case counts, and palletization standards.
- Supermarkets:Freezer-aisle facing requirements drive shelf-ready case formats with vertical stackability and front-facing graphics. Texas and Florida chains are reconfiguring aisle layouts to accommodate display-ready printed cartons.
- Convenience Stores:Limited freezer footprint demands compact case cubes and single-serve or small multi-serve portion formats. Modular portion packs are fragmenting bulk formats into flexible SKU configurations.
- Online Retail:Direct-to-consumer fulfillment requires insulated shipper compatibility and damage resistance through last-mile handling. California's Central Valley processors are piloting on-site packaging integration to reduce transport-stage cold chain losses.
- Foodservice:Institutional buyers in K-12, healthcare, and hospitality specify hinged-lid containers compatible with automated dispensing and bulk thawing protocols. Pactiv Evergreen anchors this channel with formed container supply.
Supermarkets command the largest installed base. Online Retail is climbing the fastest as cold chain infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frozen food packaging in the United States traces its industrial lineage to post-war refrigeration infrastructure buildouts along the Great Lakes and California's agricultural valleys, where cold storage networks enabled year-round produce distribution and standardized barrier packaging formats.
California
California's Central Valley hosts the densest concentration of frozen fruit and vegetable processing in North America, driving demand for high-throughput vertical form-fill-seal lines and on-site packaging integration. The state's Safe Drinking Water and Toxic Enforcement Act imposes chemical disclosure mandates that exceed baseline FDA food contact substance rules, forcing national brands into compliance frameworks that reshape material selection. Fresno and Modesto processing corridors are piloting vacuum skin tray systems for premium protein segments.
Texas
Texas grocery chains are reconfiguring freezer aisle layouts fastest among US states, displacing corrugated shippers with shelf-ready printed cartons to reduce back-of-store labor costs. Gulf Coast petrochemical corridors concentrate polyethylene and polypropylene resin supply, exposing converters to hurricane-season disruption and rail bottlenecks. Dallas-Fort Worth distribution hubs are consolidating frozen SKU assortment around display-ready case formats with vertical stackability.
Florida
Florida's convenience store density drives demand for compact case cubes and modular portion packs that fragment bulk frozen formats into flexible single-serve configurations. The state's absence of state-level chemical disclosure mandates simplifies material qualification pipelines compared to California. Miami-Dade cold chain infrastructure supports Latin American export volumes, with Port Everglades handling reefer container throughput for frozen seafood packaging specifications.
Pacific Northwest
Pacific Northwest seafood processors are adopting multi-layer coextrusion with ethylene vinyl alcohol barrier cores at pilot scale, compressing supply chain steps while maintaining sensory quality through distribution. Oregon's extended producer responsibility legislation is creating binding frozen food supply chain obligations that favor early compliance investments. Seattle-Tacoma metropolitan area converters are retooling extrusion lines for shorter runs as retailers demand SKU flexibility without full-case commitments.
Midwest
Midwest grocery chains are vertically integrating frozen ready-meal sourcing, creating captive demand for resealable lidding and printed cartons across Illinois, Ohio, and Michigan. The region's thermoforming asset base faces capital intensity in upgrading formed tray lines for thinner-gauge, higher-barrier structures. Chicago distribution networks anchor foodservice channel supply for institutional buyers in K-12 and healthcare adopting hinged-lid containers compatible with automated dispensing systems.
United States Frozen Food Packaging Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with film extrusion and thermoforming capabilities under single ownership. Three archetypes dominate: integrated resin-to-package converters controlling barrier coextrusion networks, foodservice specialists anchoring institutional channels with formed container supply, and flexible packaging houses serving retail private-label expansion. M&A activity concentrates on acquiring resealable lidding technology and vacuum skin tray system capabilities, while capacity expansion targets California's Central Valley and Texas distribution corridors.
Among integrated packaging conglomerates, Amcor Plc and Sealed Air Corporation exemplify the multi-material, multi-territory archetype with established positions across barrier film and formed tray segments. Pactiv Evergreen Inc. occupies a distinct position as the foodservice channel anchor, representing the institutional-specialist model with hinged-lid container supply for K-12 and healthcare buyers. These three companies illustrate the strategic divergence between retail-facing flexible packaging and foodservice rigid container requirements.
| Leading Market Players |
|---|
| Amcor Plc |
| Pactiv Evergreen Inc. |
| Sealed Air Corporation |
| Graphic Packaging International |
| Smurfit WestRock |
| Sonoco Products Company |
| Berry Global Inc. |
| ProAmpac |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
Midwest grocery chain procurement concentration anchors contract-based long-term offtake agreements, with private-label vertical integration compressing spot-market flexibility for converters serving retail channels.
Pricing Analysis
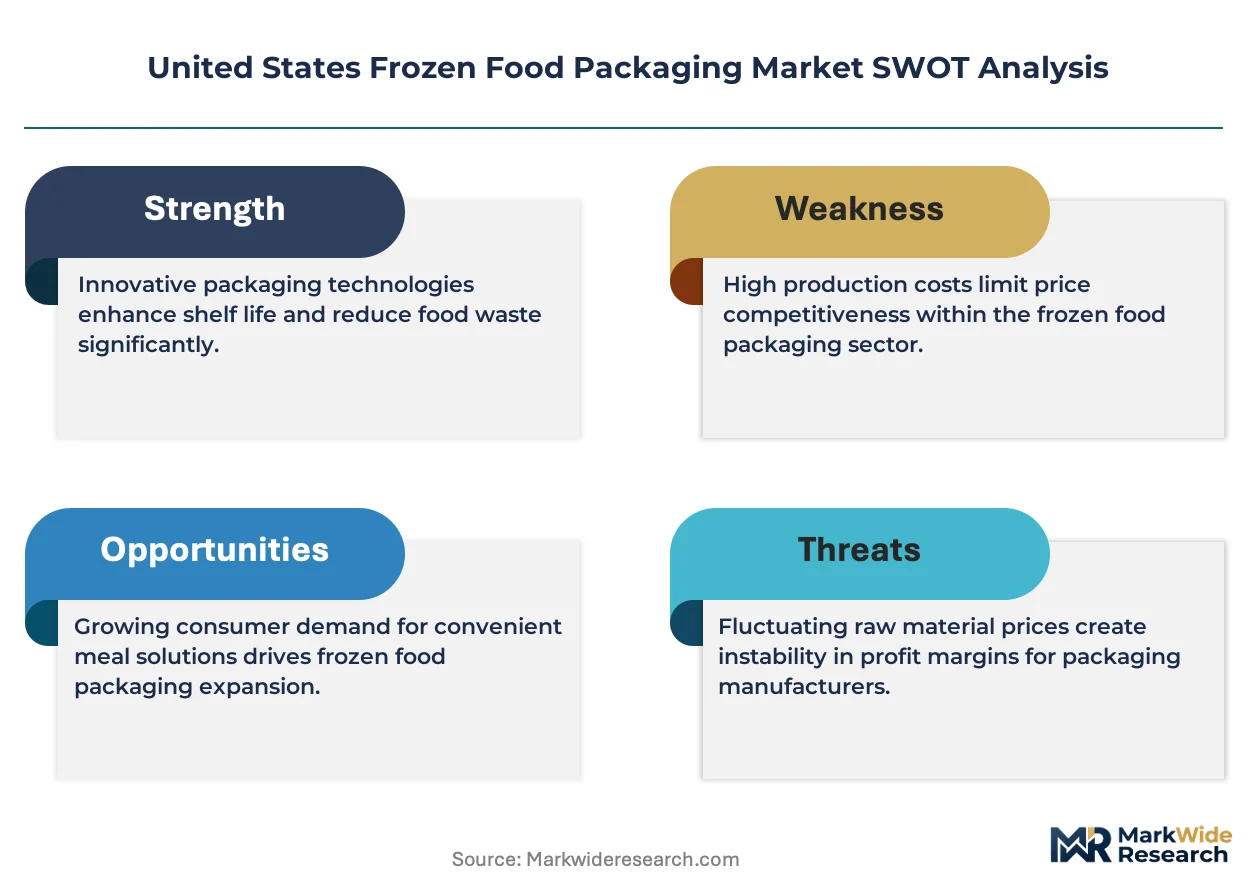
Three-tier pricing structure across premium, standard, and economy levels segments the market by barrier performance and microwave compatibility. Price differentiation separates vacuum skin tray systems with ethylene vinyl alcohol cores from commodity polyethylene bags. Pricing pressure stems from California's Safe Drinking Water and Toxic Enforcement Act compliance costs cascading through national supply chains. Foodservice institutional buyers exhibit lowest price sensitivity due to specification lock-in, while convenience store operators face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast petrochemical corridors for polyethylene and polypropylene resin supply. Raw material dependencies center on ethylene feedstock from natural gas liquids, ethylene vinyl alcohol barrier resin imports, and metallized film substrates. Hurricane-season disruption and rail bottlenecks constitute the dominant structural risk. Distribution runs through California's Central Valley processing corridor for frozen fruit and vegetable volumes, with Texas distribution hubs consolidating retail-facing SKU assortment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's tightened polyethylene migration limits function as a regulatory compounder, forcing additive package revalidation investments that favor converters with established laboratory relationships and documentation protocols.
For Market Incumbents: Extend barrier coextrusion capabilities into vacuum skin tray systems for Pacific Northwest seafood processors, defending against emerging flexible packaging houses. Deepen captive supply of ethylene vinyl alcohol films through backward integration into resin sourcing partnerships. Prioritize California chemical disclosure compliance as a channel control lever against national brands distributing across state lines. For New Entrants and Emerging Players: Launch via foodservice channel automation specifications for K-12 and healthcare hinged-lid containers, where incumbent concentration remains penetrable. Target online retail fulfillment infrastructure in California's Central Valley, where on-site packaging integration reduces transport-stage cold chain losses. Pursue resealable lidding technology licensing as the primary go-to-market angle against Midwest grocery chain private-label expansion. For Investors and Strategic Acquirers: Integrated packaging conglomerates with film extrusion and thermoforming capabilities under single ownership are the most active acquirer in this space, consolidating resealable lidding technology and vacuum skin tray system capabilities. Long-term viability hinges on extended producer responsibility legislation migration from Oregon and Maine into binding frozen food supply chain obligations. Watch for EPA recycled content standard enforcement timelines as the inflection indicator for post-consumer feedstock validation cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coextrusion Capacity Expansion | Ethylene vinyl alcohol core integration compresses supply chain steps for Pacific Northwest seafood processors. |
| Resealable Lidding Technology Acquisition | Midwest and Southeast grocery chain private-label sourcing creates captive demand for zipper profile integration. |
| California Compliance Infrastructure Buildout | Safe Drinking Water and Toxic Enforcement Act mandates exceed baseline FDA rules for national brand distribution. |
| Foodservice Channel Automation Partnership | K-12 and healthcare institutional buyers specify hinged-lid containers compatible with dispensing systems. |
| Post-Consumer Feedstock Validation Program | EPA recycled content standards for food-contact plastics require certified polymer stream qualification overhead. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converters, frozen food processors, retail category buyers, and regulatory compliance officers alongside secondary validation. FDA food contact substance notification databases, EPA recycled content guidance documents, California Office of Environmental Health Hazard Assessment chemical lists, and trade customs records provided foundational inputs. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting distributed value across material tiers, closure types, and distribution channels with California regulatory exposure treated as a distinct risk-adjustment dimension. CAGRs derived from fitted growth curves applied to base-year estimates, with barrier coextrusion adoption rates and extended producer responsibility implementation timelines serving as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA migration limit enforcement acceleration or Gulf Coast hurricane disruption severity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Food Green Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
Burger Boxes Market