
 Meal Kit Packaging Market | 2026-2036
Meal Kit Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Meal Kit Packaging Market Foresight
North American corrugated board producers are restructuring capacity to serve cold-chain meal kit fulfillment. Amcor plc leverages its film extrusion network to supply barrier lidding for protein trays. WestRock Company anchors the corrugated box segment through integrated containerboard mills. Sealed Air competes with automated packaging systems that reduce void fill and dimensional weight.
Meal kit packaging encompasses temperature-stabilizing enclosures, typically incorporating insulating liners, gel packs, and moisture-resistant barriers engineered to maintain food safety between 2°C and 8°C for 24 to 48 hours. Its primary commercial purpose is to preserve ingredient freshness and prevent cross-contamination during last-mile delivery to residential addresses. Cardboard boxes dominate unit volume due to recyclability and printability for brand differentiation, while insulated multi-compartment designs command premium positioning among meal subscription services. Biodegradable films are gaining structural attention as food brands face extended producer responsibility mandates.
The EPA regulates municipal solid waste streams that absorb discarded meal kit components, while FDA food contact substance notifications govern adhesive and coating migration limits. The EU F-Gas Regulation constrains synthetic refrigerant use in gel packs, pushing suppliers toward phase-change materials. Stakeholders must monitor how state-level extended producer responsibility laws in California and Maine reshape cost allocation between packaging converters and meal kit brands.
Market Dynamics
Extended producer responsibility mandates across Europe and North America are forcing meal kit brands to internalize end-of-life packaging costs, triggering wholesale redesign of cold-chain enclosures toward mono-material and fiber-based systems.
Growth Catalysts
- EU Green Deal compliance deadlines:Food contact packaging specifications under REACH are accelerating substitution of multi-layer plastics with recyclable fiber alternatives.
- Home-centric consumption patterns:Residential meal delivery penetration in Germany, France, and the United Kingdom is expanding insulated packaging procurement volumes.
- Phase-change material innovation:Gel pack suppliers are displacing synthetic refrigerants constrained by the EU F-Gas Regulation with bio-based thermal stabilizers.
Market Restraints
- Containerboard input cost volatility:Kraft linerboard pricing fluctuations compress corrugated converter margins during peak agricultural harvest seasons.
- Adhesive migration compliance:FDA food contact substance notification timelines extend product development cycles for barrier coating formulations.
- Film extrusion supply concentration:Barrier lidding capacity clusters in Germany and the Netherlands, creating geographic vulnerability for southern European meal kit brands.
Strategic Opportunities
- Maine and California EPR legislation:State-level extended producer responsibility laws create first-mover advantage for packaging-as-a-service models.
- Rural last-mile consolidation:Third-party logistics providers in the United Kingdom are piloting reusable thermal container pooling systems for subscription meal delivery.
- Compostable film certification:TÜV Austria and BPI industrial composting standards enable premium positioning for biodegradable multi-layer structures.
Industry Challenges
- Cold-chain engineering talent scarcity:Thermal modeling expertise for 48-hour temperature stability sits concentrated with pharmaceutical packaging specialists.
- Legacy warehouse management integration:Automated packaging line retrofits face interoperability friction with existing order fulfillment software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Kit Packaging Market |
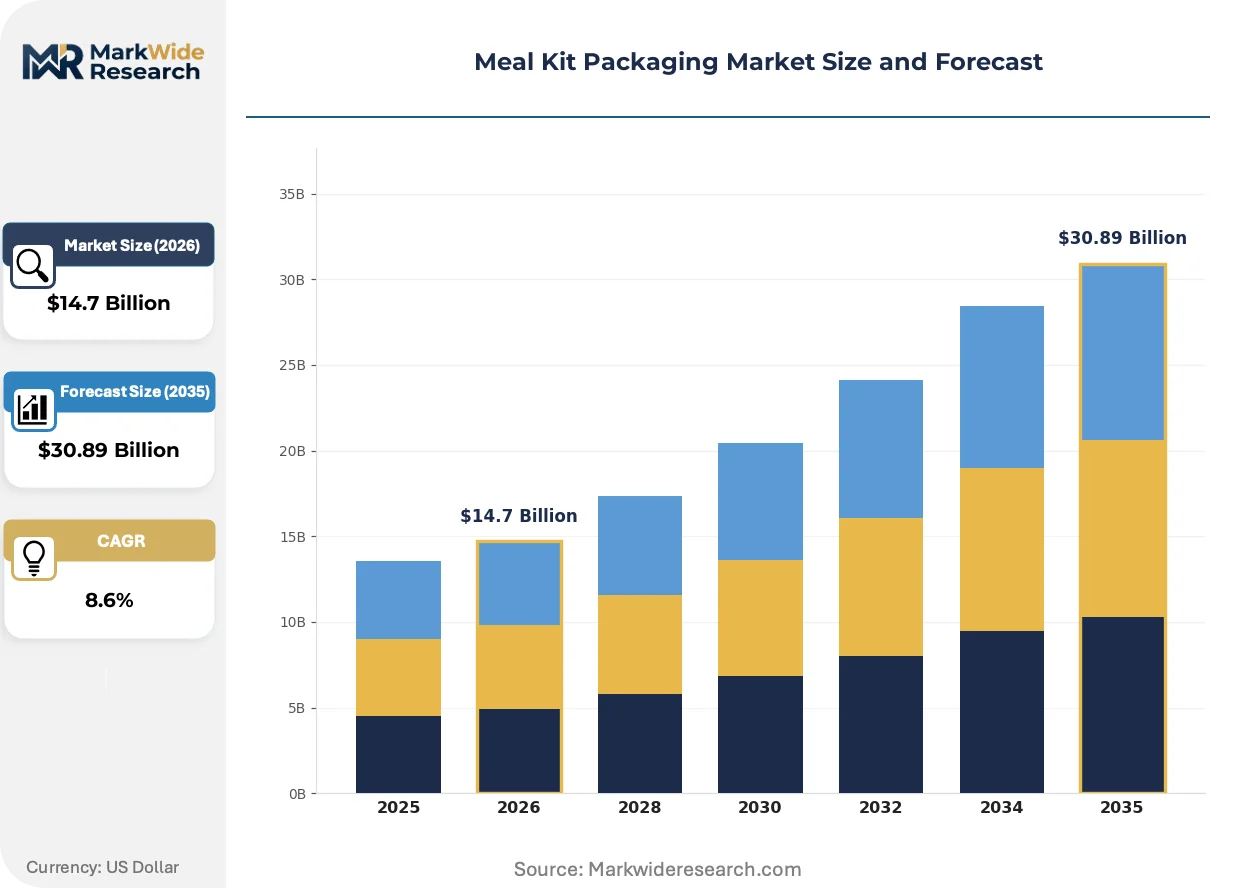
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cardboard Boxes, Resealable Bags, Glass Containers, Plastic Tubs Material: Paper, Plastic, Biodegradable Films, Aluminum End User: Retail Customers, Food Service Providers, Meal Subscription Services, E-commerce Platforms Design Feature: Eco-Friendly, Portion Control, Insulated, Multi-Compartment |
| Companies Covered | Amcor plc, WestRock Company, Sealed Air, Berry Global Inc., Huhtamaki, International Paper, DS Smith, Ball Corporation, Genpak LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Kit Packaging Market Shifts & Advancements
Active redesign of meal kit enclosures centers on disassembling complex multi-material structures into separable, single-stream recyclable components without sacrificing thermal performance.
Plant-fiber insulating liners are modularizing cold-chain architecture. Molded pulp suppliers in Sweden and Finland are engineering corrugated-compatible inserts that replace expanded polystyrene. Meal subscription services in Denmark and the Netherlands are piloting these structures for 24-hour protein preservation. The technology is modularizing supplier relationships, allowing brands to decouple thermal performance from box manufacturing.
The EU F-Gas Regulation constrains hydrofluorocarbon refrigerants in gel packs. Suppliers are reformulating phase-change materials around salt hydrates and bio-derived fatty acids. Protein-focused meal kit brands face compressed formulation timelines to maintain 2°C to 8°C stability. German cold-chain logistics providers are accelerating qualification of non-synthetic alternatives ahead of 2030 phase-down milestones.
Buyer consolidation among meal subscription platforms is compressing packaging specification cycles. Procurement teams at leading services now mandate annual sustainability reporting aligned with CSRD disclosure requirements. Tier-two meal kit brands face exclusion from preferred supplier lists without certified recyclable or compostable packaging portfolios. France and Belgium exhibit the most aggressive supplier consolidation, with three platforms controlling majority procurement volume.
Meal Kit Packaging Market Segmentation
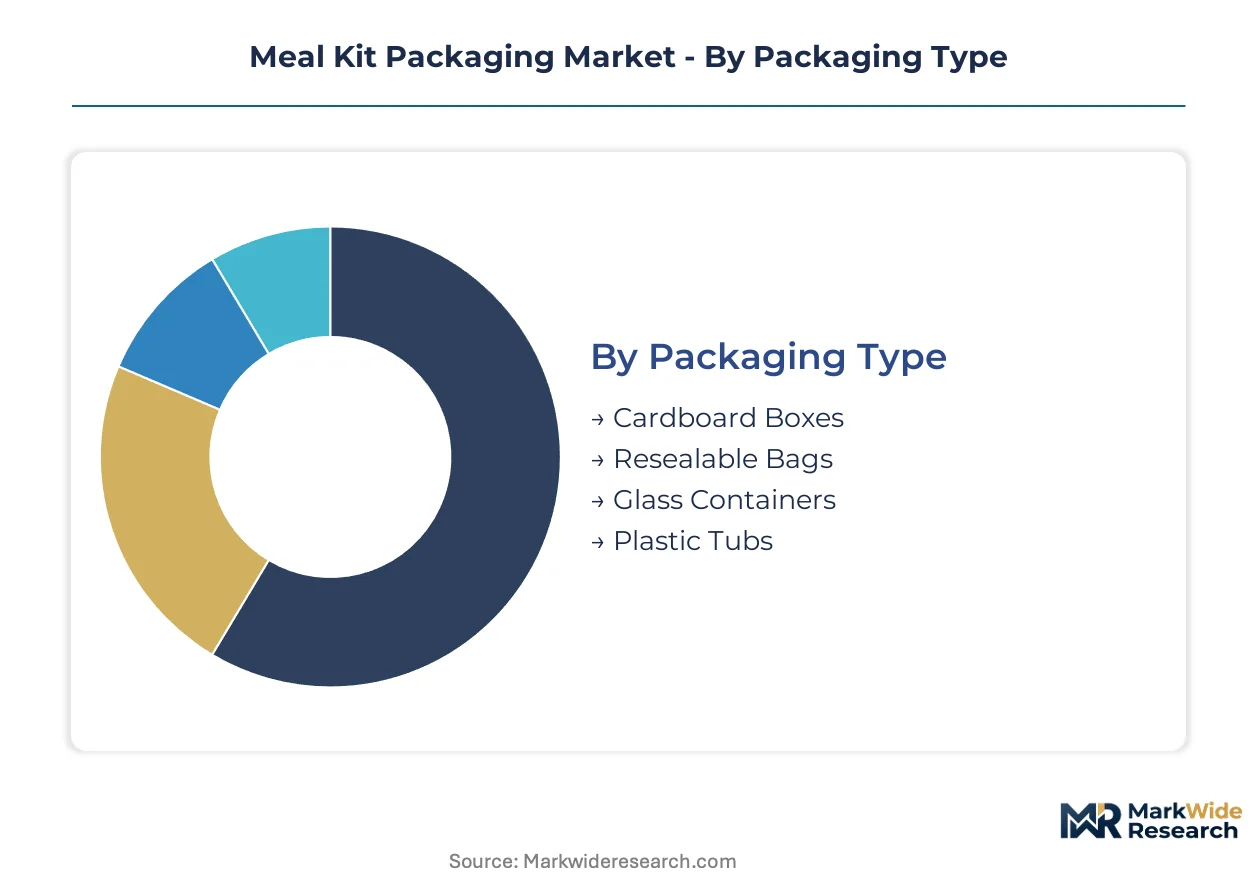
Meal kit packaging procurement decisions cascade across material specifications, thermal engineering requirements, and end-of-life compliance obligations. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape supplier relationships and brand positioning strategies.
Packaging Type:
Corrugated converter capacity concentrates in Germany, Sweden, and the Netherlands, with integrated mills controlling linerboard supply for temperature-stabilized enclosures.
- Cardboard Boxes:Double-walled corrugated structures with PE-coated barriers dominate unit volume across European meal subscription services. Kraft linerboard from Swedish mills supplies Danish and Dutch brands navigating CSRD disclosure requirements for recyclable portfolios.
- Resealable Bags:Multi-layer barrier films with zip-lock closures preserve ingredient moisture for protein and produce segments. German film extruders in Baden-Württemberg serve centralized procurement teams at French and Belgian platforms consolidating supplier lists.
- Glass Containers:Borosilicate and soda-lime jars target premium positioning within organic meal kits. Weight and breakage constraints limit deployment to short-radius urban delivery zones.
- Plastic Tubs:PP and PET thermoformed trays with modified atmosphere barriers extend shelf life for ready-to-cook components. Italian converters supply southern European brands facing REACH compliance deadlines for food contact substances.
Today's leader: Cardboard Boxes. Tomorrow's challenger: Resealable Bags.
Material:
Raw material sourcing patterns determine compliance exposure across REACH, F-Gas Regulation, and emerging extended producer responsibility frameworks.
- Paper:Unbleached kraft and molded pulp formats from Finnish suppliers displace expanded polystyrene in insulated liner applications. German logistics providers pilot corrugated-compatible pulp inserts for 24-hour protein preservation.
- Plastic:Multi-layer barrier structures incorporating EVOH and PA6 face substitution pressure under EU Green Deal circularity targets. Dutch compounders reformulate for mono-material recyclability without sacrificing oxygen transmission rates.
- Biodegradable Films:PLA and PBAT blends certified to TÜV Austria industrial composting standards command price premiums. French meal kit platforms mandate certified compostable portfolios for preferred supplier qualification.
- Aluminum:Foil laminates and trays deliver absolute barrier performance for aromatic ingredients. Energy-intensive production concentrates with Norwegian and Icelandic smelters serving Nordic premium brands.
Paper holds volume leadership. Biodegradable Films are climbing the fastest on regulatory tailwinds.
End User:
Procurement scale and specification complexity vary sharply across direct-to-consumer and institutional channels.
- Meal Subscription Services:Centralized buyers at three dominant French and Belgian platforms drive consolidated packaging specifications. Annual sustainability reporting aligned with CSRD requirements now gates supplier inclusion.
- Retail Customers:Supermarket private-label meal kits demand print-optimized corrugated with shelf-ready merchandising features. UK grocers specify FSC-certified board for consumer-facing sustainability claims.
- Food Service Providers:Contract caterers and hospitality groups prioritize portion-controlled, tamper-evident formats for operational efficiency. German institutional kitchens specify dishwasher-safe reusable containers under municipal waste reduction contracts.
- E-commerce Platforms:Generalist food delivery marketplaces require packaging compatible with third-party logistics thermal standards. UK rural consolidation pilots test reusable container pooling for subscription meal delivery.
Meal Subscription Services anchor current procurement volume. E-commerce Platforms present the steepest expansion trajectory as platform food delivery penetrates residential addressable markets.
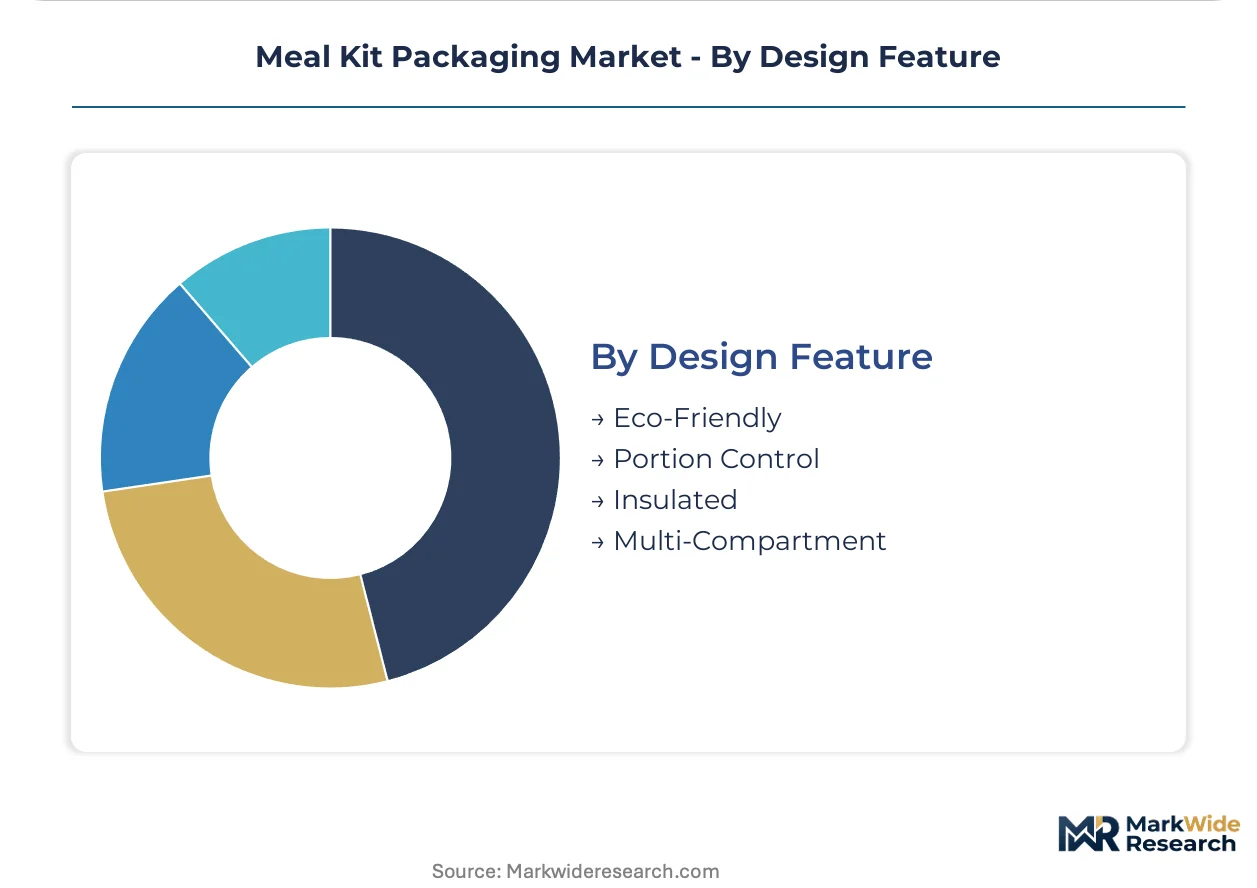
Design Feature:
Engineering trade-offs between thermal performance, disassemblability, and end-of-life processing dominate specification evolution.
- Insulated:Phase-change material integration with plant-fiber or vacuum-insulated panels maintains 2°C to 8°C stability for 48 hours. German cold-chain logistics providers accelerate qualification of bio-based thermal stabilizers ahead of F-Gas Regulation phase-down milestones.
- Eco-Friendly:Separable mono-material constructions and certified compostable films align with extended producer responsibility cost internalization. Swedish molded pulp suppliers engineer corrugated-compatible inserts replacing synthetic refrigerant-dependent systems.
- Multi-Compartment:Partitioned structures prevent cross-contamination between proteins, produce, and sauces. Danish brands pilot modular designs allowing thermal performance decoupling from box manufacturing.
- Portion Control:Pre-measured ingredient cavities reduce food waste and simplify consumer preparation. UK subscription services specify gram-accurate compartments for calorie-conscious positioning.
Insulated formats command premium positioning. Eco-Friendly engineering is gaining share fastest as EPR mandates reshape cost allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cold-chain packaging investment toward jurisdictions with phased-in extended producer responsibility timelines, as meal kit brands seek to defer compliance costs while maintaining EU market access.
Germany
Centralized procurement at Berlin and Hamburg headquarters drives consolidated specifications for insulated corrugated enclosures. The Packaging Act (VerpackG) mandates dual-system participation fees that scale with non-recyclable content, accelerating fiber-based thermal liner adoption. Baden-Württemberg film extruders supply barrier lidding to French and Belgian platforms consolidating supplier lists.
United States
California and Maine extended producer responsibility laws are creating first-mover advantage for packaging-as-a-service models in subscription meal delivery. EPA municipal solid waste regulations govern discarded kit component streams, while FDA food contact substance notifications extend barrier coating development cycles. Pacific Northwest molded pulp suppliers pilot corrugated-compatible inserts for 24-hour protein preservation.
France
Three dominant meal subscription platforms in Paris and Lyon control majority procurement volume, mandating annual CSRD-aligned sustainability reporting for supplier qualification. The Anti-Waste Law (AGEC) imposes plastic reduction targets that favor certified compostable film portfolios. Auvergne-Rhône-Alpes logistics providers test reusable thermal container pooling for rural last-mile consolidation.
United Kingdom
Supermarket private-label meal kits demand FSC-certified corrugated with shelf-ready merchandising features for retail channel penetration. Third-party logistics providers in the Midlands pilot reusable thermal container pooling systems for subscription delivery. UK grocers specify print-optimized board for consumer-facing sustainability claims at point-of-sale.
Sweden
Finnish and Swedish molded pulp suppliers engineer corrugated-compatible inserts displacing expanded polystyrene in insulated liner applications. The Swedish Environmental Protection Agency's extended producer responsibility framework internalizes end-of-life costs earlier than southern European counterparts. Stockholm-based logistics providers accelerate qualification of bio-based phase-change materials ahead of EU F-Gas Regulation phase-down milestones.
Meal Kit Packaging Market Competitive Landscape
North American integrated paperboard producers anchor one tier; European specialty converters and film extruders hold differentiated positions in barrier and thermal engineering. The vendor base separates into consolidated containerboard mills, mid-cap molded pulp specialists, and niche phase-change material formulators. Three archetypes dominate: integrated paperboard suppliers with captive linerboard supply, specialty film extruders serving centralized procurement teams, and thermal engineering boutiques qualifying bio-based refrigerant alternatives. Capacity expansion and portfolio diversification toward mono-material recyclability represent the dominant competitive vectors.
Within the integrated packaging tier, Amcor plc and WestRock Company exemplify divergent strategic positions. Amcor leverages film extrusion networks to supply barrier lidding for protein tray applications, occupying a position aligned with centralized European procurement consolidation. WestRock anchors corrugated box supply through integrated containerboard mill control, representing the scale-driven archetype in temperature-stabilized enclosure manufacturing. Sealed Air sits within the automation and systems tier, competing through equipment solutions that reduce void fill and dimensional weight in fulfillment operations.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Sealed Air |
| Berry Global Inc. |
| Huhtamaki |
| International Paper |
| DS Smith |
| Ball Corporation |
| Genpak LLC |
| Others |
Supply & Pricing Matrix
EU Green Deal compliance deadlines gate qualified supply for cold-chain meal kit enclosures, restricting premium-tier pricing access to converters with certified recyclable portfolios and REACH-compliant barrier formulations. This regulatory filtering concentrates pricing power among integrated paperboard mills and specialty film extruders while excluding tier-two suppliers from preferred procurement lists at centralized buyers.
Pricing Analysis
Direct-to-OEM contract structures dominate procurement relationships between meal subscription platforms and packaging converters, with volume-scale discounts and annual sustainability reporting requirements as standard terms. Price differentiation rests on CSRD-aligned certification tiers and thermal performance specifications, where 48-hour phase-change stability commands measurable premiums over 24-hour alternatives. Cost compression in corrugated converter margins is intensifying because kraft linerboard input volatility during peak agricultural harvest seasons. Retail customers exhibit the highest price sensitivity due to shelf-ready merchandising feature requirements, while meal subscription services prioritize thermal reliability over unit cost.
Supply Chain Analysis
TÜV Austria and BPI industrial composting certifications gate supplier qualification for French and Belgian meal kit platforms consolidating procurement lists around certified portfolios. Geographic supply concentration centers on Germany, Sweden, and the Netherlands for corrugated board and molded pulp thermal liners, with Baden-Württemberg film extruders serving barrier lidding demand. Raw material dependencies draw from Finnish kraft linerboard, German EVOH barrier compounds, and Nordic molded pulp feedstocks. Single-source vulnerability runs through concentrated gel pack phase-change material suppliers facing EU F-Gas Regulation reformulation timelines. Distribution feeds from integrated mill networks through centralized logistics hubs serving Paris, Berlin, and London metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement consolidation among three dominant French and Belgian platforms is filtering supplier access toward premium thermal engineering and certified sustainable portfolios.
For Market Incumbents: Anticipate margin compression from bio-based phase-change material substitution mandates and respond by securing captive linerboard supply through backward integration into Swedish or Finnish pulp assets. Invest in automated packaging line retrofits that reduce dimensional weight and void fill to defend positioning against Sealed Air's systems-tier competition. Prioritize REACH-compliant barrier coating R&D to compress FDA notification timelines for multi-layer film alternatives. For New Entrants and Emerging Players: Rural last-mile consolidation pilots in the United Kingdom present an underserved buyer archetype with reusable thermal container pooling systems for subscription meal delivery. Target third-party logistics providers in the Midlands and Auvergne-Rhône-Alpes seeking decoupled thermal performance from box manufacturing. Enter through compostable film certification partnerships with TÜV Austria to bypass incumbent qualification barriers at tier-one platforms. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap molded pulp specialists because EU extended producer responsibility mandates are accelerating fiber-based thermal liner substitution for expanded polystyrene. Position for five-to-ten year horizon consolidation as CSRD disclosure requirements and F-Gas Regulation phase-down milestones reshape supplier tiering. Monitor German cold-chain logistics provider qualification timelines for bio-based phase-change materials as inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Assets | Captive kraft linerboard supply secures margin stability against harvest-season volatility for corrugated converters. |
| Automated Packaging Line Deployment | Sealed Air's dimensional weight reduction technology pressures legacy fulfillment infrastructure at meal kit brands. |
| Bio-Based Phase-Change Material Qualification | German logistics providers accelerate non-synthetic refrigerant adoption ahead of EU F-Gas Regulation milestones. |
| Compostable Film Certification Investment | TÜV Austria and BPI standards enable premium positioning for French meal kit platform supplier qualification. |
| Reusable Thermal Container Pooling Pilot | UK third-party logistics providers test rural last-mile consolidation models for subscription delivery economics. |
Research Methodology
Direct dialogue with packaging procurement directors at meal subscription platforms, corrugated converter operations managers, cold-chain logistics engineers, and regulatory compliance officers anchored qualitative findings. Secondary validation drew from EU Packaging Act implementation records, FDA food contact substance notification databases, ECHA REACH registration dossiers, and Swedish Environmental Protection Agency extended producer responsibility frameworks. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level value outputs derived from material specifications, thermal engineering tiers, end-user procurement scale, and regional regulatory cluster variations. The analytical framework modeled packaging type, material composition, design feature complexity, and geographic compliance exposure throughout the forecast period. CAGRs were computed from annual procurement volume trajectories at leading meal subscription services and input cost indices for kraft linerboard and barrier film compounds.
Underlying measurement precision varies by segment; biodegradable films and phase-change material innovations carry wider uncertainty bands than established corrugated and plastic tub categories. Forecasts reflect assumptions about EU Green Deal implementation pacing and state-level extended producer responsibility adoption in California and Maine. A model refresh is warranted upon material change in F-Gas Regulation phase-down timelines or breakthrough qualification of salt hydrate thermal stabilizers at German cold-chain logistics providers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Wooden Cutlery Market