
 Foam Food Container Market | 2026-2036
Foam Food Container Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Food Container Market Foresight
The foam food container industry is repositioning around a sharp split between premium insulated packaging and commodity-grade disposables. Dart Container Corporation leverages its captive resin sourcing and thermoforming scale to dominate the North American clamshell segment. Huhtamaki Group anchors its position through integrated fiber and foam operations across multiple continents. Genpak LLC differentiates by specializing in dual-ovenable and cut-resistant formulations for prepared food channels.
A foam food container is a molded cellular structure, typically fabricated from expanded polystyrene beads fused under steam pressure to achieve thermal insulation values between 0.030 and 0.040 W/m·K, designed to maintain food temperature and prevent moisture loss during transport. Clamshell boxes and soup containers carry the deepest margin pools because they command specification-driven pricing from fast food chains and delivery aggregators. Polyethylene foam trays are gaining share in protein packaging applications where puncture resistance and drip absorption outweigh cost minimization. Biodegradable foam variants remain niche but attract R&D concentration from converters seeking preemptive compliance positioning.
The US EPA coordinates with state environmental agencies on extended producer responsibility frameworks that affect polystyrene disposal economics, while the EU REACH regulation and F-Gas Directive constrain hydrocarbon blowing agent chemistries used in foam expansion. India's BIS certification requirements for food-contact materials create non-tariff barriers that favor domestic converters with established testing relationships. Stakeholders must monitor how fragmented municipal bans on single-use foams interact with national packaging harmonization initiatives to anticipate which material platforms will retain channel access.
Market Dynamics
The foam food container market is splitting along a fault line between legacy expanded polystyrene operations facing regulatory extinction costs and next-generation biodegradable foam platforms capturing specification premiums from delivery aggregators and quick-service chains.
Growth Catalysts
- Delivery aggregator procurement:Platform-owned dark kitchens and cloud restaurant networks in urban India are standardizing insulated clamshell specifications for 30-minute delivery guarantees.
- US EPA state-level mandates:Extended producer responsibility frameworks in California, New York, and Washington are redirecting converter capital toward biodegradable foam pilot lines.
- Steam-pressure thermoforming advances:Next-generation bead fusion protocols are cutting cycle times for high-wall soup containers serving Asian noodle chains.
Market Restraints
- Styrene monomer cost volatility:Benzene-naphtha spread compression is squeezing margin on commodity-grade EPS trays used in protein retail.
- Blowing agent chemistry constraints:EU F-Gas Regulation phase-downs on HFC-245fa are forcing reformulation of extruded polyethylene foam for cold-chain applications.
- Fiber-mold substitution threat:Bagasse and bamboo pulp trays from Huhtamaki's fiber operations are capturing quick-service sandwich specifications at cost parity.
Strategic Opportunities
- India BIS certification arbitrage:Domestic converters with established food-contact testing relationships are locking out imports from Southeast Asian competitors.
- Dual-ovenable foam formulations:Convergence of microwave-safe EPS and cut-resistant polyethylene layers is opening prepared-meal channels for retail grocers.
- Municipal procurement mandates:City-level composting infrastructure investments in Pune and Bangalore are creating certified biodegradable foam demand pools.
Industry Challenges
- Bead-to-mold process engineering talent:The shrinking pipeline of steam-pressure thermoforming specialists is extending commissioning timelines for new production lines.
- Legacy equipment retrofit complexity:Converters running 1990s-era shape-molding machines face integration friction with automated stacking and labeling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Food Container Market |
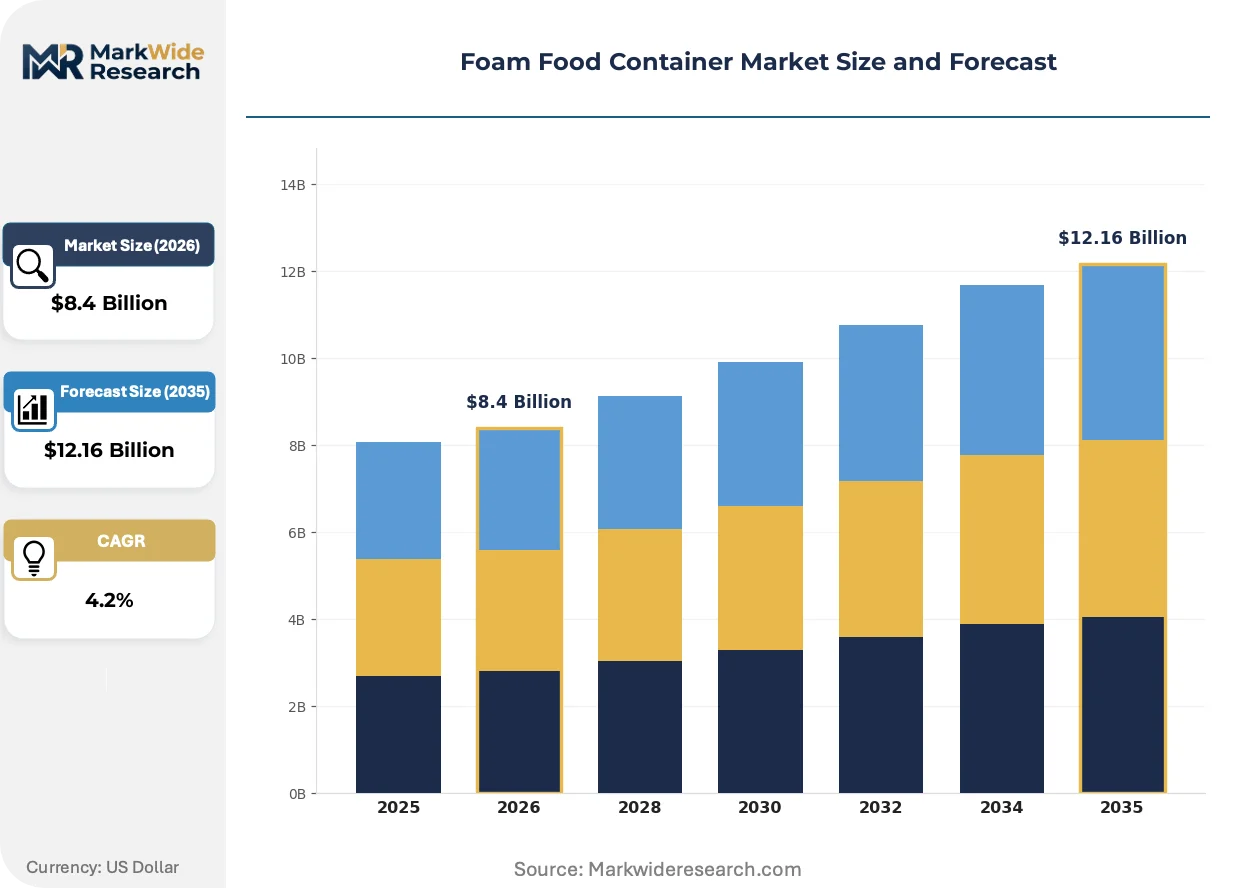
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshell Boxes, Soup Containers, Trays, Bowls, Plates, Lids Material: Expanded Polystyrene, Polyethylene Foam, Polypropylene, Biodegradable Foam, Paper Foam Application: Fast Food Chains, Cafeterias, Catering Services, Food Delivery, Street Vendors, Event Services End User: Restaurants, Food Processing Units, Grocery Stores, Food Packaging Manufacturers, Institutional Kitchens |
| Companies Covered | Placon Corporation, Sealed Air Corporation, Dart Container Corporation, Novolex Holdings, LLC, Winpak Ltd., Genpak LLC, Huhtamaki Group, Berkley International, Pactiv Evergreen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Food Container Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry bans are forcing simultaneous reinvention of foam expansion processes and end-of-life disposal economics across every major production geography.
Biodegradable starch-PLA hybrid foams are decentralizing converter investment away from petrochemical bead supply chains toward agricultural feedstock partnerships. Quick-service chains in Western Europe are piloting these materials for hot-beverage cups at 15-20% specification premiums. The technology is decentralizing production location decisions by enabling smaller-batch regional molding operations near urban consumption clusters.
REACH restrictions on hydrocarbon blowing agents are compelling European converters to shift toward water-blown and CO2-based expansion systems for extruded sheet foam. The industrial consequence is elevated capital intensity for new lines and compressed margins on legacy equipment. Cold-chain meat packaging specifications in Germany and France are most affected, with buyers accepting modest price adjustments to secure compliant supply.
Aggregator-driven consolidated procurement is compressing supplier counts for insulated delivery containers across India's top eight metropolitan markets. Dark kitchen operators are bypassing distributor networks to contract directly with molding specialists for customized clamshell geometries. This pattern is most visible in Mumbai and Delhi NCR, where platform-owned quality audits now override traditional converter certification acceptance.
Foam Food Container Market Segmentation
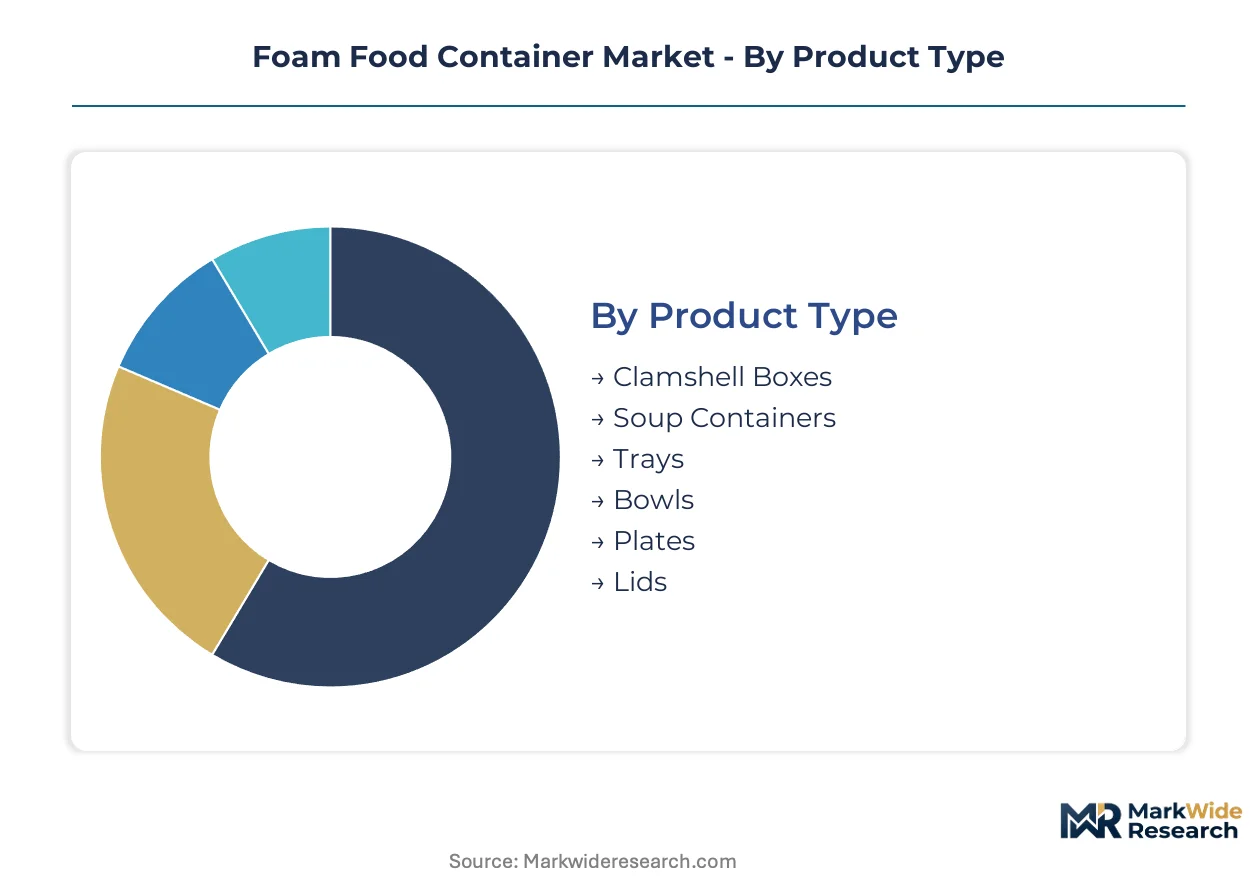
Segmentation in foam food containers tracks how regulatory pressure and delivery-aggregator procurement are fragmenting demand across material platforms and container geometries. Understanding these splits reveals where converter capital earns returns versus where legacy assets face stranded risk.
Product Type:
Container geometry determines thermal performance specifications and automation compatibility in filling-line integration.
- Clamshell Boxes:Hinged-lid cellular structures with 0.030-0.040 W/m·K insulation values maintain food temperature across 30-minute delivery windows. Dark kitchen operators in Mumbai and Delhi NCR are standardizing custom geometries for platform-owned quality audits.
- Soup Containers:High-wall cylindrical designs with fused bead construction prevent moisture loss in Asian noodle chain applications. Steam-pressure thermoforming advances are cutting cycle times for this specification.
- Trays:Flat-bottomed formats dominate protein retail where puncture resistance requirements are rising.
- Bowls:Deep-drawn configurations serve rice-based meal formats in cafeteria and catering channels.
- Plates:Shallow profiles concentrate in event services and institutional procurement with cost-minimization priorities.
- Lids:Separate cover components enable modular pricing and material substitution in hybrid packaging systems.
Volume sits with clamshell boxes; growth tilts toward soup containers.
Material:
Raw material selection now hinges on compliance positioning against municipal bans and extended producer responsibility frameworks.
- Expanded Polystyrene:Steam-fused bead construction delivers lowest unit cost but faces EPA-coordinated state-level phaseouts in California, New York, and Washington. Converter capital is redirecting toward pilot line alternatives.
- Biodegradable Foam:Starch-PLA hybrid formulations command 15-20% specification premiums from quick-service chains in Western Europe. Agricultural feedstock partnerships are decentralizing production location decisions.
- Polyethylene Foam:Extruded sheet formats with HFC-245fa blowing agents face EU F-Gas Regulation reformulation requirements for cold-chain meat packaging in Germany and France.
- Polypropylene:Higher-temperature resistance suits dual-ovenable prepared meal channels for retail grocers.
- Paper Foam:Fiber-based cellular structures bridge composting infrastructure gaps in Pune and Bangalore municipal procurement mandates.
Expanded polystyrene still carries volume; biodegradable foam is climbing the fastest.
Application:
Channel-specific procurement patterns separate specification-driven premium capture from commodity-grade margin compression.
- Food Delivery:Aggregator-owned dark kitchens bypass distributor networks for direct converter contracts with customized clamshell geometries. Quality audits now override traditional certification acceptance.
- Fast Food Chains:System-wide specifications for insulated containers support 30-minute delivery guarantees across urban India.
- Street Vendors:Volume procurement in urban India drives low-cost tray and plate demand with minimal specification complexity.
- Catering Services:Event-scale purchasing favors modular lid-and-base systems for menu flexibility.
- Cafeterias:Institutional procurement prioritizes cost minimization over thermal performance in high-throughput environments.
- Event Services:Seasonal demand patterns favor converters with rapid changeover capabilities on legacy equipment.
Food delivery dominates current volume; street vendors in urban India offer the steepest expansion trajectory.
End User:
Buyer sophistication separates specification-authors from price-takers in converter negotiations.
- Restaurants:Independent and chain operators drive clamshell standardization for delivery-aggregator compliance. Direct contracting patterns are displacing traditional distributor relationships.
- Food Packaging Manufacturers:Converter tier supplying branded food companies with custom-printed and dimensionally precise formats.
- Food Processing Units:Protein packagers specify polyethylene foam trays where puncture resistance and drip absorption outweigh cost minimization.
- Grocery Stores:Prepared-meal retail channels demand dual-ovenable formulations for microwave-safe positioning.
- Institutional Kitchens:Hospital and university procurement favors certified biodegradable foam where municipal composting infrastructure exists.
Restaurants command volume leadership; food processing units are gaining share fastest on protein packaging substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the most aggressive procurement consolidation in foam food container demand, where delivery-aggregator dark kitchens now contract directly with molding specialists for customized clamshell geometries.
United States
California, New York, and Washington state mandates on expanded polystyrene phaseouts are redirecting converter capital toward biodegradable foam pilot lines. The EPA coordinates extended producer responsibility frameworks that reshape disposal economics. Los Angeles and San Francisco municipal procurement now favors certified compostable alternatives.
India
Street vendor ecosystems in Delhi NCR and quick-service restaurant chains drive volume procurement of low-cost trays and plates. BIS certification requirements for food-contact materials create non-tariff barriers favoring domestic converters. Pune and Bangalore municipal composting infrastructure investments are generating certified biodegradable foam demand pools.
Germany
Cold-chain meat packaging specifications in Germany and France are absorbing modest price adjustments for REACH-compliant supply. The EU F-Gas Regulation phase-downs on HFC-245fa are forcing reformulation of extruded polyethylene foam. Industrial clusters in Bavaria and North Rhine-Westphalia host converters shifting toward water-blown expansion systems.
China
Dual carbon goals and provincial environmental enforcement are compressing margins on legacy expanded polystyrene operations. The Yangtze River Delta and Pearl River Delta retain concentration in high-volume thermoforming for export markets. Domestic demand is tilting toward fiber-mold substitutes in premium quick-service channels.
United Kingdom
London's delivery-aggregator procurement is standardizing insulated container specifications for sub-30-minute delivery guarantees. Post-Brexit regulatory divergence from EU REACH is creating uncertainty in blowing agent chemistry compliance. Midlands-based converters are investing in automated stacking systems to serve platform-owned quality audit requirements.
Foam Food Container Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material compliance and thermal performance specifications. The vendor base clusters around three strategic archetypes: integrated resin-to-container operators with captive bead supply, regional molding specialists serving aggregator procurement, and fiber-foam hybrid converters hedging regulatory transition. Dominant competitive moves include backward integration into agricultural feedstock partnerships for biodegradable variants and geographic expansion into India BIS certification arbitrage opportunities.
Within the integrated operator tier, Dart Container Corporation and Huhtamaki Group exemplify scale-driven positioning across multiple continents. Genpak LLC occupies a specialist position in dual-ovenable and cut-resistant formulations. Among North American fabricators, Sealed Air Corporation and Pactiv Evergreen Inc. sit within the premium packaging archetype, while Novolex Holdings, LLC represents diversified foodservice supply positioning.
| Leading Market Players |
|---|
| Placon Corporation |
| Sealed Air Corporation |
| Dart Container Corporation |
| Novolex Holdings, LLC |
| Winpak Ltd. |
| Genpak LLC |
| Huhtamaki Group |
| Berkley International |
| Pactiv Evergreen Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up molding specialists across North America and Europe are consolidating legacy expanded polystyrene assets to extract pricing discipline through captive bead supply and automated thermoforming scale. This ownership pattern tightens margin capture on commodity-grade clamshells while redirecting capital toward biodegradable foam pilot lines that command specification premiums from delivery aggregators.
Pricing Analysis
Throughput-based pricing anchors converter negotiations, where dark kitchen operators in Mumbai and Delhi NCR contract directly for customized clamshell geometries tied to 30-minute delivery guarantees. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified biodegradable foam from REACH-compliant polyethylene formulations and commodity expanded polystyrene. Cost compression in protein retail trays is intensifying because benzene-naphtha spread volatility squeezes styrene monomer margins. Street vendors in urban India exhibit the highest price sensitivity, while quick-service chains in Western Europe accept 15-20% specification premiums for starch-PLA hybrid compliance positioning.
Supply Chain Analysis
Workforce availability for steam-pressure thermoforming specialists concentrates manufacturing gravity in India, China, and Germany, where legacy equipment retrofit expertise extends commissioning timelines for new production lines. Raw material flows draw from agricultural feedstock partnerships for biodegradable variants, petrochemical bead supply chains for expanded polystyrene, and extruded polyethylene sheet operations facing EU F-Gas Regulation reformulation. Single-source vulnerability sits with hydrocarbon blowing agent chemistries constrained by REACH phase-downs. Distribution runs through platform-owned procurement networks that displace traditional distributor relationships in top metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where converters pursue backward integration into resin bead supply or agricultural feedstock partnerships to defend margin capture against regulatory transition costs.
For Market Incumbents: Cement dominance in clamshell standardization by locking aggregator procurement through platform-owned quality audit compliance, while accelerating biodegradable foam pilot line investment ahead of EPA-coordinated state-level phaseouts. Fiber-mold substitution from Huhtamaki's integrated operations represents the most immediate share threat to legacy expanded polystyrene positioning. For New Entrants and Emerging Players: Water-blown expansion technology offers a technology-first wedge into European cold-chain meat packaging specifications where REACH-compliant supply commands modest price adjustments. Target Pune and Bangalore municipal procurement mandates for certified biodegradable foam demand pools, leveraging BIS certification arbitrage to lock out Southeast Asian import competition through established food-contact testing relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional molding specialists with automated stacking capabilities in India's top eight metropolitan markets, where aggregator-driven consolidation compresses supplier counts. Long-term viability hinges on material platform diversification across petrochemical and agricultural feedstock supply chains. Watch EU F-Gas Regulation enforcement intensity as the inflection indicator for polyethylene foam reformulation capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock | Secures starch-PLA supply for biodegradable foam variants ahead of municipal procurement mandates in Pune and Bangalore. |
| Automated Thermoforming Scale-Up | Reduces cycle times for high-wall soup containers serving Asian noodle chains and dark kitchen operators. |
| BIS Certification Investment | Creates non-tariff barriers favoring domestic Indian converters over Southeast Asian competitors in food-contact materials. |
| Water-Blown Expansion System Deployment | Addresses REACH restrictions on hydrocarbon blowing agents for European cold-chain meat packaging compliance. |
| Platform-Owned Quality Audit Compliance | Enables direct contracting with delivery aggregators bypassing traditional distributor networks in Mumbai and Delhi NCR. |
Research Methodology
Document review covered trade customs data, EPA coordination frameworks, EU REACH regulatory filings, and BIS certification records, complemented by interviews with thermoforming plant managers, procurement leads at quick-service chains, dark kitchen operators, and distribution channel partners across India, the United States, and Germany. Secondary validation drew from converter SEC disclosures, state environmental agency mandates, agricultural feedstock partnership announcements, and food-contact testing laboratory reports. Bottom-up volume modeling triangulated against top-down value estimates across material platforms and container geometries.
Historical shipment data cross-referenced with panel input from industry stakeholders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material platform, container geometry, application channel, and end-user sophistication tier. CAGRs derived from curve-fitting approaches applied to disclosed capacity additions, regulatory phaseout timelines, and aggregator procurement consolidation patterns. Forecast inputs incorporated municipal composting infrastructure investment trajectories and steam-pressure thermoforming technology adoption curves.
Several conditions sit outside the modeled scope, including abrupt municipal ban implementations, styrene monomer price spikes beyond historical volatility bands, and aggregator platform exits from dark kitchen operations. Forecasts reflect documented assumptions about regulatory enforcement intensity and feedstock partnership formation rates. A small set of named triggers warrants ongoing watch: EU F-Gas Regulation phase-down acceleration, India BIS certification requirement expansion, and fiber-mold cost parity achievement in quick-service sandwich specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Cupcake Containers Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Honey Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Canned Food Packaging Market