
 Heat Induction Cap Liner Market | 2026-2036
Heat Induction Cap Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Induction Cap Liner Market Outlook
Direct supply agreements between liner converters and multinational pharmaceutical packagers are reconfiguring procurement patterns across the heat induction cap liner value chain. Selig Group leverages its European manufacturing footprint to sustain long-term contracts with branded drug manufacturers. Tekni-Plex Inc. competes through specialized multilayer structures that meet US FDA child-resistance protocols. Well-Pack Industries Co Ltd anchors Asia-Pacific supply with high-volume foil seal liner production for food and beverage exporters.
Heat induction cap liners are composite sealing discs, typically laminating aluminum foil between polymer backing layers, that bond to container rims through electromagnetic induction heating to create hermetic, tamper-evident closures. The aluminum layer melts a heat-seal coating at 120–180°C, forming an oxygen and moisture barrier critical for pharmaceutical stability and food shelf-life extension. Foil seal liners dominate pharmaceutical applications where barrier integrity commands premium positioning, while EPE foam liners retain stronghold in cosmetics where cushioning and resealability drive selection. Polyethylene material grades are displacing PVC across European and North American channels as REACH compliance and recyclability targets reshape formulation preferences.
FDA 21 CFR Part 211 mandates tamper-evident packaging for over-the-counter pharmaceuticals, directly expanding demand for certified induction seal liners in US drug packaging operations. EMA's Annex 1 sterile manufacturing guidelines and EU MDR traceability requirements are converging to push European pharmaceutical packagers toward validated, lot-trackable liner supply chains. REACH restrictions on persistent organic pollutants are accelerating material transitions away from legacy PVC formulations toward polypropylene and polyethylene alternatives. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables, as these testing protocols increasingly determine liner qualification timelines and supplier switching costs.
Market Dynamics
Pharmaceutical serialization mandates are compressing supplier qualification timelines, forcing liner converters to pre-certify multilayer structures against evolving extractables protocols before contract bidding.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:European pharmaceutical packagers are validating lot-trackable liner supply chains to meet traceability requirements, expanding demand for certified induction seal liners in sterile drug packaging.
- Aluminum-backed multilayer structures:These advanced liners are replacing legacy PVC formulations as brands pursue recyclability compliance under REACH restrictions on persistent organic pollutants.
- Food and beverage exporters:High-volume foil seal liner production is accelerating in Asia-Pacific manufacturing hubs to serve extended shelf-life requirements for ocean-freight distribution.
Market Restraints
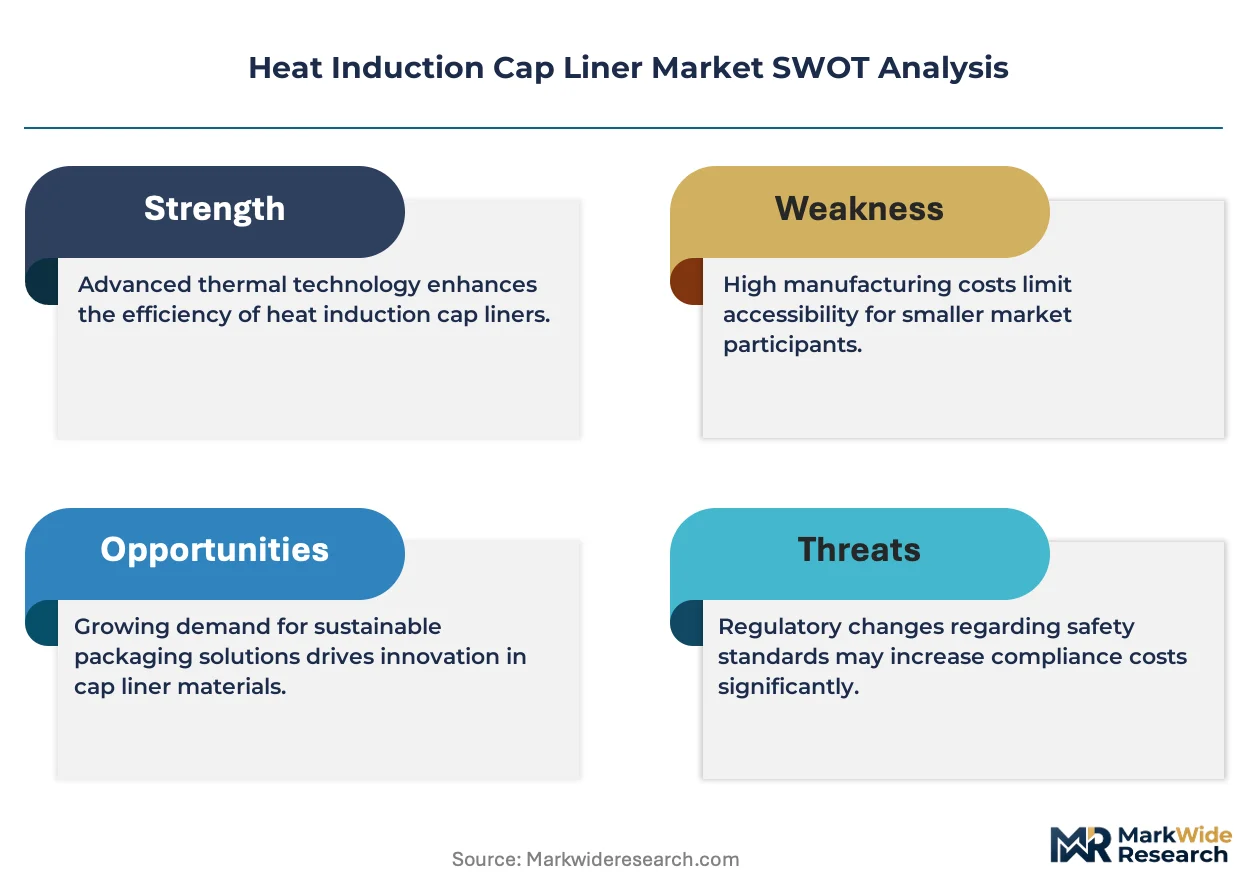
- Aluminum foil price volatility:Raw material cost swings constrain converter margin stability and complicate long-term contract pricing with multinational pharmaceutical packagers.
- German supply concentration:European pharmaceutical and chemical end users depend heavily on a single regional manufacturing anchor, creating geographic vulnerability in liner availability.
- Child-resistance certification complexity:US FDA protocol compliance for multilayer structures extends product development cycles and elevates switching costs for qualified suppliers.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO traceability mandates are creating certified liner demand as domestic drug manufacturers upgrade tamper-evident sealing capabilities for export markets.
- Cosmetics cushioning applications:EPE foam liners with resealability properties represent underpenetrated demand as premium skincare brands differentiate through unboxing experience.
- EU Green Deal circularity incentives:Polyethylene and polypropylene formulation transitions are attracting capital investment as converters position for recyclability-compliant product portfolios.
Industry Challenges
- Extractables and leachables testing expertise:Pharmacopeial qualification timelines are extending as liner suppliers build in-house analytical chemistry capabilities to meet pharmaceutical customer audit requirements.
- Legacy PVC formulation phase-out:Supply chain reconfiguration friction is intensifying as converters simultaneously manage REACH compliance deadlines and existing customer contract obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Induction Cap Liner Market |
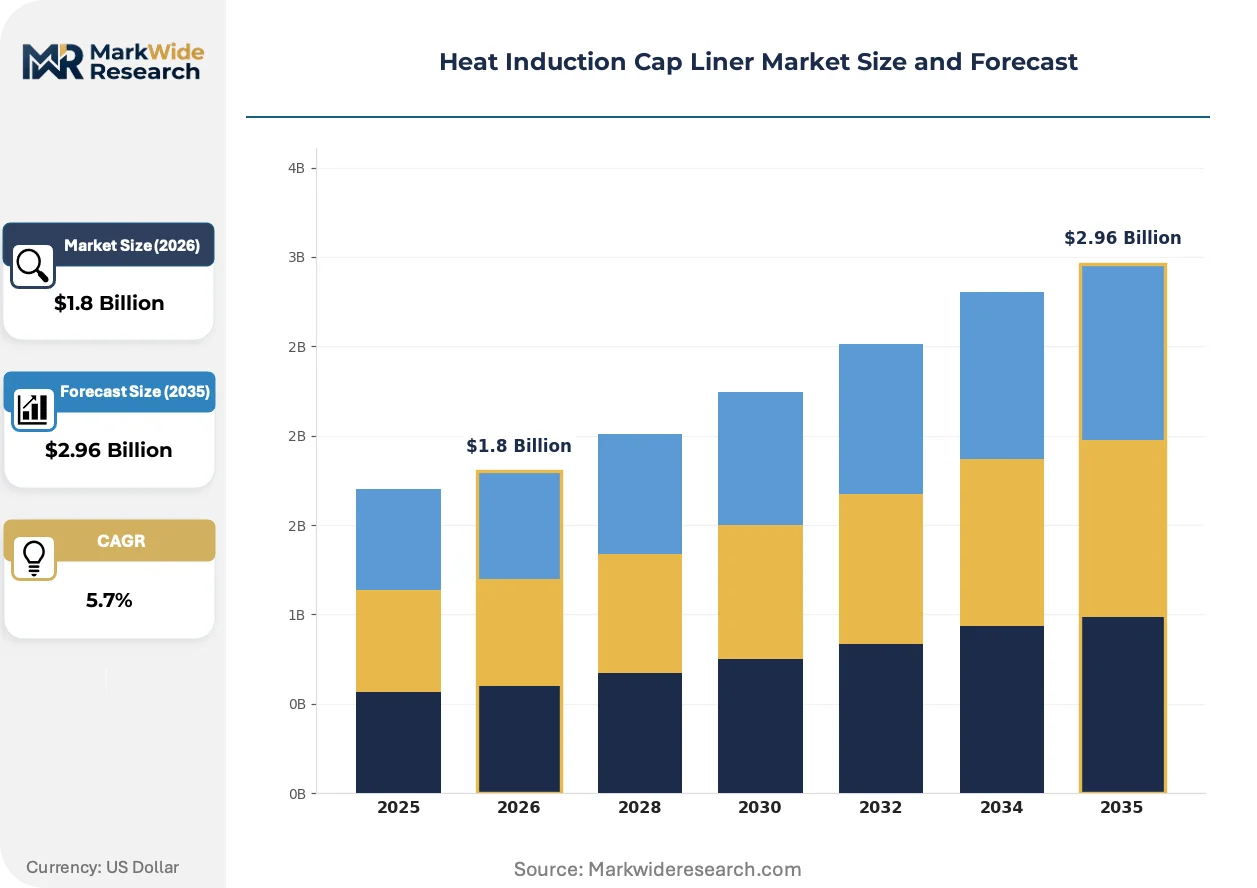
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Seal Liner, Foil Seal Liner, EPE Foam Liner, Induction Seal Liner Material: Polyethylene, PVC, Polypropylene, Aluminum Application: Pharmaceuticals, Cosmetics, Food & Beverages, Chemicals End User: Manufacturers, Distributors, Retailers, Repackagers |
| Companies Covered | B&B Cap Liners LLC, Low’s Cap Seal Sdn Bhd, Tekni-Plex Inc., Captel International Pvt Ltd, Tien Lik Cap Seal Sdn Bhd, Selig Group, Meyer Seals GmbH, Well-Pack Industries Co Ltd, Bluemay Weston Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Induction Cap Liner Market Strategic Shifts
Material science advances and regulatory chemistry protocols are converging to redefine liner performance specifications across pharmaceutical, food, and cosmetics packaging segments.
Polyethylene-based multilayer structures with enhanced heat-seal coatings are rendering obsolete conventional PVC-backed liners in European pharmaceutical applications. Major branded drug manufacturers are specifying these alternatives in new procurement tenders to preempt REACH compliance penalties. The transition is compressing demand for legacy formulations while elevating technical qualification barriers for incumbent suppliers.
REACH restrictions on persistent organic pollutants are mandating systematic material transitions across polymer backing layers used in induction sealing. ECHA enforcement timelines are accelerating converter R&D spending toward polypropylene and polyethylene alternatives. Pharmaceutical packagers in Germany and France are prioritizing suppliers with completed migration studies to avoid batch release delays.
Direct contracting between liner converters and multinational pharmaceutical packagers is displacing traditional distributor-mediated supply arrangements. Branded drug manufacturers are consolidating vendor panels to secure validated, lot-trackable supply chains under FDA 21 CFR Part 211 and EMA traceability requirements. This concentration is most visible in North American and European markets where serialization investments have already been deployed.
Heat Induction Cap Liner Market Segmentation
Heat induction cap liner procurement varies sharply by technical specification and regulatory exposure, with pharmaceutical buyers demanding validated multilayer structures while food exporters prioritize high-volume foil seal throughput. Segmentation discipline reveals where converter R&D investments concentrate and which material transitions command premium pricing.
Product Type:
After-sales technical support intensity separates premium liner converters from commodity suppliers, with pharmaceutical customers requiring ongoing extractables documentation and seal integrity validation.
- Foil Seal Liner:Aluminum-backed multilayer structures bond polymer backing to container rims through electromagnetic induction, creating hermetic barriers against oxygen and moisture penetration. Demand concentrates in pharmaceutical packaging lines serving FDA-regulated OTC drug manufacturers, where tamper-evident certification under 21 CFR Part 211 mandates validated supply chains.
- Induction Seal Liner:Composite discs engineered for precise heat-seal coating activation at 120–180°C, with thickness tolerances critical for high-speed capping lines. German pharmaceutical packagers specify these for sterile manufacturing compliance under EMA Annex 1 guidelines, prioritizing lot-trackable converters with completed migration studies.
- Single Seal Liner:Basic one-piece constructions for cost-sensitive applications with minimal barrier requirements.
- EPE Foam Liner:Expanded polyethylene cushioning layers prized in cosmetics for resealability and unboxing experience differentiation.
By volume, foil seal liners lead. By growth pace, induction seal liners are expanding most quickly.
Material:
Cost tier stratification aligns with regulatory compliance burden, with REACH-affected formulations commanding development premiums over legacy PVC alternatives.
- Polyethylene:Linear low-density and high-density grades displacing PVC across European pharmaceutical channels as ECHA enforcement accelerates. Branded drug manufacturers in France and Germany specify these in procurement tenders to preempt compliance penalties, with converters investing in migration study capabilities to secure qualification.
- Aluminum:Foil layer providing electromagnetic susceptibility and complete gas/moisture barrier integrity. Price volatility in raw metal markets constrains converter margin stability, particularly for long-term contracts with multinational pharmaceutical packagers seeking fixed pricing.
- Polypropylene:Stiffness and chemical resistance for aggressive fill products in chemical and agricultural applications.
- PVC:Legacy backing formulation facing systematic phase-out under persistent organic pollutant restrictions.
Polyethylene dominates current volume. Aluminum-backed structures are gaining share fastest.
Application:
Customer type determines specification stringency, with direct pharmaceutical packagers demanding pre-certified multilayer structures versus distributor-mediated chemical buyers accepting standard grades.
- Pharmaceuticals:Sterile and non-sterile drug packaging requiring validated, lot-trackable liner supply chains under FDA and EMA traceability mandates. Serialization investments in North American and European markets are compressing supplier qualification timelines, favoring converters with in-house extractables testing expertise.
- Food & Beverages:Extended shelf-life sealing for ocean-freight distribution, with Asia-Pacific exporters driving high-volume foil seal demand. Barrier integrity specifications are less stringent than pharmaceutical grades but volume scale rewards manufacturing efficiency.
- Cosmetics:Premium skincare and fragrance applications where EPE foam cushioning and resealability enhance unboxing experience.
- Chemicals:Industrial and agricultural chemical containment with emphasis on chemical resistance and spill prevention.
Pharmaceuticals command the highest unit margins. Food and beverages generate the steepest volume expansion.
End User:
Supply chain configuration varies by procurement scale and technical capability, with integrated manufacturers conducting direct supplier audits while smaller repackagers rely on distributor technical support.
- Manufacturers:Branded drug, food, and cosmetics producers with in-house packaging lines and direct converter relationships. These buyers consolidate vendor panels to secure validated supply chains, conducting on-site audits of liner production facilities and analytical chemistry capabilities.
- Distributors:Packaging supply intermediaries serving fragmented chemical and regional food processor markets with standard catalog offerings and limited technical support.
- Retailers:Private-label food and cosmetics brands with moderate volume requirements and specification delegation to contract packagers.
- Repackagers:Secondary packaging operations with variable demand patterns and price-sensitive procurement of standard liner grades.
Manufacturers represent the largest revenue concentration. Repackagers are expanding most quickly as private-label outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European liner distribution networks. German chemical and pharmaceutical clusters draw foil seal supply through this gateway. Asian manufacturing hubs rely on Singapore's transshipment infrastructure for ocean-freight liner exports.
United States
FDA 21 CFR Part 211 mandates drive pharmaceutical packager demand for certified induction seal liners. Serialization investments compress supplier qualification timelines for domestic drug manufacturers. New Jersey and Pennsylvania packaging corridors concentrate converter technical support capabilities.
Germany
EMA Annex 1 sterile manufacturing guidelines push lot-trackable liner validation requirements. REACH restrictions on persistent organic pollutants accelerate PVC formulation phase-outs. Meyer Seals GmbH anchors supply from Lower Saxony for European pharmaceutical and chemical end users.
India
CDSCO traceability mandates create certified liner demand as domestic drug manufacturers upgrade tamper-evident sealing. Pharmaceutical export growth drives foil seal procurement from Mumbai-Pune and Hyderabad clusters. Contract packaging expansion concentrates liner converter partnerships in Gujarat and Maharashtra.
China
SAMR packaging safety standards and NMPA drug serialization requirements reshape liner specification protocols. Yangtze River Delta manufacturing bases supply high-volume foil seal production for food and beverage exporters. Shanghai port infrastructure enables ocean-freight distribution to Southeast Asian and European markets.
Japan
METI circular economy roadmaps and PMDA pharmaceutical packaging standards drive material transitions. Osaka-Kobe industrial corridors concentrate cosmetics and pharmaceutical packaging operations. Domestic converters prioritize polyethylene-backed multilayer structures for recyclability compliance.
Heat Induction Cap Liner Market Competitive Environment
On the supply side, the industry is tiered between multinational converters with pharmaceutical certification capabilities and regional specialists serving cost-sensitive food and chemical markets. Three strategic archetypes dominate: European-based pharmaceutical-grade validators, Asia-Pacific high-volume manufacturers, and niche cushioning specialists. Capacity expansion and direct contracting with branded drug manufacturers represent the dominant competitive moves as serialization mandates compress procurement channels.
Within the European validator tier, Selig Group and Meyer Seals GmbH exemplify supply-side concentration around pharmaceutical-grade multilayer structures. Tekni-Plex Inc. occupies a position among North American specialists with FDA child-resistance protocol capabilities. Well-Pack Industries Co Ltd represents Asia-Pacific scale-driven manufacturing for food and beverage export markets.
| Leading Market Players |
|---|
| B&B Cap Liners LLC |
| Low's Cap Seal Sdn Bhd |
| Tekni-Plex Inc. |
| Captel International Pvt Ltd |
| Tien Lik Cap Seal Sdn Bhd |
| Selig Group |
| Meyer Seals GmbH |
| Well-Pack Industries Co Ltd |
| Bluemay Weston Limited |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's container throughput cost dynamics compress margin flexibility for European pharmaceutical packagers while amplifying price differentiation between certified multilayer structures and standard foil seal grades. Aluminum foil price volatility propagates through long-term contracts, forcing converters to tier pricing by qualification burden and volume commitment.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels dominates procurement negotiations. Price differentiation hinges on FDA 21 CFR Part 211 validation status and REACH migration study completion, with branded drug manufacturers absorbing premiums for lot-trackable supply chains. Cost compression in food-grade segments is intensifying because Asia-Pacific exporters consolidate purchase volumes. Repackagers exhibit highest price sensitivity; sterile pharmaceutical packagers demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Selig Group, Meyer Seals GmbH, and Well-Pack Industries Co Ltd across European and Asia-Pacific production hubs. Raw material sourcing draws from German aluminum rolling mills, Saudi petrochemical feedstocks for polyethylene grades, and Chinese polymer film converters. Single-source vulnerability concentrates in Lower Saxony pharmaceutical supply. Distribution runs through Rotterdam gateway terminals for European chemical clusters and Singapore transshipment for Asia-Pacific export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from direct-in-mold sealing technologies and laser-etched tamper-evident closures that bypass liner procurement entirely.
For Market Incumbents: Insulate pharmaceutical certification portfolios by deepening analytical chemistry capabilities for extractables testing and securing backward integration into aluminum foil converting. Child-resistance protocol expertise at Tekni-Plex Inc. demonstrates how technical moats resist commoditization pressure from Asian volume manufacturers. For New Entrants and Emerging Players: Pursue cosmetics EPE foam liner white space in premium skincare unboxing applications, where resealability specifications remain underpenetrated by pharmaceutical-focused incumbents. Gujarat and Maharashtra contract packaging clusters offer lowest barriers to qualification for CDSCO-compliant foil seal supply. For Investors and Strategic Acquirers: Mid-cap converters with completed REACH migration studies and existing EMA Annex 1 validation relationships present asymmetric upside as serialization mandates compress vendor panels. Long-term viability rests on regulatory chemistry capabilities rather than volume scale alone. Watch for FDA warning letter activity against incumbent suppliers as inflection signal for switching cost release.| Strategic Initiative | Industry Significance |
|---|---|
| Migration Study Completion | ECHA enforcement timelines elevate converters with pre-certified polyethylene formulations above PVC-dependent competitors. |
| Direct Pharmaceutical Contracting | Selig Group's long-term agreements with branded drug manufacturers displace distributor-mediated supply arrangements. |
| Aluminum Foil Backward Integration | Captive supply of rolled metal hedges raw material volatility for multiyear pharmaceutical pricing commitments. |
| Asia-Pacific Capacity Expansion | Well-Pack Industries Co Ltd scales high-volume output to capture food and beverage export growth from Yangtze River Delta. |
| Extractables Testing Investment | In-house analytical chemistry capabilities compress qualification timelines for FDA-regulated sterile manufacturing customers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement managers, regulatory affairs directors at pharmaceutical manufacturers, liner converter technical sales leads, and customs brokerage specialists handling Rotterdam and Singapore port clearances; and secondary validation against EMA Annex 1 guidance documents, FDA 21 CFR Part 211 enforcement records, ECHA REACH restriction timelines, and trade flow databases tracking aluminum foil and polymer film imports. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Forecast inputs incorporated product type segmentation across foil seal, induction seal, and EPE foam constructions; material transitions from PVC to polyethylene and polypropylene; application intensity across pharmaceutical sterile manufacturing, food shelf-life extension, and cosmetics cushioning; and end-user procurement patterns distinguishing direct manufacturer relationships from distributor-mediated supply. CAGRs were derived from regression analysis of historical qualification timeline compression and regulatory mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese converters or accelerated laser-etching substitution would shift outcomes beyond modeled ranges. Quarterly review of ECHA enforcement actions, FDA warning letter issuance against packaging suppliers, and aluminum LME price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Cap Seals Market
Caps and Closures
Spray Caps Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Cover Caps Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Indonesia Plastic Caps and Closures Market