
 Transparent Food Packaging Market | 2026-2036
Transparent Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Food Packaging Market Analytics
Food-grade clarity specifications above ninety percent light transmission is bifurcating the competitive landscape into premium optical-grade suppliers and commodity converters. Amcor plc leverages its integrated film extrusion network across multiple continents to sustain cost advantages in high-clarity PET sheet. Sealed Air Corporation anchors its position through proprietary barrier coating technologies that extend shelf visibility without compromising oxygen protection. Tetra Pak International S.A. competes by specializing in aseptic transparent carton formats that occupy niche ambient dairy segments where conventional rigid plastic faces regulatory pressure.
Transparent food packaging comprises polymer-based or cellulosic materials engineered for optical clarity, typically achieving haze values below five percent and gloss ratings exceeding eighty units, manufactured through cast film extrusion, biaxial orientation, or thermoforming processes to enable consumer visual assessment of freshness and quality. Polyethylene and polypropylene films dominate volume due to their balance of clarity, sealability, and compatibility with modified atmosphere systems, though PET containers command margin pools in ready-meal and premium deli applications where dimensional stability and microwave compatibility justify higher unit economics. The trays format leads in protein packaging while films represent the fastest-growing structural category as pillow-pack and flow-wrap configurations displace pre-formed rigid alternatives in snack and bakery segments.
The FDA maintains strict migration limits for additives in food-contact transparent polymers under 21 CFR 177, while the EU REACH framework and F-Gas Regulation constrain certain blowing agents and optical brighteners used in clarified polypropylene production. EFSA evaluations of nano-scale barrier coatings are reshaping approval pathways for next-generation high-performance transparent films. Stakeholders must monitor evolving extended producer responsibility schemes across multiple jurisdictions and assess whether mono-material recyclable designs or certified compostable clarity alternatives offer superior long-term compliance positioning.
Market Dynamics
Mono-material recyclable transparent formats are displacing multi-layer barrier constructions as the EU Packaging and Packaging Waste Regulation mandates design-for-recycling compliance across fresh food retail channels.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:The framework mandates mono-material recyclability, accelerating converter investment in clarified polypropylene and PET sheet extrusion lines.
- Modified atmosphere packaging integration:High-clarity films with embedded oxygen scavengers extend protein shelf visibility while maintaining gas barrier performance in North American retail chains.
- German supermarket mandates:Private-label meat and deli categories now require shelf-ready transparent packaging, creating pull-through demand for optical-grade PET containers.
Market Restraints
- Propylene feedstock volatility:Clarified polypropylene production depends on naphtha-derived monomer supplies concentrated in Gulf Coast petrochemical complexes.
- Barrier coating regulatory uncertainty:EFSA nano-scale coating evaluations create approval timeline risk for next-generation oxygen barrier films.
- Cellulosic substitute competition:Molded fiber trays with transparent windows threaten rigid plastic formats in ready-meal segments where microwave compatibility is secondary.
Strategic Opportunities
- India cold-chain expansion:Organized retail penetration in protein and dairy creates first-mover positioning for aseptic transparent carton formats.
- Digital watermarking integration:Combined invisible marker and optical sorting technologies enable closed-loop recycling of post-consumer clear PET trays.
- Extended producer responsibility schemes:France's Citeo and Germany's Duales System Deutschland create compliance-service revenue pools for packaging-as-a-service models.
Industry Challenges
- Optical metrology talent scarcity:Haze and gloss specification testing requires specialized spectrophotometry expertise concentrated in polymer science programs at RWTH Aachen and MIT.
- Retrofitting thermoforming lines:Legacy equipment designed for multi-layer sheet cannot process mono-material alternatives without substantial mold and heating element replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Food Packaging Market |
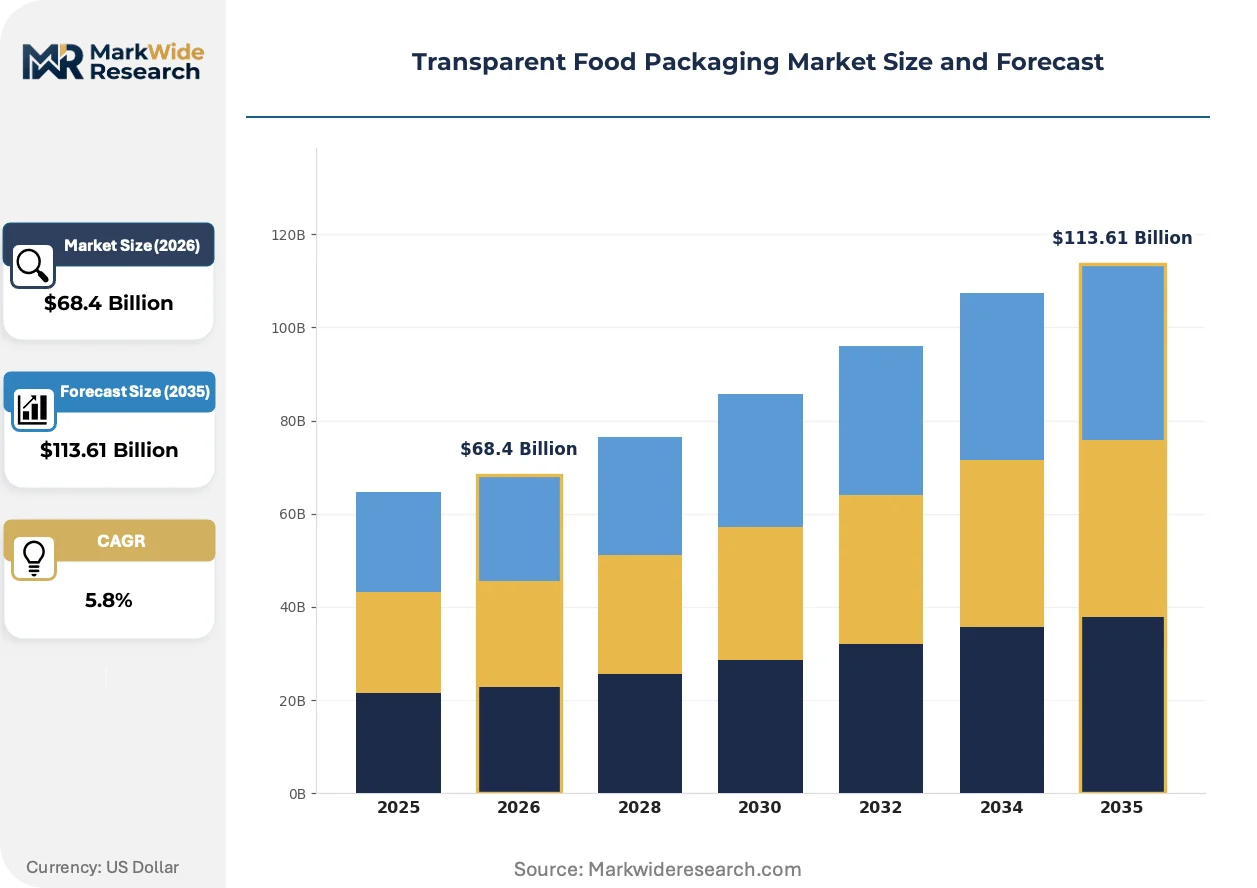
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, PET, PVC Packaging Format: Trays, Bags, Films, Containers End User: Food Manufacturers, Retailers, Restaurants, Caterers Distribution Channel: Direct Sales, Wholesalers, Online, Supermarkets |
| Companies Covered | Amcor plc, Sealed Air Corporation, Tetra Pak International S.A., Genpak, LLC, Berry Global Inc., Coveris, Anchor Packaging, Chantler Packaging Inc., Toppan Printing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Food Packaging Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from premium pharmaceutical applications into mass-market fresh food transparent formats, enabled by printable sensor technologies and declining unit economics.
Bio-based barrier coatings derived from chitosan and cellulose nanocrystals are displacing ethylene vinyl alcohol coextrusions in modified atmosphere meat packaging. European protein processors are piloting these formats at commercial scale. The shift compresses reliance on petroleum-derived oxygen barriers while complicating existing recycling stream sortation protocols.
REACH F-Gas Regulation constraints on hydrofluorocarbon blowing agents are forcing clarified polypropylene producers toward physical nucleating agents and nitrogen gas injection systems. The restriction elevates capital intensity for optical-grade sheet manufacturing. German and Italian extrusion houses are absorbing these costs to maintain EU market access.
Retail buyer consolidation is compressing supplier negotiation cycles from annual to quarterly frameworks. North American supermarket chains now mandate real-time inventory visibility through RFID-enabled transparent containers. The practice is most visible in berry and cherry tomato categories where shrinkage rates previously exceeded eight percent.
Transparent Food Packaging Market Segmentation
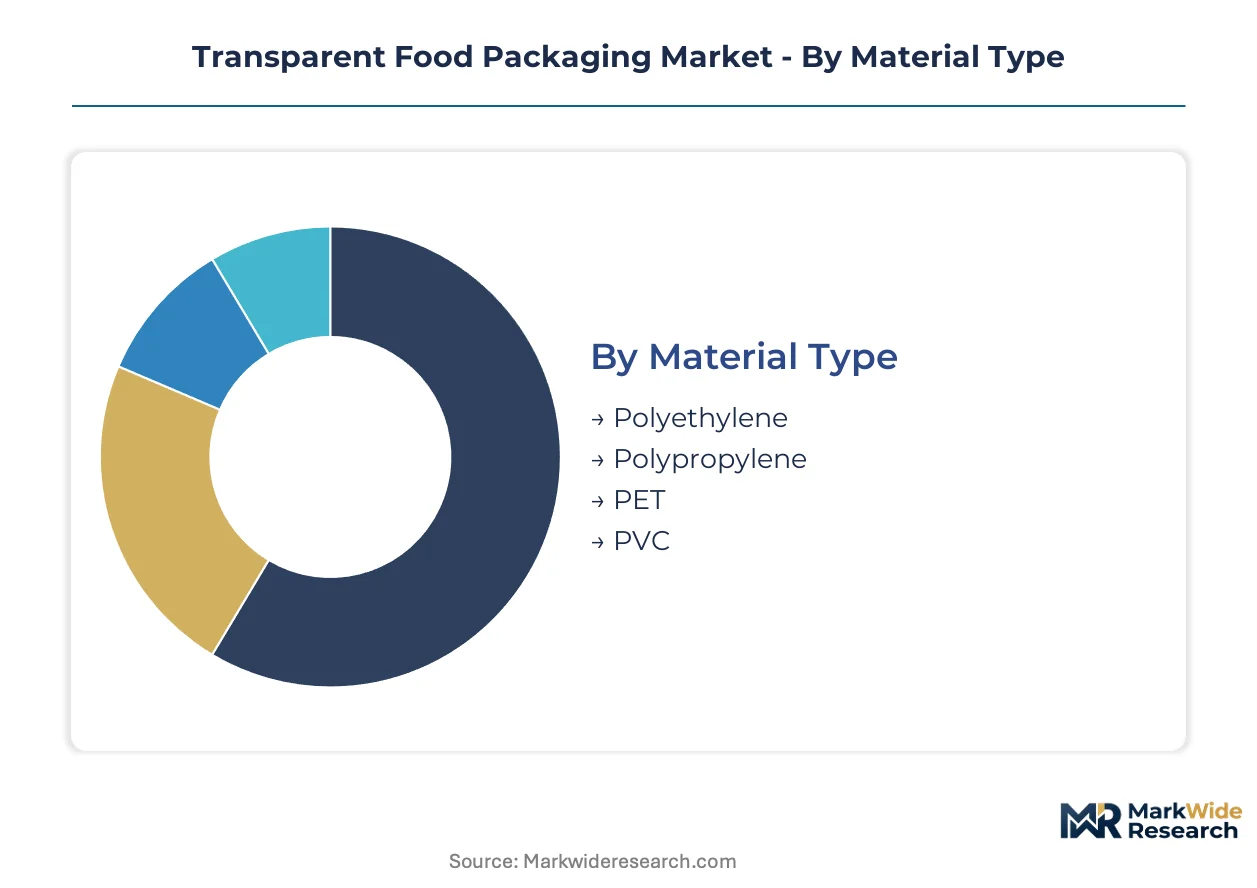
Transparent food packaging segmentation reveals how regulatory pressure on recyclability and optical performance standards fragment supplier capabilities across material grades and conversion technologies. Material chemistry and packaging geometry determine compliance pathways under divergent national frameworks.
Material Type:
FDA migration limits under 21 CFR 177 and EU REACH substance restrictions create divergent approval burdens for optical additives and clarifying agents across polymer families.
- Polyethylene:Linear low-density grades achieve clarity through metallocene catalysis with haze values below five percent. German meat processors specify clarified PE for modified atmosphere lidding films where EFSA coating evaluations now govern oxygen scavenger compatibility.
- Polypropylene:Nucleated homopolymer and random copolymer variants dominate thermoformed deli trays. REACH F-Gas Regulation constraints on hydrofluorocarbon blowing agents force Italian extruders toward nitrogen injection systems, elevating capital intensity for optical-grade sheet.
- PET:Amorphous and crystallized grades serve ready-meal containers requiring microwave stability. France's Citeo extended producer responsibility scheme rewards mono-material PET designs with lower compliance fees.
- PVC:Plasticized formulations persist in select fresh produce overwrap applications where cost sensitivity outweighs recyclability mandates. US FDA strictures on phthalate plasticizers constrain food-contact deployment.
Established volume favors polypropylene; emerging adoption favors PET.
Packaging Format:
Cost tier differentiation separates capital-intensive thermoforming equipment from lower-barrier film conversion lines.
- Trays:Thermoformed PET and clarified PP structures anchor protein retail presentation. German supermarket mandates for shelf-ready meat packaging concentrate demand in injection-stretch and pressure-forming lines.
- Films:Cast and biaxially oriented structures achieve sub-five-percent haze for flow-wrap bakery and snack applications. North American retail chains specify high-clarity films with embedded RFID for berry inventory tracking.
- Bags:Side-seal and bottom-gusseted configurations serve frozen vegetable and prepared salad segments where optical inspection of contents drives purchase conversion.
- Containers:Injection-molded clarified PP and PET jars compete in ambient dairy and deli segments where Tetra Pak aseptic cartons face regulatory displacement pressure.
Trays command margin concentration; films are climbing the fastest.
End User:
Customer type determines specification stringency and volume commitment scale.
- Food Manufacturers:Branded protein and dairy processors specify optical-grade materials with certified migration compliance for extended shelf-life applications.
- Retailers:Private-label chains in Germany and France mandate transparent shelf-ready formats with digital watermarking for sortation compatibility.
- Restaurants:Foodservice distributors prioritize cost-optimized clarified PP for grab-and-go prepared meal visibility.
- Caterers:Event and institutional foodservice deploy lower-specification PE films where presentation requirements are secondary to portion control.
Retail procurement concentrates specification power; food manufacturers drive optical innovation.
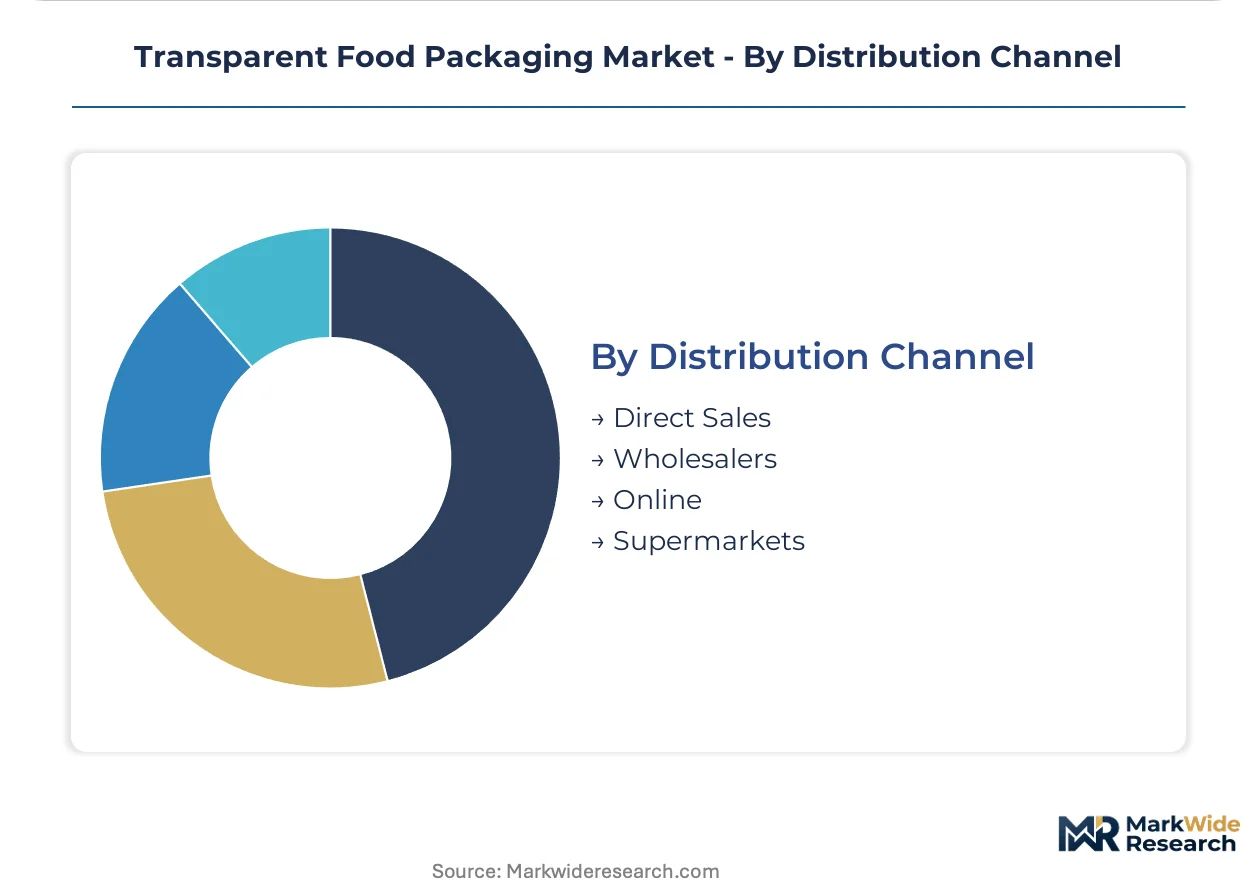
Distribution Channel:
Supply chain configuration determines technical service intensity and lot-size economics.
- Direct Sales:Major converters maintain technical service relationships with multinational protein processors for customized barrier specifications.
- Supermarkets:Chain-level packaging mandates in Germany and France bypass traditional distributor tiers for private-label compliance.
- Wholesalers:Regional distributors aggregate fragmented foodservice demand for standardized film and tray formats.
- Online:E-commerce grocery penetration creates demand for damage-resistant transparent formats with tamper-evident closures.
Direct relationships dominate specification-setting; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity for optical-grade sheet concentrates in Germany, the United States, and China, with converter investments tracking regulatory mandates for mono-material recyclability. Fresh produce retail chains and protein processors in these markets are accelerating specification shifts toward clarified polypropylene and amorphous PET formats.
United States
Modified atmosphere packaging integration drives demand for high-clarity films with embedded oxygen scavengers in North American retail chains. FDA maintains strict migration limits for additives in food-contact transparent polymers under 21 CFR 177. Fresh produce distribution hubs in California's Central Valley and the Pacific Northwest are expanding clear-container programs for berry and cherry tomato categories.
Germany
Supermarket chains have mandated shelf-ready transparent packaging for private-label meat and deli categories, creating concentrated pull-through demand. REACH F-Gas Regulation constraints on hydrofluorocarbon blowing agents force extruders toward nitrogen injection systems. The Rhine-Ruhr industrial corridor hosts clarified polypropylene sheet manufacturing clusters serving pan-European protein processors.
China
Organized retail penetration in protein and dairy segments creates scaling opportunities for aseptic transparent carton formats. GB standards and SAMR oversight govern food-contact polymer approvals with increasing stringency. The Yangtze River Delta manufacturing belt is absorbing thermoforming equipment for mono-material PET tray production.
India
Cold-chain infrastructure expansion in organized retail channels generates first-mover positioning for transparent packaging converters. FSSAI regulations and BIS certification requirements shape material approval pathways. Maharashtra and Gujarat industrial zones are attracting cast film extrusion investments for clarified PE lidding films.
France
Extended producer responsibility schemes through Citeo reward mono-material PET designs with lower compliance fees, redirecting procurement specifications. EU Packaging and Packaging Waste Regulation mandates accelerate design-for-recycling compliance timelines. The Île-de-France region anchors technical service relationships between converters and multinational dairy processors.
Transparent Food Packaging Market Competitive Landscape
Concentration sits with integrated film extruders and proprietary barrier technology holders who control optical-grade polymer supply chains. The competitive structure tiers into multinational converters with captive resin access, regional specialists in thermoformed formats, and equipment-integrated solution providers. Dominant competitive moves include backward integration into resin compounding and strategic licensing of oxygen scavenger technologies.
Among publicly listed packaging conglomerates, Amcor plc, Sealed Air Corporation, and Tetra Pak International S.A. exemplify divergent strategic archetypes. Amcor represents integrated film extrusion scale across multiple continents. Sealed Air occupies a position anchored in proprietary barrier coating intellectual property. Tetra Pak exemplifies specialized aseptic carton engineering for regulatory-displaced dairy segments.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Tetra Pak International S.A. |
| Genpak, LLC |
| Berry Global Inc. |
| Coveris |
| Anchor Packaging |
| Chantler Packaging Inc. |
| Toppan Printing Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU REACH substance restrictions and FDA migration limits under 21 CFR 177 simultaneously gate supplier qualification and stratify price tiers across optical-grade polymer markets, forcing converters to absorb certification costs or exit premium food-contact segments entirely.
Pricing Analysis
FDA migration limits under 21 CFR 177 dictate the pricing tier structure across transparent food packaging markets. Three-tier pricing separates optical-grade PET certified for extended shelf-life applications from clarified polypropylene formats and commodity PE films serving cost-sensitive produce overwrap. Price differentiation rests on EFSA coating approval status and mono-material recyclability certification under France's Citeo scheme. Cost compression in clarified PP sheet is intensifying because REACH F-Gas Regulation constraints on hydrofluorocarbon blowing agents force nitrogen injection retrofits. Food manufacturers exhibit lowest price sensitivity due to branded shelf-life requirements, while foodservice distributors prioritize economy-grade clarified PE.
Supply Chain Analysis
Germany, the United States, and China anchor extrusion capacity for optical-grade sheet serving global protein and dairy packaging demand. Feedstock supply draws from naphtha-derived monomer supplies concentrated in Gulf Coast petrochemical complexes, clarified polypropylene resin compounding in the Rhine-Ruhr corridor, and amorphous PET chip production in the Yangtze River Delta. Single-source vulnerability concentrates in Italian and German extrusion houses controlling nucleating agent formulations for sub-five-percent haze specifications. Distribution runs through direct technical service relationships with multinational protein processors, bypassing traditional distributor tiers for private-label compliance mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent food packaging is transitioning toward packaging-as-a-service models where extended producer responsibility compliance and digital watermarking integration generate recurring revenue streams expanding faster than commodity resin conversion margins.
For Market Incumbents: Shield market position by accelerating backward integration into resin compounding for optical-grade clarified polypropylene, capturing margin pools threatened by REACH F-Gas Regulation cost pass-through. Prioritize captive supply of nitrogen injection extrusion capacity in Germany and Italy to maintain EU market access against emerging Asian competitors. Deepen technical service relationships with German supermarket chains mandating shelf-ready formats to lock in specification-setting power. For New Entrants and Emerging Players: BIS certification fast-tracks for India's cold-chain expansion create first-mover positioning in Maharashtra and Gujarat industrial zones where organized retail penetration lags Western markets. Target aseptic transparent carton formats for protein and dairy segments in India where Tetra Pak faces regulatory displacement pressure under FSSAI evolving standards. Pursue equipment-integrated solution partnerships with regional distributors rather than direct multinational competition. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation mandates reshapes the acquisition landscape toward mono-material recyclable design capabilities and digital watermarking intellectual property. Long-term viability favors converters with demonstrated EFSA coating approval pathways and established Citeo compliance-service revenue. The signal to watch is EFSA nano-scale barrier coating evaluation timelines, which will determine which oxygen scavenger technologies achieve commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of optical-grade clarified PP insulates margins from REACH F-Gas cost pass-through. |
| Digital Watermarking Integration | Invisible marker technologies enable closed-loop recycling of post-consumer clear PET trays under Citeo. |
| Nitrogen Injection System Retrofit | Physical nucleating agent conversion maintains EU market access against hydrofluorocarbon restrictions. |
| Extended Producer Responsibility Service Models | Compliance-service revenue pools in France and Germany offset commodity conversion margin compression. |
| Aseptic Transparent Carton Format Expansion | Regulatory-displaced dairy segments in India and China create first-mover positioning for ambient protein packaging. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with extrusion plant managers, polymer procurement leads at protein processors, retail category buyers in German supermarket chains, and EFSA regulatory affairs specialists; combined with secondary validation from FDA 21 CFR 177 filings, EFSA scientific opinions on nano-scale coatings, Citeo extended producer responsibility databases, and customs trade data on optical-grade polymer imports. Bottom-up and top-down triangulation cross-validated converter capacity estimates against end-user procurement volumes.
Across the projection horizon, the analytical framework modeled segmentation dimensions including material chemistry, packaging format geometry, end-user specification stringency, and distribution channel technical service intensity. CAGRs were derived from trend extrapolation of mono-material recyclable adoption curves and modified atmosphere packaging integration rates. Forecast inputs incorporated EFSA coating approval timelines and German supermarket mandate rollout patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory stringency and stable naphtha feedstock pricing; material deviation in propylene monomer volatility or REACH substance restriction scope would warrant model refresh. Recalibration cycles align with material shifts in EFSA nano-scale coating evaluations and extended producer responsibility scheme revisions across European jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
North America Food Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Food Green Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Cereal Packaging Market
Food Packaging
Egg Packaging Market