
 PCR Packaging for Food and Beverages Applications Market | 2026-2036
PCR Packaging for Food and Beverages Applications Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Packaging for Food and Beverages Applications Market Insights
Asset-light leasing models for food-grade recycling infrastructure is fragmenting competitive access across the PCR packaging value chain. Amcor Group leverages its integrated film and fiber network to sustain supply security for beverage clients. Berry Global anchors North American bottle production through captive resin partnerships with regional recyclers. Mondi plc differentiates via kraft-paper hybrid formats that navigate European single-use plastic restrictions.
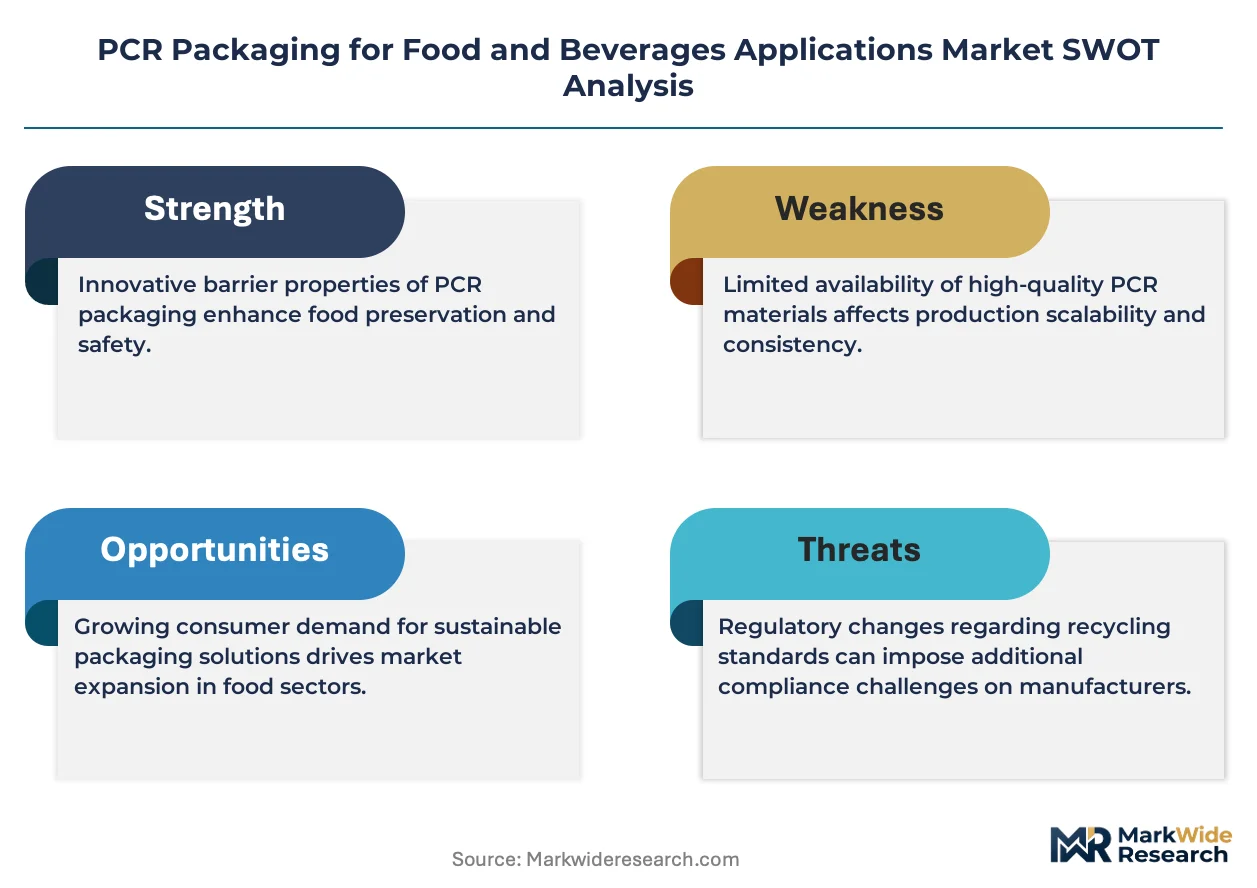
PCR packaging for food and beverages applications denotes containers manufactured with post-consumer recycled resins that meet FDA or EFSA food-contact compliance thresholds, typically requiring decontamination to residual contaminant levels below parts-per-billion thresholds. These packages serve to close material loops while preserving shelf stability for perishable and shelf-stable goods. Bottles and pouches represent the most rapidly scaling formats as beverage brands and snack producers prioritize lightweight, high-visibility formats. Polyethylene dominates material demand due to established mechanical recycling streams and favorable melt-processing characteristics, though polypropylene is gaining traction in hot-fill and retort applications where higher thermal tolerance matters.
US FDA maintains Letter of No Objection protocols for post-consumer recycled content in food contact, while EU EFSA evaluates decontamination efficiency through challenge testing under specific migration limits. The EU Green Deal and CSRD reporting obligations are forcing brand owners to document recycled content percentages across supply chains. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California, Maine, and Oregon that will reshape cost allocation between resin suppliers, converters, and retail distributors.
Market Dynamics
EU Green Deal mandates on recycled content thresholds are compressing converter margins while fragmenting resin supply security across the food-grade PCR packaging value chain. Brand owners now face binding CSRD disclosure requirements that document post-consumer recycled percentages through tier-two suppliers, forcing simultaneous compliance and cost absorption.
Growth Catalysts
- EU Green Deal Packaging and Packaging Waste Regulation:Mandatory recycled content floors for beverage containers create guaranteed offtake for food-grade PCR resins, pulling investment into decontamination infrastructure.
- Dairy sector consolidation:Large-format yogurt and milk processors are specifying minimum 30% PCR content in bottle procurement tenders, normalizing premium pricing for compliant supply.
- Mechanical recycling yield improvements:Advanced flake-sorting and melt-filtration systems are expanding the pool of input materials qualifying for FDA Letter of No Objection protocols.
Market Restraints
- Food-grade resin supply concentration:North American rPET pellet production clusters in the US Southeast, exposing converters to hurricane-related disruption and freight cost spikes.
- Decontamination capex thresholds:Super-clean recycling lines require capital commitments exceeding mid-tier converter balance sheet capacity, freezing out regional players.
- virgin price volatility:Naphtha-linked virgin polyethylene pricing swings compress PCR resin premiums during oil market downturns, eroding recycler margins.
Strategic Opportunities
- California SB 54 implementation:Extended producer responsibility frameworks will redirect packaging waste fees toward in-state food-grade recycling infrastructure, creating captive supply zones.
- Hot-fill polypropylene:Retort pouch applications for shelf-stable meals remain underpenetrated by PCR content due to thermal performance gaps, offering first-mover positioning.
- Digital watermarking integration:Combined AI-powered sorting and blockchain traceability systems are enabling brand owners to verify recycled content claims for CSRD auditors.
Industry Challenges
- Food-contact toxicologist scarcity:EFSA and FDA compliance documentation requires specialized migration testing expertise concentrated in Western European and US East Coast laboratories, creating bottlenecks.
- Legacy blow-molding equipment retrofit complexity:Converters running decades-old lines face extended downtime and yield loss when processing higher-melt-index PCR resins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Packaging for Food and Beverages Applications Market |
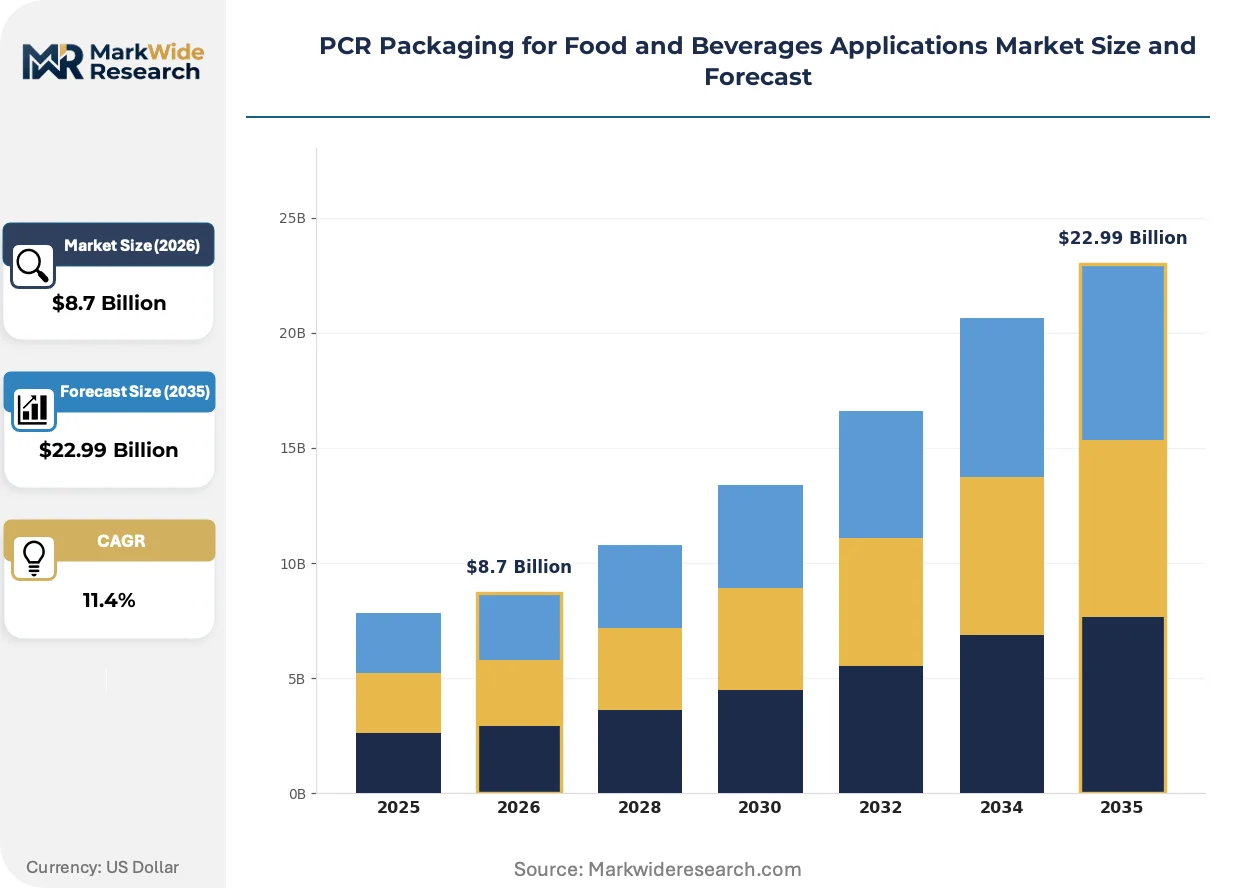
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Trays, Pouches Material: Polyethylene, Polypropylene, Polystyrene, Others Application: Dairy Products, Snacks, Beverages, Sauces End User: Food Manufacturers, Beverage Companies, Retailers, Wholesalers |
| Companies Covered | Berry Global, Amcor Group, Mondi plc, Transcontinental Inc., ePac Holdings, LLC, Novolex, Sealed Air Corporation, Sonoco Product Company, Coveris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Packaging for Food and Beverages Applications Market Trends and Innovations
Active packaging formats are converging with circular material systems, forcing equipment suppliers and resin producers into co-development partnerships. The competitive frontier has shifted from virgin-equivalent performance to verifiable closed-loop claims backed by digital traceability infrastructure.
Barrier-coated PCR polyethylene is hybridizing oxygen and moisture protection with post-consumer content ratios exceeding 50%. Snack brands in Germany and France are adopting these structures for nut and dried fruit applications where shelf life extension previously required virgin multilayer films. The technology is compressing the performance gap between mechanical recycling outputs and virgin coextrusions, enabling converters to maintain existing line speeds without capital replacement.
CSRD reporting obligations are mandating granular disclosure of recycled content percentages across packaging portfolios. EU-based food manufacturers must now audit tier-two and tier-three suppliers for PCR documentation, creating compliance service demand for third-party verification platforms. Mid-sized dairy processors in Italy and the Netherlands are responding by consolidating supplier bases to reduce audit burden, favoring converters with integrated resin-to-package traceability systems.
Retailers are unbundling shelf-space allocation from virgin-content assumptions, creating direct procurement relationships with PCR-certified converters. Discounters in Poland and Spain are piloting store-brand water bottles with 100% PCR content, bypassing traditional brand-owner intermediaries. This channel compression is most visible in private-label beverage categories where price positioning allows margin absorption of food-grade resin premiums.
PCR Packaging for Food and Beverages Applications Market Segmentation
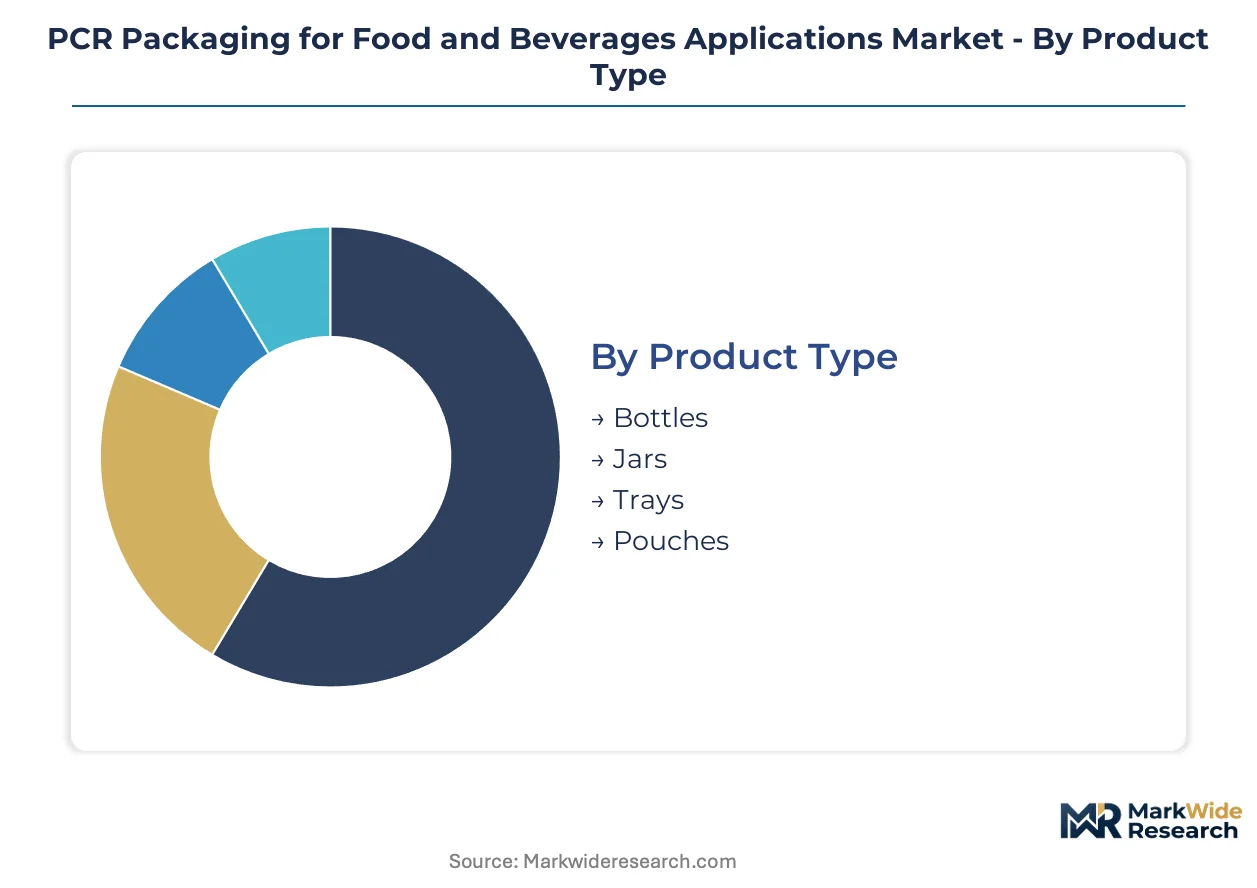
PCR packaging segmentation reveals how regulatory pressure and processing constraints fragment procurement strategies across food and beverage supply chains. Material certification tiers and format-specific decontamination requirements create distinct supplier ecosystems that converters must navigate simultaneously.
Product Type:
After-sales service intensity varies sharply across formats, with blow-molded bottles demanding technical support for line-speed optimization while pouches require film-sealing expertise.
- Bottles:Dominant format for dairy and beverage applications, blow-molded from rPET or rHDPE with super-clean decontamination protocols. German and French dairy processors specify minimum PCR content thresholds in procurement tenders, normalizing premium pricing for compliant supply.
- Pouches:Flexible multilayer structures combining PCR polyethylene with oxygen barrier coatings. Snack brands in Germany and France adopt these for nuts and dried fruits where shelf-life extension previously required virgin coextrusions.
- Jars:Wide-mouth containers for spreads and condiments, typically injection-molded from rPP with hot-fill compatibility requirements.
- Trays:Thermoformed structures for fresh produce and ready meals, limited by food-contact approval complexity for recycled polystyrene.
Bottles hold the largest share; momentum sits with pouches.
Material:
Cost tier differentiation separates mechanically recycled resins with FDA Letter of No Objection from emerging chemical recycling outputs commanding substantial premiums.
- Polyethylene:Established mechanical recycling streams and favorable melt-processing characteristics dominate rHDPE and rLDPE supply. Berry Global anchors North American production through captive resin partnerships with regional recyclers.
- Polypropylene:Higher thermal tolerance enables hot-fill and retort applications where rPP penetration remains underdeveloped. Retort pouch applications for shelf-stable meals offer first-mover positioning for compliant supply.
- Polystyrene:Limited food-grade recycling infrastructure constrains rPS adoption despite established collection systems for non-food packaging.
- Others:Emerging rPET and bio-based hybrid resins targeting premium beverage segments with 100% recycled content claims.
Polyethylene captures the volume base; polypropylene climbs the fastest.
Application:
Customer type concentration shifts procurement power toward large-format processors with binding CSRD disclosure requirements.
- Dairy Products:Yogurt and milk bottle specifications normalize 30% PCR minimums across EU tender processes. EU Green Deal mandates tighten material sourcing rules for this segment.
- Beverages:Water and soft drink brands pilot 100% PCR bottles in Polish and Spanish discount retail channels, bypassing traditional intermediaries.
- Snacks:Nut and dried fruit packaging adopts barrier-coated PCR polyethylene exceeding 50% post-consumer content.
- Sauces:Hot-fill compatibility requirements limit PCR adoption in condiment segments pending rPP thermal performance improvements.
Dairy commands established volume; beverages gain share fastest.
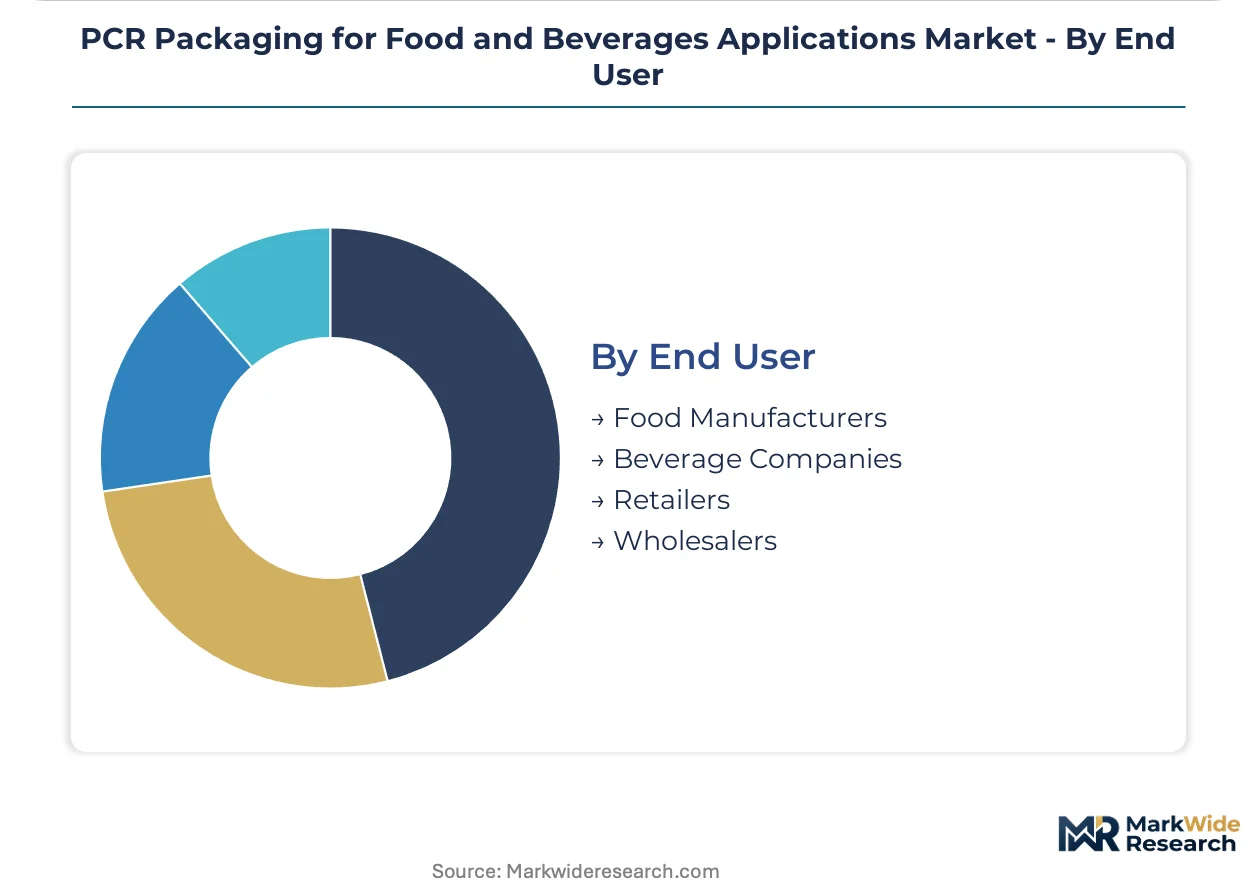
End User:
Supply concentration determines converter access, with integrated resin-to-package traceability systems favoring suppliers to consolidated manufacturer bases.
- Food Manufacturers:Mid-sized dairy processors in Italy and the Netherlands consolidate supplier bases to reduce CSRD audit burden.
- Beverage Companies:Amcor Group leverages integrated film and fiber networks to sustain supply security for this client segment.
- Retailers:Polish and Spanish discounters pilot direct procurement from PCR-certified converters for private-label water bottles.
- Wholesalers:Distribution intermediaries face margin compression as brand owners and retailers build direct converter relationships.
Food manufacturers anchor demand; retailers reshape channel structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in food-grade recycled resins are reshaping regional competitive positioning. Net importers of virgin polyethylene face mounting pressure as EU Green Deal mandates tighten sourcing requirements. Supply security now depends on proximity to decontamination infrastructure rather than traditional petrochemical corridors.
United States
Dairy processors in Wisconsin and California are accelerating rHDPE procurement for milk bottles. FDA Letter of No Objection protocols govern super-clean recycling approvals. The US Southeast concentrates pellet production capacity, exposing converters to hurricane-related disruption risks.
Germany
Beverage brands specify minimum PCR thresholds in procurement tenders. EU Green Deal Packaging and Packaging Waste Regulation mandates recycled content floors for containers. The Rhine-Ruhr industrial corridor hosts advanced decontamination lines serving pan-European dairy supply chains.
France
Snack producers adopt barrier-coated PCR polyethylene exceeding post-consumer content minimums. EFSA evaluates decontamination efficiency through challenge testing under specific migration limits. The Lyon-Grenoble cluster specializes in oxygen barrier film development for nut packaging.
Italy
Mid-sized dairy processors consolidate supplier bases to reduce CSRD audit burden. CSRD reporting obligations force granular disclosure of recycled content percentages. Northern Italy's packaging belt integrates resin-to-package traceability systems for compliance verification.
Poland
Discount retailers pilot direct procurement from PCR-certified converters for private-label water bottles. Extended producer responsibility frameworks redirect packaging waste fees toward recycling infrastructure. Warsaw-based converters supply 100% PCR bottles bypassing traditional brand-owner intermediaries.
PCR Packaging for Food and Beverages Applications Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin purification and film extrusion. The vendor base organizes around three tiers: multinational converters with captive recycling partnerships, regional specialists in format-specific decontamination, and equipment-technology licensors. Strategic moves concentrate on backward integration into resin supply and geographic consolidation of food-grade certification assets.
Within the integrated converter tier, Berry Global exemplifies North American scale positioning through regional recycler partnerships. Amcor Group occupies the multinational platform position with film and fiber network integration. Mondi plc represents the European hybrid-format specialist navigating single-use plastic restrictions.
| Leading Market Players |
|---|
| Berry Global |
| Amcor Group |
| Mondi plc |
| Transcontinental Inc. |
| ePac Holdings, LLC |
| Novolex |
| Sealed Air Corporation |
| Sonoco Product Company |
| Coveris |
| Others |
Pricing and Supply Chain Analysis
The US Southeast pellet production corridor concentrates food-grade rPET capacity, exposing converters to hurricane-related disruption risks that translate directly into freight cost spikes and supply security premiums. Naphtha-linked virgin polyethylene pricing swings compress PCR resin premiums during oil market downturns, eroding recycler margins and forcing brand owners to absorb food-grade certification costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that normalize premium pricing for FDA Letter of No Objection certified supply. Price differentiation separates super-clean decontamination tiers from standard mechanical recycling outputs, with volume scale and EFSA challenge test documentation as secondary drivers. Cost compression in mid-tier converter segments intensifies because virgin price volatility erodes PCR premiums during energy market downturns. Private-label beverage brands at Polish and Spanish discounters exhibit highest price sensitivity, while EU dairy processors with binding CSRD obligations show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Post-consumer bale collection draws from municipal curbside systems in Germany, France, and the United States as primary feedstock inputs. Raw material dependencies center on mixed-color PET flake, food-contact approved additives, and super-clean recycling line capacity. Single-source vulnerability concentrates in the US Southeast pellet production cluster, where hurricane exposure threatens converter supply security. Distribution runs through converter-direct relationships with dairy processors and beverage brand owners, bypassing traditional wholesaler intermediaries as retailers build direct PCR-certified converter partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR packaging for food and beverages sits in early-cycle expansion as EU Green Deal mandates force binding recycled content floors across beverage containers, pulling investment into decontamination infrastructure ahead of supply maturity.
For Market Incumbents: Entrench supply security through captive resin partnerships with regional recyclers, mirroring Berry Global's North American positioning. Add food-grade certification assets in the Rhine-Ruhr corridor to defend against hurricane-related disruption in US Southeast supply. Prioritize backward integration into flake-sorting and melt-filtration systems to control EFSA compliance documentation bottlenecks. For New Entrants and Emerging Players: Hot-fill polypropylene retort pouch applications in shelf-stable meals offer underpenetrated white-space positioning due to thermal performance gaps in current PCR supply. Target Italian and Netherlands mid-sized dairy processors consolidating supplier bases to reduce CSRD audit burden. Enter through integrated resin-to-package traceability systems that command compliance service premiums. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-mandated infrastructure play because EU CSRD reporting obligations and extended producer responsibility frameworks create irreversible demand floors for food-grade recycled content. Acquisition targets should display decontamination line ownership paired with brand owner offtake agreements. Watch California SB 54 implementation progress as the inflection signal for North American regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Purification | Captive control over FDA Letter of No Objection supply secures converter margins against virgin price volatility. |
| Digital Watermarking Deployment | AI-powered sorting and blockchain traceability enable CSRD audit verification for brand owner compliance. |
| Hot-Fill rPP Capacity Buildout | First-mover positioning in retort pouch applications captures shelf-stable meal packaging demand. |
| Extended Producer Responsibility Partnership | California SB 54 fee redirection creates captive in-state food-grade recycling zones for converter supply security. |
| Kraft-Paper Hybrid Format Development | Mondi plc's European strategy navigates single-use plastic restrictions while maintaining barrier performance. |
Research Methodology
Cross-validation between primary interviews with decontamination plant managers, food-contact toxicologists, dairy procurement leads, and EFSA compliance officers anchors the qualitative findings against secondary validation. Bottom-up and top-down triangulation incorporates customs and trade data on food-grade resin imports, EU EFSA challenge test submission records, SEC 10-K filings from integrated converters, and municipal recycling system performance reports.
Calibration against historical mechanical recycling yield improvements and EU Green Deal implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, material certification tier, application heat requirements, and regional regulatory cluster. CAGRs derive from decontamination capacity expansion curves, brand owner tender specifications, and virgin-to-recycled price elasticity modeling through the forecast period.
Practitioners should monitor EU Packaging and Packaging Waste Regulation enforcement timelines and California SB 54 fee structure finalization for early signals of demand inflection. Forecasts reflect assumptions on mechanical recycling yield trajectories and EFSA migration limit stability. Material shifts in oil market volatility or EFSA decontamination efficiency standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market