
 Nordic Beverage Packaging Market | 2026-2036
Nordic Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Beverage Packaging Market Outlook
Lightweighting technology is fragmenting traditional material hierarchies across the Nordic beverage packaging value chain. Ball Corporation leverages its aluminum can manufacturing scale to supply craft breweries throughout Denmark and Norway. Tetra Pak anchors aseptic carton demand for ambient juices and plant-based drinks in Sweden. Stora Enso differentiates through integrated fiber-based barrier innovations that compete directly with conventional plastic linings.
Nordic beverage packaging encompasses the engineered containment, preservation, and distribution systems for liquid consumables, typically incorporating multilayer barrier structures with oxygen transmission rates below 0.1 cc per square meter per day to maintain product integrity. Its primary commercial purpose centers on extending shelf stability while enabling efficient cold-chain and ambient logistics for carbonated, still, and fermented beverages. Aluminum material segments lead volume contribution across the region due to recycling infrastructure maturity and deposit-return system economics. Paperboard cartons represent the fastest-expanding structural category as brand owners reformulate packaging portfolios around fiber-based alternatives. Glass bottle segments occupy premium positioning within alcoholic beverage channels where tactile differentiation commands shelf price premiums.
EU REACH chemicals regulation and the Packaging and Packaging Waste Directive shape material compliance obligations for all suppliers operating across Denmark, Finland, Norway, and Sweden. Sweden's EPA and Norway's Climate and Environment Ministry enforce extended producer responsibility frameworks that mandate minimum recycled content thresholds for plastic packaging placed on each national market. Stakeholders must monitor evolving deposit-return system harmonization negotiations between Nordic governments and the European Commission, as interoperability changes will reshape cross-border supply chain configurations and reverse logistics investments.
Market Dynamics
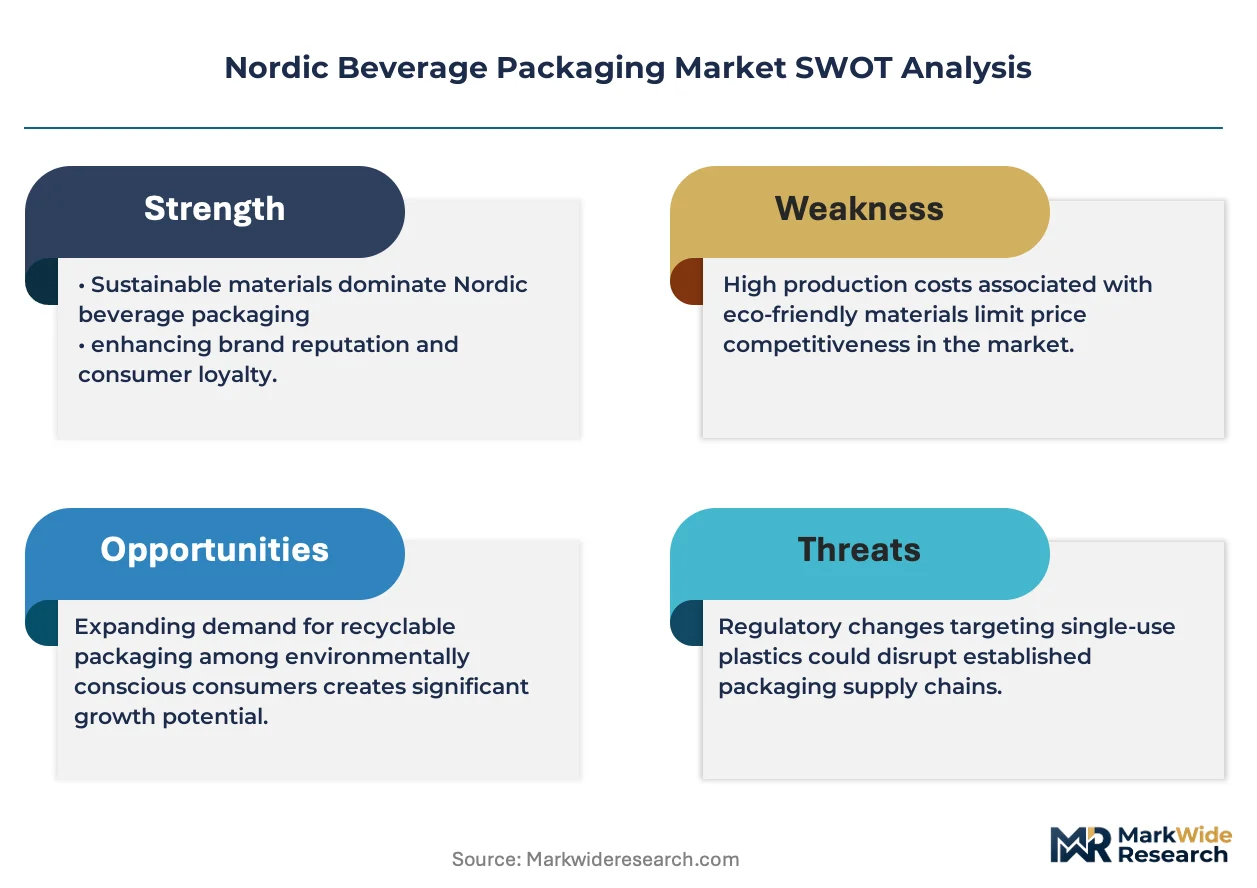
Deposit-return system economics are restructuring material selection priorities across Nordic beverage packaging, as aluminum's closed-loop recycling value outperforms competing substrates in Sweden, Norway, and Denmark.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive mandates fiber-based alternatives for specific beverage categories, accelerating paperboard carton adoption in Swedish juice and plant-based drink segments.
- Aluminum lightweighting:Sub-10 gram can designs reduce material input costs while maintaining structural integrity for carbonated beverages across Danish craft brewing operations.
- Stockholm-Uppsala packaging cluster:Concentrated R&D infrastructure and converter proximity enable rapid pilot-to-scale transitions for barrier-coated fiber prototypes.
Market Restraints
- Recycled aluminum ingot supply concentration:Nordic smelter capacity constraints create input bottlenecks for can sheet production, exposing converters to price volatility.
- Fiber barrier performance ceiling:Current polyethylene and PLA lining technologies fail to match aluminum's oxygen transmission rates for shelf-stable beer beyond six months.
- Extended producer responsibility fees:Sweden's EPA and Norway's Climate and Environment Ministry impose escalating compliance costs on plastic packaging that compress margin structures.
Strategic Opportunities
- Finland's underpenetrated craft segment:Helsinki's emerging brewery density lacks dedicated aluminum can supply agreements, creating first-mover positioning for regional converters.
- Cross-border deposit-return harmonization:Interoperability negotiations between Nordic governments and the European Commission promise unified reverse logistics networks.
- Aseptic carton line conversion:Ambient oat and pea protein beverages require high-barrier fiber packaging that Tetra Pak's Lund facility is positioned to scale.
Industry Challenges
- Multilayer separation expertise:Fiber-based barrier packaging demands specialized recycling infrastructure that Nordic mechanical recovery plants currently lack.
- Legacy glass bottling asset stranding:Premium alcoholic beverage producers face sunk-cost pressure when evaluating aluminum migration for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Beverage Packaging Market |
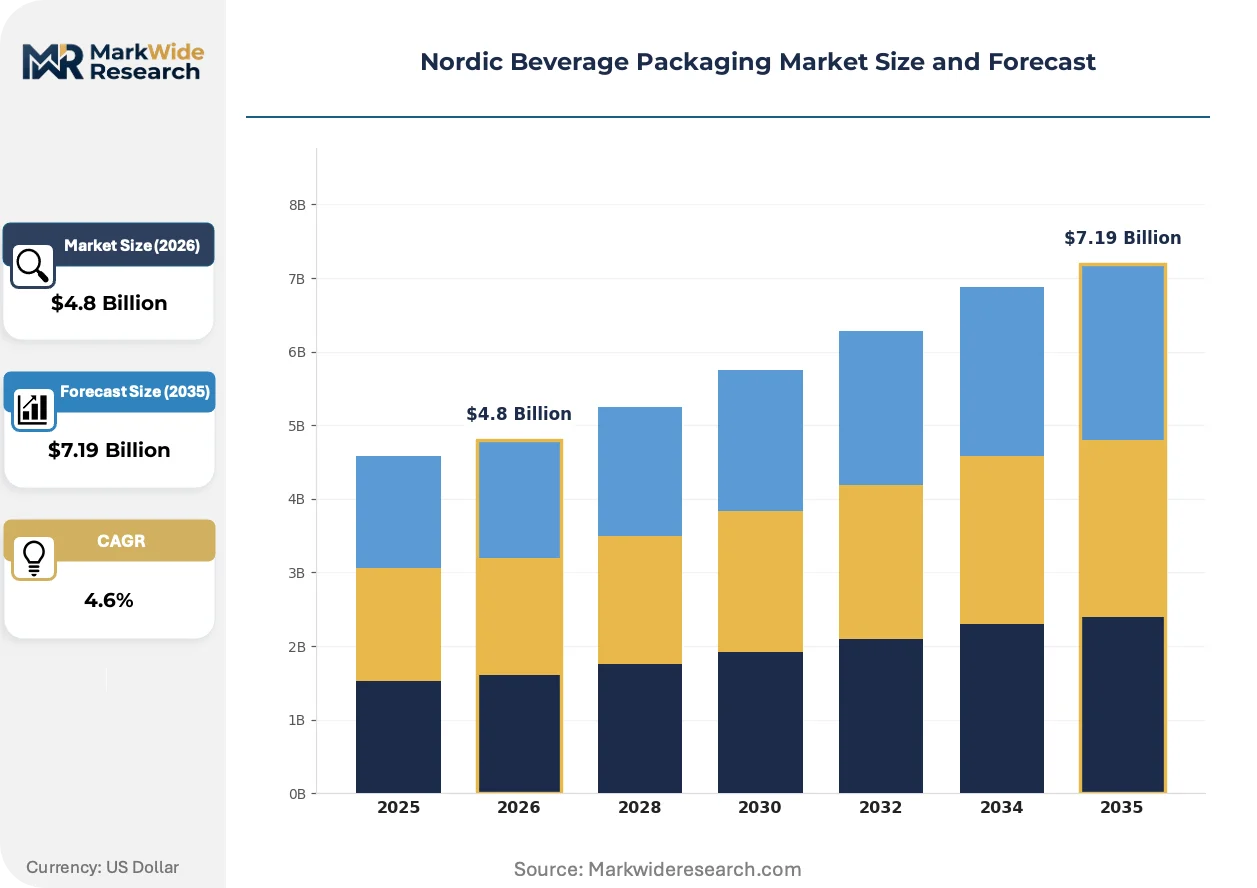
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Pouches, Cartons Material: Glass, Aluminum, Plastic, Paperboard End User: Soft Drinks, Alcoholic Beverages, Juices, Water Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ball Corporation, Amcor, Tetra Pak, Billerud AB, Crown Holdings, Stora Enso, Mondi, Huhtamaki, Ardagh Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Beverage Packaging Market Strategic Shifts
Barrier coating chemistry and sorting infrastructure are converging to expand fiber packaging's addressable beverage categories beyond historical temperature and shelf-life limitations.
Water-based barrier coatings with sub-0.1 cc oxygen transmission rates are rendering obsolete conventional polyethylene linings in aseptic carton applications. Swedish oat milk producers are converting filling lines at pace. The technology is compressing aluminum's historical dominance in ambient plant-based beverages.
REACH chemicals regulation and the EU Packaging and Packaging Waste Directive are tightening substance restrictions and recycled content mandates simultaneously. Nordic converters must reformulate adhesives and coatings while documenting circularity metrics. Swedish juice brands are accelerating fiber-only portfolio transitions to preempt compliance deadlines.
Direct-to-brewery aluminum can procurement is displacing distributor-mediated supply relationships across Denmark and Norway. Craft breweries with volumes below five million units annually now contract directly with regional can manufacturers. This pattern concentrates most visibly in Copenhagen's brewery district.
Nordic Beverage Packaging Market Segmentation
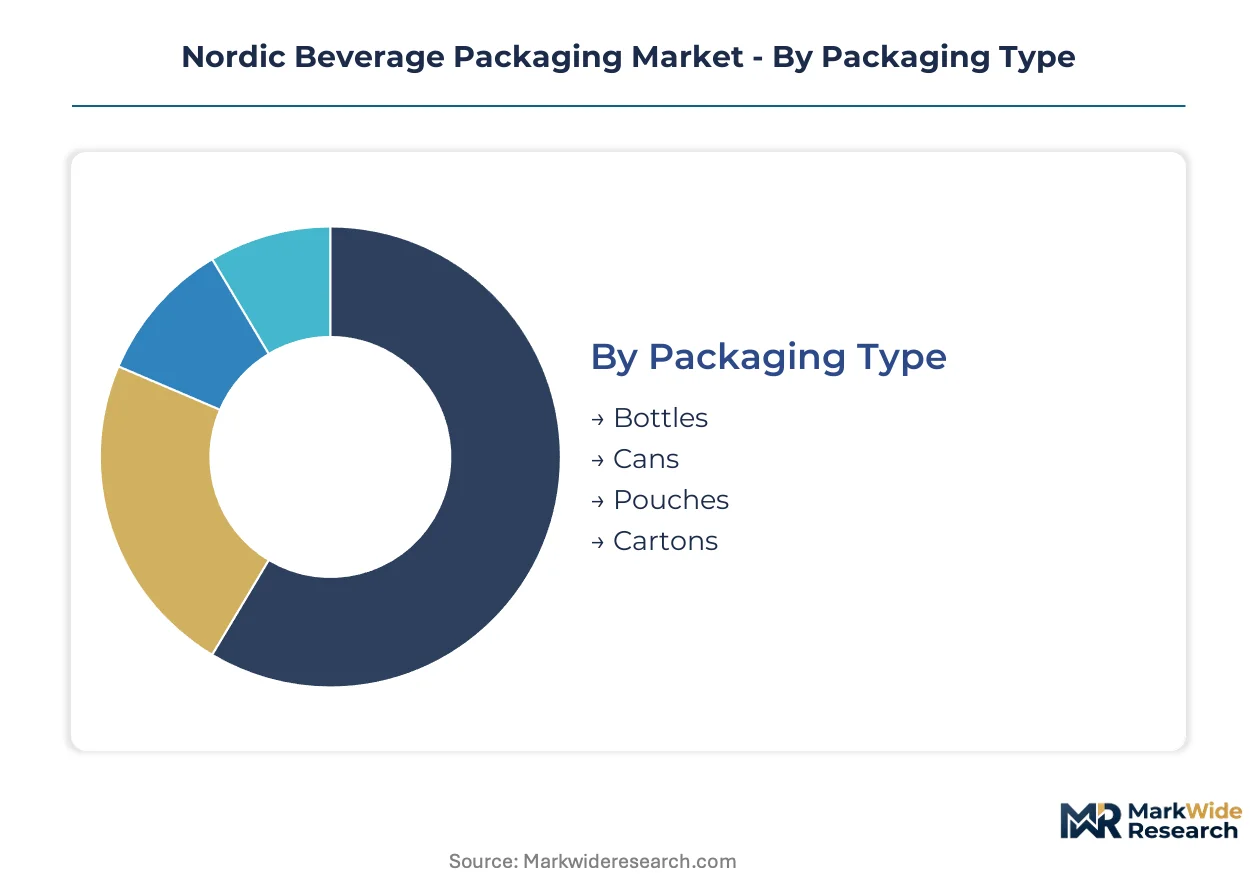
Packaging specifications in Nordic markets diverge sharply across beverage categories, driven by deposit-return economics and EU regulatory mandates. Material selection and format sizing directly determine reverse logistics costs and shelf-life performance in Sweden, Norway, and Denmark.
Packaging Type:
Mature formats dominate volume, while emerging structures capture regulatory tailwinds.
- Bottles:Glass and PET configurations serve premium alcoholic channels and carbonated soft drinks across Danish and Swedish retail. Deposit-return infrastructure maturity sustains bottle economics despite aluminum encroachment.
- Cans:Sub-10 gram aluminum designs enable cost-efficient carbonated beverage distribution. Danish craft breweries and Norwegian mineral water producers are converting filling lines at pace.
- Pouches:Flexible multilayer structures address on-the-go consumption in Finnish and Swedish convenience retail. Stand-up pouch adoption lags due to limited Nordic mechanical recycling compatibility.
- Cartons:Aseptic fiber-based barriers serve ambient oat and pea protein beverages. Swedish juice brands are accelerating fiber-only portfolio transitions to preempt EU Single-Use Plastics Directive deadlines.
Cans retain volume leadership; cartons hold the steepest expansion curve.
Material:
Cost tiers separate premium positioning from mass-market commodity supply.
- Glass:Silica-based containers command tactile differentiation premiums in Norwegian and Danish craft spirits channels. High weight and fragility constrain export logistics economics.
- Aluminum:Closed-loop recycling value outperforms competing substrates in Sweden, Norway, and Denmark. Recycled ingot supply concentration creates input bottlenecks for can sheet production.
- Plastic:PET and rPET formulations face escalating extended producer responsibility fees from Sweden's EPA and Norway's Climate and Environment Ministry. Recycled content mandates compress margin structures.
- Paperboard:Barrier-coated fiber prototypes compete with conventional plastic linings. Stockholm-Uppsala packaging cluster proximity enables rapid pilot-to-scale transitions for Swedish converters.
Aluminum dominates unit economics; paperboard is climbing the fastest on regulatory displacement.
End User:
Application requirements dictate barrier performance specifications and cold-chain dependencies.
- Soft Drinks:Carbonated formulations demand oxygen transmission rates below 0.1 cc per square meter per day. Swedish and Danish bottlers prioritize aluminum can lightweighting to reduce material input costs.
- Alcoholic Beverages:Beer, cider, and spirits segments split between glass premium positioning and aluminum export convenience. Finnish craft breweries lack dedicated can supply agreements, creating first-mover opportunities.
- Juices:Ambient distribution requirements favor aseptic carton configurations. Swedish oat milk producers are converting filling lines as water-based barrier coatings render polyethylene linings obsolete.
- Water:Still and sparkling categories concentrate in PET and glass for domestic Nordic consumption. Norwegian mineral water exports to continental Europe increasingly adopt aluminum formats.
Soft drinks anchor aluminum demand; juices are gaining share fastest on fiber substitution.
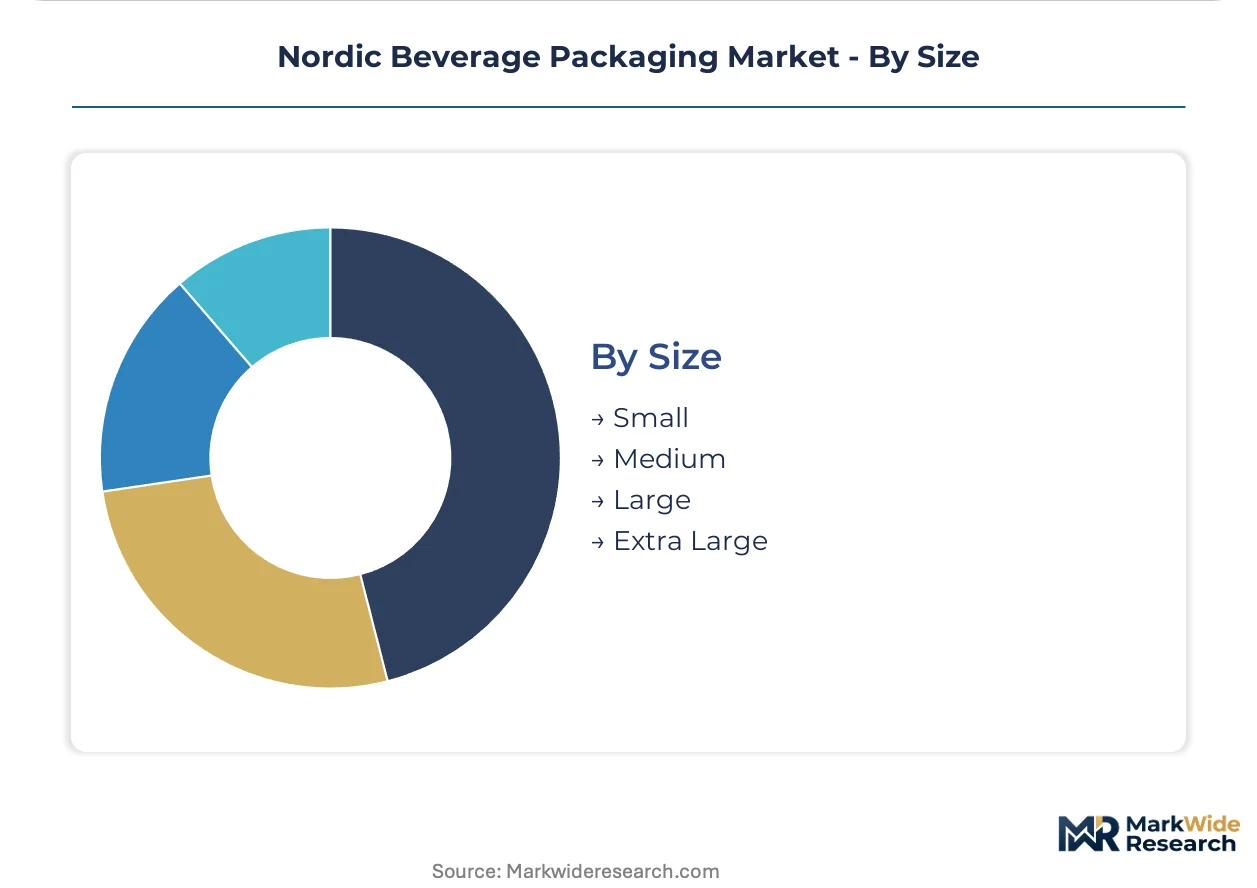
Size:
Volume tiers align with consumption occasion segmentation and retail channel requirements.
- Small:Single-serve 250-330ml formats dominate on-premise and convenience retail across Copenhagen and Stockholm. Premium pricing per liter offsets higher packaging-to-product ratios.
- Medium:500ml configurations balance portability with household consumption economics. Danish craft breweries and Swedish juice brands standardize on this tier for retail multipacks.
- Large:1-1.5 liter family sizes concentrate in grocery retail and deposit-return system volumes. Norwegian and Swedish consumers favor this tier for water and soft drink home consumption.
- Extra Large:2+ liter formats serve foodservice and institutional channels with reduced per-unit packaging costs. Limited presence in Nordic retail due to handling ergonomics and deposit logistics.
Medium sizes command the broadest channel coverage; small formats are expanding most quickly in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish juice brands and Danish craft breweries concentrate purchasing power for fiber-based and aluminum formats. Norway's mineral water exporters and Finland's emerging brewery scene represent distinct buyer archetypes with divergent packaging requirements.
Sweden
Stockholm-Uppsala packaging cluster proximity enables rapid pilot-to-scale transitions for barrier-coated fiber prototypes. Sweden's EPA enforces extended producer responsibility frameworks with escalating fees on plastic packaging. Tetra Pak's Lund facility anchors aseptic carton scaling for oat and pea protein beverages.
Denmark
Copenhagen's brewery district drives direct-to-brewery aluminum can procurement for craft producers below five million units annually. The EU Single-Use Plastics Directive accelerates fiber-based substitution timelines for domestic juice brands. Danish deposit-return infrastructure sustains glass bottle economics despite aluminum encroachment in premium alcoholic channels.
Norway
Norwegian mineral water producers convert filling lines to aluminum formats for continental European export expansion. Norway's Climate and Environment Ministry mandates minimum recycled content thresholds for plastic packaging placed on the national market. Oslo-based converters face recycled aluminum ingot supply concentration from Nordic smelter capacity constraints.
Finland
Helsinki's emerging brewery density lacks dedicated aluminum can supply agreements, creating first-mover positioning opportunities for regional converters. Finnish deposit-return system economics favor aluminum's closed-loop recycling value over competing substrates. Espoo-based R&D infrastructure supports barrier coating chemistry development for fiber packaging applications.
Nordic Beverage Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across material hierarchies. The vendor base spans integrated multinationals with converter scale and regional specialists with barrier innovation capabilities. Two strategic archetypes dominate: aluminum can manufacturers leveraging recycling infrastructure maturity, and fiber-based barrier developers capturing regulatory tailwinds from EU Single-Use Plastics Directive mandates. Competitive moves concentrate on capacity expansion in underpenetrated geographies and strategic partnerships for cross-border deposit-return harmonization.
Among aluminum specialists, Ball Corporation and Crown Holdings exemplify scale-driven positioning for craft brewery supply. Within fiber-based barriers, Stora Enso anchors integrated pulp-to-packaging control. Tetra Pak occupies a distinct position linking aseptic technology with Lund-based production scale for plant-based beverage segments.
| Leading Market Players |
|---|
| Ball Corporation |
| Amcor |
| Tetra Pak |
| Billerud AB |
| Crown Holdings |
| Stora Enso |
| Mondi |
| Huhtamaki |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Recycled aluminum ingot supply concentration from Nordic smelter capacity constraints compresses margin structures for can sheet converters while simultaneously determining tier spreads between premium barrier-coated fiber and commodity aluminum formats. This single-source dependency forces Swedish and Norwegian converters to absorb volatility pass-through, widening the pricing gap between deposit-return system-optimized materials and conventional plastic alternatives.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum pricing dominate converter-brand owner relationships across Denmark and Norway. Price differentiation stratifies across premium barrier-coated fiber, standard aluminum can sheet, and economy-grade rPET tiers, with certification to EU Single-Use Plastics Directive compliance timelines commanding material premiums. Cost compression in standard aluminum runs through recycled ingot bottlenecks at Nordic smelters. Craft breweries below five million units annually exhibit highest price sensitivity, while Swedish oat milk producers with aseptic carton line investments show lowest.
Supply Chain Analysis
Contract manufacturing concentration sits with Ball Corporation's Malmö facility and Tetra Pak's Lund operation anchoring regional can and aseptic carton capacity respectively. Geographic supply concentration draws from Sweden, Denmark, and Germany for barrier-coated paperboard, with aluminum can sheet sourcing tethered to Norwegian and Icelandic smelter output. Raw material dependencies center on bauxite-refined alumina, sustainably certified pulp, and bio-based barrier polymers. Single-source vulnerability persists in recycled aluminum ingot channels. Distribution runs through Stockholm-Uppsala packaging cluster hub-and-spoke configurations reaching Copenhagen, Oslo, and Helsinki.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Deposit-return system interoperability negotiations between Nordic governments and the European Commission create switching costs that lock in incumbent converter positions.
For Market Incumbents: Insulate market position by securing long-term recycled aluminum ingot offtake agreements with Norwegian smelters before capacity constraints intensify. Deepen backward integration into barrier coating chemistry development at Stockholm-Uppsala cluster facilities to preempt Stora Enso's fiber-based innovation pipeline. The threat of water-based barrier coatings displacing aluminum in ambient plant-based beverages demands accelerated R&D lock-in. For New Entrants and Emerging Players: Establish a beachhead in Finland's underpenetrated craft brewery segment where dedicated aluminum can supply agreements remain unclaimed. Target Helsinki's emerging brewery density with direct-to-brewery procurement models proven in Copenhagen's brewery district. The most penetrable white-space sits in medium-format aseptic carton supply for oat and pea protein beverages, with go-to-market leverage through Espoo-based R&D partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fiber-barrier specialists with captive pulp supply. Long-term viability across the projection horizon rests on regulatory tailwind capture rather than commodity cyclicality. Acquisition target archetype: regional converters with proven barrier coating scale and deposit-return system certification. The signal to watch is cross-border deposit-return harmonization implementation timing as inflection indicator for reverse logistics network economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Aluminum Supply | Captive ingot access insulates Ball Corporation and Crown Holdings from Nordic smelter bottlenecks. |
| Barrier Coating Chemistry Partnership | Stora Enso's water-based oxygen barrier collaborations compress Tetra Pak's historical aseptic dominance. |
| Direct-to-Brewery Distribution Expansion | Copenhagen-proven procurement models unlock Finnish craft segment penetration for regional converters. |
| Aseptic Carton Line Conversion | Swedish oat milk producers' filling line investments validate Lund facility scaling for plant-based beverages. |
| Cross-Border Deposit-Return Harmonization | Interoperability negotiations between Nordic governments reshape reverse logistics network investments. |
Study Parameters
A standing panel of packaging procurement managers at Swedish juice brands, Danish craft brewery operations directors, Norwegian mineral water export specialists, and Finnish converter technical leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EU Packaging and Packaging Waste Directive filings, Swedish EPA extended producer responsibility fee schedules, Norwegian Climate and Environment Ministry recycled content mandates, and Nordic smelter capacity disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic overlays.
Scenario-bracketing framed low, base, and high cases across the analysis window without deterministic point estimates. Segmentation dimensions modeled include packaging type, material substrate, end-use beverage category, format size tier, and regional deposit-return system configuration. CAGRs derived from curve-fitting historical volume trajectories against regulatory phase-in schedules and converter capacity expansion announcements. Industry-specific forecast inputs incorporated barrier coating technology readiness levels and aluminum lightweighting design iteration cycles.
Macroeconomic conditions sit as an overlay; deviation in Nordic electricity pricing, pulp futures, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding deposit-return harmonization timing and fiber barrier performance ceilings. Quarterly review of smelter capacity utilization, barrier coating pilot announcements, and interoperability negotiation communiqués is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Burger Boxes Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Poultry Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Seafood Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market