
 Chilled Food Packaging Market | 2026-2036
Chilled Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Food Packaging Market Analysis
Modular tray-lid combinations with interchangeable film specifications is expanding buyer choice across temperature-sensitive categories. Sealed Air leverages its Cryovac portfolio to dominate vacuum-sealed protein applications. Huhtamaki anchors European demand through fiber-based chilled tray capacity. Berry Global competes in multi-layer barrier films for extended shelf-life dairy.
Chilled food packaging encompasses temperature-controlled containment systems engineered to maintain 0°C to 4°C product integrity through multi-layer polymer structures or coated paperboard with oxygen transmission rates below 1 cc/m²/day. Flexible formats lead volume due to lightweighting advantages and rollstock efficiency on high-speed form-fill-seal lines. Modified atmosphere technology captures margin pools in premium prepared meals where residual oxygen below 0.5% extends sensory shelf life. Barrier technology segments sustain pricing power as ethylene vinyl alcohol coextrusion commands specification loyalty from protein processors.
EMA food contact regulations, EU Packaging and Packaging Waste Regulation targets, and FDA Title 21 CFR 177 compliance requirements collectively reshape material selection and migration testing protocols. EFSA migration limit enforcement accelerates substitution of conventional multilayer structures toward recyclable mono-polyethylene designs. Stakeholders must monitor polymer recycling infrastructure readiness against tightening extended producer responsibility thresholds.
Market Dynamics
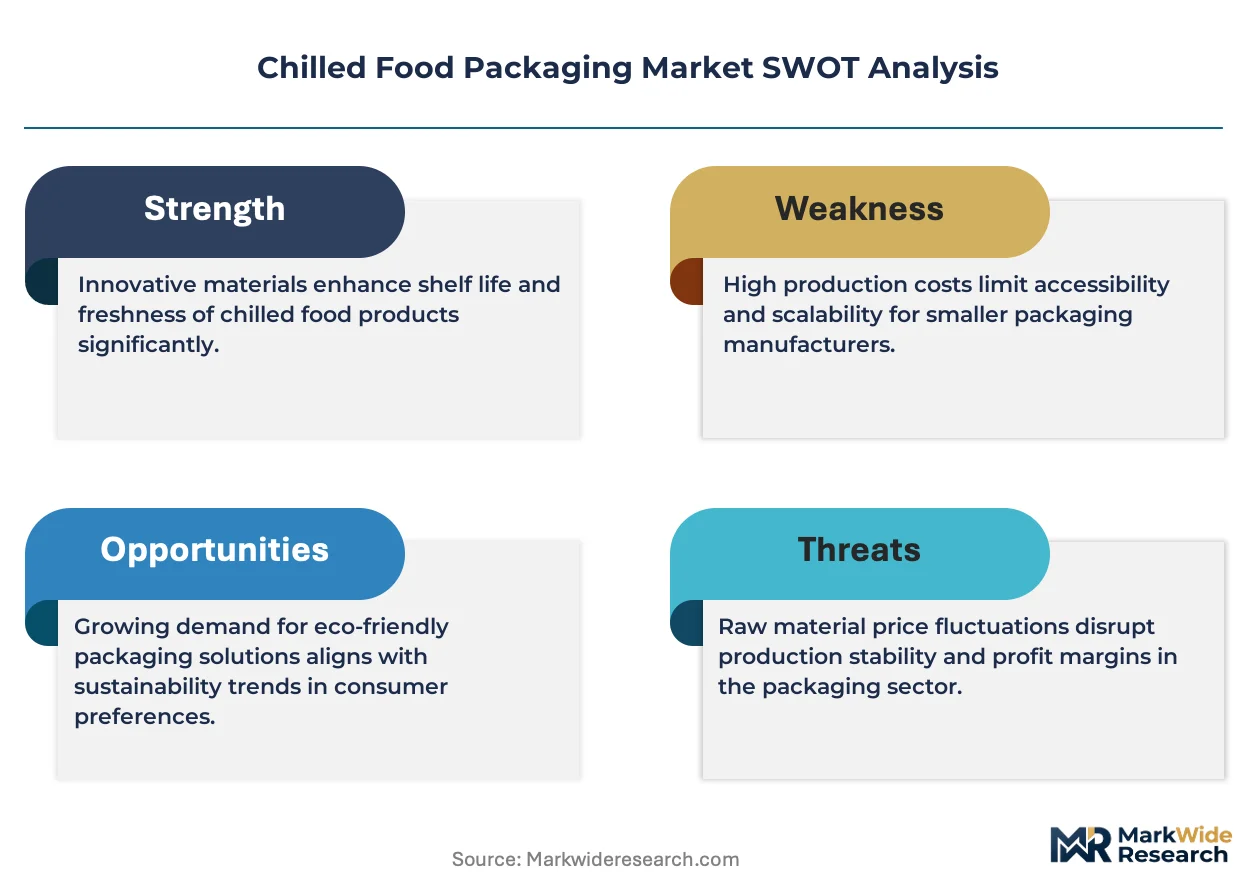
The EU Packaging and Packaging Waste Regulation is forcing converters to abandon multi-layer barrier structures in favor of recyclable mono-material designs, compressing legacy capacity while creating first-mover advantages for retooling leaders.
Growth Catalysts
- Ready-to-eat meal proliferation:European retail chains are expanding private-label chilled ranges, driving specification demand for high-oxygen-barrier flexible formats in prepared protein and pasta segments.
- Modified atmosphere technology maturation:Residual oxygen control below 0.5% is extending sensory shelf life in premium prepared meals, capturing margin pools from conventional chilled distribution.
- EMA food contact compliance harmonization:Streamlined migration testing protocols are reducing time-to-market for new material formulations across European protein processors.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Barrier resin production clusters in Northeast Asian petrochemical complexes expose converters to feedstock volatility and logistics disruption.
- Recyclability-performance tradeoff:Mono-polyethylene structures sacrifice oxygen transmission performance versus legacy EVOH coextrusion, limiting adoption in high-value protein segments.
- Extended producer responsibility thresholds:EU member state implementation timelines for packaging waste fees vary, creating compliance fragmentation for pan-European suppliers.
Strategic Opportunities
- Coated paperboard chilled tray expansion:Fiber-based formats with aqueous barrier coatings are penetrating dairy and deli categories where grease resistance and cold-chain rigidity converge.
- Refrigerated e-commerce fulfillment:Direct-to-consumer meal kit channels are specifying insulated pouch-in-box configurations with gel-pack compatibility for last-mile temperature integrity.
- EFSA migration limit substitution incentives:Regulatory pressure on conventional additives is accelerating demand for bio-based barrier coatings from European packaging converters.
Industry Challenges
- Multi-layer delamination expertise scarcity:Separation of incompatible polymers for chemical recycling requires capital-intensive sorting infrastructure that few European converters possess.
- Legacy form-fill-seal line reconfiguration:Mono-material film specifications demand seal-bar temperature and pressure recalibration, extending qualification timelines for high-speed dairy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Food Packaging Market |
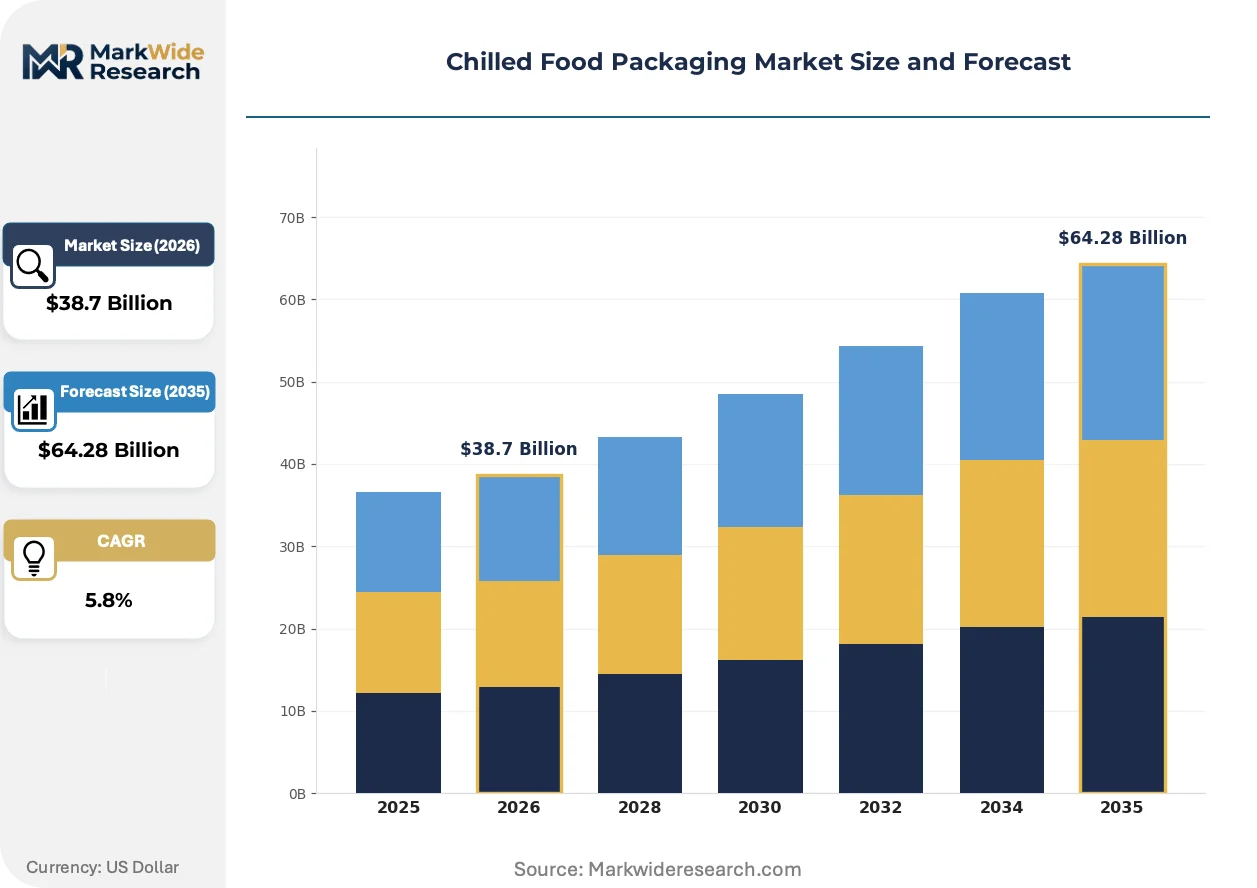
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible, Rigid, Modified Atmosphere, Vacuum Sealed Material: Plastic, Glass, Metal, Paperboard End User: Retail, Food Service, E-commerce, Food Processing Technology: Active Packaging, Smart Packaging, Eco-friendly Packaging, Barrier Technology |
| Companies Covered | Sealed Air, Linpac Packaging, Amcor, Ampac Holdings, Huhtamaki, Berry Global, International Paper, DS Smith, Sonoco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Food Packaging Market Emerging Trajectories
Active barrier technologies and substrate substitution are compressing conventional material hierarchies while regulatory deadlines force accelerated qualification cycles across European converter networks.
High-barrier mono-polyethylene films with plasma-deposited silicon oxide coatings are electrifying vacuum-sealed protein applications by matching EVOH oxygen transmission rates at reduced material mass. German and Dutch meat processors are specifying these formats for sliced deli categories. The technology is electrifying competitive positioning among mid-cap converters with captive coating capacity.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from paperboard chilled trays. European dairy and prepared food brands are migrating to clay-based or bio-wax barrier alternatives. EFSA enforcement timelines are compressing supplier qualification windows, favoring converters with existing pilot coating partnerships.
Retail buyer consolidation across German, French, and British grocery chains is centralizing chilled packaging procurement through dedicated category managers. Volume commitments are shifting toward multi-year supply agreements with technical collaboration clauses. British supermarket private-label expansion is driving this behavioral change most visibly, with specification authority migrating from brand marketing to supply chain functions.
Chilled Food Packaging Market Segmentation
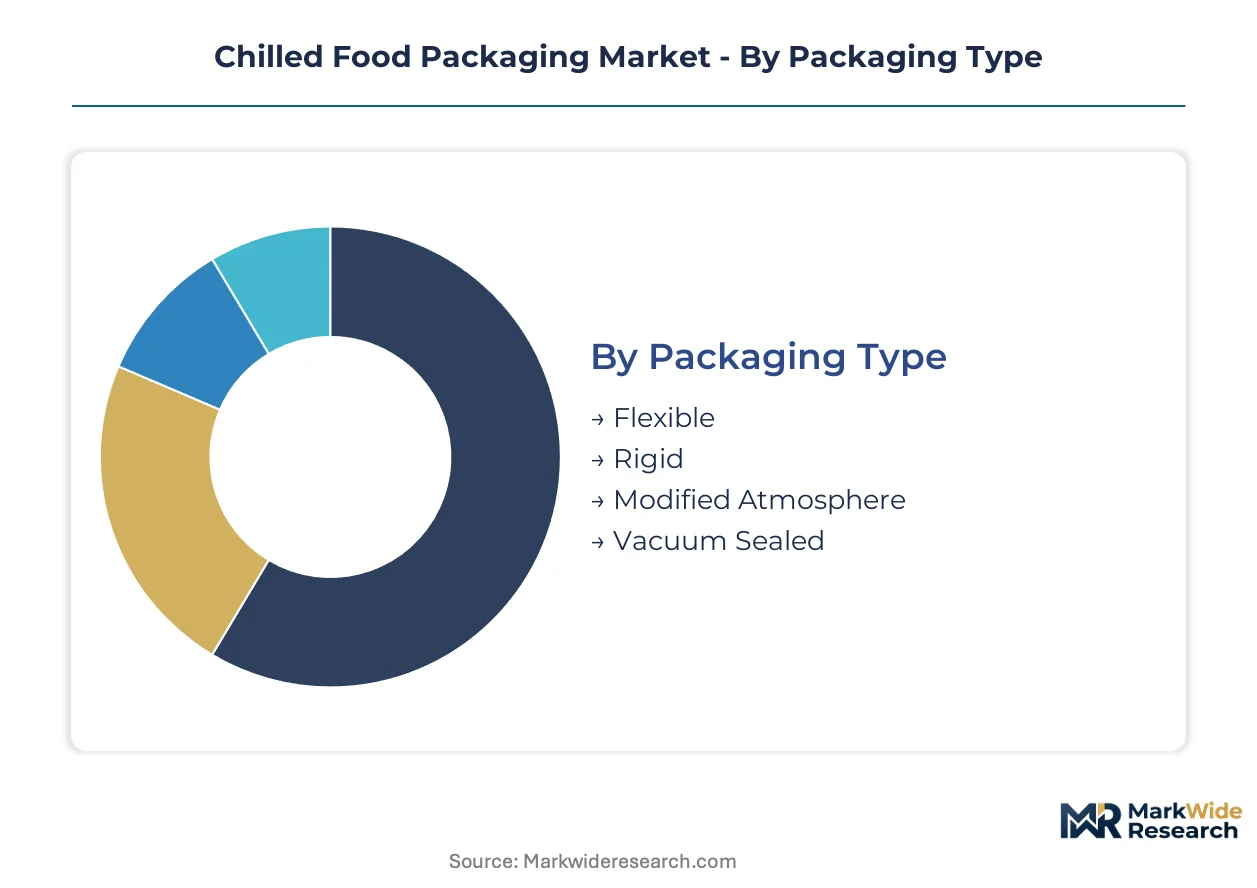
Chilled food packaging segmentation reveals how converter capacity aligns with temperature-sensitive supply chains. Material choices and format specifications diverge sharply across protein, dairy, and prepared meal channels.
Packaging Type:
Flexible film capacity clusters with European rollstock converters serving high-speed form-fill-seal dairy lines.
- Flexible:Multi-layer polymer rollstock dominates volume through lightweighting advantages and high-speed line efficiency. German and Dutch meat processors specify these formats for sliced deli and marinated protein segments where oxygen transmission below 1 cc/m²/day preserves color stability.
- Modified Atmosphere:Gas-flush tray-lid systems with residual oxygen control below 0.5% extend sensory shelf life in premium prepared meals. British supermarket private-label ranges are standardizing these specifications across pasta and protein-based ready-to-eat offerings.
- Rigid:Injection-molded trays and thermoformed tubs provide structural integrity for wet dairy and sauced applications.
- Vacuum Sealed:Cryovac-derived shrink-bag technology maintains protein freshness through oxygen exclusion and moisture retention.
Flexible formats absorb the bulk of installed capacity; Modified Atmosphere is expanding most quickly.
Material:
Converter investment patterns split between legacy multi-layer lines and mono-material retooling demanded by EU Packaging and Packaging Waste Regulation timelines.
- Plastic:Polyethylene and polypropylene structures command specification loyalty through seal integrity and moisture barrier performance. EVOH coextrusion layers face substitution pressure as EFSA migration limits tighten, yet retain dominance in high-value protein segments where oxygen sensitivity is critical.
- Paperboard:Fiber-based chilled trays with aqueous barrier coatings are penetrating dairy and deli categories. Huhtamaki's European capacity expansion reflects buyer demand for grease-resistant formats that satisfy extended producer responsibility thresholds.
- Metal:Tinplate and aluminum cans preserve shelf-stable chilled soups and sauces through hermetic sealing.
- Glass:Premium dairy and condiment applications specify glass for inertness and consumer perception of quality.
Plastic retains the deepest installed base; Paperboard is climbing the fastest among material transitions.
End User:
Procurement authority is migrating from brand marketing to supply chain functions as retail buyer consolidation centralizes chilled packaging decisions.
- Retail:German, French, and British grocery chains dominate volume through private-label chilled range expansion. Category managers now hold specification authority, driving multi-year supply agreements with technical collaboration clauses for barrier performance and recyclability compliance.
- E-commerce:Direct-to-consumer meal kit channels specify insulated pouch-in-box configurations with gel-pack compatibility. Last-mile temperature integrity requirements are reshaping format specifications toward multi-layer protective structures.
- Food Service:Contract caterers and restaurant distributors prioritize portion control and food safety labeling compliance.
- Food Processing:Protein and dairy manufacturers source captive packaging or contract with dedicated converters for integrated filling operations.
Retail channels command the largest volume commitments; E-commerce is gaining share fastest among end-user categories.
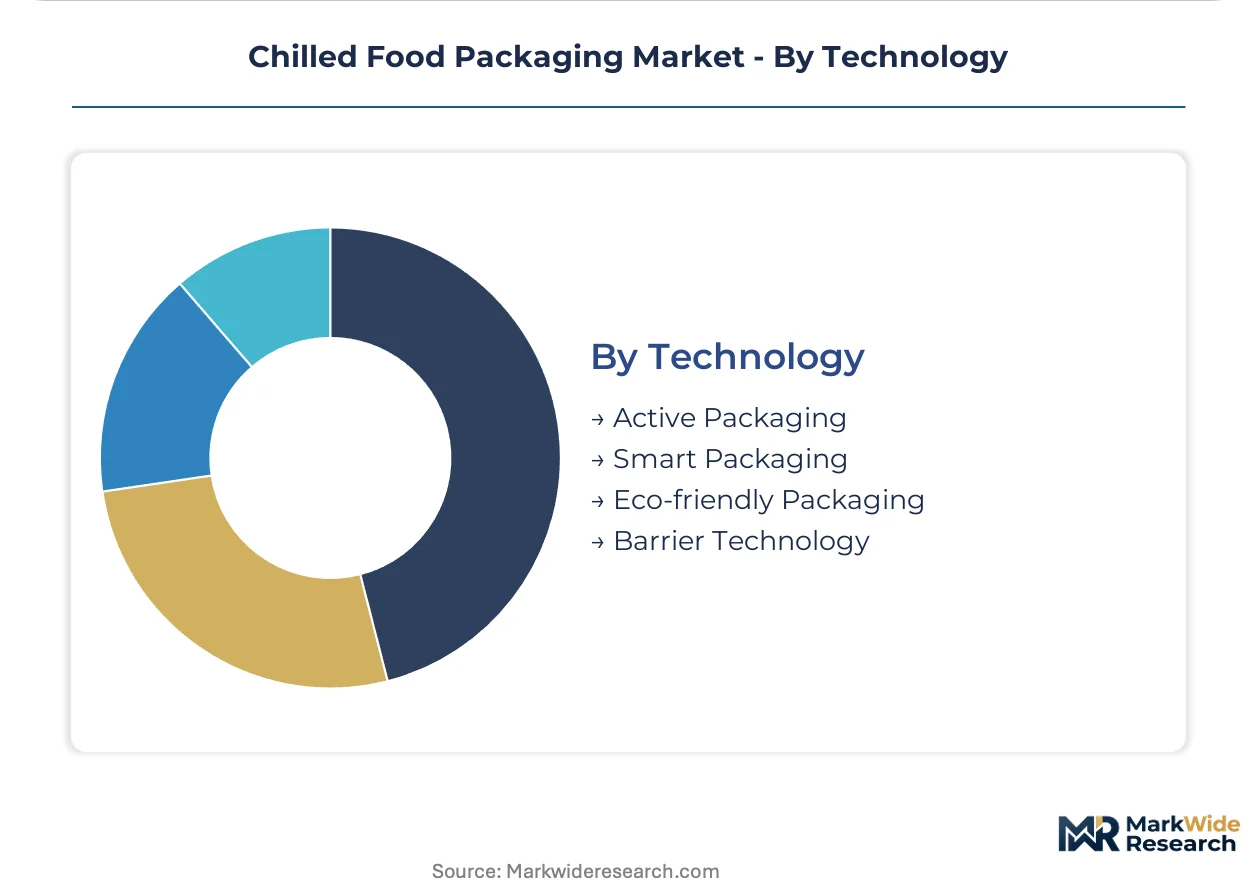
Technology:
Patent activity concentrates in barrier coating deposition and sensor integration for cold-chain verification.
- Barrier Technology:Ethylene vinyl alcohol coextrusion and emerging plasma-deposited silicon oxide coatings compete for vacuum-sealed protein applications. German meat processors are qualifying mono-polyethylene alternatives that match legacy oxygen transmission rates at reduced material mass.
- Eco-friendly Packaging:Bio-based barrier coatings and recyclable mono-material designs accelerate as REACH restrictions eliminate fluorochemical treatments from paperboard trays. EFSA enforcement timelines compress supplier qualification windows.
- Active Packaging:Oxygen scavengers and moisture regulators extend shelf life in premium chilled segments.
- Smart Packaging:Time-temperature indicators and RFID tracking verify cold-chain integrity through distribution.
Barrier Technology holds the deepest specification entrenchment; Eco-friendly Packaging faces the steepest expansion trajectory as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux packaging corridors concentrate chilled food converter capacity through Dutch and Belgian tax-advantaged logistics zones serving northwest European distribution networks.
Germany
Private-label chilled range expansion at Rewe and Edeka drives specification demand for high-barrier flexible formats. EFSA migration limit enforcement accelerates substitution toward mono-polyethylene designs. The Ruhr industrial belt hosts retooling investments for recyclable barrier film capacity.
France
Carrefour and Intermarché centralize procurement for prepared meal packaging through dedicated category managers. REACH restrictions on fluorochemical treatments eliminate legacy grease-resistant paperboard coatings. The Lyon corridor concentrates aqueous barrier coating pilot partnerships for dairy tray applications.
United Kingdom
Tesco and Sainsbury's multi-year supply agreements reshape specification authority toward supply chain functions. Extended producer responsibility thresholds under UK packaging regulations create compliance fragmentation. The Midlands packaging cluster qualifies mono-material films for high-speed dairy form-fill-seal lines.
Netherlands
Albert Heijn's chilled ready-to-eat proliferation drives modified atmosphere tray-lid specifications. EU Packaging and Packaging Waste Regulation timelines compress converter qualification windows. The Rotterdam-Antwerp corridor anchors plasma-deposited silicon oxide coating capacity for vacuum-sealed protein applications.
Italy
Coop and Conad expand chilled pasta and protein ranges requiring residual oxygen control below 0.5%. EMA food contact compliance harmonization reduces time-to-market for new material formulations. The Emilia-Romagna packaging belt concentrates fiber-based chilled tray investments for deli category penetration.
Chilled Food Packaging Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material and format boundaries. The vendor base splits between integrated packaging groups with captive resin supply and independent converters with regional filling partnerships. Three archetypes dominate: multi-material platform operators, mono-material retooling specialists, and fiber-based format innovators. Competitive moves concentrate on strategic partnerships for barrier coating technology and capacity expansion in recyclable film lines.
Within the diversified conglomerate tier, Sealed Air and Amcor exemplify platform breadth across flexible and rigid formats. Berry Global occupies a position among North American-based multi-layer specialists navigating EVOH substitution pressures. Huhtamaki represents the fiber-based format archetype through European tray capacity expansion.
| Leading Market Players |
|---|
| Sealed Air |
| Linpac Packaging |
| Amcor |
| Ampac Holdings |
| Huhtamaki |
| Berry Global |
| International Paper |
| DS Smith |
| Sonoco Products |
| Others |
Supply Flow & Price Mechanics
EU Packaging and Packaging Waste Regulation mandates on mono-material recyclability are forcing converters to absorb retooling costs and pass selective premiums to buyers specifying barrier performance. Supply response concentrates in German and Dutch coating capacity where plasma-deposited silicon oxide lines command specification loyalty from protein processors unwilling to sacrifice oxygen transmission rates.
Pricing Analysis
Short lead-time premiums attach to mono-polyethylene films with plasma-deposited barrier coatings where German meat processors face compressed qualification windows. Three-tier pricing structure across premium, standard, and economy levels separates EVOH coextrusion legacy formats from emerging silicon oxide alternatives and commodity polyethylene structures. Pricing pressure stems from EVOH feedstock volatility concentrated in Northeast Asian petrochemical complexes. Private-label retail buyers exhibit highest price sensitivity; premium prepared meal brands prioritize barrier performance over unit cost.
Supply Chain Analysis
Direct-to-retail channels handle volume commitments from consolidated German, French, and British grocery chains through dedicated category managers. Raw material supply draws from Belgium, the Netherlands, and Germany where barrier coating pilot partnerships cluster. Feedstock dependence rests on ethylene vinyl alcohol resin imports, aqueous coating chemicals, and recycled polyethylene flake. Single-source vulnerability runs through EVOH production concentration in Northeast Asia. Distribution runs through Rotterdam-Antwerp logistics corridors serving northwest European cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a compliance moat that favors converters with captive mono-material retooling capacity and penalizes legacy multi-layer operators. EFSA migration limit enforcement accelerates this barrier-to-entry dynamic.
For Market Incumbents: Deepen backward integration into plasma-deposited coating capacity to defend margin position against EVOH substitution pressures. Secure multi-year supply agreements with technical collaboration clauses before retail buyer consolidation centralizes procurement authority further. Add recyclable film capacity in the Ruhr industrial belt to capture German private-label specification demand. For New Entrants and Emerging Players: REACH restrictions on per- and polyfluoroalkyl substances in Europe open a window for aqueous barrier coating specialists to penetrate dairy and deli tray segments. Target coated paperboard formats where Huhtamaki's capacity expansion signals buyer demand validation. Pursue pilot partnerships with Lyon corridor converters to accelerate EFSA qualification timelines. For Investors and Strategic Acquirers: The window for entry favors mono-material retooling specialists with captive coating technology over diversified multi-layer legacy operators. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Watch EFSA enforcement timelines as the inflection signal for accelerated substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retooling | Converters in the Ruhr belt capture Edeka and Rewe specification shifts toward recyclable barrier films. |
| Plasma-Coating Capacity Expansion | Rotterdam-Antwerp corridor investments match EVOH oxygen transmission rates at reduced material mass. |
| Private-Label Supply Agreement | Tesco and Sainsbury's multi-year contracts with technical clauses lock in category manager procurement authority. |
| Aqueous Barrier Pilot Partnership | Lyon corridor collaborations accelerate dairy tray qualification under compressed EFSA enforcement windows. |
| EFSA Compliance Certification | Migration testing protocol mastery reduces time-to-market for new mono-polyethylene formulations. |
Methodological Framework
Trade association filings, EU regulatory databases, and customs records formed the secondary backbone for supply-side capacity mapping. Primary interviews with packaging converter plant managers, retail category buyers, barrier coating R&D directors, and cold-chain logistics operators validated material substitution trends. Bottom-up triangulation across installed line capacity and top-down demand modeling from retail chilled range expansion produced convergent volume estimates.
Historical trendline analysis of flexible film rollstock consumption and rigid tray deployment patterns anchored the projection framework. Segmentation dimensions modeled include packaging format, material substrate, end-user channel, and barrier technology tier across the analysis window. CAGRs derived from curve-fitting against regulatory deadline impacts and retail private-label rollout schedules. EVOH price volatility indices and coating capacity utilization rates fed industry-specific forecast sensitivity.
Caveats apply where EFSA enforcement timeline acceleration or EVOH supply disruption could materially shift the outlook beyond modeled substitution rates. Forecasts reflect assumptions about polymer recycling infrastructure readiness and extended producer responsibility fee harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market