
 North America PET Food Packaging Market | 2026-2036
North America PET Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America PET Food Packaging Market Outlook
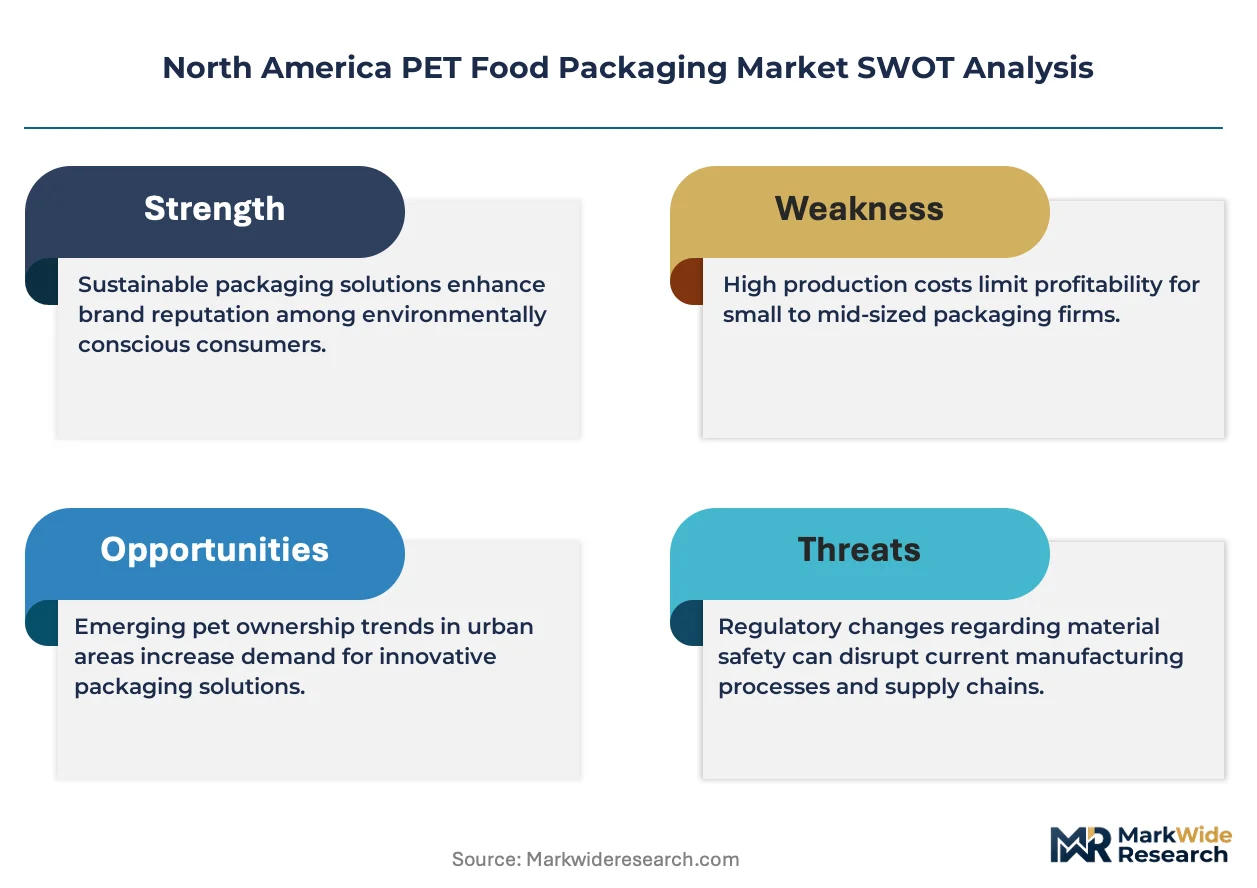
FDA food-contact notification cycles for recycled PET is reorganizing supplier qualification timelines across the industry. Amcor PLC leverages integrated film extrusion capabilities to sustain supply security for major pet food brands. Berry Global Inc. anchors its position through vertical control over blow-molded container production. ProAmpac LLC differentiates via specialized high-barrier flexible structures for oxygen-sensitive formulations.
North America PET food packaging encompasses primary and secondary containment systems engineered from polyethylene terephthalate resins, with oxygen transmission rates typically below 0.1 cc per square inch per day for multi-layer constructions, serving to preserve nutritional integrity and extend shelf stability of commercial pet nutrition products. Flexible pouches now capture the fastest expansion as wet food brands replace metal cans with retortable film structures, while rigid containers retain volume leadership in dry kibble segments where stackability and pallet efficiency dominate logistics planning. Multi-layer PET commands premium positioning due to its barrier performance, though recyclable PET formats face margin compression as mechanical recycling specifications tighten.
The FDA governs indirect food additive compliance under 21 CFR 177.1315, while EPA regulations on per- and polyfluoroalkyl substances are accelerating fluoropolymer barrier phaseouts in favor of silicon oxide coatings. State-level extended producer responsibility frameworks in California and Oregon are forcing redesign of non-recyclable laminated structures. Stakeholders must monitor emerging PFAS restrictions and decide whether to absorb reformulation costs or pass them through contract renegotiations.
Market Dynamics
Retortable flexible pouches are compressing metal can dominance as wet pet food brands pursue shelf-stable formats with lower logistics costs and improved shelf aesthetics.
Growth Catalysts
- Extended Producer Responsibility mandates:California and Oregon frameworks are forcing packaging redesign toward recyclable mono-material structures, accelerating supplier qualification for post-consumer PET streams.
- Premium wet food format migration:Oxygen-sensitive formulations in retortable pouches are capturing shelf space from legacy cans, demanding high-barrier film extrusion capabilities.
- Southeast US contract packaging clusters:Concentrated toll manufacturing capacity near major pet food processors is reducing lead times for regional brand launches.
Market Restraints
- Recycled PET feedstock volatility:Mechanical recycling specification tightening is compressing qualified resin supply and inflating input costs for multi-layer structures.
- Fluoropolymer barrier phaseout:EPA restrictions on per- and polyfluoroalkyl substances are eliminating incumbent oxygen barrier chemistries before silicon oxide coating scale-up completes.
- Film extrusion equipment concentration:Limited North American suppliers of seven-layer coextrusion lines are extending capital deployment timelines for barrier film capacity.
Strategic Opportunities
- Canadian provincial EPR expansion:British Columbia and Ontario are implementing packaging stewardship frameworks that reward recyclable mono-material designs with fee reductions.
- Silicon oxide coating convergence:Vacuum deposition technology married to PET film substrates is enabling fluorine-free barrier performance at commercial scale.
- Veterinary prescription channel growth:Therapeutic pet nutrition distributed through clinic networks requires specialized portion-control pouch formats with child-resistant features.
Industry Challenges
- FDA food-contact notification timelines:Recycled PET qualification cycles are extending supplier onboarding by 12-18 months, freezing formulation changes.
- Multi-layer delamination infrastructure:Existing mechanical recycling streams cannot process laminated pouch structures, creating stranded material volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America PET Food Packaging Market |
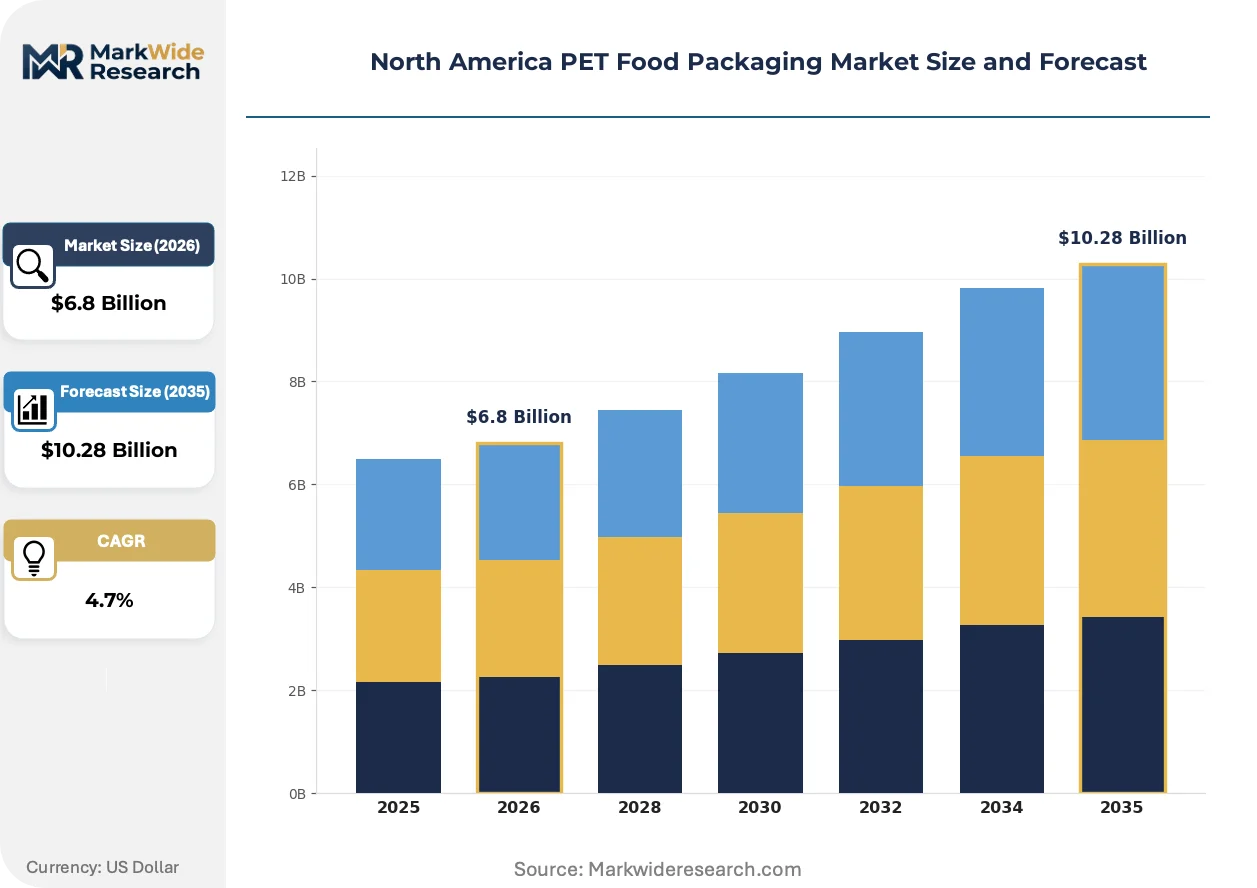
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pouches, Rigid Containers, Vacuum Packs, Stand-Up Pouches Material: Biodegradable PET, Recyclable PET, Multi-Layer PET, Laminated PET Closure Type: Screw Caps, Snap-On Lids, Zippers, Heat-Sealed End User: Pet Owners, Pet Shops, E-Commerce Platforms, Veterinary Clinics |
| Companies Covered | Berry Global Inc., Sealed Air Corporation, Amcor PLC, Huhtamaki Oyj, Winpak Ltd., Sonoco Products Company, ProAmpac LLC, Crown Holdings Inc., Mondi PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America PET Food Packaging Market Strategic Shifts
Barrier coating chemistry and flexible format engineering are converging to displace incumbent rigid containers while regulatory pressure on material safety accelerates reformulation investment.
Silicon oxide vacuum deposition is miniaturizing barrier coating application onto PET films, replacing fluoropolymer laminates in retortable pouch constructions. Mid-size wet food brands in the US Southeast are adopting these structures fastest, driven by co-packer equipment upgrades. The technology is miniaturizing the barrier layer thickness while maintaining oxygen transmission below 0.1 cc per square inch per day, compressing material costs and enabling pouch-to-can substitution at scale.
EPA per- and polyfluoroalkyl substance restrictions are eliminating C8 fluoropolymer barriers from food-contact applications by 2025. Pet food packagers must reformulate multi-layer structures or absorb penalties under state-level chemical disclosure laws. Premium wet food segments in California face immediate compliance deadlines, accelerating silicon oxide and aluminum oxide coating qualification programs.
Direct-to-subscription procurement is consolidating buyer power among e-commerce native pet food brands, bypassing traditional distributor networks. Regional contract packagers are responding with dedicated fulfillment lines and variable batch sizes. This pattern concentrates most visibly in Texas and Florida, where digitally native brands source toll manufacturing for personalized nutrition subscriptions.
North America PET Food Packaging Market Segmentation
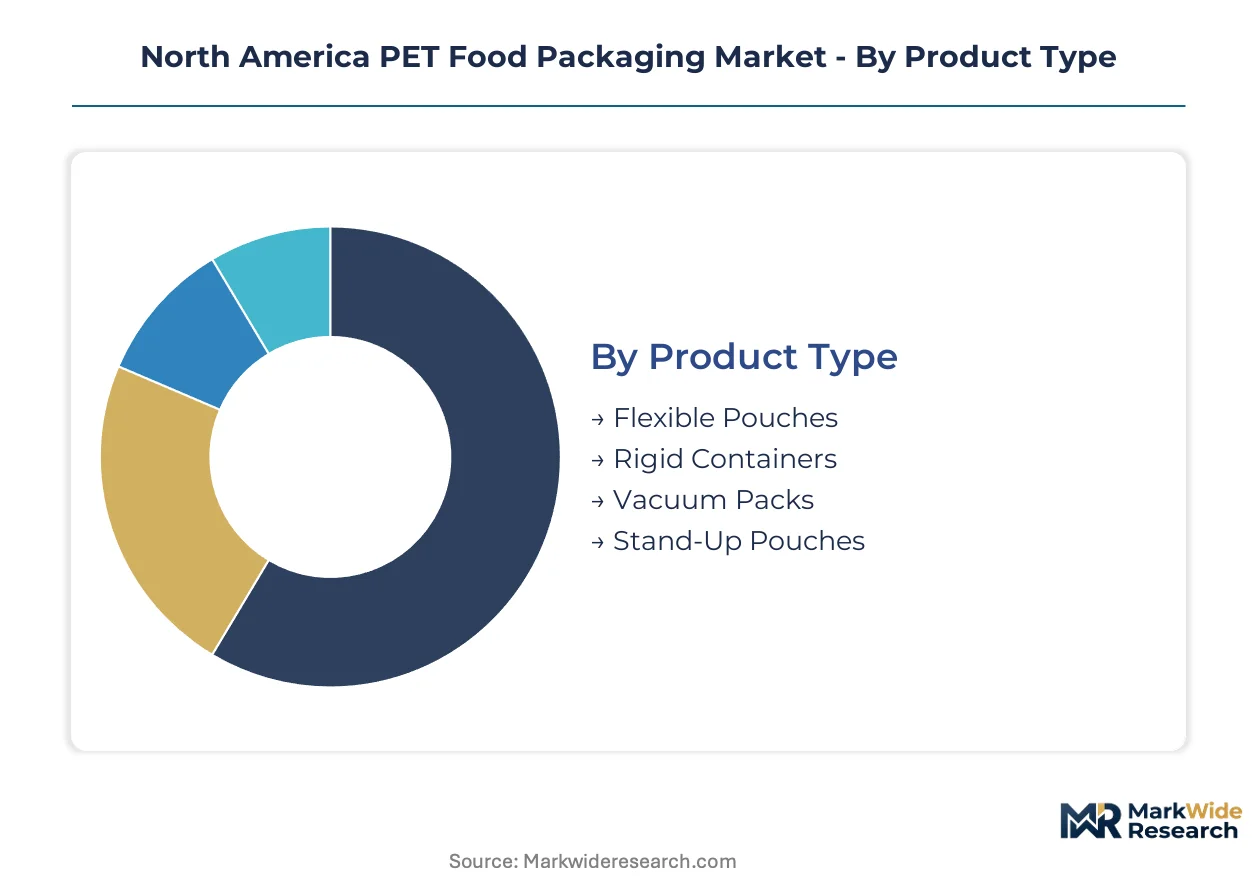
Segmentation in the North America PET food packaging market reveals how format choices align with distribution economics and regulatory pressure points. Each dimension—product type, material, closure, and end user—channels investment toward specific barrier technologies and recyclability profiles.
Product Type:
Channel mix varies sharply by format, with retail shelf presence driving rigid container specifications while e-commerce fulfillment favors lightweight flexible structures.
- Flexible Pouches:Retortable multi-layer film constructions with oxygen transmission below 0.1 cc per square inch per day. Wet food brands in the US Southeast are migrating from metal cans to these formats, driven by co-packer equipment upgrades and lower logistics cube.
- Rigid Containers:Blow-molded PET jars and bottles with stackable geometries optimized for pallet density. Dry kibble processors in Texas and Florida specify these for warehouse club and mass retail channels where shelf stability and display presence dominate.
- Vacuum Packs:Thermoformed trays with modified atmosphere capabilities serving premium raw and freeze-dried segments.
- Stand-Up Pouches:Gusseted flexible formats with resealable features capturing subscription and specialty retail channels.
Rigid containers dominate installed base. Flexible pouches are where expansion concentrates.
Material:
Cost tiers separate segments, with multi-layer constructions commanding premium positioning while recyclable mono-materials face margin compression from mechanical recycling specification tightening.
- Multi-Layer PET:Coextruded or laminated structures combining PET with EVOH or polyamide barrier layers. California and Oregon extended producer responsibility frameworks are forcing redesign of these non-recyclable formats, accelerating silicon oxide coating qualification.
- Recyclable PET:Mono-material designs qualified for post-consumer mechanical recycling streams. FDA food-contact notification cycles for recycled PET feedstock are reorganizing supplier qualification timelines, extending onboarding by 12-18 months.
- Biodegradable PET:Bio-based or compostable resin alternatives targeting premium sustainability-positioned brands.
- Laminated PET:Adhesive-bonded multi-ply constructions facing stranded material volumes as existing recycling infrastructure cannot process delaminated pouch structures.
Multi-layer PET holds volume leadership. Recyclable PET is climbing the fastest as EPR mandates bite.
Closure Type:
Application requirements dictate closure selection, with portion control and resealability driving premium specifications versus cost-optimized heat-sealed formats in commodity segments.
- Zippers:Press-to-close interlocking profiles integrated into flexible pouch top webs. Veterinary prescription channels in the US Southeast specify child-resistant zipper variants for therapeutic nutrition portion control.
- Heat-Sealed:Hermetic fusion seals for single-serve wet food pouches where resealability is unnecessary and cost minimization is paramount.
- Screw Caps:Injection-molded continuous thread closures for rigid container neck finishes.
- Snap-On Lids:Press-fit closures for wide-mouth rigid containers in treat and supplement applications.
Heat-sealed closures anchor commodity volume. Zippers are gaining share fastest on premium wet food migration.
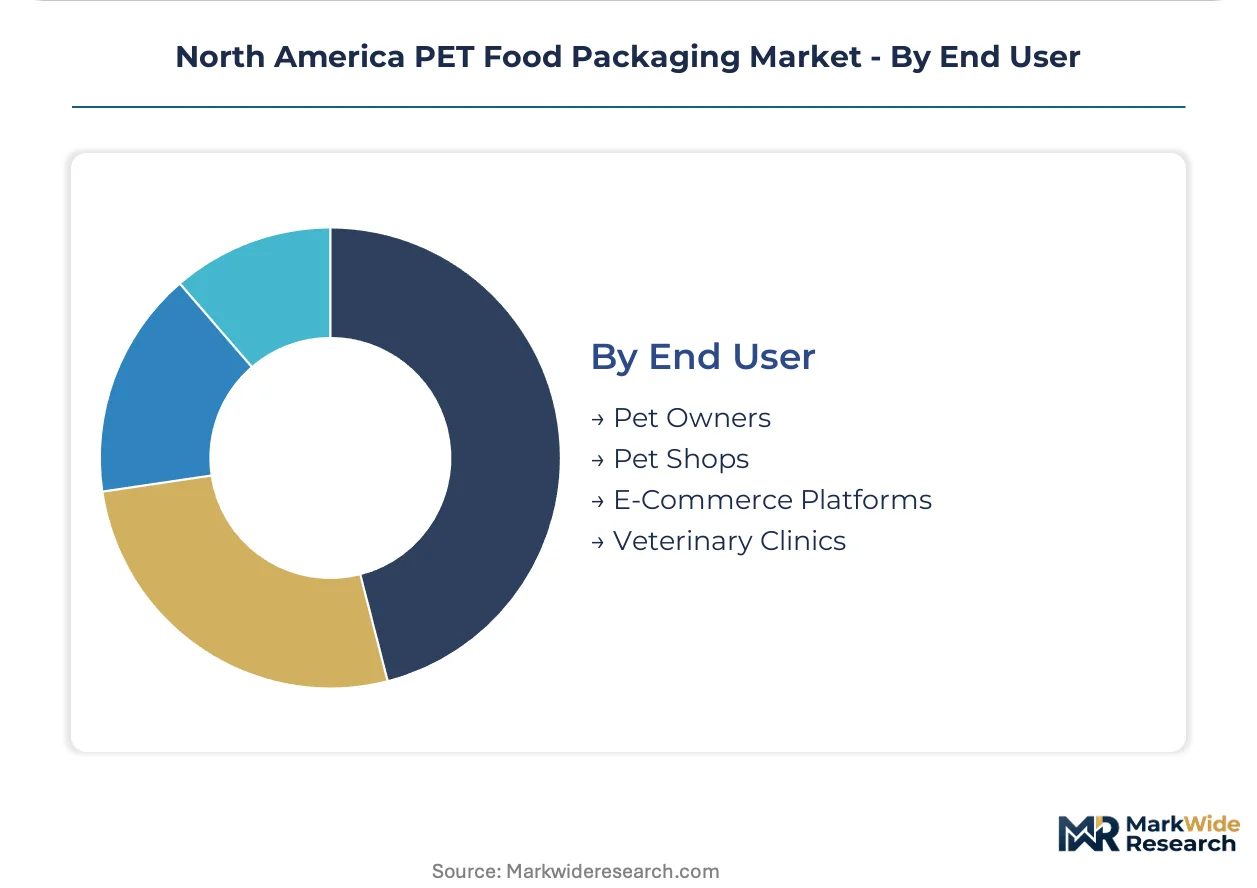
End User:
Customer type determines batch size, customization depth, and regulatory stringency, with veterinary and e-commerce channels imposing distinct specification layers over standard retail formats.
- E-Commerce Platforms:Direct-to-subscription procurement consolidating buyer power among digitally native brands. Regional contract packagers in Texas and Florida are responding with dedicated fulfillment lines and variable batch sizes for personalized nutrition subscriptions.
- Veterinary Clinics:Therapeutic pet nutrition distribution requiring specialized portion-control pouch formats with child-resistant features and extended shelf stability for prescription compliance.
- Pet Owners:Mass-market retail purchasers driving standardization and cost optimization in primary packaging specifications.
- Pet Shops:Specialty retail channel demanding differentiated shelf aesthetics and premium tactile finishes.
Pet owners represent the broadest installed demand base. E-commerce platforms are where format innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility frameworks in California and Oregon are accelerating packaging redesign toward recyclable mono-material structures across North America. FDA food-contact notification cycles for recycled PET feedstock are reorganizing supplier qualification timelines. Contract packaging clusters near major pet food processors are reducing lead times for regional brand launches.
United States
Premium wet food brands in the Southeast are migrating from metal cans to retortable flexible pouches, demanding high-barrier film extrusion capabilities. EPA restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer barriers before silicon oxide coating scale-up completes. Texas and Florida host concentrated toll manufacturing capacity serving digitally native subscription brands with dedicated fulfillment lines.
Canada
British Columbia and Ontario are implementing packaging stewardship frameworks that reward recyclable mono-material designs with fee reductions. Health Canada regulations on food-contact materials are tightening compliance requirements for imported packaging components. Quebec and Ontario-based converters are qualifying post-consumer PET streams for veterinary prescription pouch formats.
Mexico
Nuevo León and Jalisco are attracting contract packaging investment from US pet food brands seeking nearshoring alternatives. Mexico's federal environmental regulations on plastic waste management are aligning with California-style extended producer responsibility principles. Bajío Region co-packers are scaling retortable pouch capacity for wet food exports to the US Southwest.
North America PET Food Packaging Market Competitive Environment
Player mix skews toward integrated multinational packaging conglomerates with film extrusion and rigid container capabilities. Tier concentration is moderate, with three to four firms commanding significant share in barrier film and blow-molded segments. Strategic archetypes include vertically integrated resin-to-package operators, specialized high-barrier film converters, and regional contract packaging networks. Dominant competitive moves center on silicon oxide coating technology licensing and backward integration into recycled PET feedstock qualification.
Within the integrated multinational tier, Amcor PLC and Berry Global Inc. exemplify scale-driven positioning through captive control over extrusion and molding operations. ProAmpac LLC occupies a specialist position in high-barrier flexible structures for oxygen-sensitive formulations. These three firms anchor competitive dynamics as EPA fluoropolymer phaseouts and state-level extended producer responsibility mandates force simultaneous reformulation across multiple product lines.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Sealed Air Corporation |
| Amcor PLC |
| Huhtamaki Oyj |
| Winpak Ltd. |
| Sonoco Products Company |
| ProAmpac LLC |
| Crown Holdings Inc. |
| Mondi PLC |
| Others |
Value Chain & Pricing Dynamics
Seven-layer coextrusion line scarcity in North America compresses barrier film capacity and elevates price floors for oxygen-sensitive pouch formats. This equipment concentration hands pricing leverage to incumbent converters while forcing mid-size wet food brands into longer contract terms.
Pricing Analysis
Certification level (FDA food-contact notification status) creates the primary spread between qualified recycled PET suppliers and unqualified commodity resin sources. Three-tier pricing structure across premium silicon oxide-coated barriers, standard multi-layer laminates, and economy heat-sealed formats reflects this compliance gradient. Pricing pressure stems from mechanical recycling specification tightening inflating post-consumer PET feedstock costs. Mass-market retail purchasers exhibit highest price sensitivity, while veterinary prescription channels absorb premiums for child-resistant zipper features.
Supply Chain Analysis
Inbound logistics costs through West Coast ports constrain California-based converters sourcing Asian silicon oxide deposition equipment. Raw material dependencies center on virgin PET resin from US Gulf Coast crackers, EVOH barrier resins from Texas and Louisiana, and aluminum oxide coating precursors from Canadian suppliers. Single-source vulnerability concentrates in seven-layer coextrusion line manufacturers, where limited North American suppliers extend capital deployment timelines. Distribution runs through Southeast US contract packaging clusters serving major pet food processors with dedicated fulfillment lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as direct-to-subscription procurement consolidates buyer power among digitally native brands, creating niche openings for specialized converters outside incumbent networks.
For Market Incumbents: Secure captive supply of qualified recycled PET feedstock through backward integration into mechanical recycling streams, insulating margin position against FDA notification timeline extensions. Anchor barrier film capacity with silicon oxide coating licensing agreements before fluoropolymer phaseout deadlines eliminate incumbent chemistries. Defend against regional contract packager encroachment by embedding dedicated fulfillment lines with top subscription brands in Texas and Florida. For New Entrants and Emerging Players: Differentiate on fluorine-free barrier performance for California premium wet food brands facing immediate EPA compliance deadlines. Penetrate veterinary prescription pouch formats in the US Southeast, where child-resistant zipper specifications and extended shelf stability requirements filter out commodity converters. Pursue co-packer partnerships with toll manufacturers scaling retortable pouch capacity for mid-size brands migrating from metal cans. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract packagers with dedicated fulfillment lines for subscription nutrition brands, offering visibility through variable batch size contracts. Long-term viability favors converters with integrated film extrusion capabilities spanning both rigid container and flexible pouch formats. Watch silicon oxide coating scale-up completion as inflection indicator for fluoropolymer replacement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Oxide Coating Scale-Up | Enables fluorine-free barrier performance for retortable pouches before EPA phaseout deadlines. |
| Recycled PET Feedstock Qualification | Secures FDA-compliant resin streams for mono-material designs under California EPR frameworks. |
| Contract Packaging Cluster Expansion | Reduces lead times for regional brand launches near Southeast US pet food processors. |
| Child-Resistant Closure Development | Captures veterinary prescription channel growth with specialized portion-control pouch formats. |
| Direct-to-Subscription Fulfillment Lines | Aligns capacity with digitally native brands bypassing traditional distributor networks. |
Study Parameters
Operator-level perspectives from pet food packaging procurement managers, contract manufacturing executives, FDA regulatory affairs specialists, and veterinary distribution channel heads anchored the qualitative base. Secondary validation drew from FDA food-contact notification databases, EPA chemical restriction filings, state extended producer responsibility regulatory texts, and customs trade records for PET resin and barrier film imports. Bottom-up capacity assessments triangulated against top-down demand modeling across wet and dry food format segments.
Sensitivity analysis tested forecast outputs against recycled PET feedstock availability scenarios, silicon oxide coating adoption curves, and EPR mandate implementation timelines. Segmentation dimensions spanned product type (flexible pouch, rigid container, vacuum pack, stand-up pouch), material construction (multi-layer, recyclable mono-material, biodegradable, laminated), closure mechanism, and end-user channel. CAGRs derived from historical shipment data and projected format migration rates, with veterinary prescription and e-commerce channels weighted separately.
The analysis sits within stated boundaries; outcomes outside sustained FDA notification timeline extensions, accelerated PFAS regulatory enforcement, or breakthrough barrier coating technologies would require recalibration. Forecasts reflect assumptions about mechanical recycling infrastructure expansion and state-level EPR framework adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Poultry Packaging Market