
 Asia Pacific Food Packaging Market | 2026-2036
Asia Pacific Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Food Packaging Market Analysis
Ready-to-eat meal demand is recalibrating packaging specifications across Asia Pacific foodservice channels. Amcor leverages its flexible film portfolio to capture shelf-life extension contracts with regional quick-service chains. Tetra Pak anchors aseptic carton supply for ambient dairy and plant-based beverages in South and Southeast Asia. Huhtamaki dominates molded fiber and paper-based solutions as QSR brands phase out single-use plastics.
Asia Pacific food packaging encompasses materials, containers, and barrier systems engineered to protect edible products from oxygen ingress, moisture loss, and microbial contamination across supply chains spanning tropical climates. Primary functions include shelf-life extension, portion control, brand communication, and logistics compatibility for temperature-sensitive goods. Plastic formats still lead total volume but paper-based alternatives are expanding fastest as export buyers impose EUDR-aligned sustainability requirements. Flexible packaging captures margin pools in snack and confectionery segments where lightweighting and printability command premium positioning. Rigid formats sustain dominance in dairy and beverages where structural integrity and resealability determine purchasing decisions.
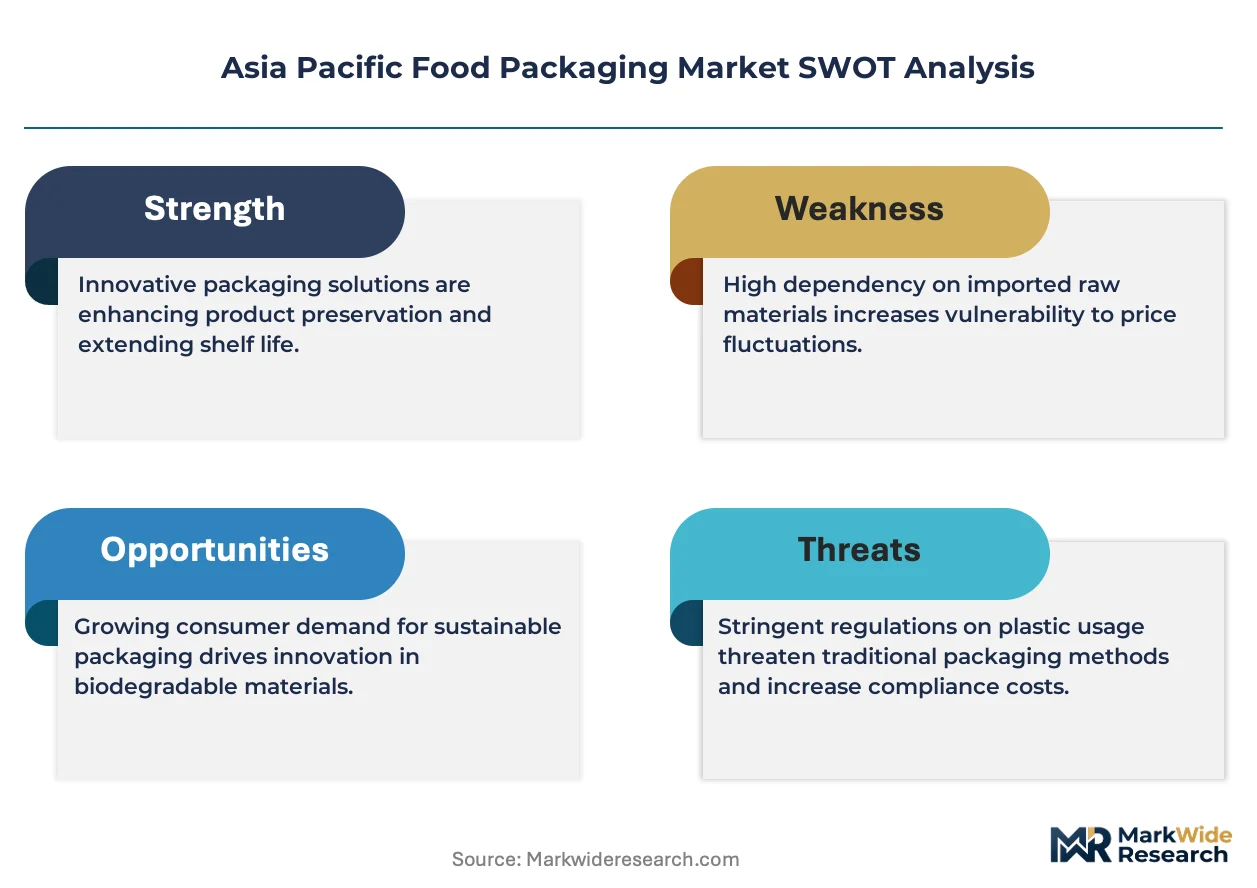
FSSAI in India enforces food-grade packaging standards and plastic migration thresholds that reshape material selection for domestic and export-oriented processors. EUDR and EU Green Deal requirements transmitted through European importer specifications are forcing Southeast Asian suppliers to demonstrate deforestation-free paper and bio-based content claims. China's SAMR and GB standards govern heavy-metal limits in glass and ceramic food contact articles, affecting cross-border trade flows. Stakeholders must monitor how diverging national sustainability mandates and importer country rules interact to determine viable material and format investments.
Market Dynamics
Asia Pacific food packaging is undergoing structural recalibration as EUDR-aligned sustainability mandates transmit through European buyer specifications, forcing Southeast Asian suppliers to reengineer material provenance and bio-based content claims across tropical fruit and frozen seafood export channels.
Growth Catalysts
- Urban ready-to-eat meal adoption:Quick-service chains across India, Indonesia, and Vietnam are scaling shelf-life extension contracts that favor high-barrier flexible films and aseptic formats for ambient distribution.
- FSSAI migration limit enforcement:India's tightened plastic food contact material thresholds are accelerating compliant multilayer coextrusion investments among domestic processors serving both local retail and export markets.
- Southeast Asian export-processing zone concentration:Frozen seafood and tropical fruit packers in Thailand, Vietnam, and the Philippines are expanding cold-chain-compatible barrier packaging capacity to meet EU and Japanese importer specifications.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with naphtha cracking economics, compressing margin stability for converters serving price-sensitive domestic dairy and beverage segments.
- Deforestation-free paper certification scarcity:EUDR-compliant pulp supply concentrates in Nordic and Latin American sources, creating input bottlenecks for Southeast Asian carton and molded fiber producers.
- Technical limitation in bio-based barrier performance:Polylactic acid and cellulose-derived films exhibit oxygen transmission rates 3-5x higher than conventional EVOH barriers, restricting adoption in high-sensitivity meat and dairy applications.
Strategic Opportunities
- Underpenetrated Indonesian archipelago cold chain:Island logistics gaps create white space for insulated pouch and phase-change material integration in fresh fish and prepared meal distribution.
- Australian and New Zealand premium export channel:Grass-fed beef and organic dairy producers are specifying carbon-footprint-labeled packaging to differentiate in European and North Asian premium retail.
- China's dual carbon policy alignment:SAMR guidelines on recycled content in food contact articles are creating compliant rPET flake demand that domestic mechanical recycling infrastructure is racing to satisfy.
Industry Challenges
- Migration testing laboratory capacity constraints:FSSAI and GB standards compliance requires specialized analytical chemistry expertise that concentrates in Mumbai, Shanghai, and Singapore, creating certification backlogs for mid-tier converters.
- Legacy thermoforming asset stranding risk:Philippine and Malaysian processors face capex-intensive retooling as quick-service brands phase out polystyrene clamshells in favor of molded fiber alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Food Packaging Market |
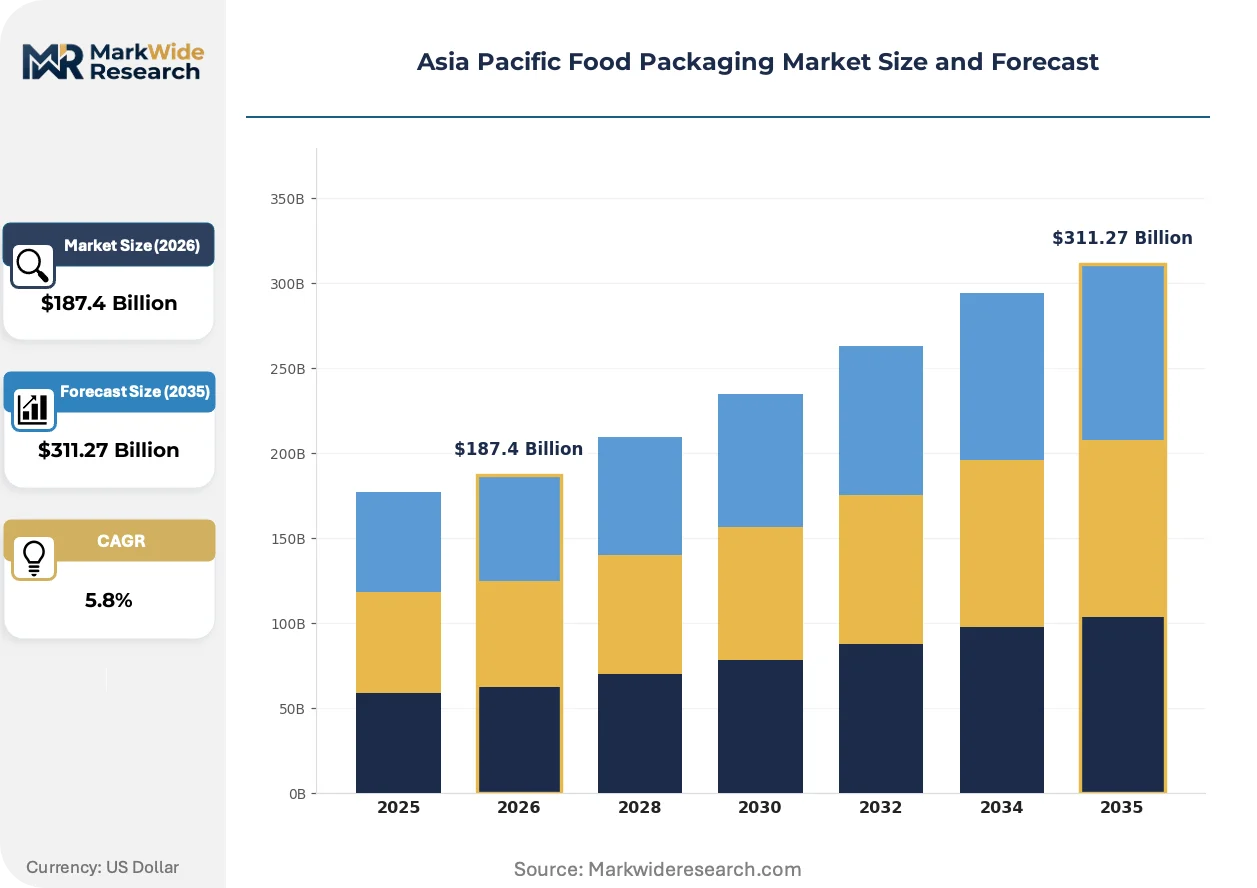
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Glass, Metal Application: Meat, Dairy, Bakery, Snacks End User: Foodservice, Retail, E-commerce, Catering Packaging Format: Flexible, Rigid, Bulk, Single-Serve |
| Companies Covered | Huhtamaki, Crown Holdings, Amcor, Sonoco Products Company, Uflex, Berry Global, Tetra Pak, Mitsubishi Chemical Corporation, Sealed Air Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Food Packaging Market Emerging Trajectories
Active and intelligent packaging systems are penetrating Asia Pacific food supply chains as tropical climate logistics and extended distribution distances create functional demand beyond passive barrier protection.
Monolayer-to-multilayer coextrusion advancement is unifying oxygen scavenging and moisture regulation within single film architectures. Regional snack and confectionery producers are adopting these formats at accelerating pace to replace separate sachet inserts. This unifying technology is compressing packaging line complexity and reducing foreign-object contamination risk in high-speed vertical form-fill-seal operations.
EU Green Deal requirements transmitted through importer specifications are mandating deforestation-free paper and bio-based content verification for Southeast Asian suppliers. Thai and Vietnamese pulp-dependent converters are restructuring supply contracts to incorporate chain-of-custody certification from plantation to finished carton. Ambient dairy and plant-based beverage segments face the steepest compliance ramps as European retail buyers harden procurement gates.
Direct-to-retail e-commerce channel expansion is fragmenting order patterns across Asia Pacific food packaging buyers. Fresh produce and prepared meal platforms in South Korea and Japan are specifying smaller lot sizes with variable print runs, displacing long-run rotogravure with digital flexographic and inkjet systems. This behavioral shift concentrates in urban fulfillment networks where same-day delivery promises compress packaging specification lead times from weeks to days.
Asia Pacific Food Packaging Market Segmentation
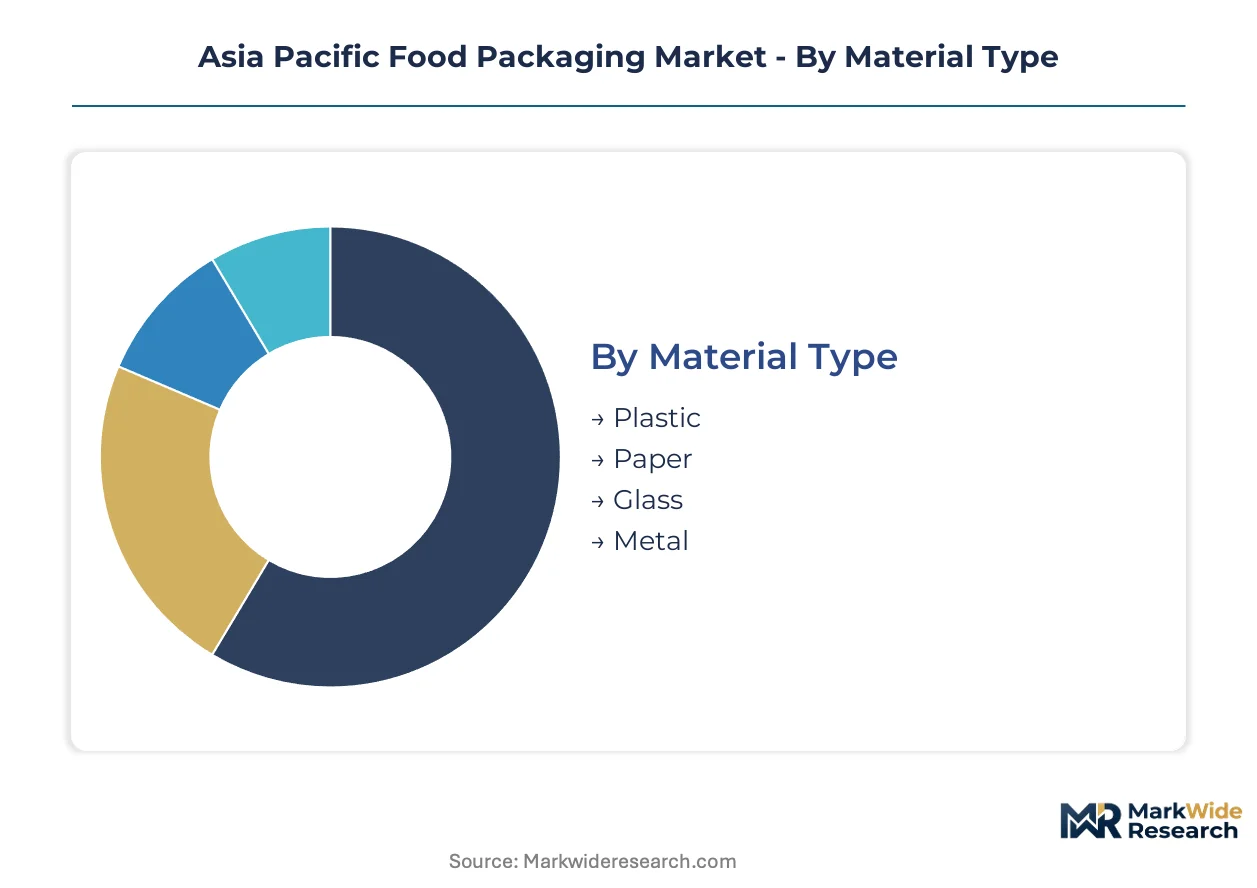
Asia Pacific food packaging purchasing decisions pivot on climate resilience, regulatory compliance depth, and format compatibility with fragmented last-mile distribution. Material selection and format architecture determine viable export channels and domestic shelf-life performance across tropical supply chains.
Material Type:
Procurement prioritizes barrier performance against humidity and oxygen ingress while navigating tightening migration limits and deforestation-free certification requirements.
- Plastic:Multilayer coextrusion films and polypropylene containers dominate ambient dairy, snack, and ready-to-eat meal segments. FSSAI migration thresholds and EUDR-aligned buyer specifications are accelerating compliant multilayer investments among Thai and Vietnamese converters.
- Paper:Molded fiber clamshells and kraft-based flexible formats are displacing polystyrene in quick-service channels. EUDR-compliant pulp supply concentrates in Nordic and Latin American sources, creating input bottlenecks for Southeast Asian carton producers.
- Glass:China's SAMR enforces heavy-metal limits in food contact glassware affecting cross-border trade flows.
- Metal:Tinplate and aluminum can formats sustain dominance in ambient beverage and processed seafood segments across Japan and South Korea.
Volume sits with plastic formats; growth tilts toward paper-based alternatives.
Application:
Temperature sensitivity and shelf-life extension requirements segment packaging specification intensity across protein and carbohydrate-based food categories.
- Meat:High-barrier vacuum and modified-atmosphere packaging dominates fresh and processed protein distribution. Australian and New Zealand grass-fed beef exporters specify carbon-footprint-labeled formats to differentiate in European premium retail channels.
- Dairy:Aseptic carton and multilayer bottle formats anchor ambient milk and plant-based beverage supply chains. Tetra Pak's regional capacity expansion targets South and Southeast Asia's growing dairy consumption.
- Bakery:Oxygen-scavenging films and resealable pouches address moisture retention in humid climates.
- Snacks:Lightweight flexible packaging with high printability commands premium positioning in India's fragmented retail landscape.
Revenue concentrates in dairy; steepest expansion trajectory emerges in meat as cold-chain infrastructure penetrates Indonesian and Philippine archipelago logistics.
End User:
Order pattern fragmentation and specification lead-time compression differentiate channel requirements across institutional and consumer-facing segments.
- Foodservice:Quick-service chains in India, Indonesia, and Vietnam are scaling shelf-life extension contracts favoring high-barrier flexible films. Huhtamaki's molded fiber portfolio captures polystyrene replacement mandates across regional QSR networks.
- Retail:Traditional trade and modern grocery formats sustain long-run rotogravure specifications for brand communication at scale.
- E-commerce:Fresh produce and prepared meal platforms in South Korea and Japan specify smaller lot sizes with variable print runs, displacing rotogravure with digital flexographic systems.
- Catering:Bulk-format insulated pouches address institutional volume requirements with phase-change material integration for temperature maintenance.
Transaction volume flows through retail; specification complexity expands fastest in e-commerce as same-day delivery promises compress lead times.
Packaging Format:
Logistics compatibility and consumption occasion alignment determine format selection across ambient and temperature-controlled distribution networks.
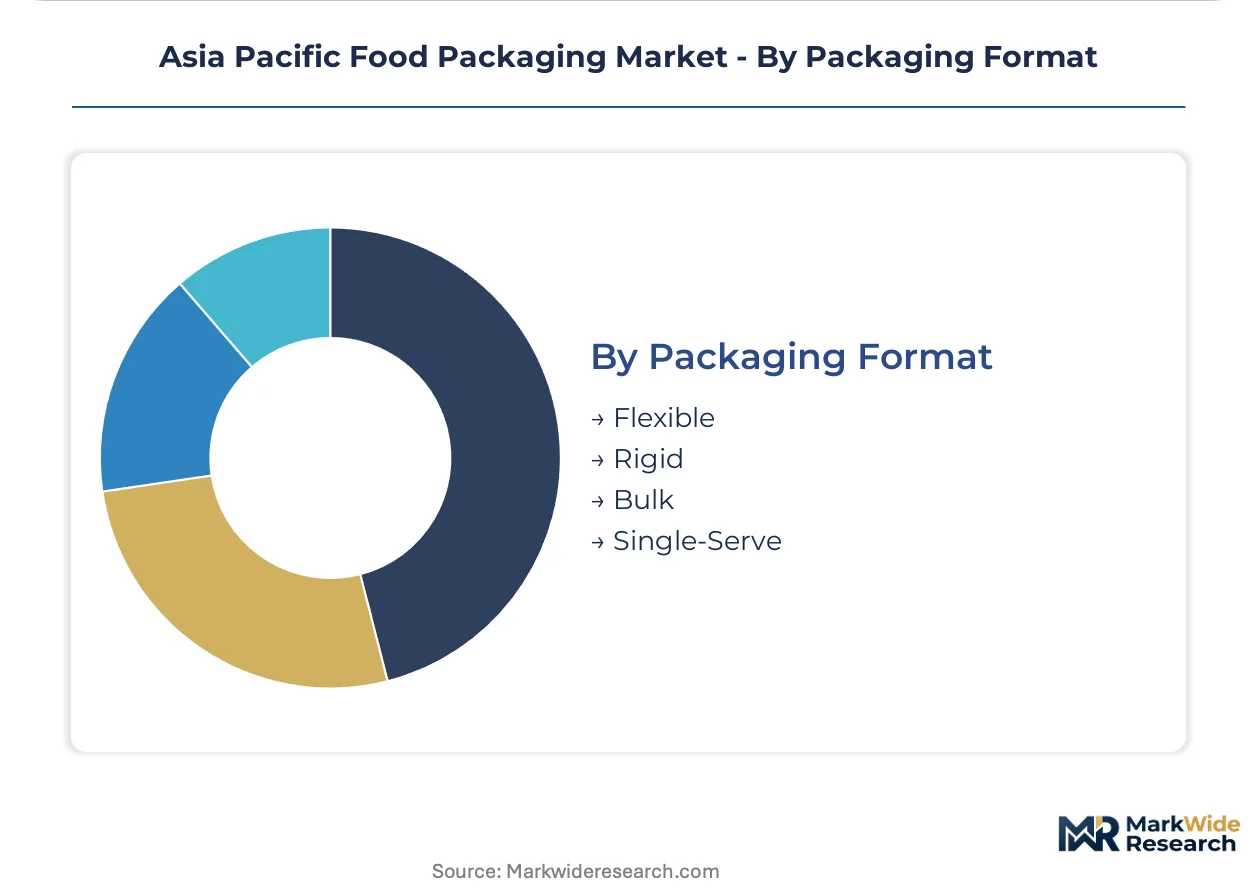
- Flexible:Roll-fed films and pre-made pouches dominate snack, confectionery, and ambient dairy segments where lightweighting reduces freight cost. Amcor's regional flexible film portfolio captures shelf-life extension contracts with quick-service chains.
- Rigid:Bottles, jars, and cartons sustain structural integrity requirements in beverage and dairy where resealability determines repurchase behavior.
- Bulk:Intermediate bulk containers and industrial totes serve foodservice and catering procurement at scale.
- Single-Serve:Portion-control formats address urban convenience demand and food waste reduction in premium retail channels.
Shipment weight concentrates in flexible formats; premium positioning shifts toward single-serve as convenience consumption expands in metropolitan Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Southeast Asian export-processing zones while consumption gravity shifts toward Indian and Indonesian urban centers. Thailand and Vietnam anchor frozen seafood and tropical fruit packaging supply chains. Chinese converters serve domestic dairy demand while facing EUDR-aligned sustainability pressures from European buyers.
China
Domestic dairy consumption drives aseptic carton and multilayer bottle demand across Yangtze River Delta manufacturing clusters. SAMR enforces GB standards on heavy-metal limits in glass food contact articles. Shanghai and Jiangsu province converters are retooling lines to meet recycled content mandates under dual carbon policy alignment.
India
Urban quick-service chain expansion recalibrates flexible film specifications for ambient ready-to-eat meal distribution. FSSAI tightened plastic migration thresholds for food contact materials in 2024. Maharashtra and Gujarat processing corridors are accelerating compliant multilayer coextrusion investments for domestic retail and Middle East export channels.
Thailand
Frozen seafood export volumes sustain cold-chain barrier packaging capacity expansion in Eastern Seaboard industrial zones. EUDR deforestation-free certification requirements transmit through European buyer procurement gates. Chonburi and Rayong province packers are restructuring pulp supply contracts to incorporate chain-of-custody verification.
Vietnam
Tropical fruit export growth to EU and Japanese markets drives high-barrier modified-atmosphere packaging adoption. EUDR compliance deadlines compress timeline for bio-based content verification systems. Ho Chi Minh City and Mekong Delta processing clusters are integrating digital traceability platforms to satisfy importer specification gates.
Indonesia
Archipelago logistics gaps create demand for insulated pouch and phase-change material integration in fresh fish distribution. National single-use plastic reduction mandates reshape quick-service packaging procurement. Java-based converters are scaling molded fiber capacity to capture QSR brand phase-out contracts across Jakarta and Surabaya metropolitan networks.
Asia Pacific Food Packaging Market Vendor Landscape
Top-tier vendors anchor diversified material portfolios, while mid-scale specialists concentrate on single-format excellence. The vendor base stratifies across integrated multinationals, regional converters with strong distributor relationships, and emerging bio-based material innovators. Strategic archetypes include sustainability-certification leaders, cold-chain logistics specialists, and digital print-on-demand enablers. Competitive moves concentrate on EUDR-compliant supply chain restructuring and aseptic format capacity expansion.
Among Asia-Pacific headquartered converters, Uflex and Huhtamaki occupy positions spanning flexible film and molded fiber archetypes respectively. Tetra Pak anchors aseptic carton supply infrastructure across South and Southeast Asian dairy corridors. These three exemplify how geographic proximity to tropical fruit and seafood export zones shapes strategic positioning.
| Leading Market Players |
|---|
| Huhtamaki |
| Crown Holdings |
| Amcor |
| Sonoco Products Company |
| Uflex |
| Berry Global |
| Tetra Pak |
| Mitsubishi Chemical Corporation |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EUDR-compliant and conventional packaging tiers manifests in both procurement premiums and sourcing network complexity across Asia Pacific food packaging. Premium-grade multilayer films and deforestation-free cartons command sustained price advantages while commodity-grade alternatives face margin compression from petrochemical volatility and import specification tightening.
Pricing Analysis
Short-lead-time premiums for digital-print flexible films and rapid-turnaround molded fiber formats separate spot-market buyers from contract-based procurement across quick-service and e-commerce channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with EUDR-aligned and FSSAI-compliant grades anchoring the premium band. Cost compression in commodity flexible film is intensifying because polypropylene resin fluctuates with naphtha cracking spreads. Foodservice chains exhibit highest price sensitivity due to volume scale and brand procurement centralization, while premium export processors show least sensitivity given pass-through to European retail buyers.
Supply Chain Analysis
Domestic-content mandates under India's FSSAI and China's SAMR recycled-content guidelines are reshaping sourcing toward local multilayer coextrusion and mechanical recycling infrastructure. Geographic supply concentration centers on Thailand, Vietnam, and China for flexible film conversion, with Nordic and Latin American pulp feeds drawing from EUDR-compliant plantation sources. Raw material dependencies rest on polypropylene resin, ethylene vinyl alcohol barrier polymers, and certified pulp grades. Single-source vulnerability concentrates in EVOH supply from limited regional polymerization capacity. Distribution runs through export-processing zones in Eastern Seaboard Thailand and Mekong Delta Vietnam, feeding EU and Japanese importer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific food packaging sits in active technology transition as monolayer-to-multilayer coextrusion unification displaces legacy passive barrier systems and separate sachet architectures.
For Market Incumbents: Anchor defensible positioning through backward integration into EUDR-compliant pulp supply chains and captive multilayer film polymerization capacity. FSSAI migration limit enforcement and quick-service brand phase-out of polystyrene clamshells threaten legacy thermoforming asset values; certification investment in chain-of-custody verification systems offers margin protection.
For New Entrants and Emerging Players: Direct-to-retail e-commerce channels offer white-space entry with digital flexographic and inkjet print-on-demand systems displacing long-run rotogravure. Indonesian archipelago cold-chain gaps present insulated pouch and phase-change material integration opportunities for fresh fish distribution. Target Australian and New Zealand premium export channels with carbon-footprint-labeled formats as the most penetrable segment.
For Investors and Strategic Acquirers: Re-rating potential sits with bio-based barrier material innovators given EUDR compliance deadline compression and technical performance gap closure. Long-term viability favors specialists bridging polylactic acid oxygen transmission limitations against conventional EVOH benchmarks. Watch bio-based film adoption rates in high-sensitivity meat and dairy applications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR-Compliant Supply Chain Restructuring | Thai and Vietnamese converters secure Nordic pulp chain-of-custody verification to maintain EU market access. |
| Multilayer Coextrusion Capacity Expansion | Indian processors in Maharashtra and Gujarat corridors accelerate FSSAI-compliant film investments for domestic and Middle East export channels. |
| Digital Print System Deployment | South Korean and Japanese e-commerce platforms adopt variable-run flexographic systems to compress specification lead times. |
| Molded Fiber Scale-Up | Java-based converters capture QSR brand phase-out contracts across Jakarta and Surabaya metropolitan networks. |
| Active Packaging Integration | Regional snack producers unify oxygen scavenging within single film architectures to reduce foreign-object contamination risk. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across packaging converters, quick-service chain procurement directors, and food safety compliance officers. FSSAI enforcement circulars, SAMR GB standard updates, and EUDR implementation guidance formed regulatory intelligence layers. Bottom-up volume modeling across material type, application, and format segments triangulated against top-down trade flow analysis.
Granularity-level modeling addressed material migration thresholds, cold-chain compatibility specifications, and digital print adoption rates across the projection horizon. Segmentation dimensions included barrier performance tier, end-use temperature sensitivity, and channel order-pattern fragmentation. CAGRs derived from trend extrapolation of urban ready-to-eat meal adoption, export-processing zone capacity expansion, and sustainability mandate transmission through buyer specifications. Industry-specific inputs incorporated EVOH barrier polymer supply constraints and EUDR-compliant pulp availability bottlenecks.
The model holds under sustained EUDR enforcement and FSSAI migration limit tightening; deviation in petrochemical feedstock volatility or bio-based barrier technical breakthroughs would shift material substitution trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Frozen Food Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
Fresh Produce Trays Market