
 Peripheral Interventions Market | 2026-2036
Peripheral Interventions Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Interventions Market Analysis
Nitinol is shifting peripheral stent design away from stainless-steel platforms, improving fatigue resistance and conformability in tortuous iliac and femoral anatomies. Boston Scientific leverages in-house nitinol processing capabilities to sustain cost advantages across its peripheral portfolio. Abbott Laboratories anchors its competitive position through drug-coated balloon technology leadership. Medtronic dominates integrated catheter-to-stent workflows that streamline complex lesion management.
Peripheral interventions encompass endovascular procedures and devices used to treat obstructive or aneurysmal disease in vessels outside the coronary and cerebral circulations, typically employing balloon-expandable or self-expanding metallic scaffolds delivered via 4-7 French sheaths. These therapies restore luminal patency, prevent limb ischemia, and reduce open surgical morbidity in patients with peripheral artery disease. Stents and balloons capture the dominant share of product-type revenue, with drug-coated balloons representing the fastest-expanding margin pool as antiproliferative coatings extend primary patency intervals. Catheters and guidewires function as enabling infrastructure, where specialized hydrophilic coatings and torque response differentiate premium access platforms from commodity alternatives.
The FDA's breakthrough device designation and 510(k) pathway shape U.S. market access timelines, while the EU MDR imposes stricter clinical evidence requirements for class III peripheral implants. Japan's PMDA maintains distinct reimbursement thresholds that filter which device innovations achieve commercial viability. Stakeholders must monitor evolving health technology assessment methodologies across these jurisdictions to anticipate which procedural categories will sustain favorable coverage decisions.
Market Dynamics
Nitinol processing concentration among a handful of specialized metallurgical suppliers is compressing peripheral stent margins and forcing device manufacturers to secure captive supply agreements or backward integration into wire drawing and laser cutting operations.
Growth Catalysts
- Drug-coated balloon coatings:Paclitaxel and sirolimus formulations extend primary patency intervals in femoropopliteal lesions, pulling procedure volume away from bare-metal stenting in United States hospital systems.
- FDA breakthrough device designation:Accelerated premarket review timelines compress regulatory lag for novel scaffold designs, enabling faster commercialization of bioresorbable peripheral platforms.
- Chronic limb-threatening ischemia protocols:Multidisciplinary wound care teams in vascular centers drive limb salvage procedure volumes through coordinated endovascular-first treatment algorithms.
Market Restraints
- Nitinol raw material volatility:Nickel-titanium alloy pricing fluctuates with aerospace and orthodontic demand cycles, squeezing gross margins on self-expanding stent platforms.
- EU MDR clinical evidence requirements:Stricter post-market surveillance and PMCF study obligations for class III peripheral implants extend certification timelines and inflate regulatory spend.
- Surgical bypass durability:Autologous vein grafts in below-knee revascularization maintain superior long-term patency, limiting endovascular penetration in critical limb ischemia cases.
Strategic Opportunities
- India vascular device penetration:Underdeveloped peripheral intervention infrastructure in tier-2 and tier-3 cities creates whitespace for catheter and balloon distribution partnerships.
- AI-enabled lesion assessment:Machine learning algorithms for intravascular ultrasound analysis converge with robotic catheter navigation to standardize complex lesion preparation.
- Japan PMDA reimbursement expansion:Revised fee schedules for drug-coated balloon procedures in specific lesion categories incentivize hospital adoption of premium technologies.
Industry Challenges
- Interventional cardiologist-to-vascular specialist transition:Cross-training requirements for tortuous anatomy navigation create workforce bottlenecks as coronary-trained operators migrate to peripheral cases.
- Bioresorbable scaffold integration:Polymer degradation profiles and mechanical performance tradeoffs complicate product development timelines and predicate device selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Interventions Market |
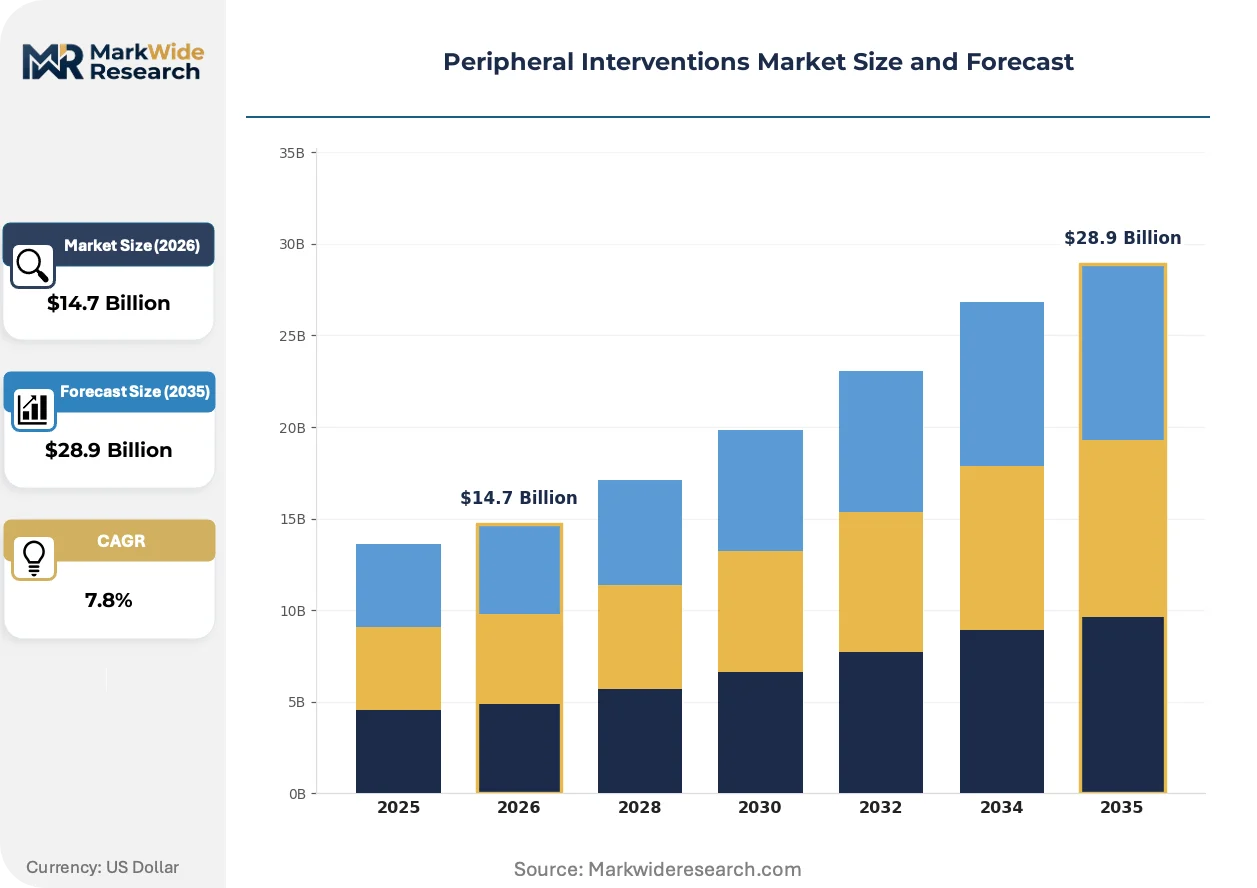
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $28.9 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Guidewires Delivery Mode: Endovenous, Transluminal, Percutaneous, Laparoscopic End User: Hospitals, Ambulatory Surgical Centers, Dialysis Centers, Clinics Procedure Type: Angioplasty, Thrombectomy, Aneurysm Repair, Embolization |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, B. Braun Melsungen AG, Terumo Corporation, Cook Medical, Cardinal Health, W. L. Gore & Associates, Biotronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Interventions Market Emerging Trajectories
Computational modeling and advanced manufacturing are compressing product development cycles while regulatory science evolves to evaluate novel material platforms. Device architecture now prioritizes deliverability and conformability over radial strength alone.
Robotic catheter systems are automating guidewire manipulation and lesion crossing in complex peripheral anatomies. Interventional suites in high-volume United States hospitals deploy these platforms to standardize procedural outcomes and reduce fluoroscopy exposure. The technology is automating repetitive manual tasks that previously consumed senior operator attention, enabling case volume expansion without proportional staffing growth.
EU MDR Article 120 transitional provisions are forcing legacy device manufacturers to accelerate clinical data generation for class III peripheral implants. Notified body capacity constraints create submission backlogs that favor well-capitalized firms with established quality management systems. Drug-coated balloon categories face heightened scrutiny of coating integrity and particulate release profiles, driving reformulation investments across European portfolios.
Hospital value analysis committees now mandate head-to-head economic evidence before approving premium stent and balloon contracts. Procurement teams bundle catheter, guidewire, and scaffold purchases through single-source agreements that displace fragmented supplier relationships. This concentration is most visible in United States integrated delivery networks, where standardized device formularies compress vendor counts and shift negotiating leverage toward high-volume purchasers.
Peripheral Interventions Market Segmentation
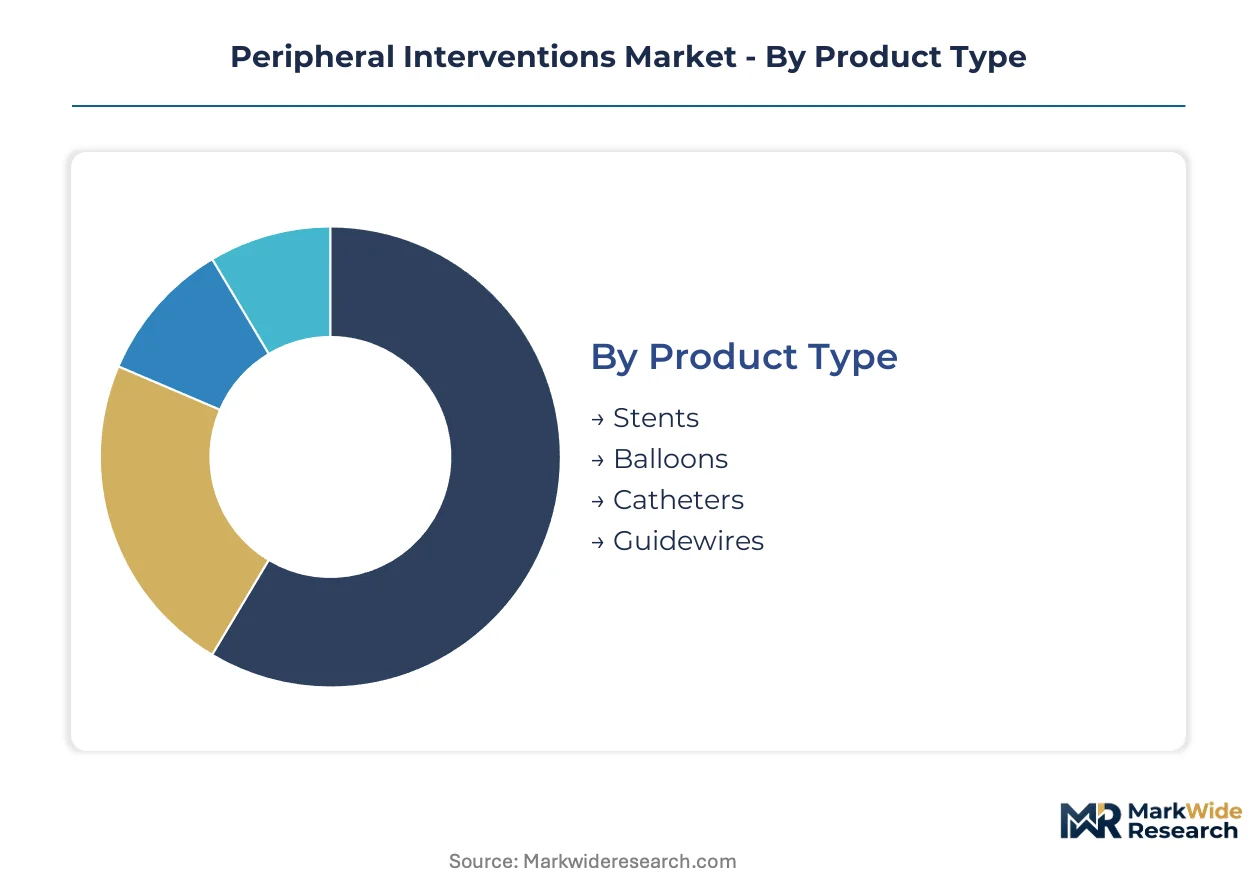
Device segmentation in peripheral interventions reveals divergent margin structures across product categories. Procedure complexity and reimbursement intensity determine which segments command premium pricing versus commodity positioning.
Product Type:
Volume concentrates in metallic scaffolds and balloons, while catheter and guidewire infrastructure captures recurring replacement cycles.
- Stents:Self-expanding nitinol platforms dominate femoropopliteal and iliac applications, with drug-eluting coatings extending patency intervals. United States hospital systems drive demand for next-generation bioresorbable scaffolds as FDA breakthrough designations accelerate clearance timelines.
- Balloons:Drug-coated balloons represent the premium tier, deploying paclitaxel or sirolimus formulations to suppress neointimal hyperplasia. United States vascular centers favor these devices for lesions where stent fracture risk complicates metallic implant selection.
- Catheters:Hydrophilic-coated access platforms enable lesion crossing in tortuous anatomy.
- Guidewires:Torque-responsive designs with specialized tip configurations support subintimal tracking.
Today's leader: Stents. Tomorrow's challenger: Balloons.
Delivery Mode:
Access route selection shapes device sizing, sheath requirements, and radiation exposure profiles across procedure types.
- Endovenous:Minimally invasive venous access for superficial vein interventions and deep venous thrombosis management.
- Transluminal:Intraluminal recanalization through true or subintimal channels dominates arterial revascularization.
- Percutaneous:Standard femoral or radial access for most peripheral arterial procedures, with 4-7 French sheaths accommodating self-expanding stent delivery.
- Laparoscopic:Hybrid surgical-endovascular approaches for complex aortic and visceral artery disease.
Transluminal access anchors current volumes. Percutaneous techniques are gaining share fastest through radial adoption.
End User:
Site-of-care economics and case complexity stratify purchasing power across institutional settings.
- Hospitals:Integrated vascular centers with hybrid operating rooms capture complex multilevel disease and limb salvage protocols. United States academic medical centers drive adoption of robotic catheter systems and intravascular imaging platforms.
- Ambulatory Surgical Centers:Lower-acuity femoropopliteal interventions migrate to outpatient settings as reimbursement codes evolve. United States ASC networks negotiate bundled device contracts that favor single-vendor sourcing.
- Dialysis Centers:Arteriovenous access maintenance creates recurring intervention demand for thrombectomy and angioplasty.
- Clinics:Office-based vein procedures concentrate in dermatology and vascular surgery private practices.
Hospitals retain the highest acuity mix. Ambulatory Surgical Centers are expanding the fastest as site-of-care shifts accelerate.
Procedure Type:
Reimbursement intensity and device utilization rates vary sharply across therapeutic categories.
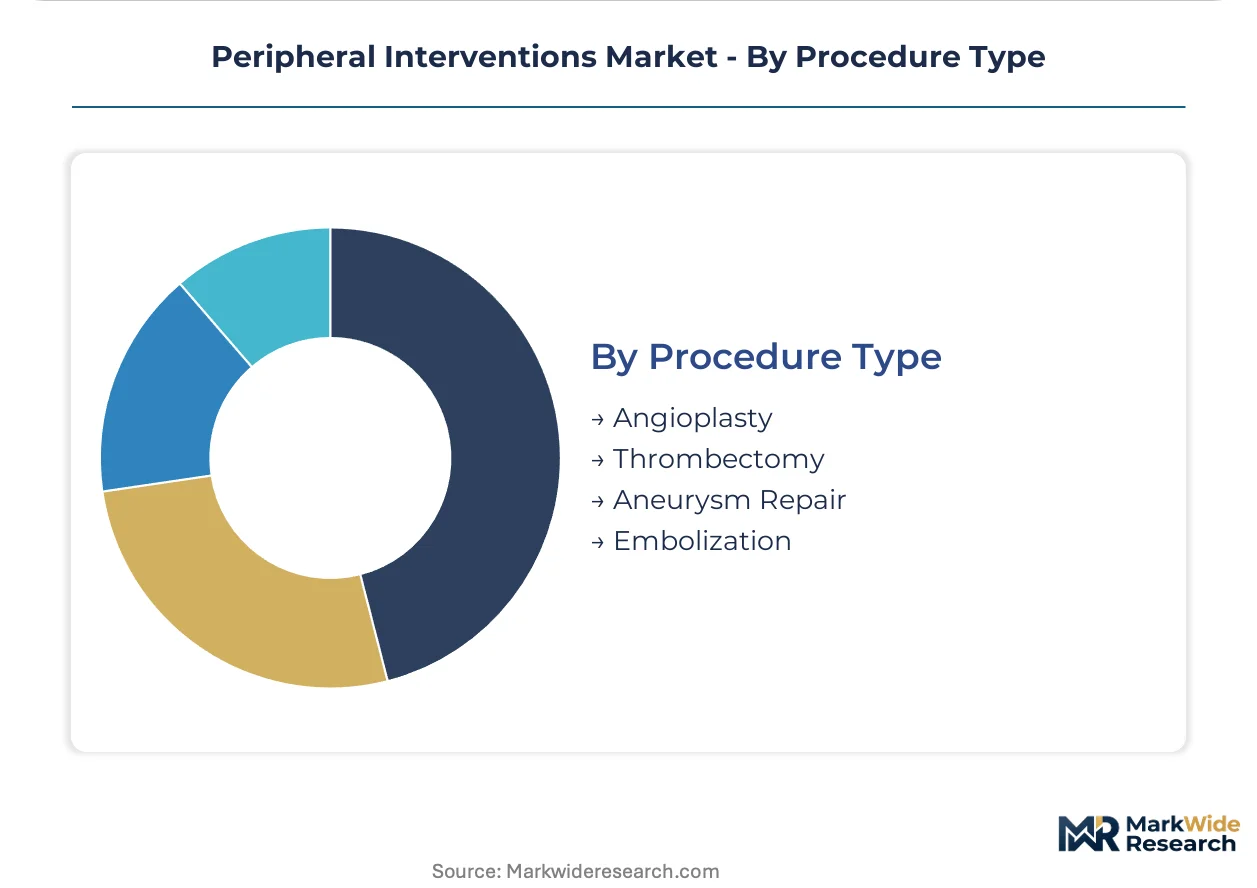
- Angioplasty:Balloon dilation with provisional stenting remains the foundational peripheral intervention. United States Medicare reimbursement rates for femoropopliteal angioplasty sustain hospital investment in dedicated peripheral labs.
- Thrombectomy:Mechanical and aspiration systems for acute limb ischemia command premium device pricing. United States trauma centers and vascular emergency protocols drive demand for rapid revascularization technologies.
- Aneurysm Repair:Endovascular sealing and stent-graft exclusion of peripheral and visceral aneurysms.
- Embolization:Coil and particle-based occlusion for hemorrhage control and tumor devascularization.
Angioplasty generates the highest procedure counts. Thrombectomy is climbing the fastest as acute limb ischemia protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-St. Paul medical device cluster anchors global peripheral intervention innovation, with Medtronic and Boston Scientific driving nitinol processing and catheter platform development from their Minnesota headquarters.
United States
Aging demographics and high diabetes prevalence sustain procedure volumes across vascular centers. FDA breakthrough device designations accelerate clearance timelines for drug-coated balloon platforms. The Cleveland Clinic and Mayo Clinic hybrid operating rooms pioneer robotic catheter integration for complex femoropopliteal cases.
Germany
EU MDR Article 120 transitional provisions force accelerated clinical data generation for class III peripheral implants. B. Braun Melsungen AG leverages its Tuttlingen surgical instruments cluster to streamline regulatory submissions. The Heidelberg and Berlin vascular centers drive adoption of intravascular imaging for lesion assessment.
Japan
Revised PMDA fee schedules for drug-coated balloon procedures incentivize hospital technology upgrades. Terumo Corporation's Tokyo headquarters anchors regional distribution networks across East Asian markets. The Osaka-Kobe medical device corridor concentrates stent manufacturing and coating technology development.
India
Tier-2 and tier-3 city hospital networks create whitespace for catheter and balloon distribution partnerships. CDSCO regulatory harmonization with IMDRF standards accelerates import clearance for multinational device portfolios. The Chennai and Hyderabad medical device clusters expand local manufacturing for cost-sensitive stent platforms.
Switzerland
Swissmedic maintains rigorous post-market surveillance requirements that filter premium device commercialization. Biotronik anchors European cardiac rhythm and vascular intervention R&D from its Bülach headquarters. The Zurich-West life sciences corridor concentrates specialized metallurgical suppliers for nitinol wire drawing operations.
Peripheral Interventions Market Vendor Landscape
Global majors compete with regional champions across regulatory science capabilities and nitinol supply chain control. The market structures around three tiers: integrated conglomerates with captive metallurgical processing, mid-scale specialists with focused peripheral portfolios, and regional distributors with localized regulatory expertise. Dominant competitive moves include backward integration into nitinol wire drawing and laser cutting operations, plus strategic partnerships with hybrid operating room equipment vendors.
Within the integrated conglomerate tier, Medtronic and Boston Scientific exemplify players with in-house nitinol processing capabilities that compress manufacturing costs. Abbott Laboratories occupies a position representing drug-coated balloon technology leadership. These three anchors illustrate how scale-driven players secure supply chain advantages while specialists concentrate on coating formulations and catheter deliverability.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Cook Medical |
| Cardinal Health |
| W. L. Gore & Associates |
| Biotronik |
| Others |
Supply Flow & Price Mechanics
Performance divergence between drug-eluting platforms and bare-metal alternatives splits the peripheral interventions market into premium and commodity tiers, with coating technology and FDA breakthrough status determining both price positioning and supplier consolidation strategies. Nitinol raw material volatility and EU MDR compliance costs propagate unevenly across these tiers, compressing margins on standard stents while insulating premium balloon categories.
Pricing Analysis
Input-cost pass-through from nickel-titanium alloy suppliers shapes contract-based long-term offtake agreements for self-expanding stent manufacturers. Pricing stratifies across premium, standard, and economy tiers based on drug-coating formulation sophistication and FDA breakthrough designation status. Cost compression in bare-metal stent categories is intensifying because hospital value analysis committees mandate head-to-head economic evidence before approving premium contracts. Ambulatory surgical centers exhibit the highest price sensitivity, while academic medical centers with hybrid operating rooms demonstrate lowest sensitivity due to bundled reimbursement structures.
Supply Chain Analysis
Nitinol wire supply rests on specialized metallurgical processors concentrated in the United States, Germany, and Switzerland, with aerospace and orthodontic demand cycles creating pricing volatility. Device manufacturers source nickel-titanium alloys, hydrophilic polymer coatings, and paclitaxel drug formulations through multi-year supply agreements. Single-source vulnerability pervades laser cutting and surface treatment operations for nitinol stent platforms. Distribution runs through hospital purchasing committees and group purchasing organizations that consolidate vendor relationships into single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peripheral interventions function as a geographic-arbitrage play where EU MDR compliance costs in Europe exceed CDSCO harmonization benefits in India, creating divergent capital deployment returns across regulatory jurisdictions.
For Market Incumbents: To counter nitinol supply concentration squeezing gross margins, Medtronic-scale players should execute backward integration into wire drawing operations and secure captive laser cutting capacity in Minnesota or Tuttlingen clusters. FDA breakthrough designation pursuit for bioresorbable scaffolds represents the priority R&D lever for pricing power defense. For New Entrants and Emerging Players: CDSCO regulatory harmonization with IMDRF standards in India opens a window for catheter and balloon distribution partnerships in tier-2 and tier-3 city hospital networks. Japan's revised PMDA fee schedules for drug-coated balloon procedures create the most penetrable reimbursement environment. A GPO contracts manager-focused go-to-market angle accelerates hospital system access. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR Article 120 transitional provisions force legacy device manufacturers to accelerate clinical data generation beyond their capital reserves. Five-to-ten year viability favors targets with established quality management systems and notified body relationships. Mid-scale specialists with focused peripheral portfolios and coating formulation expertise represent the acquisition archetype. PMDA reimbursement expansion signals warrant ongoing watch as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses commercialization timelines for nitinol scaffold platforms. |
| CE Marking Pathway Execution | EU MDR Article 120 compliance separates well-capitalized firms from capacity-constrained competitors. |
| Hospital System Partnership | Integrated delivery network contracts displace fragmented supplier relationships in United States markets. |
| Software Companion Development | AI-enabled lesion assessment algorithms differentiate premium catheter platforms from commodity alternatives. |
| Reimbursement Strategy Investment | PMDA fee schedule navigation determines commercial viability in Japanese vascular centers. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and Switzerland, with primary inputs from each market's vascular centers and regulatory authorities. The analysis combines structured interviews with interventional cardiologists, vascular surgeons, hospital purchasing committee members, and GPO contracts managers with secondary validation from FDA 510(k) and PMA filings, PMDA reimbursement bulletins, EU MDR notified body guidance documents, and CMS Medicare procedure data. Bottom-up procedure volume estimates triangulate against top-down device manufacturer revenue assessments.
Granularity-level modeling disaggregates the peripheral interventions market across product type, delivery mode, end user, procedure type, and geographic regulatory cluster throughout the forecast period. CAGRs derive from procedure volume trajectories, device utilization rates per procedure, and pricing evolution assumptions. Forecast inputs incorporate aging demographic projections, diabetes prevalence trends, and minimally invasive procedure adoption curves specific to limb salvage protocols.
Revisions become necessary when FDA breakthrough designation criteria shift, EU MDR notified body capacity constraints intensify, or nickel-titanium alloy pricing volatility exceeds historical bands. Forecasts reflect documented assumptions about reimbursement stability, regulatory pathway duration, and supply chain concentration. A small set of named triggers—PMDA fee schedule adjustments, CDSCO import clearance acceleration, and hospital value analysis committee mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Diabetes Devices Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Photopheresis Products Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Cranial Perforator Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Medical Manifolds Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Hypodermic Syringes Market