
 Autorefractor Keratometer Market | 2026-2036
Autorefractor Keratometer Market Size, Share, and Industry Trends Forecast 2026-2036
Autorefractor Keratometer Market Insights
Optical-grade polymers are consolidating into autorefractor keratometer housings as metal casings retreat on cost and weight grounds. EssilorLuxottica leverages its retail-lab network to anchor instrument placement in integrated eye-care chains. Topcon Corporation dominates wavefront module supply through in-house production of Shack-Hartmann sensor arrays. NIDEK CO., LTD. specializes in compact benchtop designs for high-throughput ophthalmology clinics across East Asia.
An autorefractor keratometer combines automated refraction measurement with corneal curvature assessment to quantify refractive errors and fit contact lenses, typically employing infrared light sources and Placido disk topography to achieve diopter precision within 0.12D. Desktop units retain the largest installed base among product types due to durability in hospital settings, while handheld variants are displacing traditional screening tools in mobile vision programs. Wavefront technology leads the technology dimension on diagnostic granularity, though digital imaging sustains share in budget-sensitive optical stores where postoperative assessments require only basic keratometry.
FDA 510(k) clearance shapes market access for autorefractor keratometers in the United States, while CE marking under the EU MDR governs commercialization across European ophthalmology clinics. Japan's PMDA enforces JIS-standard electromagnetic compatibility for devices deployed in METI-certified medical manufacturing zones. Stakeholders must monitor how evolving MDR clinical evidence requirements for Class IIa diagnostics reshape registration timelines and competitive entry.
Market Dynamics
Wavefront-enabled diagnostic platforms are compressing replacement cycles for legacy autorefractor keratometers as ophthalmology clinics demand higher-order aberration mapping for premium intraocular lens fitting.
Growth Catalysts
- EU MDR clinical evidence requirements:Class IIa diagnostic re-certification is forcing optical equipment distributors to upgrade inventory, accelerating hospital procurement of compliant wavefront systems.
- Mobile vision screening programs:Government-backed rural eye-care initiatives in India are deploying handheld autorefractor keratometers to reach populations outside tertiary hospital networks.
- Shack-Hartmann sensor miniaturization:Reduced component costs are enabling benchtop manufacturers to embed wavefront modules in mid-tier pricing bands previously served by basic digital imaging.
Market Restraints
- Optical-grade polymer supply concentration:Housing material sourcing clusters in East Asian injection molding zones create vulnerability to logistics disruptions.
- FDA 510(k) timeline extension:Enhanced scrutiny of software-as-medical-device functionality is stretching clearance durations for instruments with integrated AI-driven refraction algorithms.
- Smartphone-based refraction apps:Low-cost alternatives for preliminary screening are capturing price-sensitive segments in emerging optical retail markets.
Strategic Opportunities
- Tele-ophthalmology integration:Remote diagnostic platforms are creating demand for cloud-connected autorefractor keratometers with encrypted patient data transmission.
- Japan's METI-certified medical manufacturing zones:JIS-standard electromagnetic compatibility certification opens procurement pathways into precision instrument supply chains.
- Contact lens e-commerce channels:Direct-to-consumer fitting workflows are driving optical retailers to install in-store keratometry for immediate curvature verification.
Industry Challenges
- ISO 10993 biocompatibility testing:Patient-contact components in handheld variants require extended validation timelines for skin-safe material certification.
- Legacy EMR integration:Hospital information system interoperability demands are forcing manufacturers to maintain multiple data export protocols, increasing software maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autorefractor Keratometer Market |
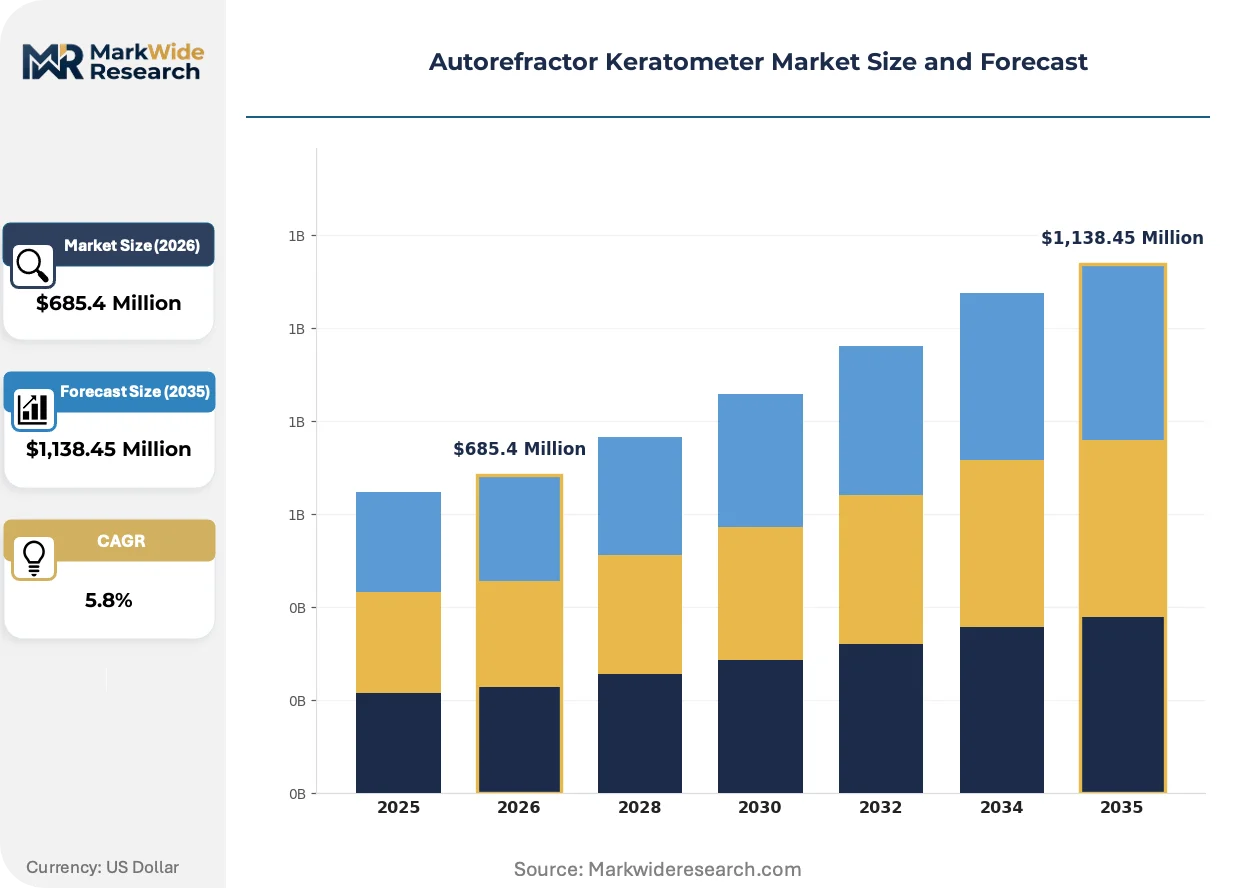
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Desktop, Automated, Hybrid Technology: Wavefront, Optical Coherence Tomography, Digital Imaging, Traditional End User: Ophthalmology Clinics, Hospitals, Research Laboratories, Optical Stores Application: Vision Screening, Postoperative Assessments, Refractive Error Measurement, Eye Health Monitoring |
| Companies Covered | CANON MEDICAL SYSTEMS CORPORATION, EssilorLuxottica, Topcon Corporation, Huvitz Co. Ltd., Visionix, NIDEK CO., LTD., Bausch + Lomb, Tomey Corporation, Carl Zeiss Meditech AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autorefractor Keratometer Market Trends and Innovations
Diagnostic granularity is becoming the primary axis of product differentiation as buyers prioritize aberration mapping depth over throughput speed in premium segment procurement.
Placido disk topography is overtaking basic keratometry in contact lens fitting workflows. Specialty lens practices are adopting combined Placido-Scheimpflug systems for simultaneous anterior segment analysis. This convergence is overtaking standalone autorefractor configurations in academic medical center purchasing decisions.
CE marking under EU MDR is tightening clinical evidence requirements for Class IIa ophthalmic diagnostics. Manufacturers must now submit prospective validation studies for software algorithms. Wavefront module suppliers with pre-existing MDR technical documentation are capturing share from competitors facing retrospective compliance gaps.
Optical retail chains are unbundling after-sales service from equipment purchase contracts. Independent service organizations are capturing maintenance revenue previously retained by original manufacturers. This fragmentation is most visible in Germany's KBA-adjacent precision manufacturing clusters where third-party calibration providers hold METAS-traceable certification.
Autorefractor Keratometer Market Segmentation
Segmentation in autorefractor keratometers reveals how regulatory pathways and clinical workflows shape procurement decisions across distinct buyer profiles. Each dimension carries specific certification burdens that determine market access velocity and pricing power.
Product Type:
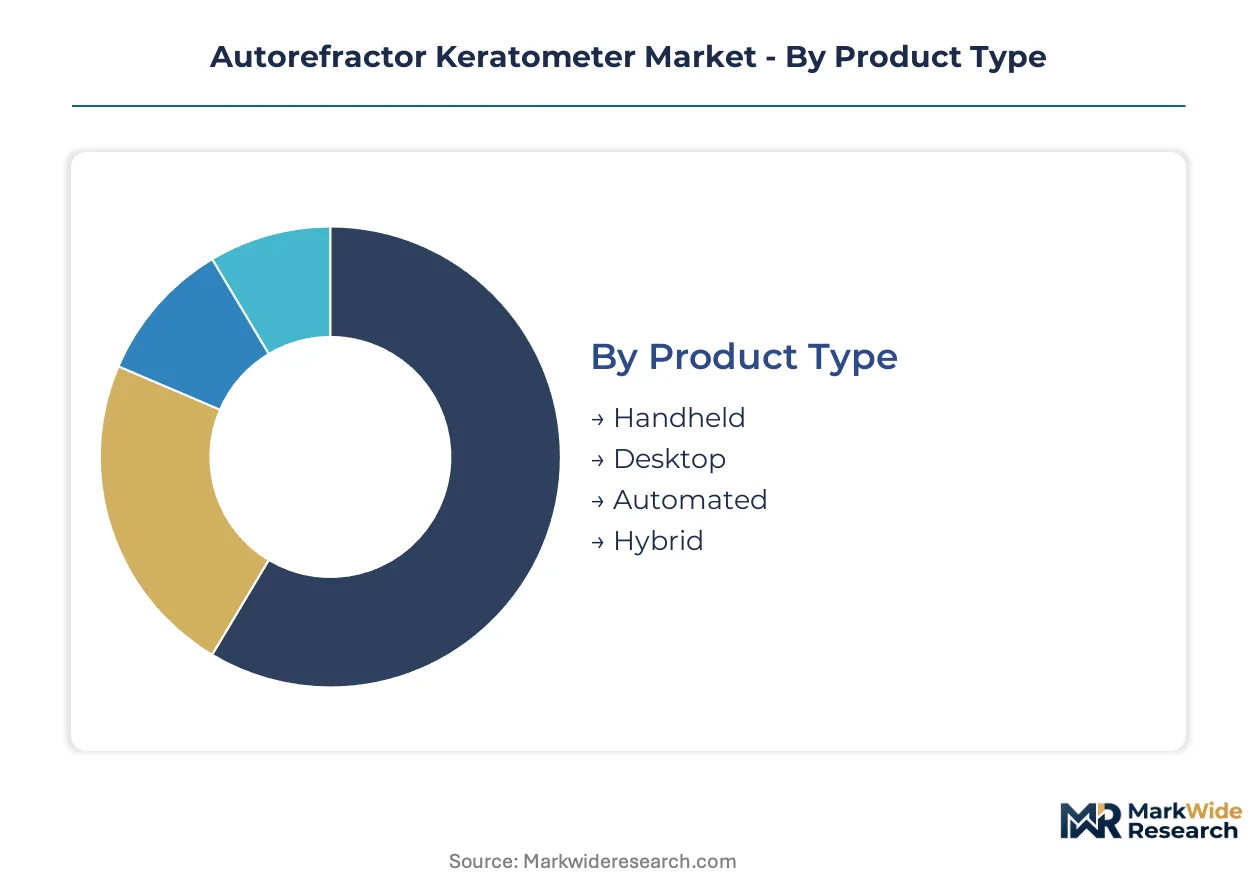
Desktop units require FDA 510(k) clearance as Class II medical devices, while handheld variants face additional ISO 10993 biocompatibility scrutiny for patient-contact surfaces. Automated and hybrid systems trigger enhanced EU MDR clinical evidence requirements due to embedded software algorithms.
- Handheld:Compact battery-powered designs with infrared light sources and integrated data storage enable mobile vision screening in rural India and community health programs. CDSCO device registration requirements are accelerating compliance investments by domestic distributors.
- Desktop:Stationary units with Shack-Hartmann wavefront modules and durable optical-grade polymer housings dominate hospital procurement in Germany's KBA-adjacent precision manufacturing clusters where METAS-traceable calibration is mandatory.
- Automated:Systems with motorized chin rests and automated alignment algorithms reduce operator dependence in high-throughput ophthalmology clinics.
- Hybrid:Configurations combining autorefractor, keratometer, and corneal topography functions in single platforms serve academic medical centers.
Desktop sits at the top of the volume ranking, with Handheld climbing the fastest.
Technology:
Cost tiers stratify sharply across technology segments, with wavefront modules commanding premium pricing against budget-sensitive digital imaging alternatives.
- Wavefront:Shack-Hartmann sensor arrays measure higher-order aberrations for premium intraocular lens fitting, capturing demand in Japan's METI-certified medical manufacturing zones where JIS-standard electromagnetic compatibility is required.
- Optical Coherence Tomography:Cross-sectional anterior segment imaging enables corneal pachymetry combined with refractive measurement, serving glaucoma screening workflows in tertiary hospitals.
- Digital Imaging:Basic Placido disk topography systems without aberration mapping meet postoperative assessment needs in price-sensitive optical stores.
- Traditional:Conventional autorefractor designs with manual keratometry rings persist in replacement cycles for legacy equipment bases.
Wavefront holds the revenue concentration lead, with Optical Coherence Tomography expanding most quickly in academic center procurement.
End User:
Customer type determines service bundling expectations, with hospital buyers demanding multi-year maintenance contracts versus optical retailers prioritizing capital efficiency.
- Ophthalmology Clinics:Private practice settings prioritize throughput speed and EMR interoperability, driving demand for cloud-connected systems with encrypted patient data transmission.
- Hospitals:Tertiary care centers require FDA-cleared devices with comprehensive validation documentation for integrated eye-care chains.
- Research Laboratories:Academic settings demand open data formats and raw wavefront export capabilities for clinical studies.
- Optical Stores:Retail chains focus on immediate curvature verification for contact lens e-commerce integration, unbundling after-sales service from purchase contracts.
Hospitals maintain the largest installed base, with Optical Stores gaining share fastest through retail-lab network expansion.
Application:
Application maturity varies by diagnostic complexity, with basic vision screening approaching commoditization while aberration-guided surgical planning commands technology premiums.
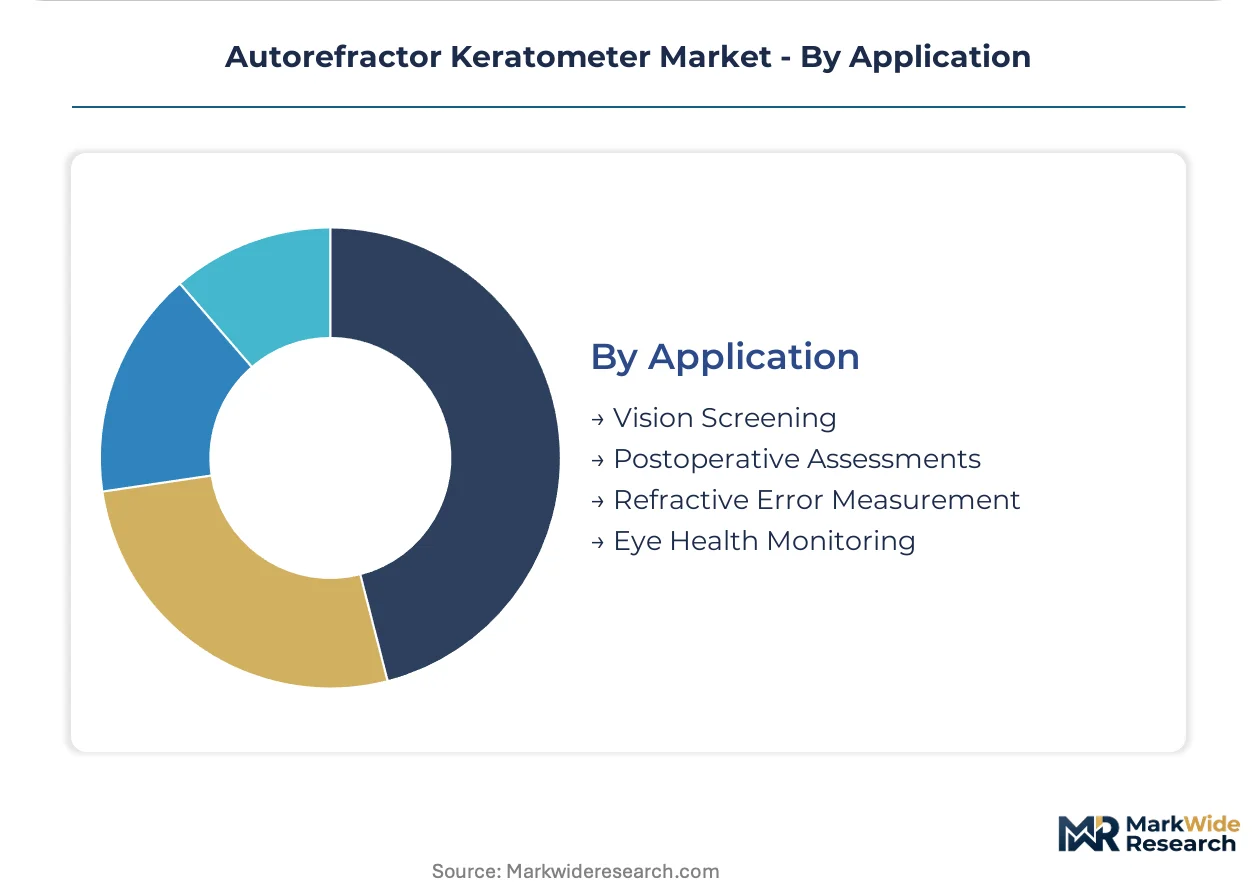
- Vision Screening:Mass population assessment programs in government-backed rural initiatives deploy handheld units with simplified operator interfaces.
- Postoperative Assessments:Cataract surgery follow-up requires basic keratometry without wavefront analysis, sustaining digital imaging demand.
- Refractive Error Measurement:Standard autorefraction for eyeglass prescription generation represents the historical core use case.
- Eye Health Monitoring:Longitudinal tracking of corneal changes in contact lens wearers drives combined Placido-Scheimpflug system adoption.
Refractive Error Measurement dominates procedure volume, with Eye Health Monitoring showing the steepest expansion trajectory as specialty lens practices proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA-adjacent precision manufacturing clusters anchor regional demand for autorefractor keratometers, with wavefront-enabled desktop systems capturing procurement concentration across multiple regulatory jurisdictions. National regulators enforce divergent certification pathways that reshape competitive entry timelines and equipment upgrade cycles.
United States
Tertiary hospital networks and integrated eye-care chains drive procurement volume for FDA-cleared desktop systems with Shack-Hartmann wavefront modules. FDA 510(k) clearance timelines have extended for instruments embedding AI-driven refraction algorithms, stretching market access for new entrants. The Greater Boston medical technology corridor concentrates validation documentation expertise and METAS-traceable calibration services.
Germany
Academic medical centers and specialty lens practices prioritize combined Placido-Scheimpflug systems for anterior segment analysis workflows. CE marking under EU MDR enforces prospective validation studies for Class IIa diagnostic software, accelerating inventory upgrades among optical equipment distributors. Stuttgart and Munich precision manufacturing zones supply optical-grade polymer housings with JIS-standard electromagnetic compatibility certification.
Japan
High-throughput ophthalmology clinics and METI-certified medical manufacturing zones generate concentrated demand for compact benchtop designs with embedded wavefront modules. PMDA enforces JIS-standard electromagnetic compatibility requirements that filter non-compliant imports from procurement pathways. Nagoya and Osaka industrial clusters host captive production of Shack-Hartmann sensor arrays and precision optical components.
India
Government-backed rural eye-care initiatives deploy handheld autorefractor keratometers for mobile vision screening outside tertiary hospital networks. CDSCO device registration requirements for ophthalmic diagnostics are accelerating compliance investments by domestic distributors. Maharashtra and Karnataka optical retail chains are expanding refractive screening services amid contact lens e-commerce integration.
South Korea
MFDS certification pathways and Seoul Capital Area medical device clusters support export-oriented manufacturing of mid-tier digital imaging systems. Domestic optical retailers prioritize capital-efficient procurement with unbundled after-sales service contracts. Busan-Ulsan precision instrument zones supply calibration services with ISO 17025-accredited traceability chains.
Autorefractor Keratometer Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers secure wavefront module supply and distribution channel access. The vendor base concentrates around three tiers: diversified optical conglomerates with retail-lab networks, specialized ophthalmic instrument manufacturers with in-house sensor production, and regional fabricators serving price-sensitive optical retail markets. Two archetypes define competitive positioning: integrated eye-care solution providers leveraging backward integration into diagnostic hardware, and component specialists supplying Shack-Hartmann arrays to multiple OEM brands. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping market structure.
Among Japan-based specialists, Topcon Corporation and NIDEK CO., LTD. exemplify divergent strategic archetypes within the ophthalmic instrument segment. Topcon Corporation anchors the wavefront module supply tier through captive production of precision sensor arrays. NIDEK CO., LTD. occupies a position within the compact benchtop design specialization for high-throughput clinical workflows. EssilorLuxottica represents the integrated conglomerate archetype, leveraging optical retail network density to secure instrument placement in chain environments. These three entities collectively illustrate how vertical scope and distribution control determine competitive positioning across premium and mid-tier market segments.
| Leading Market Players |
|---|
| CANON MEDICAL SYSTEMS CORPORATION |
| EssilorLuxottica |
| Topcon Corporation |
| Huvitz Co. Ltd. |
| Visionix |
| NIDEK CO., LTD. |
| Bausch + Lomb |
| Tomey Corporation |
| Carl Zeiss Meditech AG |
| Others |
Pricing and Supply Chain Analysis
Integrated eye-care chains and hospital procurement committees anchor pricing power in the autorefractor keratometer market, concentrating volume leverage around wavefront-enabled desktop systems with bundled multi-year service contracts. This buyer concentration rewards manufacturers with JIS-standard certification and METAS-traceable calibration capabilities, while squeezing margins for regional fabricators serving unbundled optical retail channels.
Pricing Analysis
Shack-Hartmann sensor array costs pass through directly to end-equipment pricing, with captive production at Topcon Corporation and NIDEK CO., LTD. insulating their premium tiers from component volatility. Three-tier pricing structure across premium wavefront, standard digital imaging, and economy traditional systems differentiates by FDA 510(k) clearance depth and EU MDR clinical evidence grade. Pricing pressure stems from smartphone-based refraction apps capturing preliminary screening segments in India's price-sensitive optical retail expansion. Optical stores exhibit highest price sensitivity, while Japan's METI-certified medical manufacturing zones tolerate premium positioning for JIS-compliant electromagnetic compatibility.
Supply Chain Analysis
Freight cost sensitivity shapes inventory positioning for optical-grade polymer housings sourced from Stuttgart and Munich injection molding zones serving German KBA-adjacent precision manufacturing clusters. Shack-Hartmann sensor arrays concentrate in Nagoya and Osaka industrial zones, precision optical components in South Korea's Busan-Ulsan instrument corridors, and calibration services with ISO 17025-accredited traceability chains. Single-source vulnerability runs through East Asian wavefront module production for mid-tier benchtop manufacturers lacking backward integration. Distribution runs through EssilorLuxottica's retail-lab network for integrated chains, independent distributors for hospital procurement, and direct-to-clinic channels for academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autorefractor keratometer market reads as a late-cycle quality story, with ophthalmology clinics and specialty lens practices prioritizing aberration mapping depth over throughput speed in procurement decisions. Wavefront-enabled diagnostic platforms are compressing replacement cycles for legacy equipment, rewarding manufacturers with pre-existing MDR technical documentation and Shack-Hartmann sensor miniaturization capabilities.
For Market Incumbents: Extend wavefront module supply agreements into exclusive arrangements with academic medical centers, locking out competitors facing retrospective EU MDR compliance gaps. Deepen captive production of optical-grade polymer housings to offset logistics disruption risks from East Asian injection molding concentration. Defend against smartphone-based refraction apps by embedding cloud-connected tele-ophthalmology functionality at mid-tier price points previously served by basic digital imaging. For New Entrants and Emerging Players: CDSCO device registration requirements in India open a window for domestic distributors to capture handheld autorefractor keratometer demand in government-backed rural eye-care initiatives outside tertiary hospital networks. Target optical retail chains in Maharashtra and Karnataka expanding refractive screening services amid contact lens e-commerce integration, where unbundled after-sales service contracts reduce incumbent attachment. Pursue white-label manufacturing partnerships with Seoul Capital Area medical device clusters for MFDS-certified export-oriented production. For Investors and Strategic Acquirers: Integrated eye-care conglomerates with retail-lab network density are the most active acquirer in this space, seeking wavefront module suppliers with pre-existing MDR technical documentation to fill portfolio gaps. Five-to-ten year viability hinges on tele-ophthalmology platform integration and encrypted patient data transmission capabilities. Acquisition target archetype: compact benchtop specialists with JIS-standard electromagnetic compatibility certification and high-throughput clinic relationships in East Asia. Monitor FDA 510(k) timeline extensions for AI-driven refraction algorithms as inflection indicator for new entrant market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements for Class IIa diagnostics reshape competitive entry timelines for wavefront module suppliers. |
| Hospital System Partnership | Integrated eye-care chains demand multi-year maintenance contracts with EMR interoperability, favoring manufacturers with cloud-connected platforms. |
| Software Companion Development | AI-driven refraction algorithms face enhanced FDA 510(k) scrutiny, stretching clearance durations for instruments with embedded diagnostic software. |
| Backward Integration | Captive Shack-Hartmann sensor production insulates premium tier pricing from component cost volatility in East Asian supply clusters. |
| Reimbursement Strategy | Government-backed rural vision screening programs in India create procurement pathways for handheld units with CDSCO device registration. |
Research Methodology
Bottom-up ophthalmology clinic and optical retail modeling reconciled against top-down Shack-Hartmann sensor array production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and optical equipment distributors combined with secondary validation against FDA 510(k) filings, PMDA submission databases, CDSCO device registration records, and EU MDR notified body documentation. Triangulation across bottom-up procedure volume estimates and top-down manufacturer shipment data ensures segmentation integrity.
Input-output matrix framing connects wavefront module production capacity to end-equipment installation base across desktop, handheld, automated, and hybrid product configurations. Segmentation dimensions modeled include technology tier, product type, end-user category, and application workflow across the projection horizon. CAGRs derive from installed base replacement cycle analysis, regulatory-driven upgrade demand, and mobile vision screening program expansion. Industry-specific forecast inputs incorporate JIS-standard electromagnetic compatibility certification velocity and METAS-traceable calibration service availability.
Revisions become necessary when FDA 510(k) timeline extensions for software-as-medical-device functionality intensify, EU MDR clinical evidence requirements for Class IIa diagnostics shift, or optical-grade polymer supply concentration in East Asian injection molding zones disrupts. Forecasts reflect assumptions about regulatory pathway stability, component cost trajectories, and tele-ophthalmology platform adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Spinal Traction Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Endoprosthesis Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Global Cosmetic Implants Market