
 Global Deep Vein Thrombosis Market | 2026-2036
Global Deep Vein Thrombosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Deep Vein Thrombosis Market Foresight
Hospital procurement channels for DVT prophylaxis are rewriting traditional purchasing hierarchies as integrated delivery networks consolidate vendor contracts. Pfizer leverages its established anticoagulant portfolio to sustain formulary dominance across major health systems. Boehringer Ingelheim anchors European hospital channels through specialized injectable therapy lines. Medtronic competes in mechanical intervention segments with catheter-based thrombectomy platforms.
Deep vein thrombosis refers to pathological clot formation within deep venous structures, typically the lower extremity iliofemoral system, requiring anticoagulant intervention with agents targeting factor Xa or thrombin to prevent pulmonary embolism and post-thrombotic syndrome. Anticoagulants dominate product type revenue due to chronic therapy requirements and oral formulation convenience, while mechanical compression devices represent the fastest-expanding segment as ambulatory surgery centers adopt non-pharmacologic prophylaxis protocols. Prophylaxis leads the therapy area dimension because surgical populations require systematic pre- and post-operative clot prevention, whereas acute treatment commands premium pricing through hospital-based injectable administration.
The FDA oversees anticoagulant approval pathways and risk evaluation mitigation strategies, while the EMA coordinates European marketing authorization through centralized procedures that shape multinational product launches. ISO 13485 standards govern compression device manufacturing quality, directly affecting market access for mechanical intervention suppliers. Stakeholders must monitor evolving thrombosis guidelines from the American College of Chest Physicians and European Society of Cardiology, as recommendation shifts between pharmacologic and mechanical prophylaxis will redirect procurement budgets across hospital and ambulatory settings.
Market Dynamics
Hospital formulary consolidation is compressing vendor access as integrated delivery networks centralize anticoagulant procurement decisions across multi-state systems. Mechanical prophylaxis protocols are expanding into ambulatory surgery centers, creating parallel demand channels that bypass traditional pharmaceutical contracting hierarchies.
Growth Catalysts
- Post-surgical prophylaxis mandates:The Joint Commission's surgical care improvement project standards now require systematic DVT risk assessment across accredited US hospitals, institutionalizing pharmacologic intervention protocols.
- Aging surgical populations:Germany's vascular surgery networks report expanding procedure volumes among patients over 65, where comorbidity profiles necessitate extended anticoagulant therapy.
- Injectable-to-oral transition:Direct oral anticoagulant formulations eliminate parenteral administration requirements, enabling outpatient treatment initiation and reducing hospital length-of-stay.
Market Restraints
- Heparin supply concentration:Porcine mucosa sourcing for unfractionated heparin production concentrates in Chinese agricultural processing regions, exposing manufacturers to veterinary health disruptions.
- Bleeding risk liability:Anticoagulant-associated hemorrhage generates substantial malpractice exposure, particularly in neurosurgical and trauma populations where reversal agent availability remains inconsistent.
- Mechanical device reimbursement gaps:CMS coverage determinations for intermittent pneumatic compression vary across surgical indication categories, creating payment uncertainty for device manufacturers.
Strategic Opportunities
- Home-based prophylaxis expansion:Japan's aging-in-place healthcare reforms create demand for portable mechanical compression systems that integrate with remote monitoring infrastructure.
- Biosimilar anticoagulant entry:EMA biosimilar guidance for low-molecular-weight heparins opens formulation substitution pathways in European hospital tender processes.
- Catheter-directed thrombolysis:Convergence of ultrasound-assisted lysis with aspiration thrombectomy enables single-session iliofemoral clot clearance, displacing multi-day infusion protocols.
Industry Challenges
- Specialized interventional training:Mechanical thrombectomy platform adoption requires vascular surgery fellowship programs to expand endovascular curriculum, creating credentialing bottlenecks.
- ISO 13485 certification timelines:Compression device manufacturers face extended quality system audits as notified bodies apply tightened MDR conformity assessment procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Deep Vein Thrombosis Market |
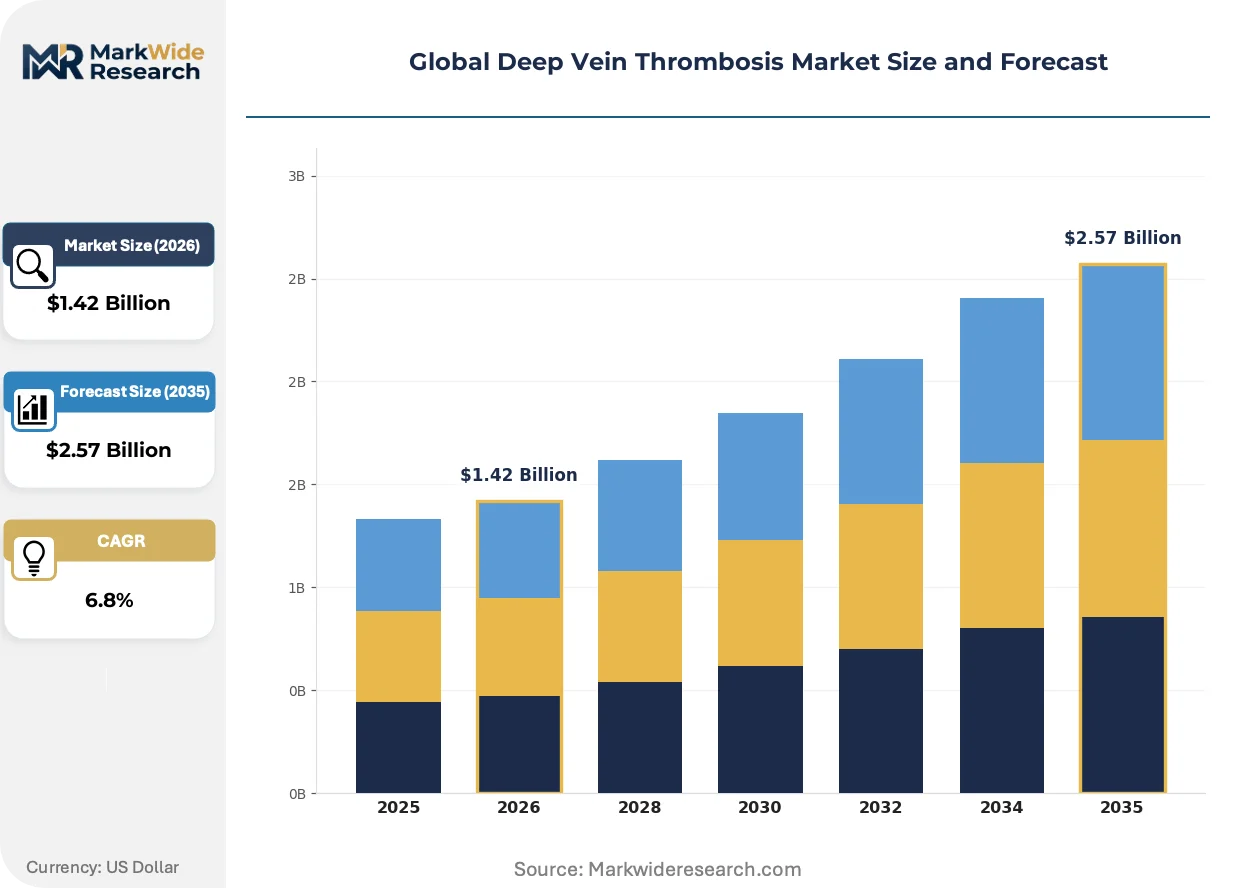
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Thrombolytics, Compression Devices, Inferior Vena Cava Filters, Venotonic Agents Therapy Area: Prophylaxis, Acute Treatment, Chronic Care, Post-Thrombotic Syndrome Management End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Rehabilitation Clinics Treatment Method: Oral Medication, Injectable Therapy, Mechanical Intervention, Physical Compression |
| Companies Covered | Pfizer, Bayer, Johnson & Johnson, Sanofi, Bristol-Myers Squibb, Boehringer Ingelheim, AstraZeneca, Novartis, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Deep Vein Thrombosis Market Shifts & Advancements
Wearable sensor integration and algorithmic risk stratification are transforming prophylaxis from protocol-driven to precision-targeted intervention. These developments compress the window between clot formation and therapeutic response while redistributing care delivery across inpatient and ambulatory settings.
Point-of-care D-dimer testing with age-adjusted cutoffs is rendering obsolete laboratory-based coagulation panels for low-probability patient triage. Emergency departments in the Netherlands and Scandinavia have adopted handheld devices for same-visit rule-out protocols. This decentralization is compressing diagnostic timelines from hours to minutes while reducing imaging utilization.
The FDA's 2023 updates to direct oral anticoagulant labeling requirements now mandate real-world evidence submissions for expanded indications, reshaping post-market study obligations. Manufacturers must maintain active surveillance infrastructure across heterogeneous patient populations. Hospital systems in the United States are responding by consolidating formulary decisions under pharmacy and therapeutics committees with dedicated anticoagulation stewardship programs.
Ambulatory surgery centers are unbundling prophylaxis from surgical episode payments, creating standalone mechanical device rental models. This separation enables procedure-agnostic compression therapy procurement that spans orthopedic, gynecologic, and general surgery service lines. The shift is most visible in Texas and Florida, where certificate-of-need deregulation has accelerated freestanding facility development.
Global Deep Vein Thrombosis Market Segmentation
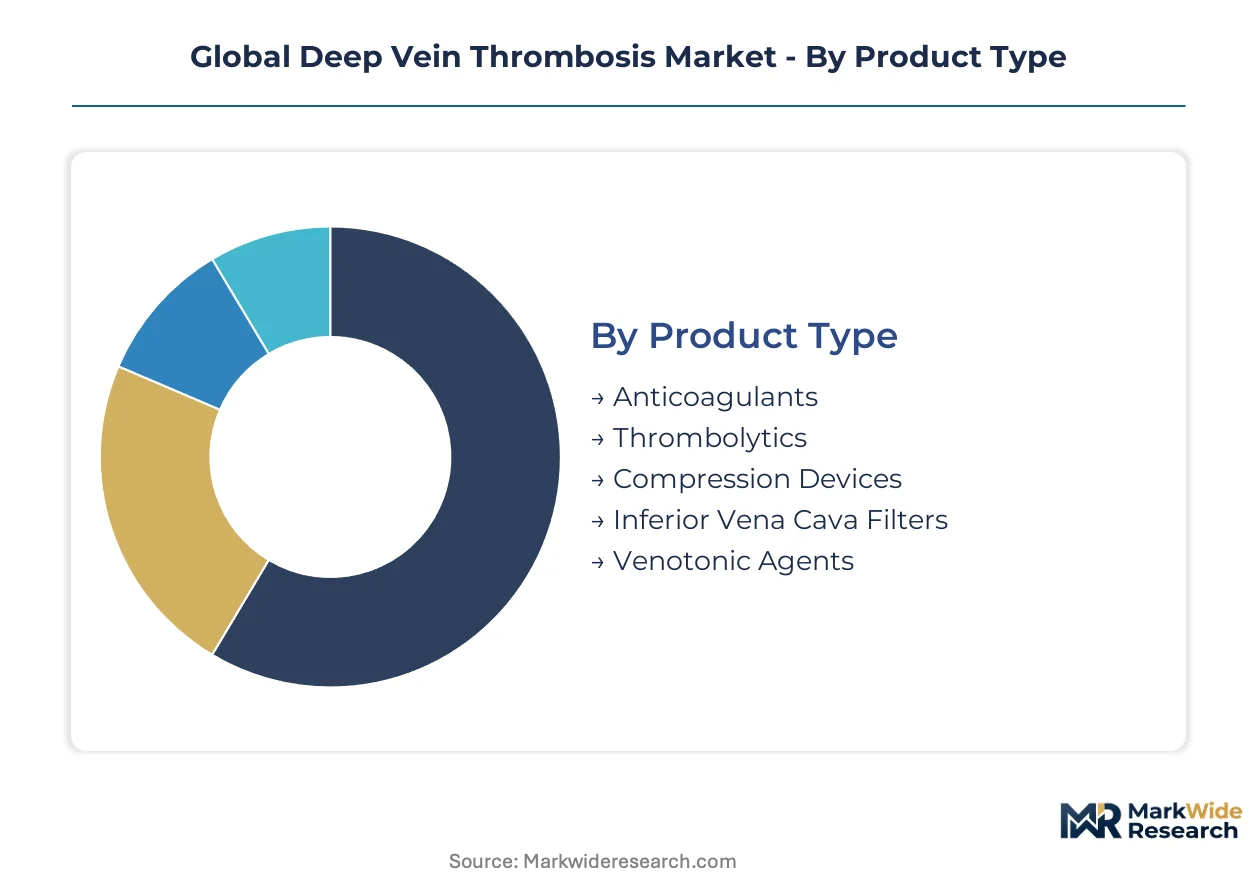
DVT market segmentation reflects divergent clinical workflows across acute intervention and chronic management settings. Product type and therapy area dimensions capture the tension between pharmaceutical revenue concentration and mechanical device expansion. End-user and treatment method categories map how care delivery is fragmenting between hospital systems and ambulatory venues.
Product Type:
Pharmacologic and mechanical modalities serve distinct patient risk profiles and care settings across the clinical spectrum.
- Anticoagulants:Factor Xa inhibitors and direct thrombin antagonists form the chronic therapy backbone, with oral formulations enabling outpatient management. Hospital formularies in Germany and the United States prioritize these agents for post-surgical prophylaxis protocols, though bleeding risk monitoring constrains expansion in neurosurgical populations.
- Compression Devices:Intermittent pneumatic and graduated compression systems deliver non-pharmacologic prophylaxis through programmable pressure cycles. Ambulatory surgery centers in Texas and Florida are adopting rental-based procurement models that bypass traditional pharmaceutical contracting channels.
- Thrombolytics:Tissue plasminogen activators and urokinase derivatives dissolve established clots through catheter-directed infusion.
- Inferior Vena Cava Filters:Retrievable and permanent implantable devices intercept emboli before pulmonary circulation.
- Venotonic Agents:Phlebotonics and micronized purified flavonoid fractions address venous insufficiency symptoms.
The dominant share belongs to Anticoagulants, while Compression Devices are gaining share fastest.
Therapy Area:
Revenue concentration varies sharply between prevention mandates and premium-priced acute intervention.
- Prophylaxis:Systematic risk assessment protocols now mandate pre- and post-operative clot prevention across Joint Commission-accredited facilities. Surgical populations in aging demographics—particularly Germany's vascular surgery networks—drive consistent procedure-linked demand for extended pharmacologic regimens.
- Acute Treatment:Hospital-based injectable administration commands premium pricing through parenteral heparin bridging and thrombolytic infusion. The FDA's evolving DOAC labeling requirements shape inpatient initiation protocols before oral transition.
- Chronic Care:Extended anticoagulation for recurrent clot prevention spans months to indefinite duration.
- Post-Thrombotic Syndrome Management:Compression therapy and venoactive drug combinations address long-term venous insufficiency sequelae.
Prophylaxis generates the highest procedure volume, yet Acute Treatment captures the steepest margin per episode.
End User:
Procurement authority is consolidating under integrated delivery networks while ambulatory channels fragment.
- Hospitals:Multi-state health systems centralize anticoagulant formulary decisions under pharmacy and therapeutics committees with dedicated stewardship programs. The Joint Commission's surgical care improvement project standards institutionalize systematic DVT risk assessment across accredited US facilities.
- Ambulatory Surgery Centers:Freestanding facilities in deregulated certificate-of-need states unbundle prophylaxis from surgical episode payments. Mechanical device rental models now span orthopedic, gynecologic, and general surgery service lines without procedure-specific constraints.
- Diagnostic Laboratories:Point-of-care D-dimer testing with age-adjusted cutoffs enables same-visit rule-out protocols.
- Rehabilitation Clinics:Post-acute settings manage extended compression therapy and ambulation protocols.
Hospitals retain the largest procurement budgets, though Ambulatory Surgery Centers are expanding their share of mechanical prophylaxis volume.
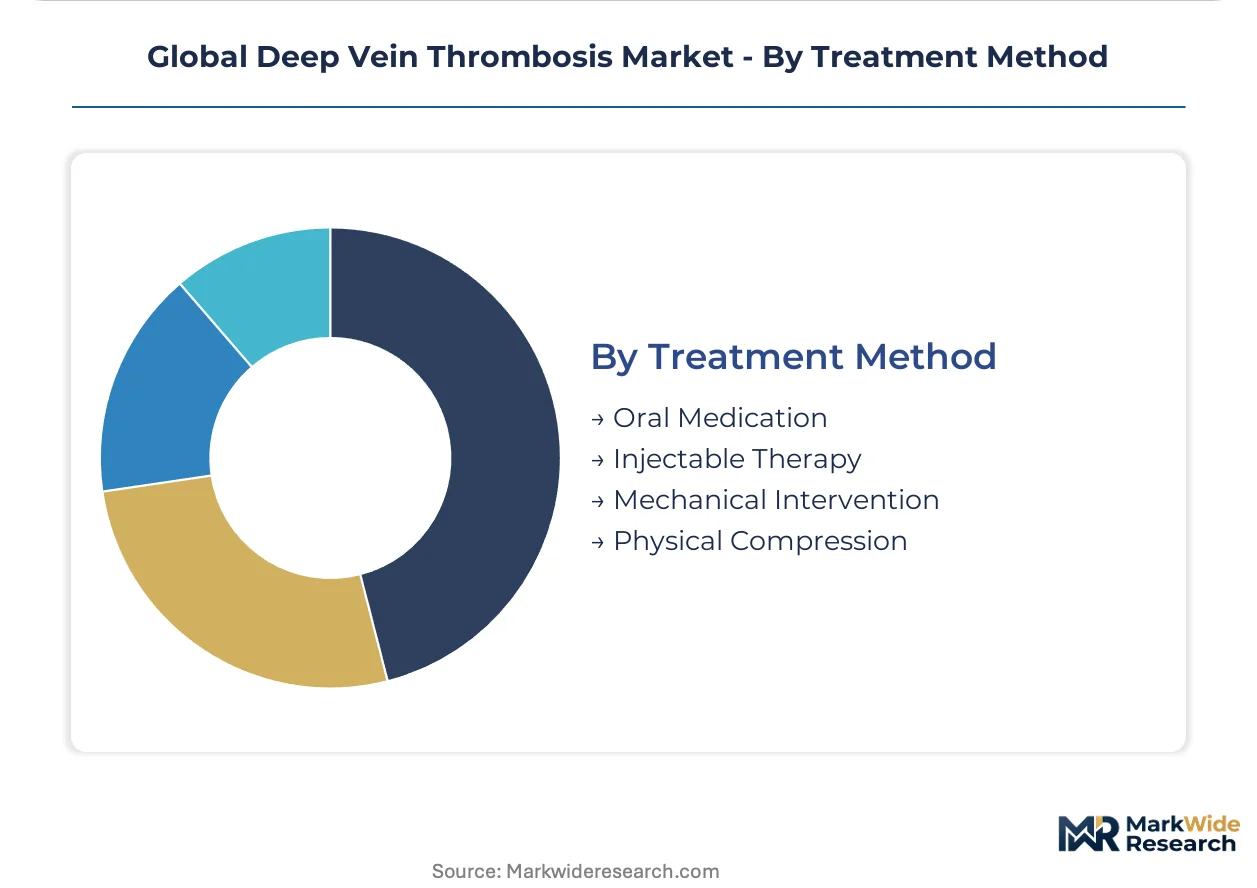
Treatment Method:
Administration route determines care setting, reimbursement pathway, and patient compliance architecture.
- Oral Medication:Direct oral anticoagulants eliminate parenteral requirements and enable outpatient treatment initiation. The FDA's 2023 labeling updates mandate real-world evidence submissions for expanded indications, reshaping post-market study obligations across heterogeneous populations.
- Injectable Therapy:Subcutaneous low-molecular-weight heparin and unfractionated heparin remain essential for acute bridging and perioperative management. Porcine mucosa sourcing concentration in Chinese agricultural regions exposes manufacturers to veterinary health disruptions.
- Mechanical Intervention:Catheter-directed thrombolysis and aspiration thrombectomy enable single-session iliofemoral clot clearance.
- Physical Compression:External pneumatic and elastic systems deliver prophylaxis without pharmacologic bleeding risk.
Oral Medication dominates chronic therapy volume, while Mechanical Intervention is climbing the fastest through endovascular platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy shifts and surgical volume mandates are redistributing DVT prophylaxis demand across mature healthcare systems. Government procurement programs and hospital accreditation standards now determine where pharmacologic and mechanical interventions concentrate.
United States
The Joint Commission's surgical care improvement project standards mandate systematic DVT risk assessment across all accredited facilities. FDA labeling updates for direct oral anticoagulants require real-world evidence submissions, reshaping post-market study obligations. Texas and Florida ambulatory surgery centers are unbundling prophylaxis from surgical episode payments, creating standalone mechanical device rental markets.
Germany
Aging demographics and established vascular surgery networks drive consistent procedure volumes among patients over 65 with complex comorbidity profiles. EMA centralized marketing authorization procedures shape multinational product launches for anticoagulant manufacturers. Baden-Württemberg and Bavaria host concentrated medical device manufacturing clusters producing compression therapy systems for European hospital tenders.
Japan
Aging-in-place healthcare reforms generate demand for portable mechanical compression systems integrating with remote monitoring infrastructure. PMDA oversight of anticoagulant approval pathways maintains rigorous safety evaluation standards. The Kanto region around Tokyo anchors hospital system procurement decisions for extended pharmacologic prophylaxis regimens.
United Kingdom
NICE guidelines on venous thromboembolism prevention drive formulary standardization across NHS trusts. MHRA post-Brexit regulatory autonomy creates parallel approval pathways diverging from EMA centralized procedures. London and the Southeast concentrate specialist vascular services performing catheter-directed thrombolysis interventions.
Netherlands
Point-of-care D-dimer testing with age-adjusted cutoffs enables same-visit rule-out protocols in emergency departments. Dutch healthcare insurance authority reimbursement determinations influence mechanical prophylaxis adoption in ambulatory settings. The Randstad urban corridor hosts medical technology firms developing wearable sensor integration for algorithmic risk stratification.
Global Deep Vein Thrombosis Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pharmaceutical portfolios and specialized mechanical intervention platforms. Hospital formulary decisions increasingly centralize under pharmacy and therapeutics committees with dedicated anticoagulation stewardship programs. Two strategic archetypes dominate: diversified pharmaceutical conglomerates with established anticoagulant franchises, and focused medical device specialists with catheter-based thrombectomy capabilities. Competitive moves concentrate on M&A to expand endovascular platforms and strategic partnerships to secure porcine mucosa sourcing for heparin production.
Within the pharmaceutical archetype, Pfizer leverages its established anticoagulant portfolio to sustain formulary dominance, while Boehringer Ingelheim anchors European hospital channels through specialized injectable therapy lines. Medtronic occupies a position in mechanical intervention segments with catheter-based thrombectomy platforms. These three represent the span from chronic oral therapy to acute mechanical intervention across hospital procurement hierarchies.
| Leading Market Players |
|---|
| Pfizer |
| Bayer |
| Johnson & Johnson |
| Sanofi |
| Bristol-Myers Squibb |
| Boehringer Ingelheim |
| AstraZeneca |
| Novartis |
| Medtronic |
| Others |
Supply & Pricing Matrix
Undercapacity in Chinese heparin API manufacturing is tightening raw material availability and amplifying pricing volatility for injectable anticoagulant producers. Pharmaceutical formularies and ambulatory surgery centers are responding with divergent procurement strategies that reshape margin structures across product tiers.
Pricing Analysis
Volume-discount tiering structures separate hospital system GPO contracts from ambulatory surgery center rental arrangements. Three-tier pricing stratifies across branded oral anticoagulants, biosimilar heparins, and mechanical compression devices. Price differentiation rests on FDA approval status and Joint Commission accreditation requirements. Cost compression in mechanical prophylaxis is intensifying because ASCs are unbundling device procurement from surgical episode payments. Ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks command lowest net pricing through consolidated purchasing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for heparin manufacturers. API production concentrates in China and India, with finishing operations in Germany and the United States. Porcine mucosa sourcing, medical-grade polymer fabrication, and sterile fill-finish capacity anchor upstream dependencies. Single-source vulnerability in Chinese agricultural processing regions threatens uninterrupted heparin supply. Distribution runs through integrated delivery network central warehouses and direct-to-ASC equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
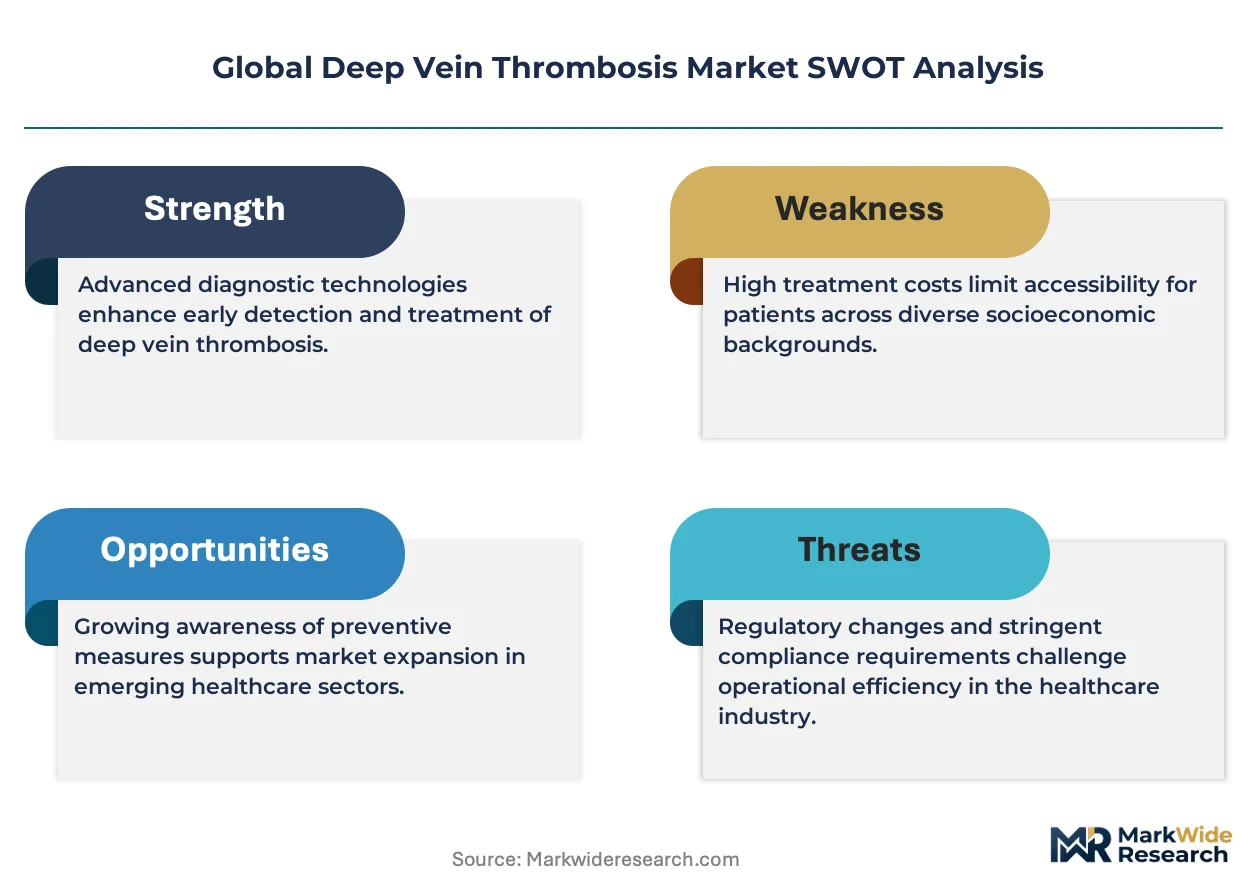
The DVT market is approaching a platform-economics inflection as wearable sensor integration and algorithmic risk stratification create interoperability standards that favor ecosystem orchestrators over standalone product vendors.
For Market Incumbents: Harden formulary position through captive heparin API supply and embedded pharmacy stewardship programs. Secure backward integration into porcine mucosa processing to mitigate Chinese supply concentration. Expand catheter-directed thrombolysis platform capabilities through vascular surgery fellowship partnerships that credential interventionalists. For New Entrants and Emerging Players: Portable mechanical compression systems for Japan's aging-in-place infrastructure represent the most penetrable entry point. Biosimilar low-molecular-weight heparin tenders in European hospital procurement channels offer formulation substitution pathways. Pursue regulatory approval alignment with EMA centralized procedures to accelerate multinational market access. For Investors and Strategic Acquirers: Capital is best deployed toward endovascular platform specialists with integrated thrombectomy and lysis capabilities. Long-term viability hinges on convergence with outpatient procedural migration and remote monitoring infrastructure expansion. Watch FDA real-world evidence submission requirements as the signal for post-market study obligation intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Pfizer secures formulary dominance through integrated delivery network contracting. |
| CE Marking Pathway | EMA centralized procedures accelerate mechanical device launches across European tenders. |
| Software Companion Development | Wearable sensor integration enables algorithmic DVT risk stratification for precision prophylaxis. |
| Reimbursement Strategy | CMS coverage determinations for intermittent pneumatic compression shape device adoption. |
| FDA Submission | Real-world evidence mandates for DOAC labeling reshape post-market surveillance infrastructure. |
Research Methodology
Desk research of FDA labeling archives, EMA marketing authorization databases, and hospital procurement records preceded structured interviews with vascular surgeons, pharmacy and therapeutics committee chairs, GPO contract managers, and biomedical engineers. Secondary validation drew from CMS coverage determinations, Joint Commission accreditation standards, and ISO 13485 certification registries. Bottom-up procedure volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Fixed assumptions included regulatory pathway timelines, reimbursement parity between pharmacologic and mechanical prophylaxis, and stable porcine mucosa supply chains. Variables encompassed biosimilar substitution rates, ASC facility development pace, and wearable sensor adoption curves. The analytical framework modeled product type, therapy area, end user, and treatment method segments across the projection horizon. CAGR derivation incorporated surgical volume demographics, aging-in-place policy shifts, and endovascular platform penetration.
Practitioners should monitor heparin supply disruptions, FDA real-world evidence enforcement intensity, and CMS mechanical device coverage expansions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Global Statin Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Stroke Management Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market