
 Automatic Pill Dispenser Machine Market | 2026-2036
Automatic Pill Dispenser Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Pill Dispenser Machine Market Intelligence
Home care is repositioning as the dominant end-use vertical, overtaking hospital-centric deployment as patients prioritize aging-in-place strategies. Omnicell Inc. leverages institutional pharmacy automation expertise to extend into ambulatory settings, while Yuyama Co., Ltd. anchors Asian manufacturing scale for compact residential units. Baxter International Inc. competes through integrated infusion-dispensing platforms that blur device category boundaries.
An automatic pill dispenser machine is an electromechanical or software-enabled device that stores, sorts, and releases medications at programmed intervals, typically incorporating load-cell weight sensors, tamper-evident compartments, and audible or visual alert systems to ensure dosing adherence. Its primary commercial purpose is to reduce medication errors, improve therapeutic compliance, and lower healthcare system costs associated with adverse drug events. Standalone units dominate current volume as the accessible price point drives penetration in retail pharmacy and home settings, while integrated systems capture margin pools through enterprise software tie-ins with electronic health records. Cloud connectivity represents the fastest-expanding technology segment as remote patient monitoring contracts expand and reimbursement codes mature for telehealth-adjacent services.
FDA 510(k) clearance pathways and HIPAA Security Rule mandates shape device validation timelines and data architecture requirements for manufacturers targeting the United States. The EU Medical Device Regulation imposes clinical evidence and post-market surveillance obligations that favor established players with regulatory affairs infrastructure. Stakeholders must monitor evolving CMS reimbursement decisions for remote therapeutic monitoring, as coverage determinations will dictate whether home-based dispensing shifts from consumer-paid to insurer-funded procurement models.
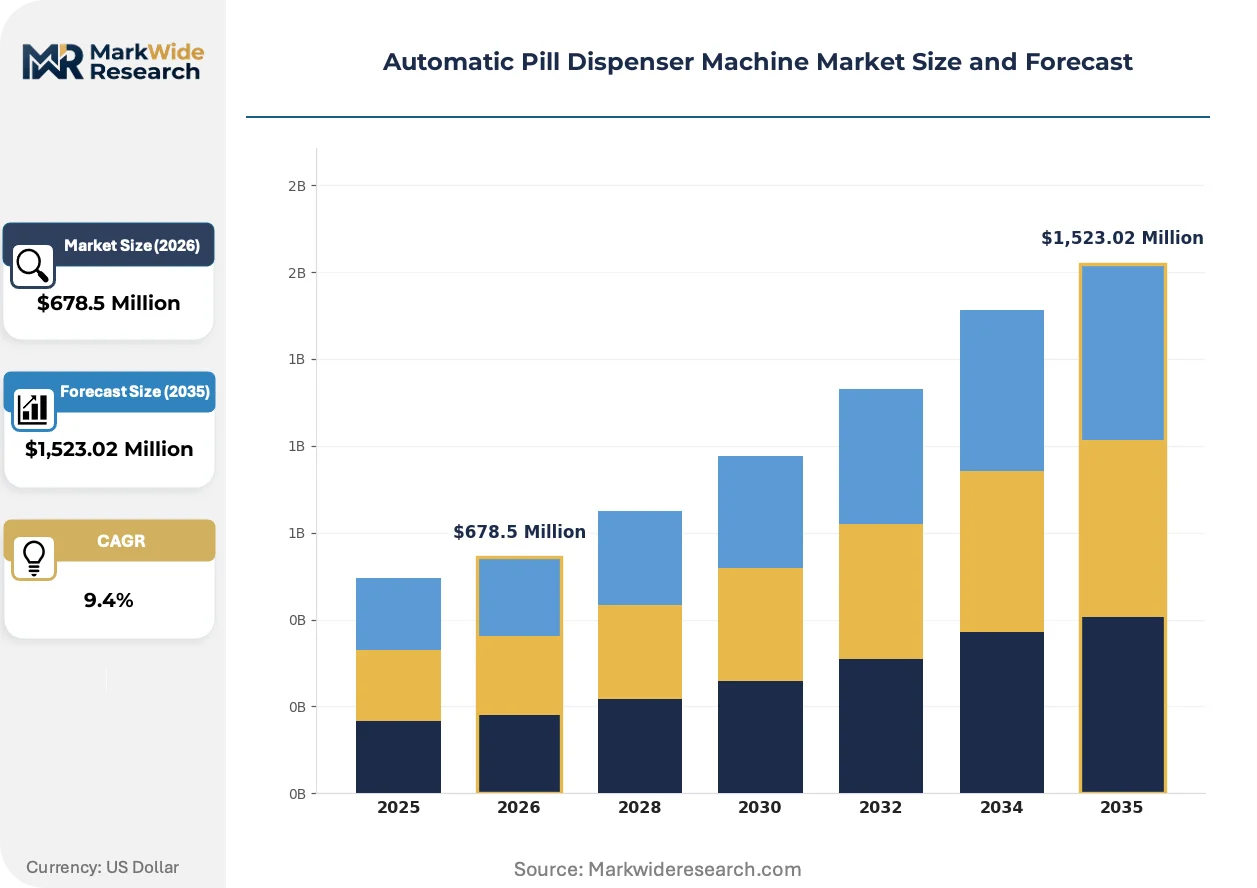
Market Dynamics
Home-based medication management is displacing institutional dispensing as chronic disease patients seek autonomy and payers push cost avoidance through remote monitoring infrastructure.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined premarket notification for moderate-risk devices accelerates product launch timelines and reduces regulatory capital requirements for manufacturers targeting the United States.
- Cloud-Enabled Remote Monitoring:Cellular and Wi-Fi connectivity modules embedded in residential units enable real-time adherence tracking and caregiver alerts, expanding reimbursable telehealth service bundles.
- Japan's Super-Aged Society:METI-supported smart home initiatives drive municipal procurement of automated dispensing systems for public housing complexes serving citizens over 75.
Market Restraints
- Semiconductor Component Volatility:Microcontroller and sensor supply constraints originating from concentrated East Asian foundry capacity inflate bill-of-materials costs and extend production lead times.
- EU MDR Clinical Evidence Burden:Post-market surveillance and periodic safety update report obligations impose documentation costs that disadvantage smaller manufacturers lacking regulatory affairs infrastructure.
- Manual Pill Organizers:Low-cost plastic compartment boxes retain preference among price-sensitive consumers and informal caregivers, limiting addressable market expansion in emerging economies.
Strategic Opportunities
- CMS Remote Therapeutic Monitoring Codes:Expanding Medicare reimbursement for device-supplied physiologic data creates a payer-funded procurement pathway previously restricted to consumer out-of-pocket purchase.
- Behavioral Health Integration:Psychiatric medication adherence applications represent an underserved vertical where mood-stabilizing and antipsychotic regimens require strict timing compliance.
- Voice-Assistant Convergence:Integration with Amazon Alexa and Google Home ecosystems enables hands-free status queries and caregiver notifications, differentiating premium residential units.
Industry Challenges
- Firmware Validation for FDA Submission:Software-as-a-medical-device documentation requirements demand specialized quality engineering talent scarce among hardware-centric manufacturers.
- Legacy EHR Integration Complexity:Proprietary data formats in hospital and pharmacy information systems obstruct seamless adherence data flow, requiring costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Pill Dispenser Machine Market |
| Market Size in 2026 | $678.5 Million |
| Market Size in 2035 | $1,523.02 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Units, Integrated Systems, Mobile Devices, Advanced Models Technology: Smart Dispensing, RFID Tracking, Automated Sorting, Cloud Connectivity End User: Home Care, Pharmacies, Hospitals, Assisted Living Facilities Delivery Mode: Self-Service, Remote Monitoring, In-Store Assistance, On-Demand |
| Companies Covered | Omnicell Inc., Becton Dickinson and Company, ScriptPro LLC, Capsa Healthcare, McKesson Corporation, Baxter International Inc., Yuyama Co., Ltd., Cerner Corporation, Swisslog Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Pill Dispenser Machine Market Strategic Shifts & Innovations
Connectivity architectures and reimbursement policy evolution are compressing the boundary between consumer wellness devices and regulated medical equipment.
Load-cell weight sensing paired with machine learning algorithms is overtaking simple timer-based dispensing in residential units. Home care agencies and aging-in-place service providers are adopting these systems to document medication events for liability reduction. The technology is overtaking basic alarm-clock dispensers in premium segments by enabling pill-by-pill verification rather than binary door-open events.
The EU Medical Device Regulation's software classification rules are redefining product development roadmaps. Manufacturers must now compile clinical performance evidence for algorithm-driven dosing reminders previously treated as accessory features. German and French notified bodies are enforcing stricter cybersecurity documentation, compelling firmware architecture redesigns for cloud-connected units sold in Europe.
Pharmacy benefit managers are piloting direct-to-patient device fulfillment models that bypass retail distribution. CVS Caremark and Express Scripts contracts now include automatic dispenser placement for high-cost specialty medications with narrow therapeutic indices. This channel compression is most visible in the United States, where vertical integration between insurers and pharmacy operations enables closed-loop adherence monitoring tied to outcome-based rebate contracts.
Automatic Pill Dispenser Machine Market Segmentation
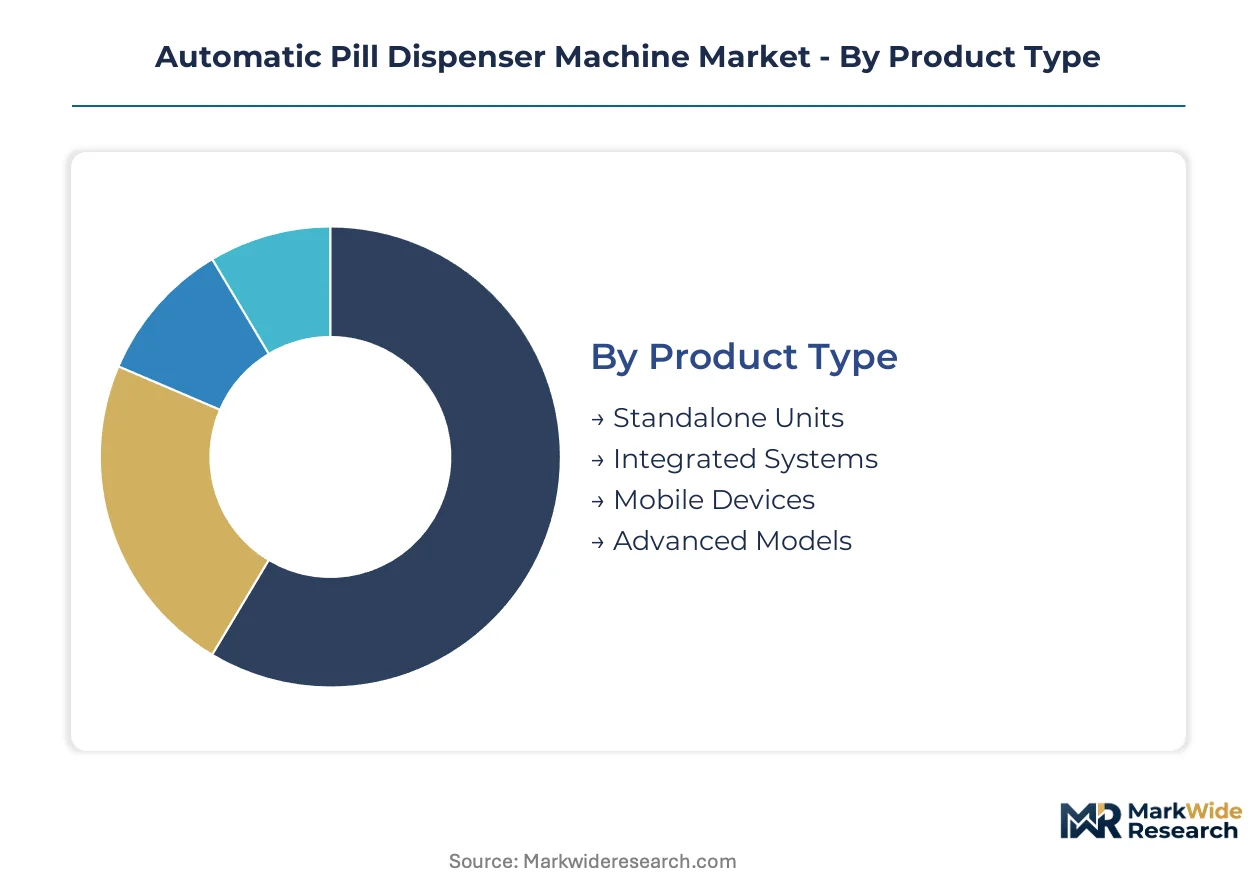
Segmentation in the automatic pill dispenser machine market reveals how capital allocation, technical complexity, and reimbursement pathways diverge across product architectures. Manufacturers prioritize segments where hardware margins align with recurring software revenue or where regulatory clearance unlocks institutional procurement channels.
Product Type:
Capital intensity varies sharply across this category, with integrated systems demanding multi-year software development cycles and FDA validation budgets that dwarf mechanical fabrication costs.
- Standalone Units:Electromechanical cabinets with programmable timers and compartmentalized storage dominate residential and retail pharmacy deployment. Home care agencies in the United States favor these units for their accessible price point and minimal installation requirements, though reimbursement remains predominantly consumer-funded.
- Integrated Systems:Enterprise-grade platforms tethered to electronic health records and pharmacy information systems require substantial upfront investment in interoperability middleware. Hospitals and health systems concentrate demand here, driven by Joint Commission medication safety mandates and liability reduction objectives.
- Mobile Devices:Portable dispensers with battery power and cellular connectivity serve traveling patients and field-based caregivers.
- Advanced Models:Units incorporating biometric authentication and machine learning algorithms occupy the premium tier.
Standalone units absorb the bulk of installed capacity; integrated systems are expanding most quickly through health system consolidation and EHR mandates.
Technology:
Application context determines which technology layers command investment priority, with cloud infrastructure and algorithm development now consuming larger budget shares than hardware engineering.
- Smart Dispensing:Microcontroller-driven mechanisms with load-cell verification and adaptive timing algorithms enable pill-by-pill adherence tracking. Home care providers in Japan's municipal housing programs deploy these systems to document medication events for regulatory compliance.
- Cloud Connectivity:Cellular and Wi-Fi modules transmitting dosing events to remote monitoring platforms represent the steepest expansion trajectory. United States reimbursement evolution through CMS remote therapeutic monitoring codes is accelerating payer-funded procurement previously restricted to direct-to-consumer sales.
- RFID Tracking:Radio-frequency identification enables unit-dose verification and supply chain authentication.
- Automated Sorting:Robotic mechanisms for high-volume institutional pharmacy environments reduce labor costs.
Smart dispensing retains the largest installed base; cloud connectivity is climbing the fastest as telehealth infrastructure matures.
End User:
Customer type segmentation maps directly to procurement authority structures, with institutional buyers leveraging group purchasing organizations and home care segments navigating fragmented reimbursement landscapes.
- Home Care:Individual patients and family caregivers purchasing through retail channels or aging-in-place service providers. Japan's METI-supported smart home initiatives and United States Medicare Advantage supplemental benefits are concentrating demand here.
- Hospitals:Inpatient and outpatient pharmacy departments with formulary control and clinical decision support integration. FDA 510(k) clearance requirements shape vendor qualification processes.
- Pharmacies:Retail chains and specialty pharmacies deploying patient adherence programs.
- Assisted Living Facilities:Operators balancing medication management liability with staffing constraints.
Home care captures the greatest volume expansion; hospitals maintain the highest average transaction values.
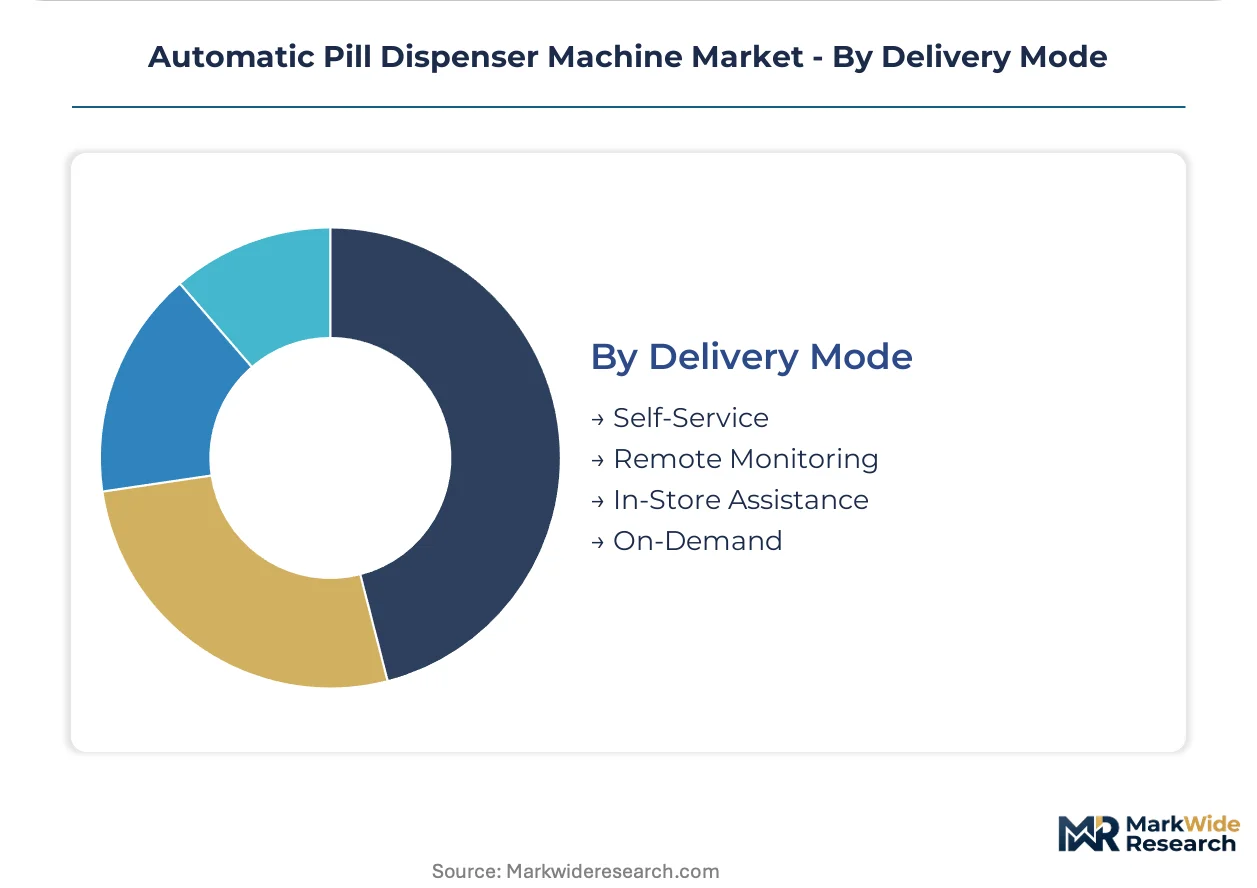
Delivery Mode:
Distribution architecture determines margin capture, with self-service and remote monitoring models enabling recurring revenue streams that in-store assistance cannot replicate.
- Remote Monitoring:Cloud-connected devices with caregiver dashboards and adherence alerts generate subscription revenue alongside hardware sales. Pharmacy benefit managers in the United States are piloting direct-to-patient fulfillment for specialty medications.
- Self-Service:Retail pharmacy kiosks and e-commerce direct shipment with minimal clinical oversight. Price-sensitive consumers and informal caregivers drive volume here.
- In-Store Assistance:Pharmacist-guided device setup and medication loading.
- On-Demand:Rental or short-term deployment models for post-acute transitions.
Self-service accounts for the majority of unit shipments; remote monitoring is gaining share fastest through reimbursement code expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Massachusetts and Minnesota concentrate FDA-cleared manufacturing capacity for automatic pill dispensers targeting United States reimbursement channels.
United States
Medicare Advantage supplemental benefits and remote therapeutic monitoring reimbursement codes drive home care procurement. FDA 510(k) clearance pathways shape product validation timelines for manufacturers. The Minneapolis-St. Paul corridor anchors institutional pharmacy automation engineering talent pools.
Japan
METI-supported smart home initiatives for citizens over 75 accelerate municipal procurement of residential dispensing systems. PMDA medical device regulations align with international harmonization frameworks. The Nagoya industrial cluster concentrates compact electromechanical fabrication for Asian export markets.
Germany
EU MDR clinical evidence requirements favor established manufacturers with regulatory affairs infrastructure. The country's national pharmaceutical regulator enforces post-market surveillance obligations through notified bodies. The Baden-Württemberg medical technology corridor integrates dispensing systems with hospital information networks.
United Kingdom
NHS long-term plan commitments to aging-in-place services expand home-based medication management procurement. MHRA post-Brexit device regulations maintain alignment with EU MDR standards. The Cambridge life sciences cluster develops algorithm-driven adherence verification software.
China
NMPA Class II medical device registrations enable domestic manufacturers to capture hospital pharmacy automation demand. The country's national pharmaceutical regulator accelerates review timelines for innovation-track products. The Suzhou industrial park hosts contract manufacturing for compact residential units serving aging urban populations.
Automatic Pill Dispenser Machine Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with institutional buyers consolidating procurement through group purchasing organizations while home care channels fragment across direct-to-consumer and aging-in-place service providers. The vendor base organizes into three tiers: enterprise health system integrators, regional pharmacy automation specialists, and compact residential unit fabricators. Two dominant competitive moves define current positioning: strategic partnerships with pharmacy benefit managers for closed-loop adherence monitoring, and backward integration into cloud connectivity modules to capture recurring software revenue.
Among North American health technology conglomerates, Omnicell Inc., Becton Dickinson and Company, and Baxter International Inc. exemplify the enterprise integration archetype, occupying positions where institutional pharmacy automation expertise extends into ambulatory and residential settings through software-enabled service bundles.
| Leading Market Players |
|---|
| Omnicell Inc. |
| Becton Dickinson and Company |
| ScriptPro LLC |
| Capsa Healthcare |
| McKesson Corporation |
| Baxter International Inc. |
| Yuyama Co., Ltd. |
| Cerner Corporation |
| Swisslog Healthcare |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance bifurcation separates premium-certified units from commodity-grade dispensers, with this certification ladder manifesting in pricing spreads exceeding threefold and supply chains clustering around regulatory expertise hubs versus generic electromechanical fabrication zones. Manufacturers without FDA validation capacity face exclusion from Medicare-funded procurement channels, compressing their addressable market to cash-pay retail segments with corresponding margin erosion.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with health systems paying substantial markups for expedited FDA-cleared inventory while spot-market units from uncertified Asian fabricators trade at steep discounts. The dominant pricing model stratifies across premium, standard, and economy tiers tied to certification grade and connectivity sophistication. Price differentiation hinges on FDA clearance status and cloud software bundling, with the former commanding institutional procurement and the latter enabling recurring SaaS revenue. Cost compression in economy tiers is intensifying because microcontroller supply constraints inflate bill-of-materials costs. Home care agencies exhibit highest price sensitivity, while hospital purchasing committees prioritize liability reduction over unit cost.
Supply Chain Analysis
Workforce availability constraints in Massachusetts and Minnesota medical device corridors limit scaling capacity for FDA-validated production, pushing manufacturers toward automation investments. Geographic supply concentration centers on China for compact electromechanical components, Japan for precision load-cell sensors, and the United States for cloud connectivity modules and regulatory affairs talent. Raw material dependencies encompass medical-grade polymers, semiconductor microcontrollers, and cellular communication chipsets. Single-source vulnerability in East Asian foundry capacity presents structural risk given geopolitical friction and export control exposure. Distribution runs through pharmacy benefit manager direct-fulfillment networks for institutional buyers and e-commerce platforms for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
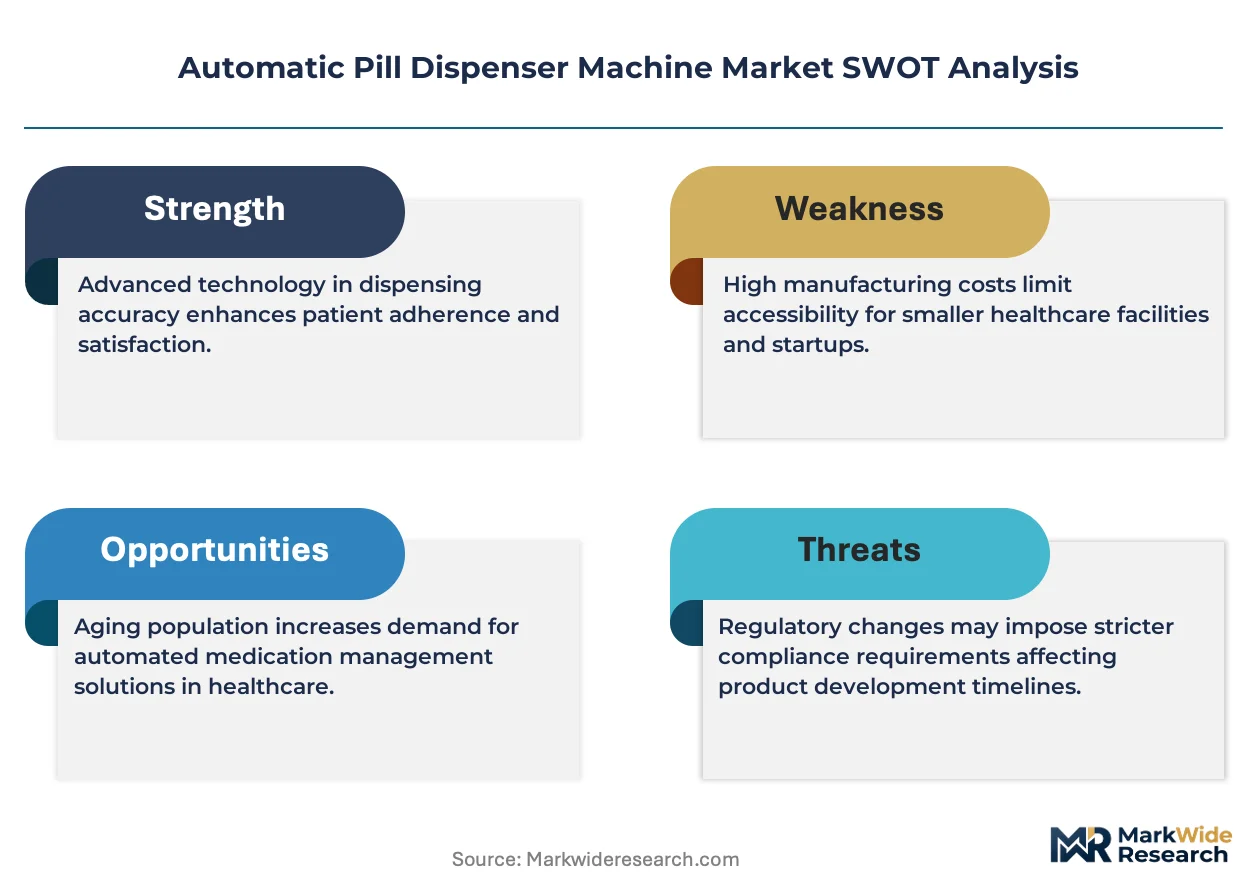
This market is consolidating around regulatory compliance capabilities, with EU MDR documentation burdens and FDA software-as-medical-device requirements forcing capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from pharmacy benefit manager vertical integration by securing backward integration into cloud connectivity modules and proprietary adherence algorithms. Omnicell Inc. and Baxter International Inc. exemplify defensive positioning through EHR-integrated platform bundling that raises switching costs for health system customers. Capacity addition in FDA-cleared manufacturing zones reinforces procurement qualification for Medicare-funded channels. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most penetrable entry vector, bypassing institutional procurement barriers dominated by entrenched vendors. Behavioral health medication adherence represents underserved white-space, with psychiatric regimens requiring strict timing compliance and limited incumbent specialization. Voice-assistant ecosystem integration provides differentiated go-to-market positioning against basic timer-based competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by health technology conglomerates seeking ambulatory care expansion capabilities. Long-term viability favors manufacturers with demonstrated FDA 510(k) clearance velocity and recurring software revenue traction over hardware-only fabricators. The signal to watch is CMS remote therapeutic monitoring code expansion, which would trigger payer-funded procurement inflection and revalue device-supplied data platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks Medicare reimbursement channels and hospital procurement qualification for manufacturers. |
| Cloud Connectivity Module Development | Enables recurring SaaS revenue streams tied to remote patient monitoring contracts. |
| Pharmacy Benefit Manager Partnership | Secures closed-loop adherence monitoring contracts with verticalized insurer networks. |
| Behavioral Health Vertical Expansion | Captures underserved psychiatric medication adherence demand with specialized timing protocols. |
| Voice-Assistant Ecosystem Integration | Differentiates premium residential units through hands-free caregiver notification capabilities. |
Research Approach
Document review covered FDA 510(k) clearance databases, EU MDR notified body guidance, and CMS reimbursement determinations, complemented by interviews with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and home care agency operators. Secondary validation drew from hospital procurement databases, Medicare Advantage plan filings, and medical device trade customs records. Bottom-up unit shipment estimates triangulated against top-down healthcare expenditure allocation models across the analysis window.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework, with segmentation dimensions encompassing product architecture, connectivity technology, end-user procurement authority, and delivery mode. CAGRs were derived from fitted growth curves applied to validated baseline estimates, incorporating remote therapeutic monitoring reimbursement evolution and aging-in-place demographic projections as industry-specific forecast inputs.
The model holds under stable CMS coverage determination trajectories and continued FDA 510(k) pathway accessibility; deviation in reimbursement code expansion timelines or semiconductor supply normalization would shift volume and value projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Global Transdermal Skin Patches Market