
 Canada Respiratory Devices Market | 2026-2036
Canada Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Respiratory Devices Market Outlook
Canada is narrowing its reliance on imported respiratory equipment through targeted domestic manufacturing incentives and provincial health authority procurement localization. Medtronic PLC leverages extensive distribution agreements with Canadian hospital networks to sustain equipment placement across acute care settings. Koninklijke Philips N.V. anchors its position through sleep apnea diagnostic and therapy platforms aligned with provincial reimbursement schedules. Fisher & Paykel Healthcare Limited specializes in humidification and high-flow nasal cannula systems that dominate intensive care protocols in Canadian teaching hospitals.
Respiratory devices encompass mechanical apparatus designed to assist, monitor, or deliver therapeutic agents to the pulmonary system, typically operating at pressure ranges from 4-20 cm H₂O for positive airway pressure applications and flow rates exceeding 60 L/min for high-flow oxygen delivery. These systems serve critical functions across acute intervention, chronic disease management, and home-based nocturnal therapy. CPAP devices and oxygen concentrators capture the largest installed base within the product type dimension, reflecting entrenched reimbursement for sleep-disordered breathing and chronic hypoxemic conditions. Home care and long-term care facilities represent the fastest-expanding end user channel as provincial health systems discharge patients earlier to reduce hospital occupancy costs. Digital monitoring technology within the technology segment commands premium positioning through remote adherence tracking and cloud-connected diagnostic feedback loops that integrate with electronic health records.
Health Canada administers the Medical Devices Regulations under the Food and Drugs Act, classifying respiratory equipment from Class II to Class IV based on invasiveness and criticality, which directly determines pre-market submission requirements and quality system audits. The Canadian Standards Association maintains CAN/CSA-ISO 80601-2-80 for home healthcare respiratory support equipment, establishing electrical safety and alarm performance benchmarks that manufacturers must satisfy for market authorization. Provincial formularies and interprovincial purchasing alliances further constrain pricing flexibility while demanding evidence-based clinical outcomes documentation. Stakeholders must monitor evolving interoperability mandates between respiratory devices and hospital information systems as provinces consolidate digital health infrastructure procurement.
Market Dynamics
Provincial health authorities in Ontario and Quebec are accelerating home care discharge protocols, compressing hospital length-of-stay targets and forcing device manufacturers to reconfigure product portfolios toward portable, patient-managed respiratory support systems.
Growth Catalysts
- Canada's Medical Devices Regulations:Health Canada's streamlined Class II-IV approval pathways for home-use respiratory equipment reduce time-to-market for manufacturers targeting chronic disease management segments.
- High-flow nasal cannula systems:Intensive care units in Canadian teaching hospitals are standardizing humidified high-flow oxygen delivery protocols, creating sustained procurement demand for integrated heated breathing circuits.
- Ontario's aging demographic concentration:The province's 65-plus population density drives volume procurement through centralized provincial purchasing alliances and regional health networks.
Market Restraints
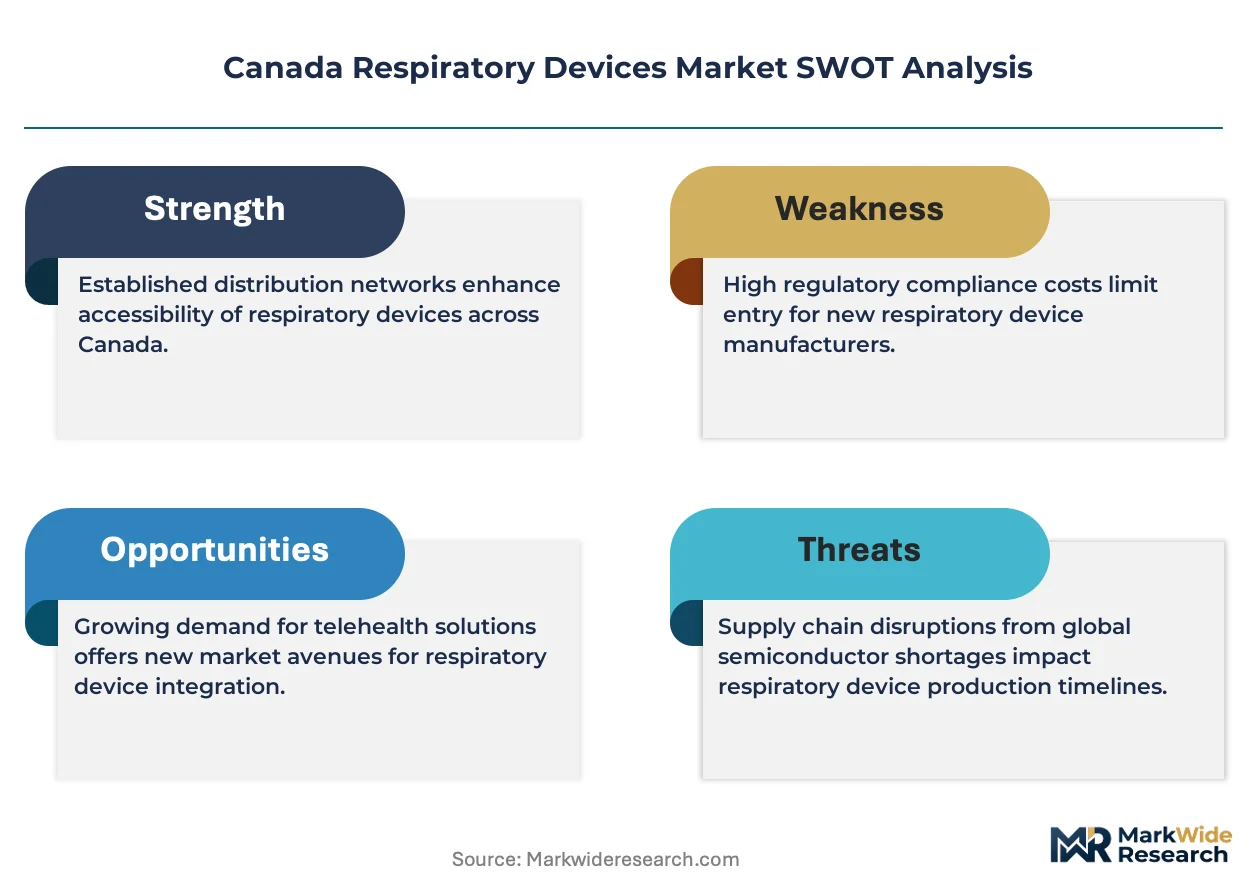
- Semiconductor component concentration:Flow sensors and pressure transistors sourced from East Asian foundries expose Canadian distributors to supply volatility and extended lead times.
- Interprovincial pricing compression:Pan-Canadian Pharmaceutical Alliance joint procurement agreements constrain manufacturer margin flexibility across ventilator and oxygen concentrator categories.
- Biocompatible polymer input costs:Medical-grade polycarbonate and silicone elastomer prices fluctuate with petrochemical feedstock indices, pressuring bill-of-materials stability.
Strategic Opportunities
- Remote patient monitoring convergence:Cloud-connected CPAP adherence platforms integrating with provincial electronic health records create service revenue streams beyond hardware sales.
- Quebec's long-term care expansion:Provincial infrastructure investments in CHSLD facilities generate demand for non-invasive ventilation and cough-assist devices in institutional settings.
- Digital therapeutics reimbursement:Emerging provincial codes for software-enabled respiratory coaching applications open adjacent revenue pools for device-software bundled offerings.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in respiratory algorithm development and pneumatic system design concentrates in Toronto and Montreal, constraining R&D scaling.
- CAN/CSA-ISO 80601-2-80 certification timelines:Electrical safety and alarm performance testing for home healthcare respiratory equipment extends product launch schedules by 8-14 months.
- Legacy hospital information system integration:Proprietary data protocols in established provincial EHR networks complicate interoperability certification for connected respiratory devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Respiratory Devices Market |
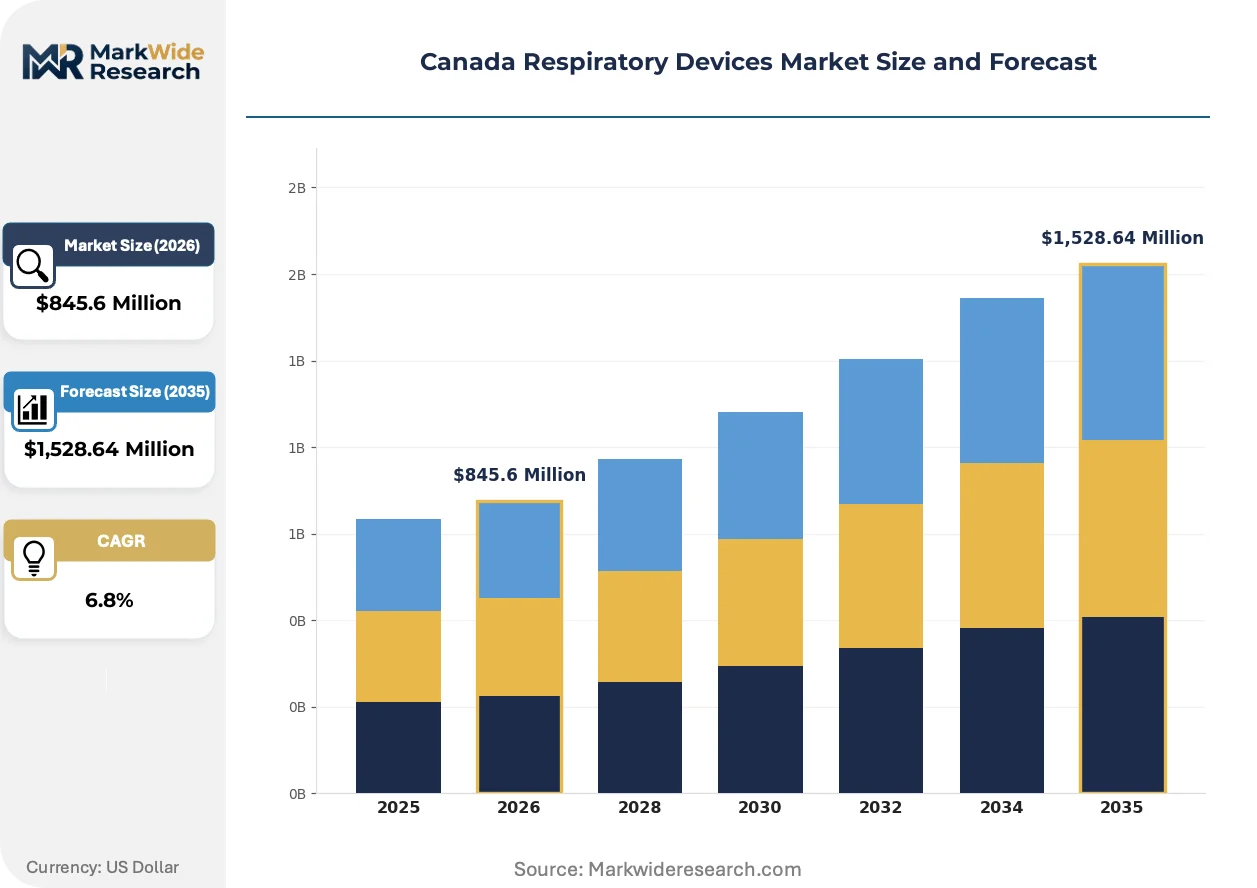
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,528.64 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Devices, Oxygen Concentrators End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Technology: Portable Devices, Digital Monitoring, Drug Delivery Systems, Mechanical Ventilators Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Other Respiratory Disorders |
| Companies Covered | Nihon Kohden Corporation, Fisher & Paykel Healthcare Limited, Koninklijke Philips N.V., Hamilton Medical AG, Dragerwerk AG & Co KGaA, Medtronic PLC, Getinge AB, Invacare Corporation, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Respiratory Devices Market Strategic Shifts
Respiratory device architecture is pivoting from standalone mechanical systems toward software-defined platforms where data capture and algorithmic therapy adjustment determine clinical and commercial differentiation.
Closed-loop oxygen titration technology is digitizing acute care workflows. These systems autonomously adjust fractional inspired oxygen delivery based on continuous pulse oximetry feedback. Intensive care units in Vancouver and Calgary are piloting installations to reduce manual nursing adjustments. The technology is digitizing staffing models by compressing respiratory therapist intervention frequency for stable hypoxemic patients.
Health Canada's evolving guidance on software-as-a-medical-device classification is reshaping pre-market submission requirements. Manufacturers must now demonstrate algorithm validation and clinical performance for machine-learning-enabled respiratory support features. Sleep apnea diagnostic platforms incorporating automated scoring algorithms face heightened scrutiny, with several submissions delayed pending additional clinical evidence packages.
Hospital procurement departments are unbundling device acquisition from service contracts. Previously bundled preventive maintenance and remote monitoring agreements are now tendered separately, enabling competitive displacement of incumbent service providers. British Columbia's Provincial Health Services Authority has pioneered this separation model, with other provincial health authorities observing outcomes before adoption.
Canada Respiratory Devices Market Segmentation
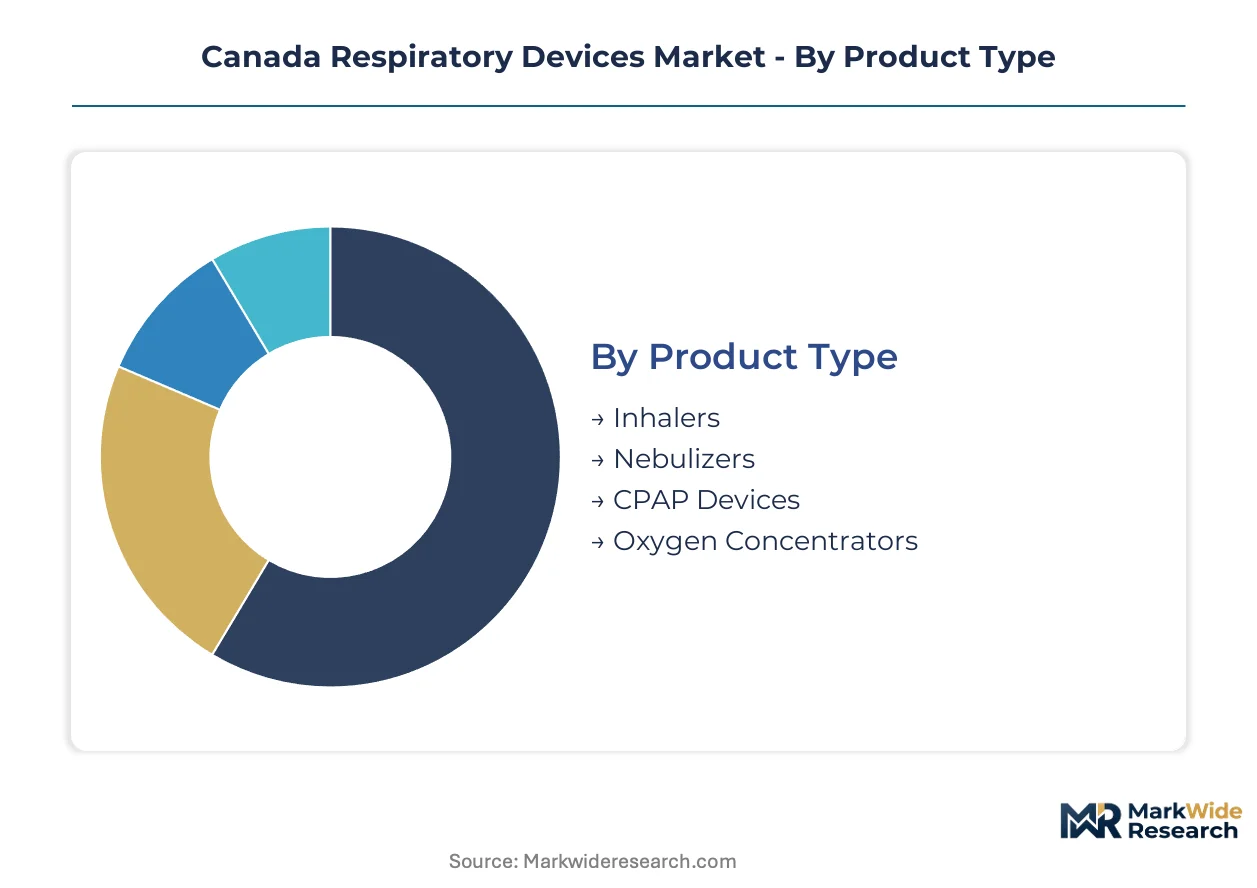
Respiratory device segmentation in Canada reflects divergent clinical workflows across acute intervention, ambulatory management, and nocturnal home therapy. Provincial reimbursement schedules and Health Canada device classifications create distinct commercial pathways for each category.
Product Type:
Device selection spans immediate symptom relief, continuous airway support, and oxygen supplementation across hospital and community settings.
- CPAP Devices:These positive airway pressure systems deliver 4-20 cm H₂O through nasal or oronasal interfaces to maintain pharyngeal patency during sleep. Ontario and Quebec sleep clinics drive procurement volumes through provincial diagnostic funding streams that mandate therapy initiation within 90 days of diagnosis.
- Oxygen Concentrators:Pressure-swing adsorption units extract medical-grade oxygen from ambient air, delivering continuous flow up to 10 L/min or pulse-dose equivalents. Home care discharge protocols in British Columbia and Alberta prioritize these devices for chronic hypoxemic patients to reduce hospital readmission penalties under provincial quality metrics.
- Inhalers:Metered-dose and dry-powder devices deliver bronchodilator and corticosteroid formulations directly to lower airways. Community pharmacies across Canada dispense these as first-line maintenance therapy for reversible airflow obstruction.
- Nebulizers:Jet and mesh aerosol generators convert liquid medication into respirable particles for patients with suboptimal inhaler technique. Pediatric emergency departments and long-term care facilities maintain these for acute bronchospasm management.
Established volume favors CPAP devices; emerging adoption favors oxygen concentrators.
End User:
Care setting determines device specification, regulatory classification, and service contract structure.
- Home Care:Patient-managed respiratory support operates outside institutional supervision, requiring simplified interfaces and remote monitoring capability. Provincial health authorities in Ontario and Quebec are expanding funding envelopes for domiciliary oxygen and non-invasive ventilation to accelerate hospital discharge.
- Hospitals:Acute care facilities demand multi-modal ventilatory support with integrated humidification and precise fraction of inspired oxygen control. Teaching hospitals in Vancouver, Calgary, and Toronto standardize procurement through regional health network tenders that specify interoperability with existing patient monitoring infrastructure.
- Long-Term Care Facilities:Institutional settings require durable equipment for residents with progressive neuromuscular or obstructive conditions. Quebec's CHSLD expansion program generates concentrated demand for cough-assist devices and non-invasive ventilation platforms.
- Clinics:Ambulatory diagnostic and titration centers perform sleep studies and oxygen assessments to qualify patients for home therapy reimbursement. Private sleep medicine practices in major metropolitan areas compete with hospital-based programs for provincial funding contracts.
Hospital procurement maintains the largest absolute spend; home care channels are climbing the fastest.
Technology:
Technology tiers separate legacy mechanical systems from connected platforms that capture adherence and physiological data.
- Digital Monitoring:Cloud-connected respiratory devices transmit usage metrics, mask leak rates, and oximetry to centralized dashboards for clinician review. Health Canada's software-as-a-medical-device guidance is extending pre-market review timelines for platforms incorporating machine-learning algorithms.
- Portable Devices:Miniaturized oxygen concentrators and travel CPAP units enable patient mobility outside domiciliary settings. Airlines operating transcontinental routes from Toronto and Vancouver are expanding onboard power specifications to accommodate these devices.
- Mechanical Ventilators:Critical care platforms provide invasive and non-invasive ventilatory modes with advanced monitoring. Provincial pandemic stockpiling programs in Ontario and Quebec established surge capacity requirements that shape current replacement cycles.
- Drug Delivery Systems:Integrated nebulizer and inhaler platforms with dose counters and electronic adherence tracking support value-based reimbursement pilots in select provincial formularies.
Mechanical ventilators command premium unit economics; digital monitoring capabilities are gaining share fastest.
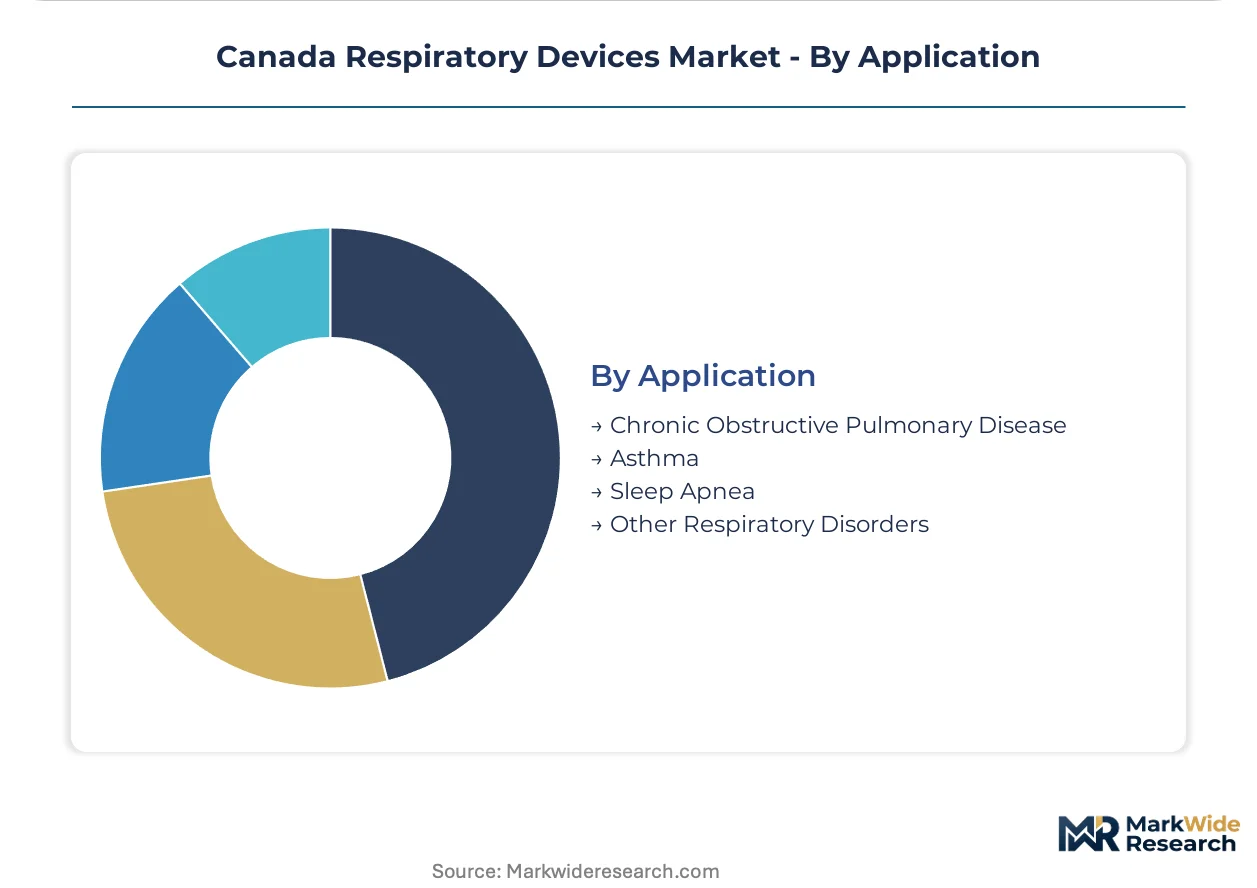
Application:
Disease-specific demand patterns align with demographic prevalence and provincial screening program coverage.
- Sleep Apnea:Obstructive and central sleep-disordered breathing conditions drive the largest addressable population for positive airway pressure therapy. Ontario's centralized sleep assessment and management program has reduced diagnostic wait times, expanding the qualified patient pool.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requires escalating intervention from bronchodilator therapy through long-term oxygen and eventually ventilatory support. Smoking cessation program funding in British Columbia and Alberta is slowing incidence growth but expanding the treated prevalent population.
- Asthma:Reversible bronchospasm management concentrates in pediatric and young adult populations with allergen or exercise triggers. School-based asthma management protocols in Ontario create institutional demand for emergency inhaler supplies.
- Other Respiratory Disorders:Interstitial lung disease, neuromuscular conditions, and post-surgical respiratory failure generate specialized device requirements. Tertiary referral centers in Toronto and Montreal coordinate multidisciplinary care for these lower-prevalence indications.
Sleep apnea captures the largest treated population; chronic obstructive pulmonary disease presents the steepest expansion trajectory as screening penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors regulatory oversight across provincial health authorities, with procurement concentration in Ontario and Quebec driving national demand patterns for respiratory equipment.
Ontario
Sleep apnea diagnostic volumes and centralized provincial purchasing alliances sustain equipment procurement across hospital networks. Ontario's sleep assessment program compresses diagnostic-to-therapy intervals, expanding qualified patient pools for positive airway pressure systems. Toronto's teaching hospitals coordinate multi-site clinical trials for connected respiratory platforms.
Quebec
CHSLD expansion programs generate institutional demand for non-invasive ventilation and cough-assist devices in long-term care settings. Provincial infrastructure investments prioritize respiratory support for aging residents with progressive neuromuscular conditions. Montreal's biomedical engineering cluster concentrates algorithm development talent for device-software integration.
British Columbia
Home care discharge protocols prioritize portable oxygen concentrators to reduce hospital readmission penalties under provincial quality metrics. The Provincial Health Services Authority pioneered unbundled device-service procurement models now observed by other jurisdictions. Vancouver's intensive care units pilot closed-loop oxygen titration technology for autonomous hypoxemia management.
Alberta
Smoking cessation program funding slows COPD incidence growth while expanding the treated prevalent population for oxygen therapy. Provincial formularies emphasize early intervention with bronchodilator therapy through community pharmacy networks. Calgary's regional health networks standardize high-flow nasal cannula protocols across acute care facilities.
Atlantic Canada
Interprovincial purchasing alliances aggregate procurement volumes for ventilator and oxygen concentrator categories across smaller provincial health systems. Aging demographic profiles in Nova Scotia and New Brunswick mirror Ontario's demand drivers at reduced absolute scale. Halifax coordinates maritime distribution logistics for respiratory equipment imports through Atlantic port infrastructure.
Canada Respiratory Devices Market Competitive Environment
Capability concentration sits with diversified medical technology conglomerates; scale advantage sits with specialized respiratory equipment manufacturers. The vendor base stratifies across three tiers: integrated critical care platform providers, sleep-disordered breathing specialists, and home care mobility device fabricators. Dominant competitive moves include portfolio diversification into software-enabled adherence monitoring and geographic expansion through provincial health authority tender participation.
Among diversified medical technology conglomerates, Medtronic PLC and Koninklijke Philips N.V. occupy positions anchoring acute care and home therapy segments respectively. Fisher & Paykel Healthcare Limited exemplifies the specialized tier, with its corporate structure reflecting focused respiratory and acute care orientation. These three entities represent distinct strategic archetypes: horizontal integration across care continuums, platform-centric sleep medicine dominance, and humidification technology specialization.
| Leading Market Players |
|---|
| Nihon Kohden Corporation |
| Fisher & Paykel Healthcare Limited |
| Koninklijke Philips N.V. |
| Hamilton Medical AG |
| Dragerwerk AG & Co KGaA |
| Medtronic PLC |
| Getinge AB |
| Invacare Corporation |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
The Port of Vancouver container corridor shapes cost dynamics across Canadian respiratory device distribution, with Pacific freight rates feeding into both supply concentration among East Asian component manufacturers and downstream price differentiation between hospital procurement tiers and home care channels.
Pricing Analysis
Ontario and Quebec procurement alliances command price spreads that narrow margins for standard oxygen concentrators while preserving premiums for digitally integrated CPAP platforms. Pricing stratifies across premium, standard, and economy tiers based on Health Canada Class IV certification status and bundled remote monitoring service contracts. Cost compression in economy-tier nebulizers is intensifying because of Pan-Canadian Pharmaceutical Alliance joint tendering. Hospital purchasing committees demonstrate lowest price sensitivity; home care patients and long-term care facilities face highest budget constraints.
Supply Chain Analysis
Medical-grade polycarbonate and silicone elastomer feedstock costs fluctuate with petrochemical indices, exposing Canadian device assemblers to input volatility. Component sourcing concentrates in China, Taiwan, and South Korea for flow sensors, pressure transistors, and microcontroller units. Single-source vulnerability sits with semiconductor foundries serving respiratory algorithm processing modules. Distribution runs through provincial health authority central warehouses and specialized durable medical equipment dealers with Health Canada establishment licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected adherence monitoring and preventive maintenance contracts expand faster than hardware unit sales, positioning service-attach revenue as the primary margin expansion vector for stakeholders across the Canadian respiratory device ecosystem.
For Market Incumbents: Entrench market position through backward integration into humidification circuit manufacturing and exclusive service contracts with Ontario regional health networks. Emerging software-as-a-medical-device entrants threaten diagnostic platform incumbents through automated scoring algorithms. Certification investment in Health Canada machine-learning validation pathways represents the critical defensive lever. For New Entrants and Emerging Players: Pursue white-space opportunities in Quebec CHSLD non-invasive ventilation procurement and Atlantic Canada interprovincial purchasing alliance participation. Long-term care facilities present the most penetrable institutional segment given infrastructure expansion timelines. Go-to-market execution should anchor on respiratory therapist training partnerships and simplified interface design for elderly patient populations. For Investors and Strategic Acquirers: Specialized humidification technology developers with established Canadian teaching hospital relationships command premium valuation multiples given limited domestic R&D talent concentration. Long-term viability over the coming decade hinges on software-enabled platform transitions rather than standalone mechanical device manufacturing. Watch Health Canada software-as-a-medical-device submission volumes as the inflection signal for algorithmic therapy platform adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class IV Submission | Accelerates market authorization for high-risk ventilatory support platforms in acute care settings. |
| Provincial GPO Partnership | Secures multi-year equipment placement through Ontario and Quebec centralized purchasing alliances. |
| Software Companion Development | Enables reimbursement capture under emerging provincial codes for digital respiratory coaching applications. |
| Remote Monitoring Integration | Aligns with British Columbia's unbundled procurement model separating device acquisition from service contracts. |
| Reimbursement Strategy | Optimizes provincial formulary positioning for home oxygen and sleep apnea therapy funding streams. |
Study Parameters
Operator-level perspectives from hospital biomedical engineers, provincial GPO contracts managers, respiratory therapists, and home care equipment coordinators anchored the qualitative base. Primary interviews combined with secondary validation against Health Canada Medical Devices Active Licence Listing database, provincial health authority procurement records, and Canadian Standards Association technical bulletins. Bottom-up installed base estimates and top-down provincial health spending allocations were triangulated to establish market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, end user channel, technology tier, and application indication. CAGRs were derived from trend-line extrapolation of historical provincial procurement volumes adjusted for demographic shift projections and reimbursement policy trajectories. Forecast inputs incorporated Health Canada approval pipeline velocity and interprovincial purchasing alliance tender schedules.
Macroeconomic conditions sit as an overlay; deviation in CAD-USD exchange rates, petrochemical feedstock indices, or semiconductor foundry capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding provincial health spending growth continuity and regulatory pathway stability. Cross-checking against Canadian Institute for Health Information expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Cyclotron Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Nephrostomy Catheters Market