
 US Medical Bionic Implants & Artificial Organs Market | 2026-2036
US Medical Bionic Implants & Artificial Organs Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Bionic Implants & Artificial Organs Market Insights
US manufacturing capacity for titanium-machined implant components is tilting toward domestic foundries and precision machining clusters. Medtronic plc anchors its cardiac rhythm portfolio through captive supply chains for pacemaker leads and enclosures. Cochlear Limited differentiates through sustained R&D intensity in electrode array miniaturization for hearing restoration devices. Zimmer Biomet competes by leveraging its orthopedic implant scale across hip, knee, and extremity reconstructions.
Medical bionic implants and artificial organs comprise electromechanical devices and synthetic biological constructs designed to replace or augment native physiological functions, typically fabricated from titanium alloys, silicone elastomers, or biocompatible polymers with feature tolerances below 50 microns for neural and cardiovascular interfaces. These systems restore sensory perception, motor control, or organ-level homeostasis in patients with congenital deficits, trauma-induced loss, or degenerative pathologies. Pacemakers and cochlear implants represent mature revenue pools with established reimbursement, while artificial organs and prosthetic limbs with integrated robotics command premium positioning due to technical complexity and limited supplier bases. Bioprinting and nanotechnology segments attract development capital fastest, though regulatory validation timelines for tissue-engineered constructs remain extended relative to electromechanical alternatives.
FDA premarket approval pathways and CMS national coverage determinations govern market access timelines and reimbursement eligibility for implantable devices across US territories. OSHA workplace safety standards and state-level certificate-of-need regulations further shape deployment economics for surgical programs in hospital systems. Stakeholders must monitor evolving FDA guidance on brain-computer interfaces and artificial heart durability benchmarks to anticipate competitive repositioning requirements.
Market Dynamics
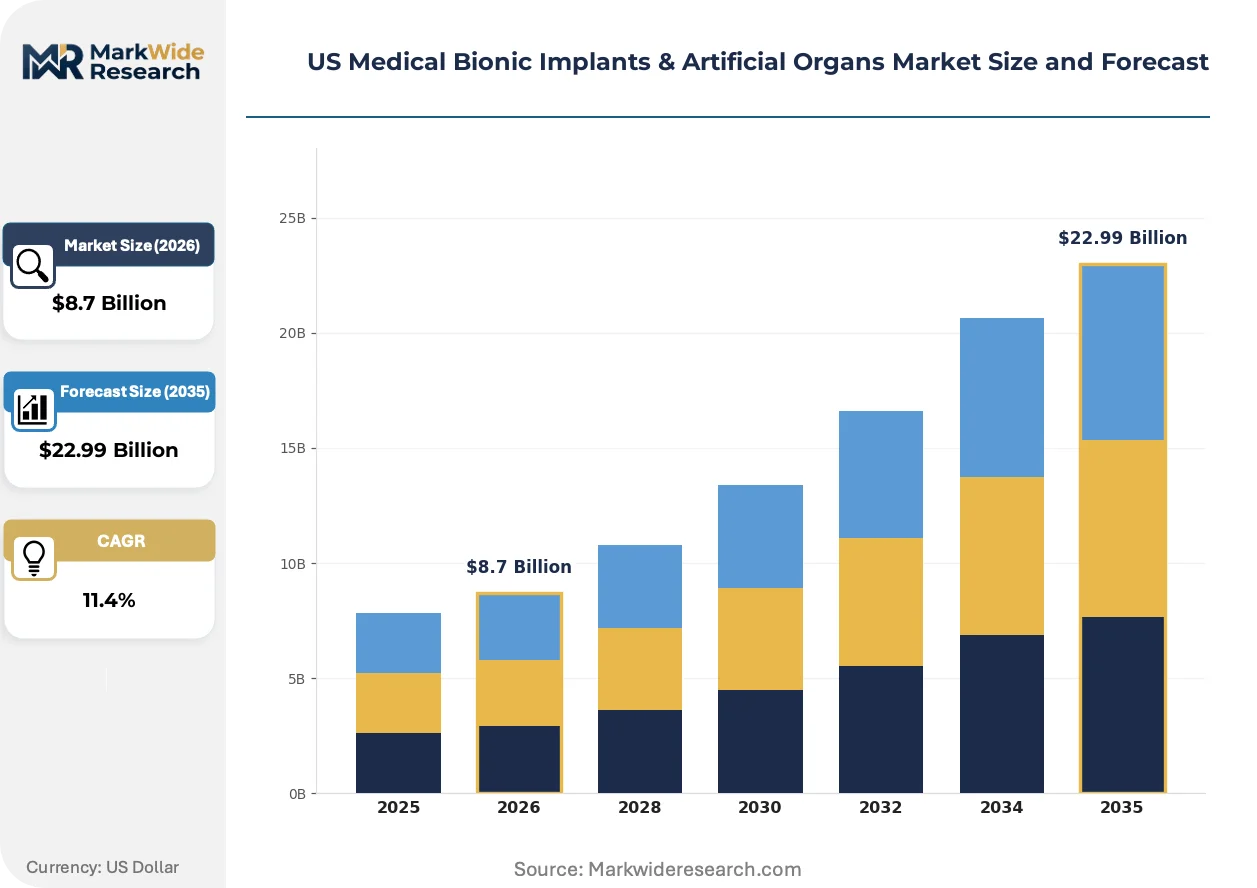
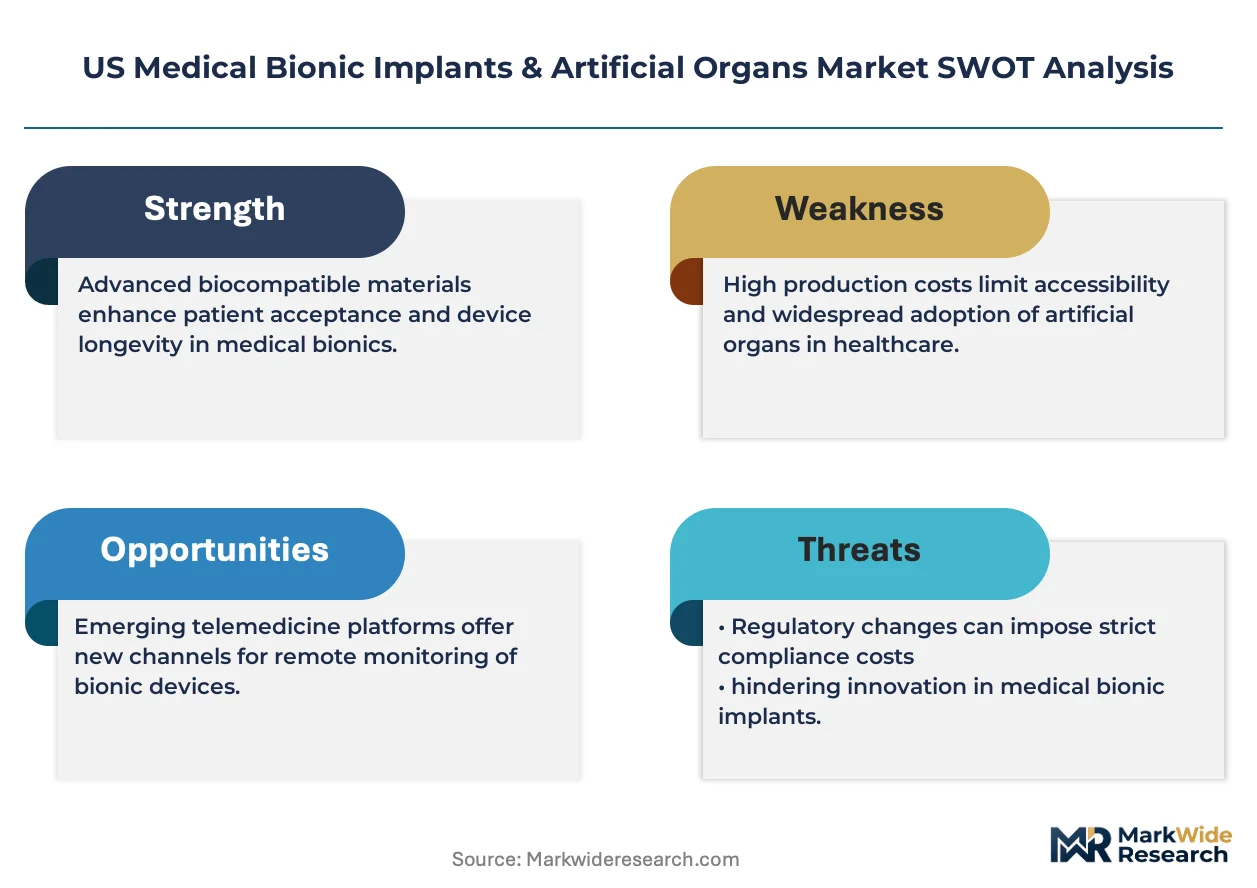
FDA breakthrough device designations and CMS reimbursement pathway expansions are compressing commercialization timelines for neural interfaces and total artificial hearts, pulling capital toward preclinical-stage bioprinting ventures.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement eligibility for ventricular assist devices accelerates hospital procurement cycles in cardiac surgery centers.
- Titanium machining clusters:Domestic foundry capacity expansion in Ohio and Michigan reduces lead times for orthopedic implant enclosures.
- Brain-computer interface protocols:FDA guidance drafts on neural signal acquisition standards de-risk early-stage electrode array development.
Market Restraints
- Platinum-iridium alloy concentration:Single-source dependency for pacemaker electrode materials exposes pricing volatility to South African mining output fluctuations.
- Premarket approval timelines:FDA PMA pathway averages 18-36 months for novel artificial organs, freezing venture deployment until clinical endpoints resolve.
- Bioprinted tissue durability gaps:Vascularized organ constructs fail to match mechanical device longevity benchmarks, limiting addressable patient populations.
Strategic Opportunities
- Texas medical corridor expansion:Houston and Dallas-Fort Worth hospital systems underindex in bionic limb procurement relative to population density.
- OSHA-mandated workplace accommodation:Upper-limb prosthetic coverage requirements for industrial injury cases expand employer-funded device channels.
- Silicone-elastomer microfluidics convergence:Soft robotics integration with neural cuffs enables closed-loop sensory feedback in next-generation prosthetics.
Industry Challenges
- Electrophysiology firmware certification:FDA software-as-medical-device validation requirements extend engineering timelines for implantable pulse generators.
- Cleanroom assembly capacity:ISO 14644 Class 7 facility scarcity constrains scaling for electrode array manufacturers.
- Interoperability standards fragmentation:Proprietary wireless telemetry protocols between implants and external controllers complicate multi-vendor system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Bionic Implants & Artificial Organs Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Cochlear Implants, Prosthetic Limbs, Artificial Organs Material: Silicone, Titanium, Biocompatible Polymers, Metal Alloys End User: Hospitals, Rehabilitation Centers, Home Care, Surgical Clinics Technology: Robotics, Nanotechnology, Bioprinting, Remote Monitoring |
| Companies Covered | Cochlear Limited, Zimmer Biomet, Medtronic plc, Sonova, Abiomed, Boston Scientific Corporation, Edwards Lifesciences Corporation, Ekso Bionics, Össur, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Bionic Implants & Artificial Organs Market Trends and Innovations
Neural decoding algorithms and additive manufacturing protocols are compressing the gap between laboratory demonstration and clinical deployment for sensory restoration devices.
Additive manufacturing of patient-specific titanium lattice structures is collapsing the traditional tooling-to-implant production cycle from 12 weeks to under 72 hours. Orthopedic surgery departments at Cleveland Clinic and Mayo Clinic are piloting point-of-care machining cells for complex revision arthroplasty cases. This compression is eliminating inventory carrying costs for oversized implant libraries while enabling anatomically matched reconstructions previously deemed unmanufacturable.
FDA draft guidance on brain-computer interface safety and effectiveness testing establishes predicate device pathways for cortical electrode arrays. The framework mandates chronic biocompatibility studies and wireless cybersecurity validation, extending premarket submission requirements. Neural implant developers are responding by front-loading GLP toxicology programs and embedding encryption modules during early prototyping phases.
Hospital value analysis committees now require five-year total cost-of-ownership projections for implantable devices, unbundling hardware acquisition from surgical training and remote monitoring subscriptions. This recalibration favors vendors offering predictive maintenance algorithms and outcome warranty structures. The shift is most pronounced in California integrated delivery networks, where procurement contracts increasingly index payments to mobility restoration metrics for lower-limb prosthetics.
US Medical Bionic Implants & Artificial Organs Market Segmentation
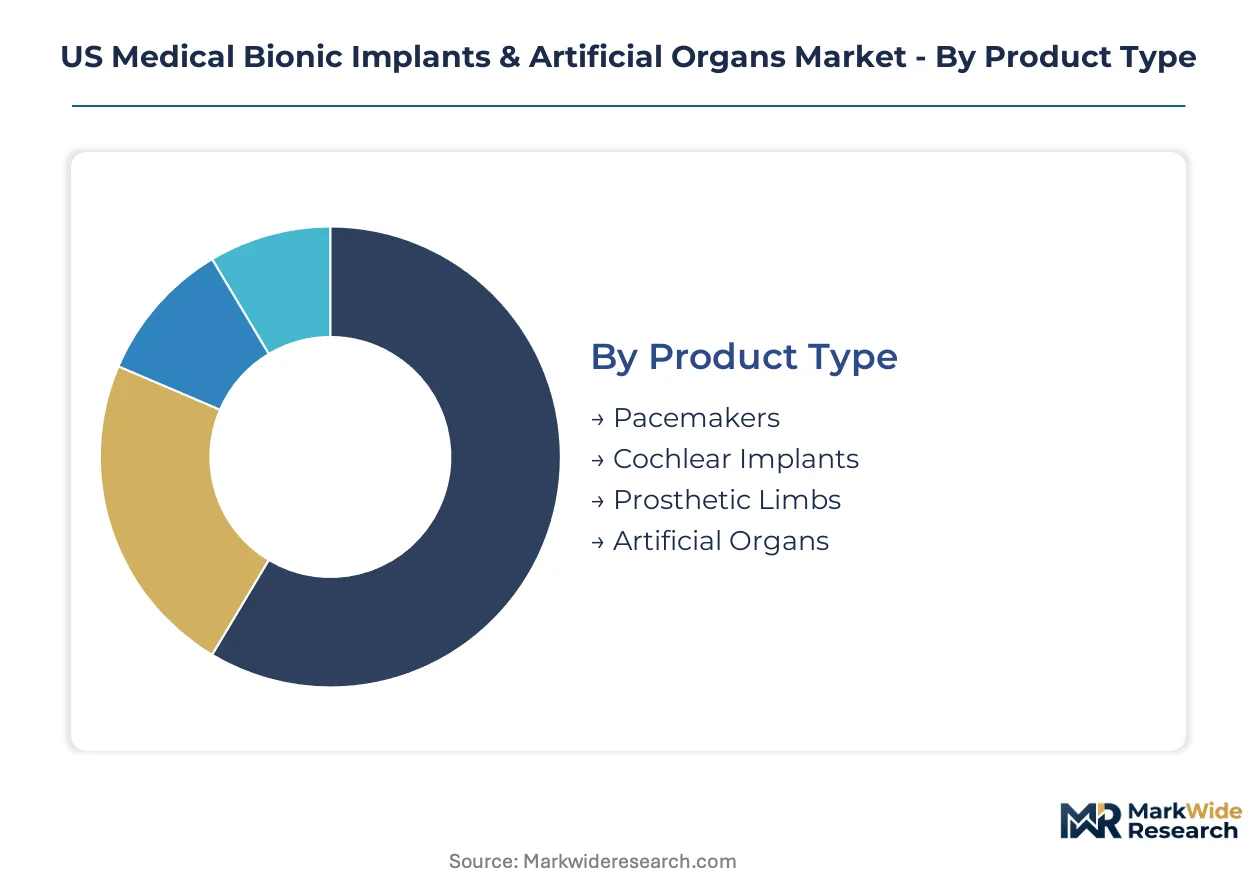
Segmentation in the US medical bionic implants market reveals distinct procurement patterns across cardiac, sensory, and motor restoration applications. Hospital value analysis committees evaluate each category through separate total cost-of-ownership frameworks, with reimbursement eligibility varying sharply by CMS national coverage determination status.
Product Type:
Use-case spectrum spans chronic disease management through acute trauma reconstruction, with each product category commanding distinct FDA pathway timelines and hospital integration requirements.
- Pacemakers:Electromechanical pulse generators fabricated from titanium enclosures with lithium-iodine power cells restore cardiac rhythm in bradycardia patients. Demand concentrates in metropolitan cardiac surgery centers across Texas and the Northeast corridor, with CMS reimbursement stability supporting predictable procurement cycles.
- Cochlear Implants:Electrode arrays surgically implanted in the cochlea bypass damaged hair cells to stimulate the auditory nerve directly. Pediatric adoption drives volume in California integrated delivery networks, where early intervention protocols align with FDA-approved expanded indications for bilateral implantation.
- Prosthetic Limbs:Myoelectric and body-powered devices replace upper and lower extremity function following trauma or congenital absence.
- Artificial Organs:Total artificial hearts and ventricular assist devices provide circulatory support as bridge-to-transplant or destination therapy.
Established volume favors pacemakers; emerging adoption favors artificial organs.
Material:
Material selection determines biocompatibility certification requirements, machining tolerances, and supply chain concentration for implantable device manufacturers.
- Titanium:Grade 5 titanium alloys machined to sub-50-micron tolerances form structural enclosures for cardiac and orthopedic implants. Domestic foundry capacity expansion in Ohio and Michigan is compressing lead times for hospital procurement.
- Silicone:Medical-grade elastomers enable flexible electrode insulation and soft-tissue interfaces in neural and cochlear arrays. Demand is climbing fastest in brain-computer interface development programs.
- Biocompatible Polymers:PEEK and UHMWPE bearing surfaces reduce wear debris in joint reconstructions.
- Metal Alloys:Cobalt-chrome and platinum-iridium compositions serve specialized electrochemical and radiopaque applications.
Titanium anchors current revenue; silicone-elastomer microfluidics integration represents the steepest expansion trajectory.
End User:
Procurement authority and reimbursement pathway complexity fragment demand across institutional settings with varying surgical volume and capital equipment requirements.
- Hospitals:Academic medical centers and community hospital systems perform the majority of implantation procedures requiring general anesthesia and intensive care unit admission. California, Texas, and Northeast corridor networks account for disproportionate device procurement.
- Rehabilitation Centers:Post-acute facilities manage prosthetic fitting and neurorehabilitation for limb and sensory restoration patients.
- Home Care:Remote monitoring infrastructure enables discharge with external controllers and telemetry systems.
- Surgical Clinics:Ambulatory surgery centers handle select cochlear and minor orthopedic implant procedures.
Hospital systems capture procedural revenue concentration; home care channels are gaining share fastest through remote monitoring integration.
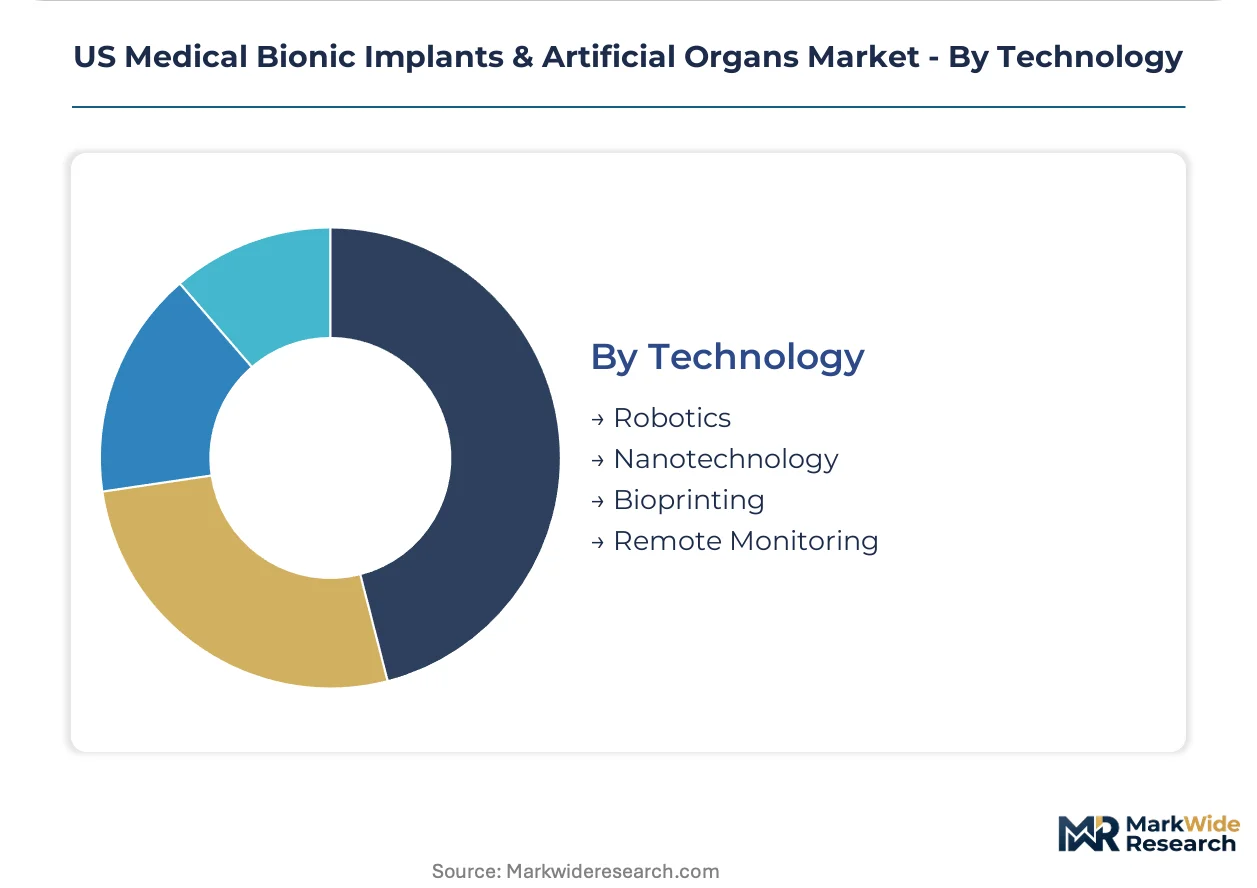
Technology:
Technology maturity determines regulatory validation burden and capital intensity for product development pipelines.
- Remote Monitoring:Wireless telemetry systems transmit implant performance data to clinical decision support platforms. FDA cybersecurity guidance is extending engineering timelines for encrypted data transmission modules.
- Robotics:Integrated servo motors and sensor arrays enable closed-loop control in advanced prosthetic limbs.
- Nanotechnology:Surface modifications and drug-eluting coatings enhance biocompatibility and infection resistance.
- Bioprinting:Additive manufacturing of vascularized tissue constructs targets organ replacement applications.
Remote monitoring commands near-term deployment; bioprinting holds the longest development runway pending durability validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulatory frameworks and CMS reimbursement pathways anchor demand concentration across US hospital systems. Metropolitan networks in California, Texas, and the Northeast corridor capture disproportionate procurement volume for cardiac and orthopedic bionic implants. State-level certificate-of-need regulations and OSHA workplace safety standards further shape deployment economics for surgical programs.
California
Pediatric cochlear implant adoption and integrated delivery network procurement drive volume in Los Angeles and San Francisco Bay Area corridors. Medi-Cal expansion and commercial payer coverage mandates accelerate bilateral implantation protocols. Stanford and UCLA medical centers anchor neural interface development clusters with FDA breakthrough device trial participation.
Texas
Houston and Dallas-Fort Worth hospital systems underindex in bionic limb procurement relative to population density, creating expansion headroom. Texas Medical Center cardiac surgery programs command ventricular assist device destination therapy volume. State-level tort reform reduces malpractice exposure for novel artificial organ surgical programs.
Northeast Corridor
Massachusetts General and New York-Presbyterian networks concentrate pacemaker and defibrillator implantation volume. FDA headquarters proximity accelerates pre-submission meeting cadence for PMA pathway sponsors. Boston-Cambridge medtech corridor hosts electrode array miniaturization foundries and GLP toxicology contract research organizations.
Midwest
Cleveland Clinic and Mayo Clinic orthopedic departments pilot point-of-care titanium machining cells for revision arthroplasty. Ohio and Michigan foundry capacity expansion reduces implant enclosure lead times. CMS national coverage determination stability supports predictable procurement budgeting across Michigan Medicine and Northwestern Memorial networks.
Pacific Northwest
Seattle and Portland rehabilitation centers specialize in upper-limb myoelectric prosthetic fitting for industrial injury cases. OSHA-mandated workplace accommodation enforcement expands employer-funded device channels. University of Washington neural engineering programs supply talent to brain-computer interface startups with FDA early feasibility study designations.
US Medical Bionic Implants & Artificial Organs Market Competitive Landscape
Capability concentration sits with specialized electrode array and soft-tissue interface developers; scale advantage sits with diversified cardiovascular and orthopedic implant manufacturers. The vendor base stratifies across three tiers: integrated conglomerates with captive supply chains, mid-cap specialists with single-technology depth, and venture-stage bioprinting ventures awaiting durability validation. Dominant competitive moves include backward integration into titanium machining capacity and strategic partnerships with academic medical centers for clinical trial site designation.
Among diversified cardiovascular and orthopedic manufacturers, Medtronic plc, Zimmer Biomet, and Cochlear Limited occupy distinct archetype positions. Medtronic exemplifies the integrated conglomerate model with captive supply chain control over pacemaker component fabrication. Zimmer Biomet represents scale-driven orthopedic implant manufacturing across joint reconstruction categories. Cochlear Limited anchors the specialized sensory restoration tier with sustained electrode array miniaturization focus. These three entities collectively illustrate the capability-scale tradeoff governing competitive positioning in FDA-regulated implantable device markets.
| Leading Market Players |
|---|
| Cochlear Limited |
| Zimmer Biomet |
| Medtronic plc |
| Sonova |
| Abiomed |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Ekso Bionics |
| Össur |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic titanium foundries is compressing supplier margins while amplifying pricing power for precision-machined implant enclosures. Ohio and Michigan machining clusters are running at elevated utilization, forcing orthopedic manufacturers to accept longer lead times or premium surcharges for Grade 5 titanium alloy components.
Pricing Analysis
Metropolitan hospital networks in California command lower per-unit pricing than Texas systems due to integrated delivery network purchasing scale and GPO contract aggregation. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated neural interfaces from legacy pacemaker platforms and commodity orthopedic hardware. Cost compression in standard-tier cardiac rhythm devices is intensifying because of concentrated buyer consolidation among Catholic health systems. Safety-net hospitals exhibit acute price sensitivity, while academic medical centers prioritize outcome-linked warranty structures over acquisition cost.
Supply Chain Analysis
Platinum-iridium feedstock draws from South African mining output and Russian refining capacity, creating single-source vulnerability for pacemaker electrode manufacturers. Titanium sponge sources from Japan and Kazakhstan, while silicone elastomer precursors feed from German chemical specialists and US Gulf Coast petrochemical complexes. Tariff exposure on Chinese-sourced rare-earth magnets for prosthetic servo motors threatens cost stability in robotics-integrated limb systems. Distribution runs through specialized medical device distributors with ISO 13485 certification rather than general healthcare logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level certificate-of-need regulations and CMS coverage determination timelines is spawning addressable niches for specialized players. Hospital value analysis committee proliferation is fragmenting procurement authority, creating entry points for outcome-guarantee business models.
For Market Incumbents: Entrench position by capturing captive titanium machining capacity in Ohio and Michigan before foundry utilization peaks strain component availability. Deepen backward integration into electrode array cleanroom assembly to offset ISO 14644 Class 7 facility scarcity constraining competitor scaling. Prioritize FDA pre-submission meeting cadence acceleration through Boston-Cambridge regulatory consulting clusters to compress PMA pathway timelines against emerging bioprinting ventures. For New Entrants and Emerging Players: Texas medical corridor underpenetration in bionic limb procurement relative to population density offers white-space expansion without incumbent saturation. Target OSHA-mandated workplace accommodation channels for upper-limb myoelectric devices in Pacific Northwest industrial injury cases, where employer-funded procurement bypasses traditional reimbursement friction. Lead with silicone-elastomer microfluidics convergence demonstrations to differentiate against legacy body-powered prosthetic architectures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA breakthrough device designation velocity and CMS national coverage determination expansions are compressing commercialization timelines for preclinical-stage ventures. Acquisition focus should center on electrode array miniaturization specialists with GLP toxicology program front-loading and embedded cybersecurity module prototyping. Watch FDA draft guidance finalization on brain-computer interface safety benchmarks as the inflection signal for neural implant valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for neural interfaces and total artificial hearts through prioritized review. |
| CMS National Coverage Determination Expansion | Unlocks reimbursement eligibility for ventricular assist devices in cardiac surgery centers. |
| Hospital System Partnership | Stanford and UCLA anchor clinical trial site designation for neural interface development clusters. |
| Software Companion Development | Predictive maintenance algorithms satisfy California IDN requirements for five-year total cost-of-ownership projections. |
| Reimbursement Strategy | Outcome warranty structures align with value analysis committee indexing to mobility restoration metrics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket approval databases, CMS national coverage determination records, and hospital procurement contract filings. Interviews with cardiac surgeons, biomedical engineers, GPO contracts managers, and hospital purchasing committee members informed demand-side validation. Secondary sources include SEC 10-K disclosures from listed device manufacturers, ISO certification registries, and trade data on titanium alloy imports. Bottom-up implant volume modeling triangulates against top-down market value reconstruction.
Forecast inputs span product type segmentation across pacemakers, cochlear implants, prosthetic limbs, and artificial organs; material categories from titanium alloys to silicone elastomers; and technology tiers including remote monitoring, robotics, nanotechnology, and bioprinting. End-user segmentation captures hospitals, rehabilitation centers, home care channels, and surgical clinics. CAGRs derive from logistic diffusion modeling of reimbursement pathway expansion and foundry capacity utilization trajectories. Input assumptions incorporate FDA guidance draft progression and CMS coverage determination velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-stage bioprinting ventures with FDA early feasibility study designations would shift outcomes through accelerated durability validation. Unanticipated platinum-iridium supply disruption or OSHA workplace accommodation mandate expansion would revise trajectory. Quarterly review of FDA pre-submission meeting schedules, CMS national coverage determination dockets, and domestic titanium foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Gamma Knife Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Active Wheelchair Market
Medical Devices
Toe Fixation System Market
Medical Devices
Knee Braces Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Next Generation Implants (NGI) Market