
 Global Peripheral Stent Market | 2026-2036
Global Peripheral Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peripheral Stent Market Outlook
A capital-intensity divergence between integrated manufacturers and component assemblers is redrawing competitive boundaries in peripheral stents. Abbott Laboratories leverages captive nitinol supply chains to sustain margin resilience against raw material volatility. Boston Scientific Corporation anchors its position through differentiated laser-cutting capabilities that competitors struggle to replicate at equivalent throughput.
Peripheral stents are tubular metallic or polymeric scaffolds, typically manufactured from nitinol or cobalt-chromium alloys via laser machining, designed to maintain patency in femoropopliteal, iliac, or renal arteries compromised by atherosclerotic disease. Drug-eluting platforms command premium positioning due to sustained-release formulations that suppress neointimal hyperplasia, while self-expanding configurations dominate superficial femoral artery applications where vessel flexibility demands conformability. Ambulatory surgical centers represent the fastest-growing end-user channel as reimbursement migration and catheter-based technique standardization enable same-day discharge protocols.
The FDA enforces rigorous biocompatibility and fatigue testing standards under 21 CFR 820 quality system regulations, while the EU Medical Device Regulation mandates clinical evidence thresholds that extend market access timelines for novel platforms. Japan's PMDA imposes additional pharmacokinetic scrutiny on drug-eluting variants that manufacturers must navigate for Asian market entry. Stakeholders should monitor evolving real-world evidence requirements as payers increasingly predicate coverage on comparative effectiveness data rather than premarket trial endpoints alone.
Market Dynamics
FDA fatigue-testing mandates for nitinol-based devices are compressing development timelines while elevating capital barriers for new entrants, fundamentally restructuring competitive boundaries around in-house metallurgical capabilities.
Growth Catalysts
- Medicare reimbursement migration:United States federal payment policies now favor endovascular peripheral revascularization performed in ambulatory surgical centers, accelerating same-day discharge protocols.
- Drug-eluting platform maturation:Sustained-release formulations that suppress neointimal hyperplasia command premium positioning across femoropopliteal applications.
- Japan PMDA pharmacokinetic pathways:Streamlined scrutiny timelines for drug-eluting variants enable faster Asian market entry for compliant manufacturers.
Market Restraints
- Nitinol supply concentration:Captive supply chains dominate raw material access, locking out component assemblers from margin resilience against alloy price volatility.
- EU MDR clinical evidence thresholds:Extended market access timelines for novel platforms compress investment return windows for European-focused developers.
- Bare-metal substitution pressure:Cost-conscious hospital procurement in emerging markets favors conventional stents despite inferior patency outcomes.
Strategic Opportunities
- Brazil ANVISA harmonization:Regulatory alignment with FDA standards creates expedited pathway for approved United States devices into Latin American markets.
- Renal artery underpenetration:Atherosclerotic renal disease applications remain underserved relative to femoropopliteal volumes, offering white-space expansion.
- Polymeric bioresorbable convergence:Magnesium alloy scaffolds combined with bioabsorbable polymer coatings enable temporary scaffolding without permanent implant risks.
Industry Challenges
- Laser-cutting talent scarcity:Precision machining expertise for cobalt-chromium and nitinol stent geometries concentrates among a handful of specialized engineering clusters.
- 21 CFR 820 compliance capex:Enhanced fatigue-testing infrastructure demands substantial facility investment before commercialization.
- ISO 25539-2 certification timelines:Vascular stent-specific standard verification extends quality system implementation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peripheral Stent Market |
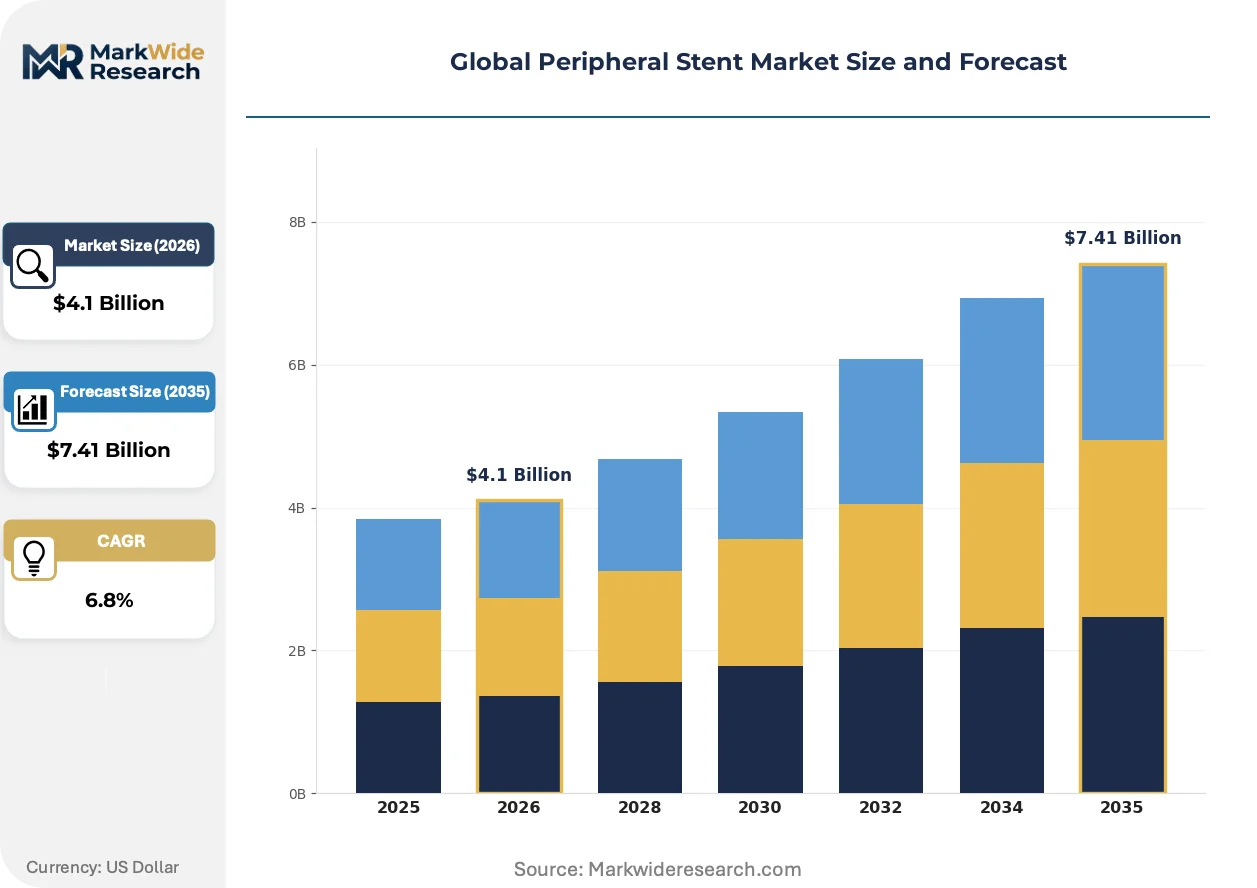
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Stented, Self-Expanding, Drug-Eluting, Bio-Absorbable End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Academic Institutions Delivery Mode: Open Surgery, Endovascular, Minimally Invasive, Hybrid Approach Application: Cardiology, Vascular Surgery, Gastroenterology, Peripheral Vascular Disease |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Terumo Corporation, B. Braun SE, Becton Dickinson and Company, W.L. Gore & Associates, Cook Group, Biotronik SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peripheral Stent Market Strategic Shifts
Material science advances and regulatory science evolution are compressing traditional product lifecycles while opening differentiation vectors beyond bare-metal mechanical performance.
Thin-strut cobalt-chromium alloys with improved radial strength-to-profile ratios are supplanting conventional nitinol in iliac and renal applications where precise deployment control matters. Interventional cardiologists in high-volume United States academic medical centers have accelerated adoption over the past eighteen months. This material transition is enabling smaller-profile delivery systems that expand treatable patient anatomies previously excluded from endovascular approaches.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic real-world evidence collection across all risk classes. Manufacturers must maintain active implant registries with minimum five-year follow-up protocols. Drug-eluting platforms face the steepest compliance burden, with notified bodies demanding pharmacokinetic modeling that extends technical documentation preparation by eight to fourteen months.
Ambulatory surgical centers now negotiate directly with manufacturers for stent-procedure bundles that unbundle traditional hospital markup structures. United States freestanding endovascular clinics in Florida, Texas, and Arizona lead this procurement model transformation. Facility administrators prioritize predictable per-procedure costs over capital-equipment relationships that historically locked purchasing decisions to cath-lab vendor ecosystems.
Global Peripheral Stent Market Segmentation
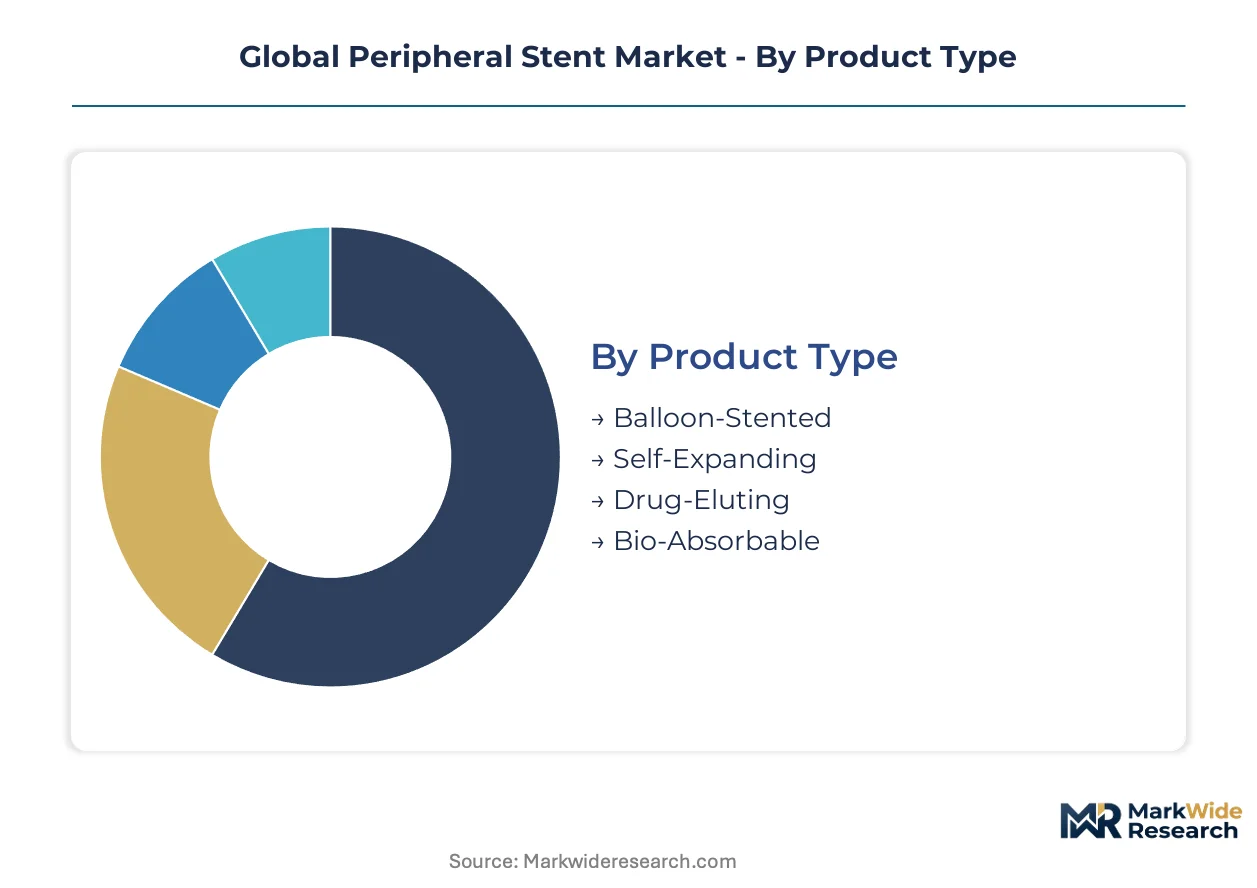
Segmentation in peripheral stents reveals how clinical workflow preferences and reimbursement pathways fragment demand across delivery settings and procedural approaches. Understanding these divides exposes where pricing power concentrates versus where commoditization pressures mount.
Product Type:
Domestic production clusters in the United States and Germany dominate balloon-stented and self-expanding platforms, while drug-eluting variants flow through specialized export channels into Asian markets.
- Balloon-Stented:Stainless steel or cobalt-chromium scaffolds mounted on balloon catheters deploy via controlled inflation for precise diameter achievement in iliac arteries. Demand concentrates in German hospital systems where statutory reimbursement favors established mechanical platforms over premium alternatives.
- Drug-Eluting:Polymer matrices containing paclitaxel or sirolimus coat nitinol substrates to suppress neointimal proliferation in femoropopliteal segments. Japanese PMDA pharmacokinetic pathways and United States Medicare coverage expansion accelerate adoption in academic medical centers pursuing patency superiority.
- Self-Expanding:Nitinol superelasticity enables crush recovery in superficial femoral artery applications.
- Bio-Absorbable:Magnesium alloy scaffolds with polymeric coatings enable temporary support without permanent implant risks.
Drug-eluting platforms hold the largest share; momentum sits with bio-absorbable development pipelines.
End User:
Cost tier stratification separates capital-intensive hospital systems from lean ambulatory operators pursuing per-procedure margin optimization.
- Hospitals:Integrated cath-lab infrastructure and 24-hour interventional coverage support complex multi-vessel cases requiring staged revascularization. United States academic medical centers in Massachusetts and California anchor volume concentration through fellowship training programs that standardize device selection protocols.
- Ambulatory Surgical Centers:Freestanding endovascular clinics in Florida, Texas, and Arizona negotiate direct manufacturer bundles that bypass traditional hospital markup structures. Same-day discharge protocols and Medicare site-neutral payment policies expand treatable patient anatomies previously excluded from outpatient settings.
- Specialty Clinics:Cardiovascular-focused outpatient facilities concentrate elective diagnostic and interventional volume.
- Academic Institutions:Teaching hospitals balance clinical service with device trial enrollment and fellow training mandates.
Hospitals retain volume dominance; ambulatory surgical centers are expanding most quickly.
Delivery Mode:
Application maturity separates established endovascular workflows from hybrid approaches still defining reimbursement and training standards.
- Endovascular:Catheter-based deployment through femoral or radial access avoids open surgical exposure, reducing recovery intervals and complication profiles. United States freestanding clinics and German outpatient centers drive standardization through high-volume operator experience and streamlined pre-procedural protocols.
- Hybrid Approach:Combined open surgical exposure with endovascular completion addresses complex anatomies—chronic total occlusions, heavily calcified vessels, or prior bypass graft failure—that pure percutaneous techniques cannot resolve. Tertiary referral centers in Texas, Ohio, and Bavaria concentrate this capability through multidisciplinary vascular surgery teams.
- Open Surgery:Direct arterial exposure with surgical endarterectomy or bypass grafting persists for failed endovascular candidates.
- Minimally Invasive:Percutaneous techniques with reduced sheath sizes and closure device advancement enable early ambulation.
Endovascular commands the largest share; hybrid approaches are gaining share fastest among complex case referrals.
Application:
Customer type differentiation separates high-volume vascular surgery programs from cardiology services cross-training into peripheral territory.
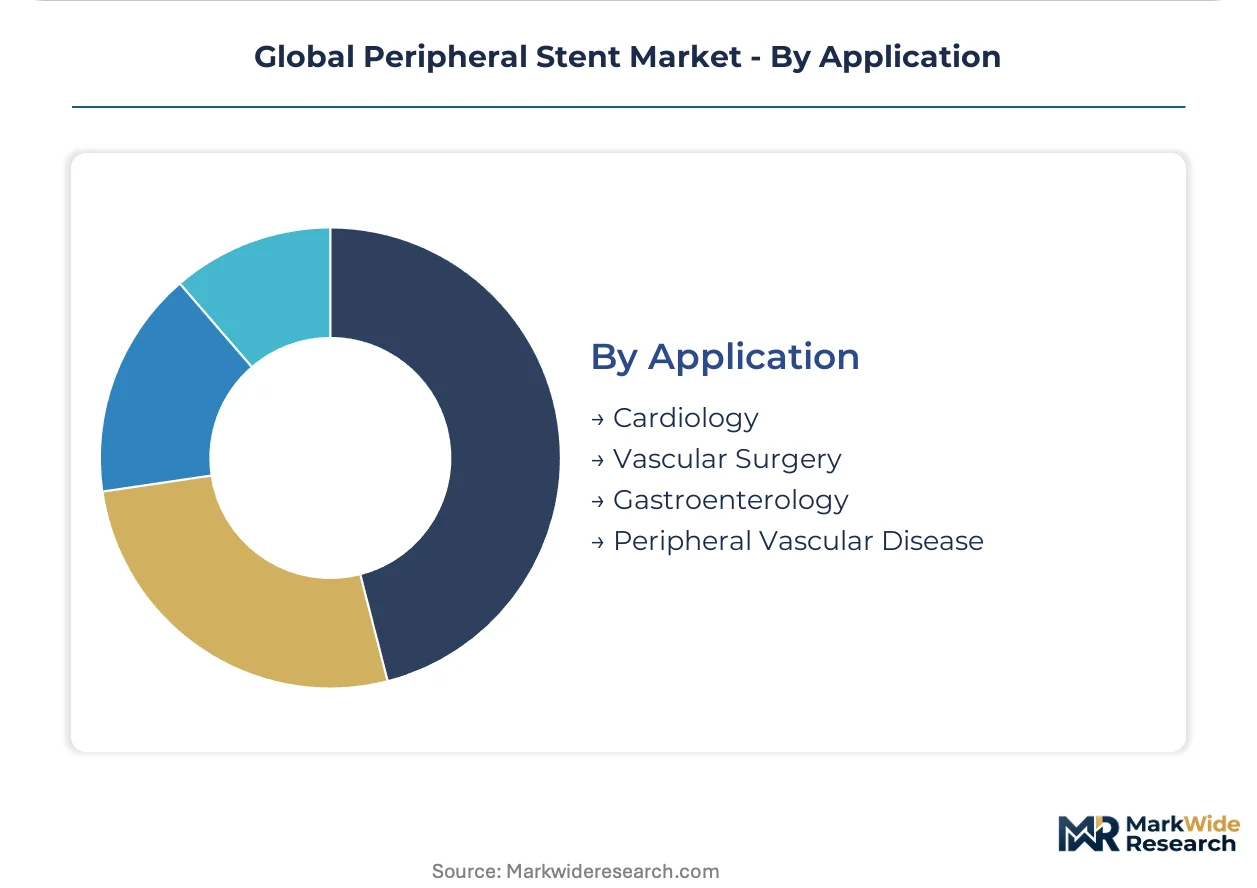
- Peripheral Vascular Disease:Atherosclerotic obstruction of femoropopliteal, iliac, or infrapopliteal arteries drives the core indication base for self-expanding and drug-eluting platforms. United States Medicare beneficiary demographics and German statutory insurance population aging sustain procedure volume concentration in these geographies.
- Vascular Surgery:Specialist-trained operators manage complex anatomies and complication salvage, anchoring premium device utilization in academic and tertiary settings. Fellowship programs at Cleveland Clinic, Massachusetts General, and Heidelberg University Hospital standardize technology evaluation and adoption curves.
- Cardiology:Interventional cardiologists extend coronary techniques into peripheral territory, particularly renal and carotid applications.
- Gastroenterology:Transhepatic portal venous interventions and biliary stenting represent niche crossover applications.
Peripheral vascular disease holds the largest share; momentum sits with vascular surgery specialization driving premium platform selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals favor drug-eluting platforms for femoropopliteal cases, while German statutory reimbursement sustains balloon-stented volumes and Japanese regulators impose additional pharmacokinetic hurdles that reshape product mix.
United States
Medicare site-neutral payment policies and ambulatory surgical center expansion drive same-day discharge protocols for peripheral revascularization. FDA 21 CFR 820 quality system regulations enforce rigorous fatigue-testing standards for nitinol devices. Freestanding endovascular clinics in Florida, Texas, and Arizona negotiate direct manufacturer bundles that bypass traditional hospital markup structures.
Germany
Statutory health insurance reimbursement favors established mechanical platforms over premium alternatives in iliac artery applications. EU Medical Device Regulation post-market surveillance mandates systematic real-world evidence collection with five-year follow-up protocols. Production clusters in Baden-Württemberg and Bavaria concentrate laser-cutting expertise for cobalt-chromium stent geometries.
Japan
Aging demographics and expanding interventional cardiology training sustain procedure volume concentration in femoropopliteal segments. PMDA pharmacokinetic scrutiny on drug-eluting variants extends technical documentation preparation timelines. Academic medical centers in Tokyo and Osaka anchor adoption curves through fellowship programs that standardize device evaluation protocols.
Brazil
Cost-conscious hospital procurement in emerging markets favors conventional stents despite inferior patency outcomes. ANVISA regulatory alignment with FDA standards creates expedited pathways for approved United States devices. São Paulo and Rio de Janeiro concentrate interventional capacity through private hospital networks pursuing catheter-based technique standardization.
China
Domestic production capacity expansion targets import substitution in nitinol-based self-expanding platforms. NMPA clinical evidence requirements for novel devices extend market access timelines compared to mature geographies. Yangtze River Delta manufacturing clusters scale laser machining capabilities for cobalt-chromium alloy substrates.
Global Peripheral Stent Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive metallurgical capabilities separating margin-resilient manufacturers from component assemblers exposed to raw material volatility. The competitive terrain stratifies across three archetypes: diversified medtech conglomerates with captive supply chains, precision machining specialists with differentiated laser-cutting capabilities, and regional fabricators competing on cost-adjusted delivery. Consolidation pressure manifests through strategic partnerships for regulatory navigation and capacity expansion for fatigue-testing infrastructure.
Among diversified medtech conglomerates, Medtronic and Abbott Laboratories occupy positions representing integrated manufacturing archetypes with upstream control over nitinol supply. Boston Scientific Corporation exemplifies the precision-specialist tier, anchoring competitive positioning through differentiated fabrication capabilities. Terumo Corporation sits within the Asia-Pacific fabrication cluster, representing geographic diversification strategies for regulatory pathway optimization.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Terumo Corporation |
| B. Braun SE |
| Becton Dickinson and Company |
| W.L. Gore & Associates |
| Cook Group |
| Biotronik SE & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day nitinol alloy lead times from United States and German suppliers concentrate pricing power among integrated manufacturers with captive metallurgical capabilities, while spot-market buyers absorb volatility premiums that compress margins for component assemblers.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated manufacturers and academic medical center networks, insulating premium drug-eluting platforms from spot-price turbulence. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated fatigue-tested devices from CE-marked mechanical alternatives and emerging-market bare-metal substitutes. Pricing pressure stems from ambulatory surgical center bundle negotiations in Florida, Texas, and Arizona that unbundle traditional hospital markup structures. Hospital procurement committees exhibit lowest price sensitivity for complex renal artery cases, while emerging-market distributors drive hardest bargain on conventional self-expanding platforms.
Supply Chain Analysis
Just-in-time inventory strategies predominate among German and United States laser-cutting facilities serving high-mix, low-volume stent geometries, while Asian fabricators maintain strategic stockpiles of cobalt-chromium feedstock to buffer against maritime logistics variability. Supply concentrates in United States nitinol smelters, German precision machining clusters, and Chinese magnesium alloy foundries. Raw material dependencies center on nickel-titanium shape-memory alloys, cobalt-chromium L605 substrates, and paclitaxel active pharmaceutical ingredients. Single-source vulnerability in FDA-audited nitinol suppliers exposes manufacturers to qualification timeline delays. Distribution runs through GPO contracts with hospital systems and direct manufacturer agreements with freestanding ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambulatory surgical center consolidation into multi-state operator networks in the United States is shifting procurement leverage toward buyers, fragmenting historical vendor lock-in and compressing pricing premiums for mechanical platforms.
For Market Incumbents: Secure captive nitinol supply commitments through backward integration into United States metallurgical facilities before FDA fatigue-testing mandates tighten further. Anchor hospital system partnerships through bundled procedural pricing that resists ambulatory center unbundling. Defend against magnesium alloy bioresorbable substitutes by accelerating polymer-coating R&D pipelines. For New Entrants and Emerging Players: Post-market surveillance data services for EU MDR compliance represent an under-served layer where incumbents lack specialized staffing. Target Brazilian private hospital networks pursuing ANVISA-FDA harmonization for fastest regulatory pathway. Penetrate renal artery applications through hybrid OR training partnerships with Texas and Ohio tertiary centers. Lead with per-procedure cost predictability rather than capital-equipment relationships. For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because laser-cutting talent scarcity and 21 CFR 820 compliance infrastructure create durable moats around precision machining specialists. Acquisition targets should display in-house fatigue-testing facilities and active notified body relationships for EU MDR. Watch for ANVISA approval timelines shortening as the signal that Latin American pricing premiums are compressing toward United States levels.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Drug-Eluting Variants | Pharmacokinetic modeling investment accelerates Medicare coverage expansion in academic medical centers. |
| CE Marking Pathway Under EU MDR | Five-year implant registry commitments extend quality system implementation periods for notified bodies. |
| Hospital System Partnership | GPO contract anchoring resists ambulatory surgical center unbundling pressures in United States markets. |
| Software Companion Development | Deployment planning tools for hybrid OR workflows differentiate positioning in complex chronic total occlusion cases. |
| Reimbursement Strategy | Medicare site-neutral payment optimization enables same-day discharge protocol expansion into treatable anatomies. |
Study Parameters
Desk research of FDA 510(k) filings, EU MDR technical documentation, and CMS Medicare claims databases preceded structured interviews with vascular surgery program directors, GPO contracts managers, biomedical engineers, and nitinol metallurgy specialists. Primary fieldwork combined hospital purchasing committee observations with ambulatory surgical center administrator discussions. Secondary validation drew from notified body guidance documents, ISO 25539-2 certification timelines, and trade customs data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Variance decomposition across product type, end-user channel, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to Medicare beneficiary demographics and interventional training program expansion rates. Modeled inputs included PMDA pharmacokinetic pathway timelines, ANVISA harmonization progress, and laser-cutting capacity utilization in Baden-Württemberg production clusters.
Forecasts assume regulatory continuity in FDA 21 CFR 820 enforcement, EU MDR post-market surveillance mandates, and Japan PMDA pharmacokinetic scrutiny; material policy shifts would require re-modeling. Revision becomes warranted when ambulatory surgical center Medicare site-neutral payment ratios cross thresholds that accelerate hospital system consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market