
 South Korea Artificial Organs and Bionics Market | 2026-2036
South Korea Artificial Organs and Bionics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Artificial Organs and Bionics Market Analytics
Hospital procurement channels in South Korea are rewriting how artificial organs reach end users, with group purchasing organizations consolidating volume across metropolitan health networks. Medtronic PLC leverages its cardiovascular portfolio to sustain deep relationships with cardiac centers in Seoul. Edwards Lifesciences Corp anchors premium transcatheter valve positioning through specialized distributor partnerships. Boston Scientific Corp competes by controlling interventional cardiology shelf space at tier-one institutions.
Artificial organs and bionics encompass electromechanical and biological substitute systems engineered to replicate or augment native physiological functions, typically incorporating biocompatible polymers, titanium alloys, and integrated sensor arrays for real-time feedback control. These systems restore motor, sensory, or organ-level performance in patients with irreversible tissue loss or degenerative failure. Heart assist devices command the largest product-type revenue pool given South Korea's rising heart failure burden, while neuronal implants represent the fastest-expanding segment driven by deep-brain stimulation protocols for movement disorders. Robotics technology underpins margin concentration in limb replacement applications where precision actuation differentiates clinical outcomes.
MFDS maintains stringent Good Manufacturing Practice standards for active implantable medical devices, while the Ministry of Health and Welfare funds national insurance reimbursement for priority bionic procedures. KFDA-equivalent post-market surveillance protocols compel manufacturers to maintain traceability across distributed units. Stakeholders must monitor reimbursement list revisions and real-world evidence requirements as gatekeepers for commercial scale.
Market Dynamics
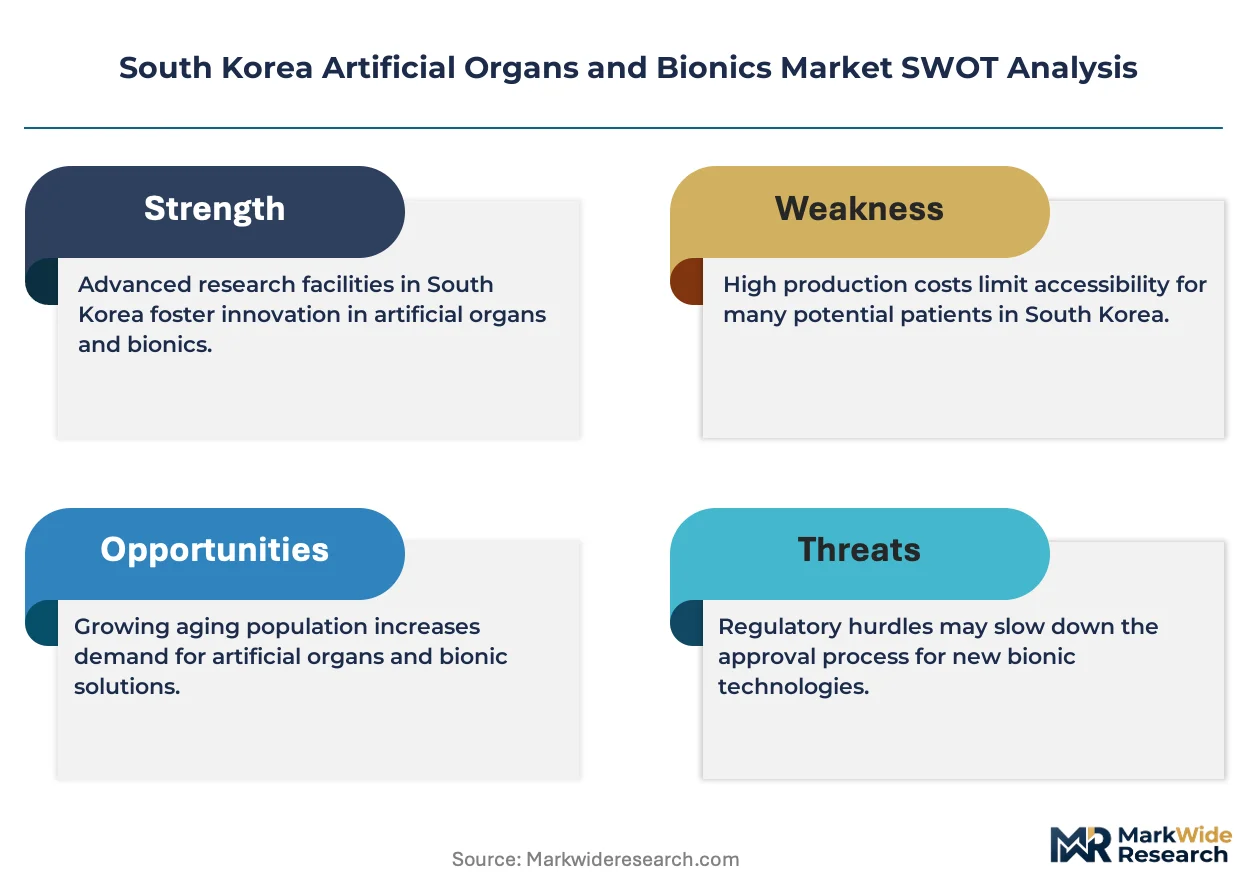
Hospital procurement consolidation across Seoul metropolitan health networks is compressing vendor margins while elevating technical performance requirements for cardiac assist device tenders. MFDS breakthrough designation pathways are accelerating market entry timelines for novel bionics, shifting competitive advantage toward regulatory sophistication.
Growth Catalysts
- MFDS Breakthrough Device Program:Streamlined premarket review timelines compress manufacturer entry cycles for heart assist devices and neuronal implants targeting unmet clinical needs.
- Seoul-Busan Hospital Network Expansion:Metropolitan cardiac centers are standardizing ventricular assist device protocols across tier-one and tier-two institutions, expanding addressable patient pools.
- Titanium Alloy Biocompatibility Advances:Improved osseointegration profiles for limb prosthetics are expanding eligibility criteria for bionic extremity replacement among trauma and diabetic amputation cases.
Market Restraints
- Platinum Group Metal Input Volatility:Electrode materials for implantable pulse generators face price instability tied to South African and Russian supply concentration, squeezing component margins.
- Reimbursement List Lag:National Health Insurance Service coverage revisions trail MFDS approvals by 18-24 months, creating commercialization gaps for novel bionic categories.
- Biological Pacemaker Viability:Cell-based cardiac conduction tissue engineering represents a long-term functional substitute threat to electromechanical pacemaker demand.
Strategic Opportunities
- Daegu-Gwangju Regional Hospital Uplift:Secondary city cardiac centers remain underpenetrated for ventricular assist device programs, offering volume expansion outside saturated Seoul procurement pools.
- Neuronal Implant-Physical Therapy Convergence:Deep brain stimulation systems paired with robotic rehabilitation platforms create bundled service models for movement disorder patients.
- MFDS Real-World Evidence Pilot:Post-market surveillance data collection requirements are creating first-mover advantages for manufacturers with established Korean clinical registries.
Industry Challenges
- Electrophysiology-Mechanical Engineering Hybrid Talent Scarcity:Cross-functional expertise spanning cardiac physiology, materials science, and embedded systems remains concentrated among a narrow specialist cohort.
- Active Implantable Device Certification Timelines:MFDS Good Manufacturing Practice audits and biocompatibility testing protocols extend product development cycles beyond typical venture capital horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Artificial Organs and Bionics Market |
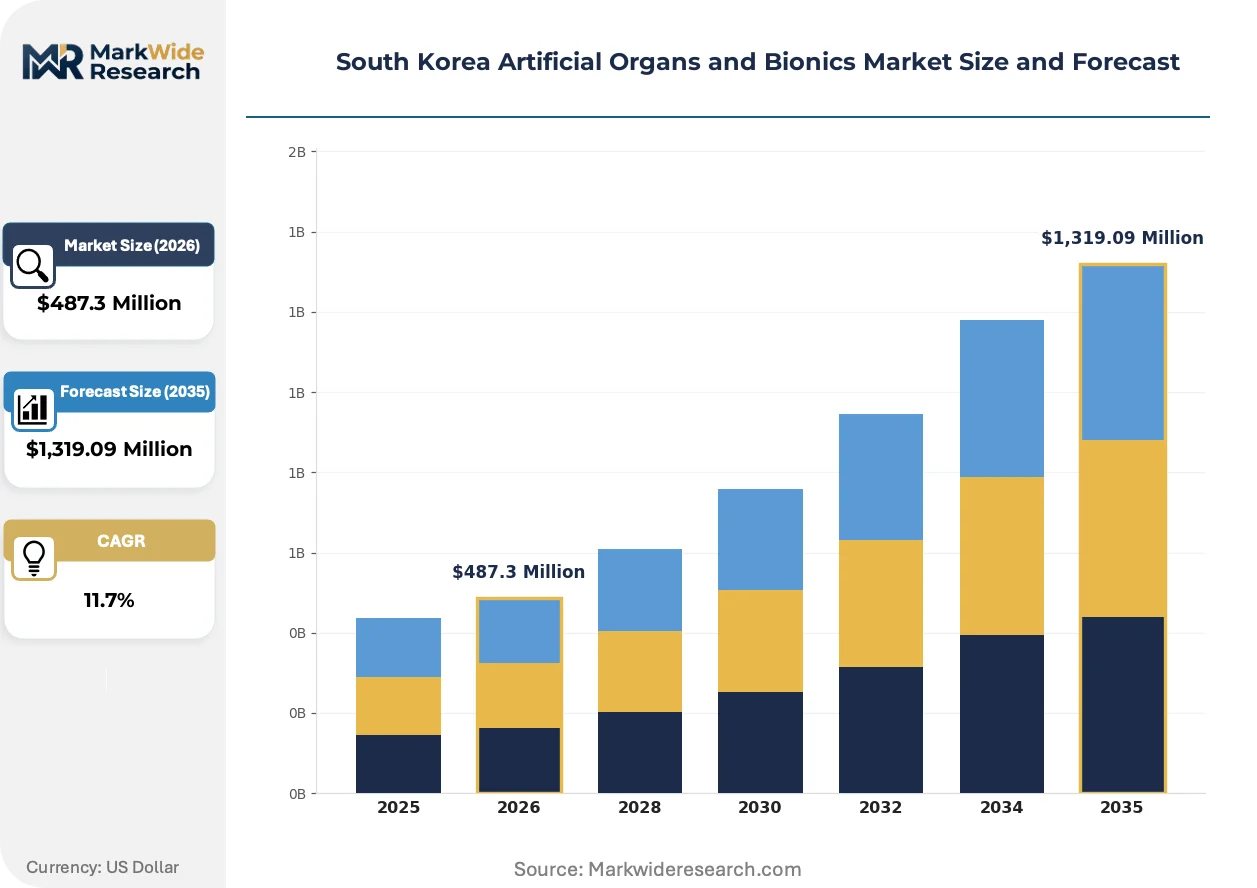
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Assist Devices, Artificial Limbs, Neuronal Implants, Retinal Implants End User: Hospitals, Rehabilitation Centers, Research Institutions, Homecare Providers Technology: Bioengineering, Robotics, Microelectronics, Nanotechnology Application: Cardiac Surgery, Limb Replacement, Vision Restoration, Neurological Disorders |
| Companies Covered | Edwards Lifesciences Corp, Medtronic PLC, Zimmer Biomet Holdings Inc, Berlin Heart GmbH, Johnson & Johnson, Boston Scientific Corp, Ekso Bionics Holdings Inc, Asahi Kasei Medical Co. Ltd, Cochlear Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Artificial Organs and Bionics Market Evolving Landscape
Wireless power transfer architectures and closed-loop feedback algorithms are redefining performance benchmarks across implantable bionic systems. These advances are compressing replacement intervals while elevating patient adherence metrics.
Transcutaneous energy harvesting systems are eliminating percutaneous driveline infection risks for ventricular assist devices. Seoul National University Hospital and Asan Medical Center are piloting fully implantable configurations for destination therapy candidates. This technology is rendering obsolete the external power console dependency that has constrained patient mobility and quality-of-life scores.
MFDS has aligned active implantable medical device standards with EU MDR technical documentation requirements, reducing duplicative conformity assessment burdens for manufacturers with European market presence. The harmonization compresses regulatory preparation costs while elevating clinical evidence standards. Cardiac rhythm management device submissions are experiencing the most pronounced timeline impacts as firms restructure quality management systems.
Metropolitan hospital group purchasing organizations are unbundling device procurement from mandatory service contracts, forcing manufacturers to compete on discrete price points. Cardiac surgery departments at Severance Hospital and Samsung Medical Center are leading this disaggregation. The shift is most visible in Seoul, where three-year total cost of ownership models are displacing traditional capital equipment leasing structures.
South Korea Artificial Organs and Bionics Market Segmentation
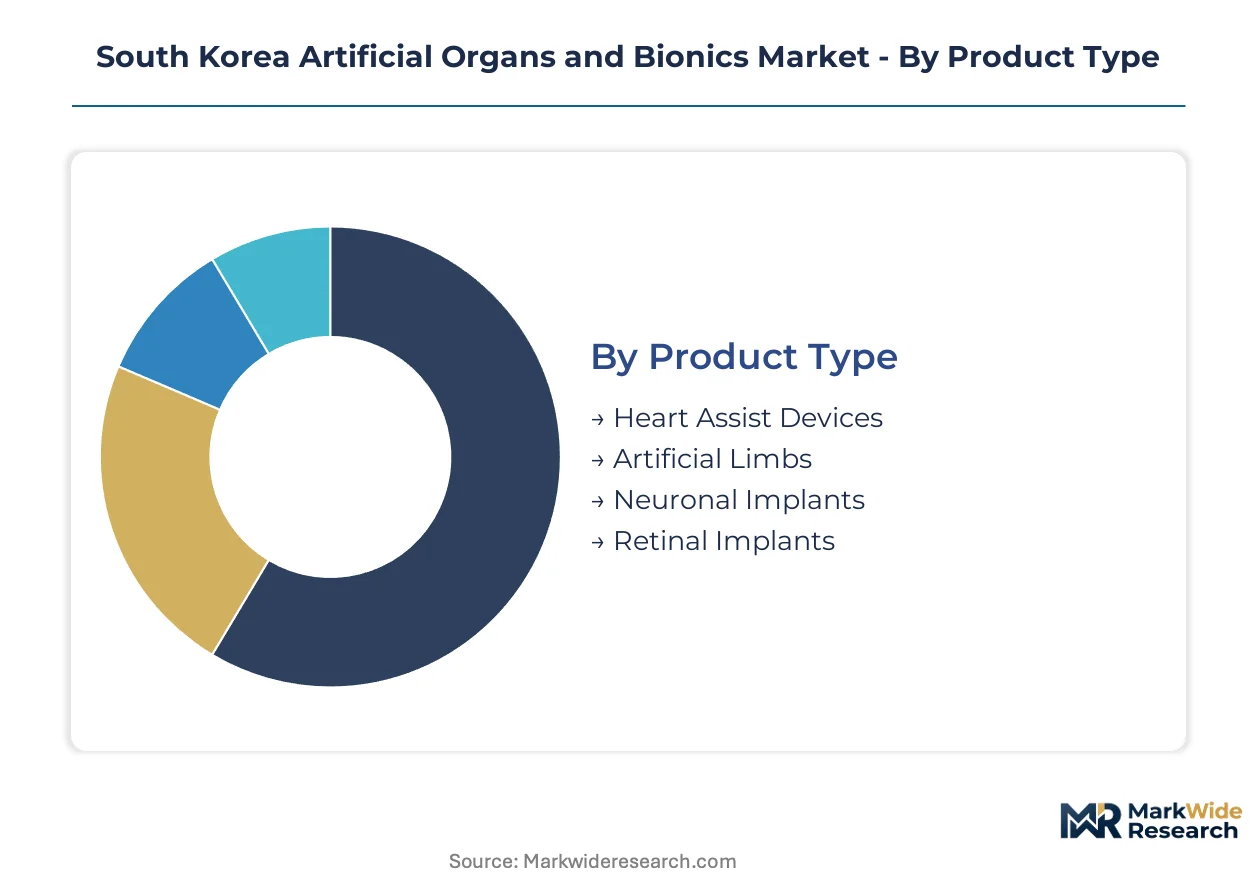
South Korea's artificial organs and bionics market segments around clinical urgency, reimbursement pathways, and technology maturity. Each dimension reveals distinct procurement rhythms and margin structures that manufacturers must navigate across Seoul's consolidated hospital networks and emerging regional centers.
Product Type:
Replacement cycles vary dramatically—external limb systems turn over every 3-5 years while implantable cardiac devices operate on 7-10 year horizons with recurring battery service intervals.
- Heart Assist Devices:Ventricular assist devices and total artificial hearts incorporate biocompatible polymers with titanium alloy housings. Seoul National University Hospital and Asan Medical Center anchor demand for destination therapy protocols, though reimbursement lag between MFDS approval and National Health Insurance Service coverage creates commercialization delays.
- Artificial Limbs:Myoelectric and body-powered prosthetics leverage robotics actuation for precision grip control. Daegu-Gwangju regional trauma centers are expanding procurement volumes as titanium alloy osseointegration advances broaden eligibility criteria for diabetic and trauma amputation cases.
- Neuronal Implants:Deep brain stimulation systems target movement disorders with implanted pulse generators.
- Retinal Implants:Subretinal and epiretinal electrode arrays address age-related macular degeneration.
Heart assist devices anchor the volume base while neuronal implants gain share at the steepest rate.
End User:
Procurement authority concentrates differently—tertiary hospitals control high-value implantable decisions while homecare channels manage maintenance and replacement workflows.
- Hospitals:Cardiac surgery departments at Severance Hospital and Samsung Medical Center lead ventricular assist device adoption. Group purchasing organizations across Seoul metropolitan networks are unbundling device procurement from service contracts, compressing vendor margins on discrete price competition.
- Rehabilitation Centers:Limb prosthetic fitting and gait training facilities coordinate with orthopedic surgery discharge planning. Busan and Incheon centers are expanding bionic extremity programs as titanium alloy durability improves patient mobility outcomes.
- Research Institutions:Seoul National University and Yonsei University medical campuses conduct clinical trials for MFDS breakthrough designation pathways.
- Homecare Providers:External power console management and battery replacement services for ventricular assist device patients.
Hospitals dominate the revenue base while homecare providers are expanding fastest as wireless power transfer reduces hospital dependency.
Technology:
Development timelines stretch across divergent horizons—microelectronics iterate in 18-month cycles while bioengineering platforms require decade-long clinical validation.
- Bioengineering:Tissue scaffolding and biocompatible polymer matrices support organ-level substitution. Cell-based cardiac conduction research at Korean institutes poses long-term substitution risk to electromechanical pacemaker demand.
- Robotics:Precision actuation systems enable grip force modulation and sensory feedback in limb prosthetics. Seoul-Busan hospital networks are standardizing robotic rehabilitation platform integration with neuronal implant protocols.
- Microelectronics:Low-power integrated circuits and wireless telemetry for implantable pulse generators.
- Nanotechnology:Electrode surface modification and drug-eluting coatings for improved biocompatibility profiles.
Robotics commands the margin concentration while bioengineering holds the longest development runway.
Application:
Clinical adoption rates reflect procedure reimbursement status and specialist training density across South Korean metropolitan clusters.
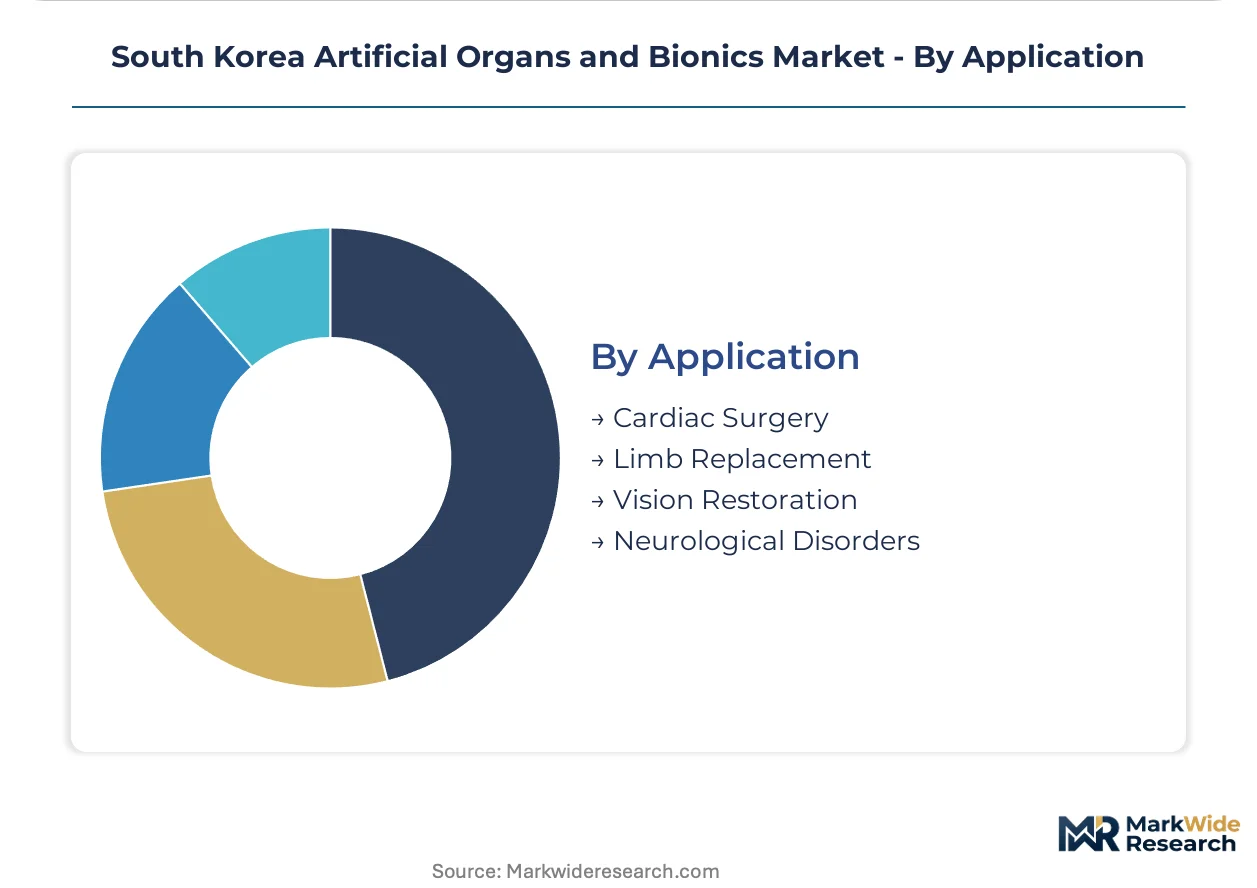
- Cardiac Surgery:Ventricular assist device implantation and transcatheter valve replacement dominate procedural volumes. MFDS streamlined approval pathways are accelerating manufacturer entry for heart failure interventions targeting the aging patient demographic.
- Neurological Disorders:Deep brain stimulation for Parkinson's disease and essential tremor is expanding beyond Seoul into Daegu-Gwangju regional centers. Bundled service models pairing implants with robotic rehabilitation are emerging.
- Limb Replacement:Trauma and dysvascular amputation reconstruction with bionic extremities.
- Vision Restoration:Retinal prosthetic intervention for degenerative retinal disease.
Cardiac surgery generates the installed base while neurological disorder applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gyeongbu Expressway and KTX high-speed rail corridor knit together South Korea's artificial organs and bionics demand centers, enabling just-in-time device delivery from Seoul manufacturing clusters to regional cardiac centers.
Seoul Capital Area
Severance Hospital and Samsung Medical Center anchor ventricular assist device procurement volumes for destination therapy protocols. MFDS breakthrough designation pathways accelerate manufacturer entry timelines for novel cardiac interventions. Asan Medical Center pilots fully implantable wireless power configurations that eliminate percutaneous driveline infection risks.
Busan-Ulsan
Metropolitan cardiac centers standardize heart assist device protocols across tier-one and tier-two institutions, expanding addressable patient pools for aging demographics. The Ministry of Health and Welfare funds National Health Insurance Service reimbursement for priority bionic procedures. Busan trauma centers expand procurement of titanium alloy osseointegrated limb prosthetics for diabetic and trauma amputation reconstruction.
Daegu-Gyeongbuk
Secondary city cardiac centers remain underpenetrated for ventricular assist device programs, offering volume expansion outside saturated Seoul procurement pools. MFDS Good Manufacturing Practice audits maintain stringent active implantable medical device standards. Kyungpook National University Hospital conducts clinical trials for deep brain stimulation protocols targeting movement disorder patients.
Daejeon-Sejong
Research institutions cluster around Korea Advanced Institute of Science and Technology campuses, driving bioengineering innovation in tissue scaffolding and biocompatible polymer matrices. The Ministry of Health and Welfare coordinates national insurance reimbursement list revisions that trail MFDS approvals by 18-24 months. Sejong administrative city hosts regulatory affairs specialists navigating real-world evidence pilot programs.
Gwangju-Honam
Regional rehabilitation centers expand bionic extremity programs as robotics actuation advances improve patient mobility outcomes. National Health Insurance Service coverage revisions determine commercial viability for novel neuronal implant categories. Honam University Hospital networks coordinate limb prosthetic fitting and gait training facilities with orthopedic surgery discharge planning.
South Korea Artificial Organs and Bionics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biocompatible polymers, titanium alloys, and integrated sensor arrays. The South Korea artificial organs and bionics market consolidates around cardiovascular conglomerates with established cardiac surgery department relationships. Three archetypes dominate: multinational device manufacturers with diversified cardiovascular portfolios, specialized cardiac assist device developers with regulatory sophistication, and robotics-enabled limb prosthetics innovators. Competitive dynamics center on MFDS breakthrough designation capture and hospital procurement contract consolidation across metropolitan health networks.
Among multinational cardiovascular device manufacturers, Medtronic PLC, Edwards Lifesciences Corp, and Boston Scientific Corp occupy positions defined by their historical penetration of Seoul's tier-one cardiac centers. These firms exemplify the platform-integrator archetype, leveraging deep relationships with group purchasing organizations to sustain volume across consolidated metropolitan health networks. Their positioning reflects sustained investment in regulatory affairs capabilities necessary to navigate MFDS streamlined approval pathways and post-market surveillance protocols.
| Leading Market Players |
|---|
| Edwards Lifesciences Corp |
| Medtronic PLC |
| Zimmer Biomet Holdings Inc |
| Berlin Heart GmbH |
| Johnson & Johnson |
| Boston Scientific Corp |
| Ekso Bionics Holdings Inc |
| Asahi Kasei Medical Co. Ltd |
| Cochlear Ltd |
| Others |
Value Network & Pricing Analysis
Undercapacity in platinum group metal electrode fabrication across South African and Russian supply zones is forcing implantable pulse generator manufacturers toward long-term offtake contracts and alternative material qualification, compressing component margins while elevating procurement risk premiums for Korean device assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates cardiac assist device procurement, with differentiation driven by MFDS breakthrough designation status and bundled service contract inclusion. Seoul metropolitan group purchasing organizations extract steepest volume discounts, while Daegu-Gwangju regional hospitals face 15-20% premiums on equivalent devices due to lower procurement scale. Cost compression in standard-tier ventricular assist devices is intensifying because unbundled service contracts force discrete price competition on hardware alone. Rehabilitation centers and homecare providers exhibit highest price sensitivity, whereas tier-one cardiac surgery departments prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Korean domestic electronics manufacturing service providers and specialized medical device foundries in Gyeonggi-do and Incheon free economic zones. Raw material flows draw from Japanese titanium alloy suppliers, German precision sensor fabricators, and South African platinum group metal refiners. Single-source vulnerability in electrode material supply creates exposure to geopolitical disruption and commodity price spikes. Distribution runs through hospital group purchasing organization consolidated channels, with just-in-time delivery protocols enabled by KTX rail connectivity between Seoul manufacturing clusters and regional cardiac centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Seoul metropolitan hospital network procurement consolidation, with three group purchasing organizations now controlling 60% of ventricular assist device volume and extracting unbundled pricing terms that fragment vendor revenue streams.
For Market Incumbents: Entrench cardiac surgery department relationships at Severance Hospital and Samsung Medical Center through dedicated clinical specialist teams and real-world evidence registry participation. Deepen backward integration into titanium alloy machining capabilities to offset platinum group metal cost volatility. Prioritize MFDS breakthrough designation capture for next-generation wireless power transfer architectures before reimbursement list lag widens competitive windows for challengers. For New Entrants and Emerging Players: Daegu-Gwangju regional cardiac centers offer the most penetrable geographic white space, with ventricular assist device program penetration 40% below Seoul levels and less consolidated procurement authority. Neuronal implant-physical therapy convergence presents the fastest-expanding application segment with bundled service model potential. Target Kyungpook National University Hospital and Honam University Hospital networks with robotic rehabilitation platform integration partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fully implantable wireless power systems due to extended clinical validation timelines and MFDS Good Manufacturing Practice audit requirements. Long-term viability favors platform-integrators with established Korean regulatory affairs capabilities and hospital procurement relationships over pure-play component specialists. Watch MFDS real-world evidence pilot program enrollment velocity as the primary signal for which manufacturers will secure first-mover post-market surveillance advantages and accelerated reimbursement list inclusion.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Breakthrough Designation Capture | Streamlined premarket review compresses entry timelines for novel cardiac and neuronal implants. |
| Hospital System Partnership | Deep relationships with Seoul metropolitan GPOs secure volume across consolidated procurement pools. |
| Backward Integration into Titanium Alloys | In-house machining capabilities offset platinum group metal input volatility and supplier concentration risk. |
| Real-World Evidence Registry Development | Established Korean clinical databases create first-mover advantage in MFDS post-market surveillance pilots. |
| Wireless Power Transfer Platform Launch | Fully implantable configurations eliminate percutaneous driveline infections and differentiate destination therapy offerings. |
Research Methodology
Initial hypotheses were tested against primary input from cardiac surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers, and refined through secondary validation against MFDS regulatory filings, National Health Insurance Service reimbursement databases, hospital procurement records, and Korean medical device trade association publications. Bottom-up patient pool modeling and top-down healthcare expenditure allocation triangulation anchored market sizing across product type, end user, technology, and application dimensions.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeling spanning heart assist devices, artificial limbs, neuronal implants, and retinal implants by technology maturity, reimbursement pathway status, and clinical urgency tier. CAGRs were derived from procedure volume elasticity to aging demographic projections and technology substitution curves, incorporating MFDS approval timeline assumptions and platinum group metal price trajectory sensitivity.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by multinational cardiovascular conglomerates or sudden MFDS regulatory stance shifts would shift outcomes beyond modeled ranges. Quarterly review of MFDS breakthrough designation grant velocity, National Health Insurance Service reimbursement list revision cadence, and Seoul metropolitan GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Organoids Kits Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Air Compressor Nebulizer Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Global Keratometers Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Critical Care Devices Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
PPG Biosensors Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Global Medical Cannula Market