
 Diabetes Devices Market | 2026-2036
Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Devices Market Intelligence
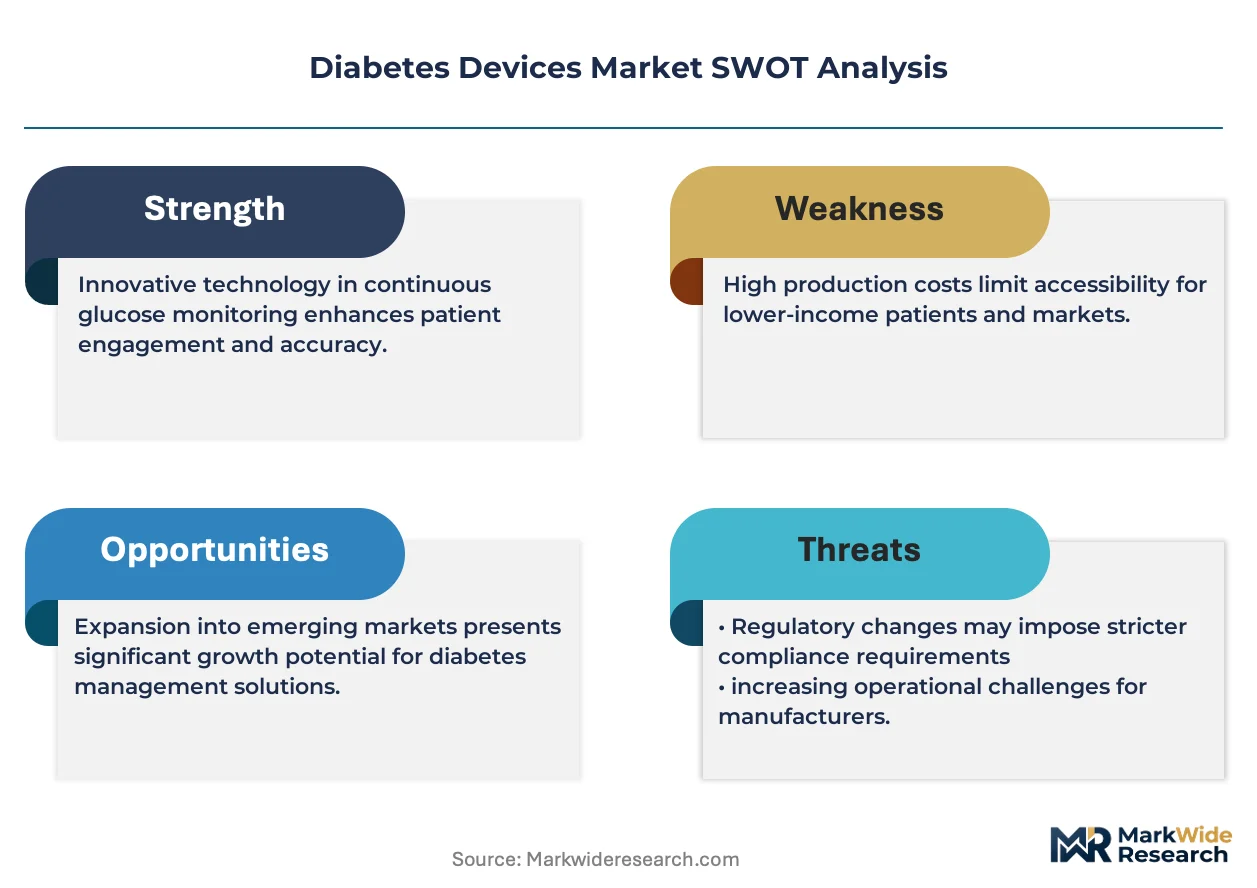
The EU Green Deal's medical device sustainability criteria is decoupling procurement preferences from pure cost metrics across European hospital systems. Abbott Laboratories leverages integrated continuous glucose monitoring manufacturing to sustain supply security for sensor-integrated pump ecosystems. Medtronic anchors its position through vertically controlled insulin delivery algorithm development. Dexcom competes on factory automation scale for disposable sensor output.
Diabetes devices comprise electromechanical and disposable instruments engineered to measure blood glucose concentration, administer insulin, or manage metabolic data through sensor arrays typically operating at 2.4 GHz wireless protocols and subcutaneous insertion depths of 5-13 millimeters. Their primary commercial purpose centers on reducing glycemic variability and preventing microvascular complications in insulin-dependent populations. Continuous glucose monitors command the fastest expansion trajectory within product type segments, while Bluetooth-enabled and mobile app integrated technologies concentrate margin pools through recurring software subscription architectures. Home care settings within end user segments absorb the dominant volume share as remote patient monitoring infrastructure matures.
The FDA breakthrough device program and EU MDR conformity requirements jointly elevate clinical evidence thresholds for new glucose monitoring platforms seeking commercial access. ISO 15197 accuracy standards for blood glucose meters and HIPAA data interoperability rules in the United States further constrain product design specifications and cloud architecture investments. Stakeholders must weigh regulatory submission sequencing against sensor-integrated pump convergence timelines to preserve reimbursement positioning.
Market Dynamics
Sensor-integrated pump convergence is compressing standalone device margins while elevating software and algorithmic differentiation as the primary value capture mechanism across insulin delivery ecosystems.
Growth Catalysts
- Automated Insulin Delivery Algorithms:Machine learning-driven glucose prediction models are reducing hypoglycemic events in Type 1 populations, accelerating hospital procurement group contracting for closed-loop systems in the United States.
- FDA Breakthrough Device Pathway:Accelerated review timelines for sensor-integrated pumps are compressing commercialization cycles, enabling earlier reimbursement coding for hybrid closed-loop configurations.
- Germany's Ambulatory Networks:Dense diabetes care infrastructure in Bavaria and North Rhine-Westphalia is generating concentrated demand clusters for continuous glucose monitoring adoption among insulin-dependent patients.
Market Restraints
- EU MDR Conformity Costs:Elevated clinical evidence requirements for glucose monitoring platforms are extending certification timelines and inflating regulatory submission expenditures for manufacturers seeking European market access.
- Disposable Sensor Supply Concentration:Factory automation scale advantages have concentrated high-volume sensor production among a limited supplier base, creating vulnerability to single-source disruption.
- Interoperability Standard Fragmentation:Proprietary data protocols between pump and sensor ecosystems are limiting patient choice and complicating health system procurement standardization efforts.
Strategic Opportunities
- Remote Patient Monitoring Infrastructure:Bluetooth-enabled and mobile app-integrated diabetes devices are capturing recurring software subscription revenue through cloud-based metabolic data management platforms.
- Home Care Setting Penetration:Underpenetrated rural and suburban populations in the United States present expansion potential as telehealth reimbursement codes mature for remote glucose management.
- EU Green Deal Procurement Criteria:Sustainability-weighted hospital procurement scoring is creating first-mover advantage for manufacturers with circular manufacturing and reduced packaging footprints.
Industry Challenges
- Algorithm Validation Talent Scarcity:Competitive hiring for computational biologists and control systems engineers is constraining in-house insulin delivery algorithm development timelines.
- HIPAA Cloud Architecture Investment:Health data interoperability rules are forcing substantial capital allocation toward compliant data infrastructure and cybersecurity certification.
- Legacy Meter Integration Complexity:Health system EMR connectivity requirements are complicating backward compatibility for next-generation continuous glucose monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Devices Market |
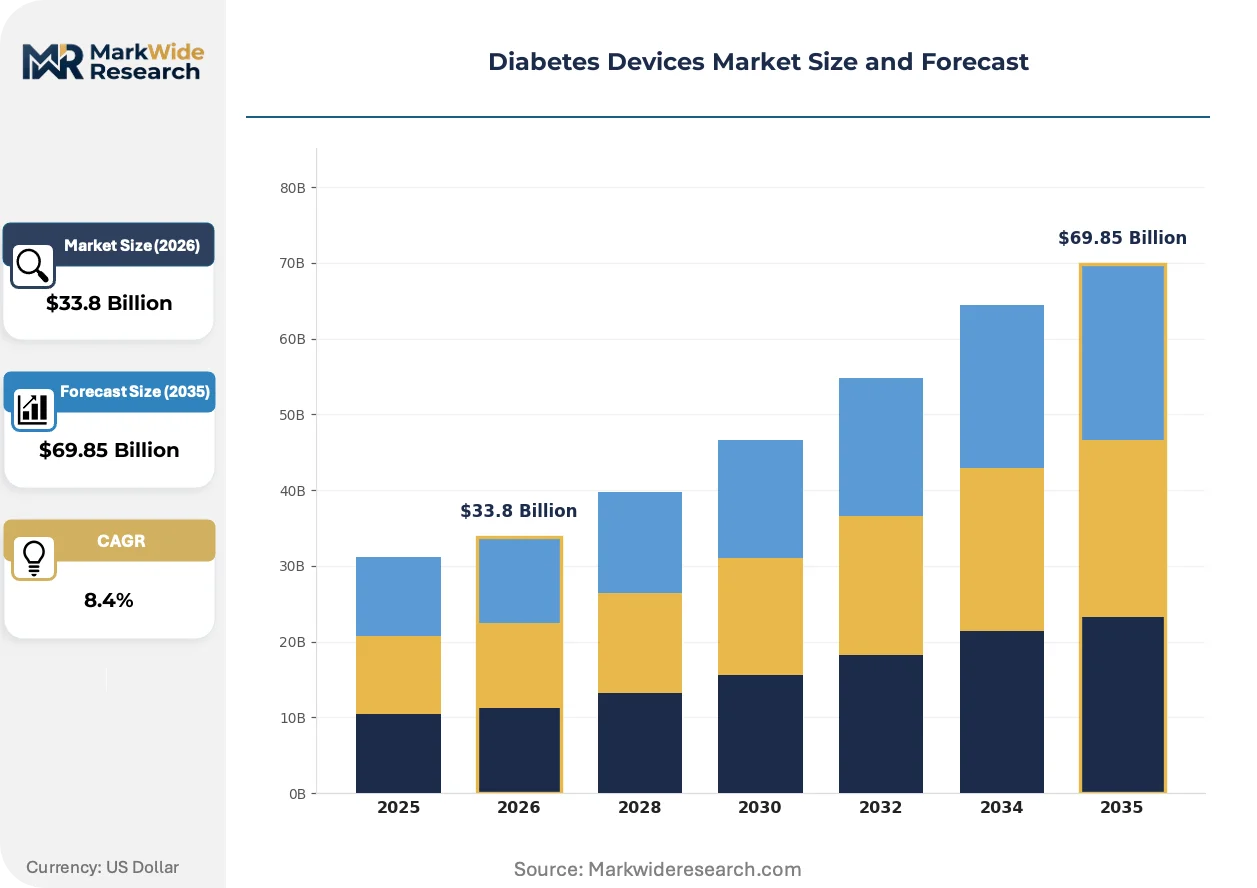
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $69.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Glucose Meters, Continuous Glucose Monitors, Insulin Pens, Lancets Technology: Bluetooth-enabled, Wireless, Mobile App Integrated, Sensor-based, Cloud-connected Application: Blood Glucose Monitoring, Insulin Delivery, Data Management, Hypoglycemia Detection End User: Diabetic Clinics, Diagnostic Laboratories, Home Care, Pharmacies |
| Companies Covered | Abbott Laboratories, Medtronic, Roche, Dexcom, Insulet Corporation, Novo Nordisk, Tandem Diabetes Care, Lifescan, Ascensia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Devices Market Strategic Shifts & Innovations
Algorithmic unification of sensing and delivery functions is displacing modular device architectures, while regulatory data requirements and procurement model evolution are simultaneously reshaping competitive entry barriers and customer capture mechanisms.
Artificial pancreas systems are unifying continuous glucose monitoring with predictive insulin dosing through integrated control algorithms. Pediatric endocrinology departments in academic medical centers are piloting these configurations at accelerated adoption rates. This convergence is compressing the addressable market for standalone insulin pumps and blood glucose meters.
EU MDR conformity assessment and FDA breakthrough device designation are jointly elevating clinical evidence thresholds for new market entrants. Manufacturers must now complete randomized controlled trials exceeding prior predicate device standards. Sensor-integrated pump categories face the steepest compliance burden, favoring incumbents with established quality management systems.
Hospital procurement groups are consolidating supplier contracts through multi-year automated insulin delivery agreements that bundle devices, disposables, and software access. Group purchasing organizations are displacing individual hospital negotiations in the United States. This concentration is most visible in the Southeast and Midwest regions where health system consolidation has advanced furthest.
Diabetes Devices Market Segmentation
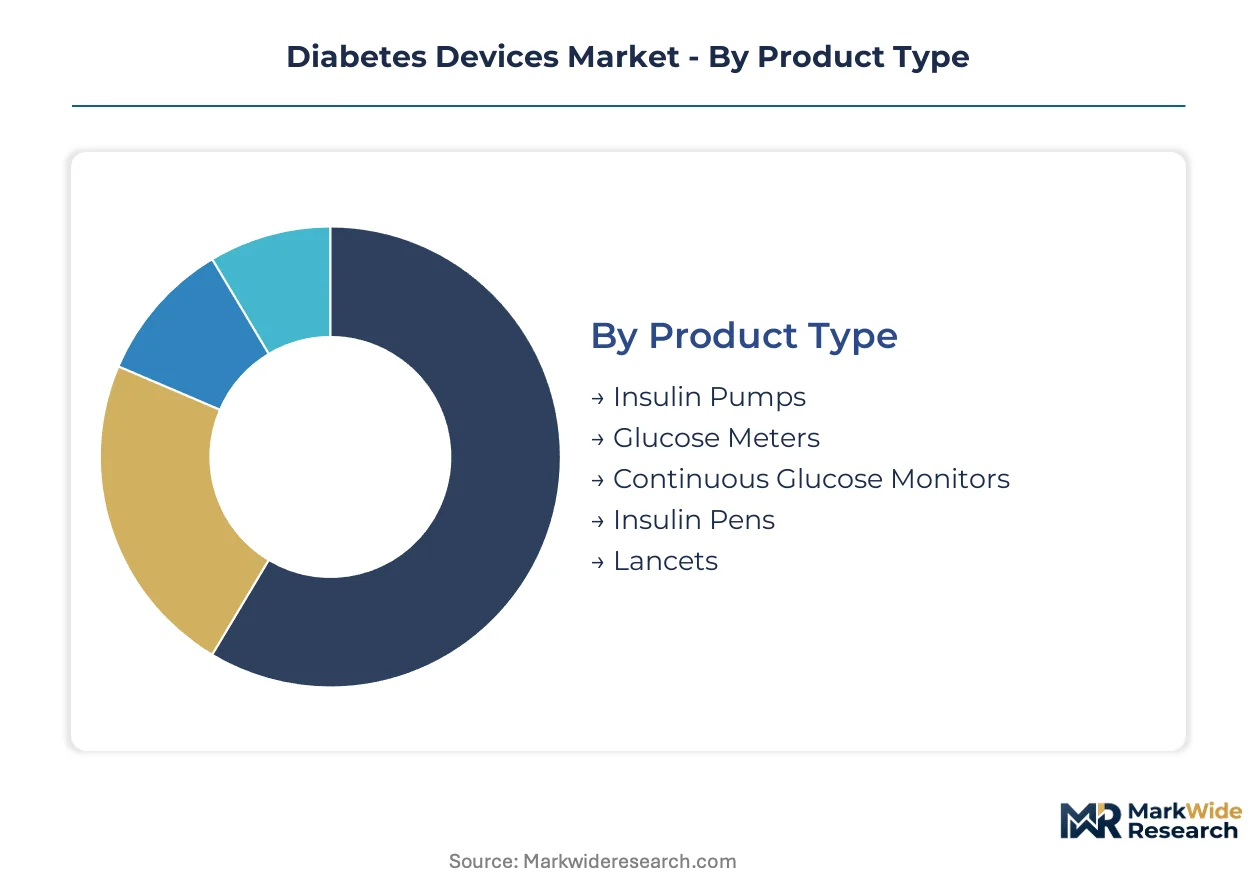
Device segmentation in diabetes care tracks how reimbursement pathways and patient self-management preferences split purchasing decisions across hardware categories and connectivity tiers. Procurement groups weigh disposable recurring revenue against capital equipment durability when structuring multi-year contracts.
Product Type:
Hospital procurement groups distinguish segments by capital intensity versus consumable replenishment cycles, reshaping contract bundling strategies.
- Continuous Glucose Monitors:Disposable sensor arrays operating at 2.4 GHz wireless protocols with 5-13 millimeter subcutaneous insertion depths. Demand concentrates in Germany's ambulatory diabetes care networks, driven by closed-loop algorithm integration with insulin pumps.
- Insulin Pumps:Electromechanical delivery systems with programmable basal-bolus dosing. United States hospital procurement groups are expanding automated insulin delivery contracts, compressing standalone pump margins through sensor-integrated convergence.
- Glucose Meters:Portable electrochemical analyzers for capillary blood sampling.
- Insulin Pens:Disposable and reusable injection devices for manual insulin administration.
- Lancets:Single-use skin puncture instruments for blood sample collection.
Continuous glucose monitors lead volumes today; insulin pumps are gaining share fastest through sensor integration.
Technology:
Connectivity architecture determines software subscription attach rates and cloud infrastructure compliance costs.
- Mobile App Integrated:Smartphone-tethered platforms capturing recurring revenue through metabolic data dashboards. Home care settings absorb dominant volume as telehealth reimbursement codes mature for remote glucose management in underpenetrated rural United States populations.
- Bluetooth-enabled:Short-range wireless protocols enabling device-to-device communication. FDA breakthrough device designation accelerates approvals for sensor-integrated pump configurations, elevating clinical evidence thresholds.
- Sensor-based:Electrochemical or optical glucose detection without fingerstick calibration.
- Cloud-connected:HIPAA-compliant data architecture for health system EMR integration.
- Wireless:Proprietary RF protocols for pump-sensor communication.
Mobile app integrated systems lead volumes today; Bluetooth-enabled platforms are climbing the fastest through procurement standardization.
Application:
Clinical outcome metrics separate segments by acute intervention urgency versus chronic management monitoring.
- Insulin Delivery:Automated and manual systems for exogenous insulin administration. Machine learning-driven glucose prediction models are reducing hypoglycemic events in Type 1 populations, accelerating United States hospital procurement group contracting.
- Blood Glucose Monitoring:Interstitial fluid or capillary blood measurement for glycemic tracking. Germany's ambulatory networks generate concentrated demand clusters for continuous monitoring adoption among insulin-dependent patients.
- Data Management:Cloud-based metabolic record aggregation and pattern analysis.
- Hypoglycemia Detection:Predictive alert systems for low glucose event prevention.
Insulin delivery leads volumes today; blood glucose monitoring is expanding most quickly through sensor-integrated pump convergence.
End User:
Site-of-care economics drive reimbursement code availability and device complexity requirements.
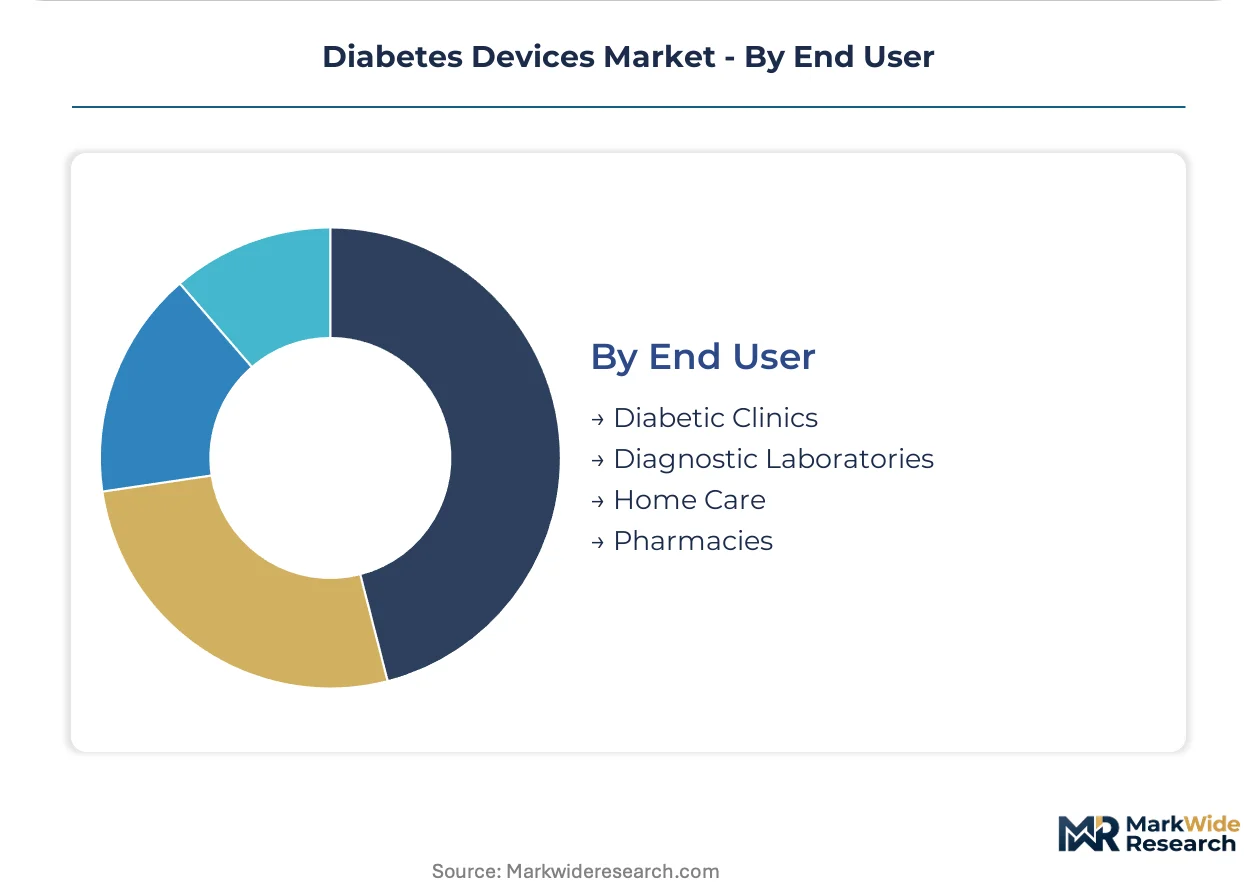
- Home Care:Patient-operated devices for self-managed diabetes control. Remote patient monitoring infrastructure maturity concentrates volume here, with Bluetooth-enabled and mobile app-integrated technologies capturing recurring software subscription revenue.
- Diabetic Clinics:Specialized ambulatory facilities with integrated care teams. Bavaria and North Rhine-Westphalia infrastructure generates dense demand clusters for continuous glucose monitoring adoption.
- Diagnostic Laboratories:Centralized testing facilities for HbA1c and glucose analysis.
- Pharmacies:Retail distribution points for over-the-counter and prescription devices.
Home care leads volumes today; diabetic clinics are gaining share fastest through ambulatory network densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetes device manufacturing originated in the United States and Germany during the 1980s, when electrochemical glucose sensing first achieved commercial viability. These historical centers remain dominant today, though production and demand patterns have diffused across specialized clusters worldwide.
United States
Hospital procurement groups in the Southeast and Midwest are consolidating multi-year automated insulin delivery contracts. FDA breakthrough device designation accelerates sensor-integrated pump approvals, compressing commercialization timelines. The Greater Boston and San Diego metro areas host dense concentrations of glucose monitoring algorithm development.
Germany
Bavaria and North Rhine-Westphalia generate Europe's densest demand clusters for continuous glucose monitoring adoption. EU MDR conformity requirements elevate clinical evidence thresholds for glucose monitoring platforms seeking European market access. Baden-Württemberg's precision manufacturing base supplies sensor-integrated pump components.
China
Domestic insulin-dependent populations drive volume demand for cost-optimized glucose meters and disposable sensors. NMPA regulatory pathways for innovative medical devices are shortening review cycles for sensor-integrated systems. The Yangtze River Delta region concentrates contract manufacturing for Bluetooth-enabled monitoring hardware.
Japan
PMDA approval standards for artificial pancreas systems are advancing faster than historical glucose meter benchmarks. METI industrial policy supports domestic production of electrochemical sensor arrays. The Kansai region around Osaka maintains specialized fabrication capacity for subcutaneous insertion devices.
India
Underpenetrated rural populations present expansion potential as telehealth reimbursement infrastructure matures. CDSCO medical device regulations are harmonizing with ISO 15197 accuracy standards for blood glucose meters. Maharashtra and Gujarat host emerging distribution networks for mobile app-integrated diabetes management platforms.
Diabetes Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across algorithmic differentiation and sensor manufacturing scale. The vendor base stratifies into three tiers: integrated system architects controlling insulin delivery algorithms, disposable sensor specialists capturing recurring revenue, and legacy meter manufacturers defending installed base positions. Consolidation pressures concentrate among standalone insulin pump producers facing sensor-integrated convergence. Dominant competitive moves include backward integration into sensor fabrication and strategic partnerships for cloud-connected data platforms.
Within the integrated system tier, Abbott Laboratories and Medtronic occupy positions as archetypal full-stack players combining sensing and delivery functions. Dexcom exemplifies the disposable sensor specialist archetype, while Tandem Diabetes Care represents the pump-centric competitor navigating convergence pressures. Roche and Novo Nordisk sit within the diversified healthcare conglomerate category, leveraging pharmaceutical insulin relationships for device distribution access. Insulet Corporation anchors the patch pump specialization segment.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Roche |
| Dexcom |
| Insulet Corporation |
| Novo Nordisk |
| Tandem Diabetes Care |
| Lifescan |
| Ascensia |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up sensor specialists have consolidated factory automation assets across the United States and Germany, compressing procurement leverage for downstream pump assemblers while sustaining premium pricing for disposable arrays through single-source dependencies. This ownership concentration feeds directly into subscription-based revenue models that lock hospital procurement groups into multi-year consumable replenishment cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated sensor-integrated pumps from Bluetooth-enabled standalone monitors and conventional capillary meters. Price differentiation rests on algorithmic sophistication and ISO 15197 certification tier, with premium tiers commanding software subscription attach rates exceeding lower tiers. Cost compression in the standalone pump segment is intensifying because sensor-integrated convergence is displacing modular architectures. Hospital procurement groups exhibit the highest price sensitivity, while pediatric endocrinology departments in academic medical centers demonstrate the lowest.
Supply Chain Analysis
Returns and refurbishment flows for reusable insulin pump components are concentrated in Baden-Württemberg's precision manufacturing corridor, where remanufacturing operations recover electromechanical subassemblies for redeployment in secondary markets. Geographic supply concentration centers on the United States, Germany, and China's Yangtze River Delta region for electrochemical sensor fabrication. Raw material dependencies include platinum-group catalysts for glucose oxidase electrodes, medical-grade polymers for subcutaneous insertion devices, and lithium-ion cells for pump power systems. Single-source vulnerability pervades high-volume disposable sensor production. Distribution runs through hospital procurement groups and group purchasing organizations in the United States, ambulatory care networks in Germany, and retail pharmacy chains in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetes devices market operates as a regulatory compounder, with FDA breakthrough device designation and EU MDR conformity requirements jointly elevating clinical evidence thresholds that permanently advantage incumbents with established quality management systems.
For Market Incumbents: Extend algorithmic differentiation through in-house control systems engineering capabilities, capturing hospital procurement group consolidation through bundled sensor-integrated pump contracts. Backward integration into electrochemical sensor fabrication secures supply security against disposable array supply concentration. Defend against emerging patch pump specialists by accelerating pediatric artificial pancreas pilot programs. For New Entrants and Emerging Players: Begin with underpenetrated rural and suburban United States populations where telehealth reimbursement infrastructure is maturing fastest, avoiding head-to-head contracting competition with consolidated hospital procurement groups in the Southeast and Midwest. Target mobile app-integrated platforms for home care settings, where software subscription architectures generate recurring revenue without capital equipment manufacturing scale. Pursue EU Green Deal sustainability-weighted procurement scoring as a first-mover differentiation lever. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone insulin pump manufacturers facing sensor-integrated convergence pressure, presenting acquisition targets with installed base positions convertible to artificial pancreas ecosystems. Long-term viability favors integrated system architects controlling both sensing and delivery algorithms over disposable sensor specialists vulnerable to manufacturing scale competition. Watch FDA breakthrough device designation velocity as the primary inflection indicator for reimbursement coding acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization cycles for sensor-integrated pump configurations. |
| CE Marking Pathway under EU MDR | Conformity assessment elevates clinical evidence thresholds favoring established quality management systems. |
| Hospital System Partnership | Multi-year automated insulin delivery contracts displace individual hospital negotiations in consolidated regions. |
| Software Companion Development | Mobile app-integrated platforms capture recurring subscription revenue through cloud-based metabolic dashboards. |
| Reimbursement Strategy | Early coding for hybrid closed-loop configurations secures favorable positioning with Medicare and commercial payers. |
Research Approach
Multiple input streams — hospital procurement contract databases, FDA 510(k) and breakthrough device filings, EU MDR notified body conformity assessments — were reconciled through structured primary interviews with hospital GPO contracts managers, biomedical engineers, and pediatric endocrinologists, validated against secondary sources including CMS Medicare reimbursement data, hospital supply chain disclosures, and ISO 15197 certification registries. Bottom-up demand modeling across patient population segments and top-down supply-side capacity analysis were triangulated to produce convergent estimates.
Data-stream reconciliation applied segmentation dimensions spanning product type, connectivity architecture, application urgency, and site-of-care economics across the analysis window. CAGRs were derived from installed base growth rates, replacement cycle compression, and software subscription attach rate trajectories. Forecast inputs incorporated FDA breakthrough designation velocity, EU MDR transition timelines, and telehealth reimbursement code expansion patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway revisions, supply chain disruptions from geopolitical events, and algorithm validation failures in pivotal trials. Forecasts reflect assumptions regarding sustained hospital procurement group consolidation and continued FDA breakthrough device pathway utilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Infant Incubator Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Global Cranial and Facial Implants Market