
 Cranial Perforator Market | 2026-2036
Cranial Perforator Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Perforator Market Analytics
Preventive maintenance contracts and software-defined depth-limiting features are decoupling hardware sales from recurring revenue streams in the cranial perforator space. Medtronic leverages its service infrastructure to lock in multi-year hospital agreements. Stryker Corporation anchors its competitive stance through specialized neurosurgical instrument portfolios. Johnson & Johnson (DePuy Synthes) differentiates via integrated operating room ecosystems that bundle perforators with navigation platforms.
A cranial perforator is a surgical instrument engineered to create controlled apertures in the skull vault, typically employing high-speed rotary cutting elements with adjustable depth stops measured in millimeters to prevent dural injury during neurosurgical access. Electric perforators dominate procedural throughput in busy neurosurgical suites, while disposable perforators capture expanding share in ambulatory settings where sterilization logistics constrain reusable workflows. Guided technology segments command premium positioning as stereotactic integration becomes standard in academic medical centers.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations govern commercial entry for cranial perforators in North America and Europe, with Japan's PMDA adding supplementary clinical evaluation standards for motorized variants. These layered compliance frameworks elevate R&D burn rates for new entrants while insulating incumbents with established quality management systems. Stakeholders must weigh capital deployment toward disposable platform scale against the defensibility of rechargeable systems with embedded usage analytics.
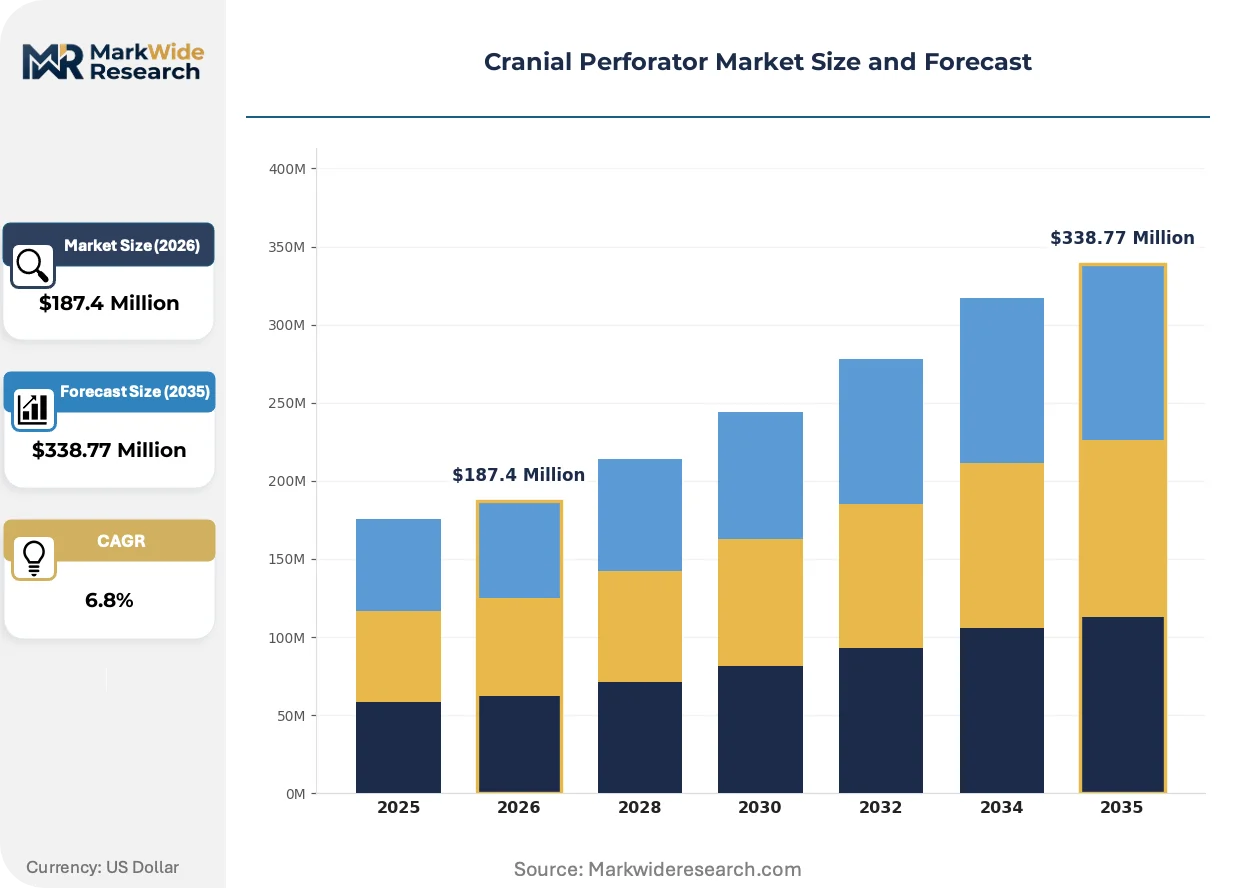
Market Dynamics
Software-defined depth-limiting mechanisms are decoupling hardware revenues from recurring service streams, forcing manufacturers to restructure commercial models around predictive maintenance contracts and usage analytics rather than capital equipment sales alone.
Growth Catalysts
- EU MDR technical documentation pathways:Harmonized conformity assessment procedures accelerate multi-country market entry for Class IIa motorized perforators, reducing redundant testing burdens across Germany, France, and Italy.
- Stereotactic navigation integration:Academic medical centers in the United States and Japan are mandating perforator compatibility with frameless guidance systems, elevating demand for instrumented cutting heads with real-time positional feedback.
- Ambulatory surgery center expansion:Single-use perforator adoption concentrates in outpatient neurosurgical facilities where sterilization infrastructure constraints favor disposable workflows over reprocessing logistics.
Market Restraints
- Tungsten carbide supply concentration:Cutting element fabrication depends on Chinese powder metallurgy suppliers, exposing manufacturers to export quota volatility and forced technology transfer requirements.
- FDA 510(k) predicate device dependencies:Substantial equivalence determinations for next-generation perforators hinge on legacy device clearances, creating regulatory path dependencies that slow iterative innovation cycles.
- Manual trephine substitution in resource-limited settings:Low-cost hand-cranked alternatives retain procedural share in secondary hospitals across India and Southeast Asia where capital equipment procurement budgets remain constrained.
Strategic Opportunities
- Brazilian ANVISA fast-track pathways:Priority review designations for neurosurgical instruments with novel safety mechanisms offer accelerated access to Latin America's largest elective cranial procedure market.
- AI-enabled cutting parameter optimization:Convergence of torque sensing arrays with machine learning algorithms enables real-time bone density adaptation, differentiating premium perforator portfolios in tertiary hospital tenders.
- Direct-to-hospital digital procurement platforms:Specialized surgical instrument marketplaces are disintermediating traditional distributor networks in Germany and Japan, compressing margin capture for middle-tier intermediaries.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for brushless motor control and safety interlock logic outpaces available neurosurgical device specialization in the United States and Switzerland.
- ISO 13485 quality management system certification timelines:New entrant manufacturers face 18-24 month implementation periods before notified body audits, delaying commercial launch schedules.
- Legacy sterilization protocol incompatibility:Rechargeable lithium-ion battery packs in next-generation electric perforators conflict with existing steam autoclave workflows, forcing capital investment in alternative low-temperature sterilization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Perforator Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Perforators, Manual Perforators, Disposable Perforators, Rechargeable Perforators End User: Hospitals, Ambulatory Surgical Centers, Neuro Clinics, Research Laboratories Technology: Guided Technology, Non-guided Technology, High-speed Technology, Laser Technology Material: Stainless Steel, Plastic, Biodegradable Materials, Titanium |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson (DePuy Synthes), Integra LifeSciences, B. Braun, Zimmer Biomet, NSK NAKANISHI INC., Nouvag AG, ACRA-CUT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Perforator Market Evolving Landscape
Active materials integration and predictive analytics are compressing the traditional boundary between cutting instrument and surgical navigation system, with manufacturers racing to embed intelligence at the point of bone contact.
Shape-memory alloy depth stops are rewriting safety architecture in high-speed cranial access. Nitinol-based mechanical limiters automatically arrest cutting progression at preset thresholds without electronic dependency. Tertiary neurosurgical departments in Germany and Japan are piloting these mechanisms for emergency burr hole procedures. The technology is rewriting liability allocation between device manufacturers and hospital risk management departments.
Japan's PMDA supplementary clinical evaluation standards for motorized surgical instruments now mandate post-market surveillance data submission for perforators with integrated irrigation systems. This regulatory expansion elevates documentation burdens for manufacturers seeking renewal approvals. Smaller device firms without established Japanese regulatory affairs infrastructure are partnering with local distributors to satisfy pharmacovigilance obligations.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, demanding itemized pricing for preventive maintenance, software updates, and consumable components. This disaggregation concentrates negotiating leverage with large integrated delivery networks in the United States that command volume-based discounts. The shift is most visible in academic medical center tenders where total cost-of-ownership models now dominate source selection criteria over upfront capital expenditure minimization.
Cranial Perforator Market Segmentation
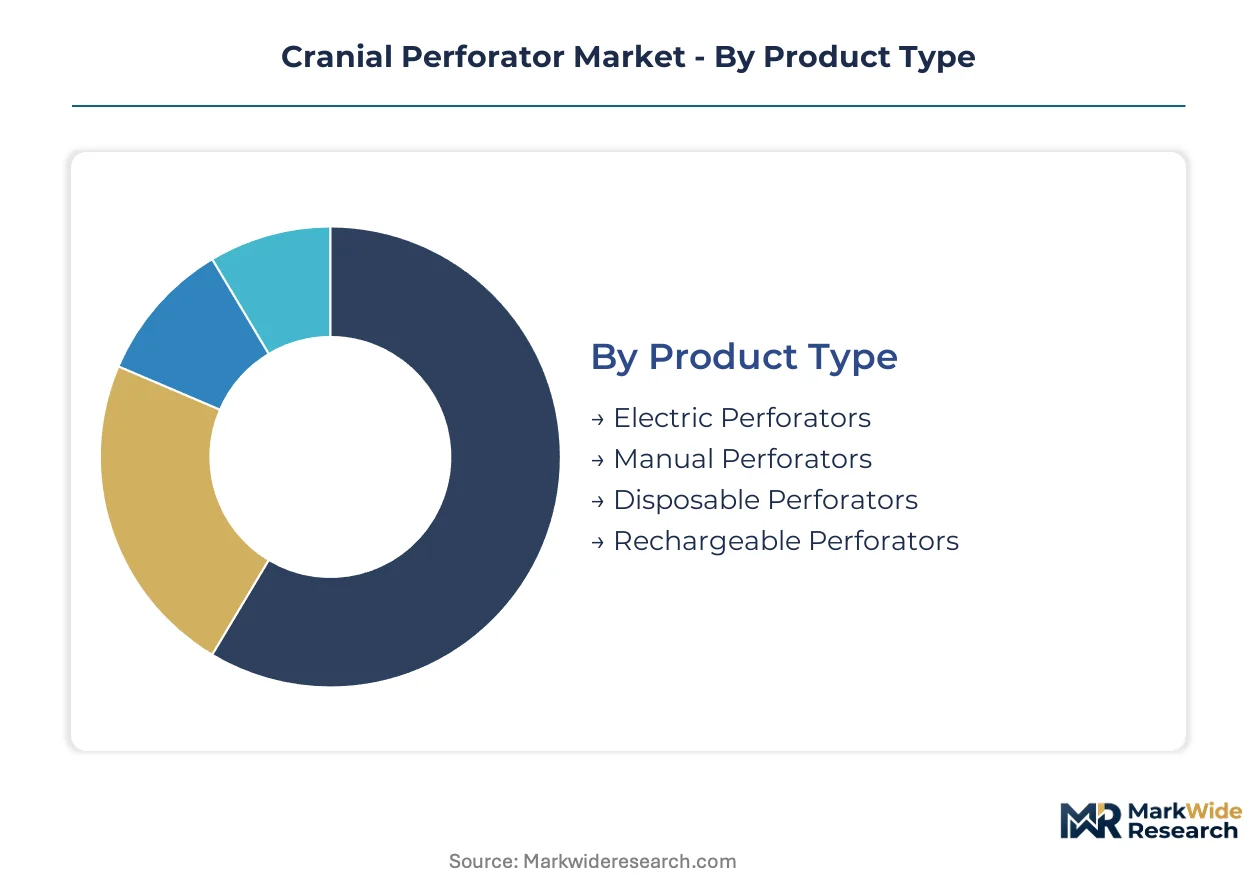
Cranial perforator procurement committees evaluate segments through divergent lenses: capital equipment buyers prioritize motor longevity and service infrastructure, while disposable adopters emphasize sterility assurance and per-procedure economics. Segmentation choices directly determine regulatory pathway complexity and margin structure.
Product Type:
FDA 510(k) clearance burdens cluster heavily on motorized variants with embedded electronics, while manual and single-use platforms navigate lighter documentation requirements.
- Electric Perforators:Brushless motor systems with adjustable RPM settings and integrated torque feedback dominate procedural throughput in United States tertiary hospitals. Academic medical centers in Germany and Japan specify these units for stereotactic navigation compatibility, though sterilization protocol conflicts with lithium-ion battery packs force infrastructure upgrades.
- Disposable Perforators:Pre-sterilized single-use units with fixed-depth mechanical stops eliminate reprocessing logistics. Ambulatory surgical centers across the United States favor this segment where sterilization infrastructure constraints limit reusable workflows.
- Manual Perforators:Hand-cranked trephine designs with tungsten carbide cutting edges serve resource-limited secondary hospitals in India where capital procurement budgets remain restricted.
- Rechargeable Perforators:Cordless lithium-ion systems with embedded usage analytics enable predictive maintenance contracting models.
Leading the category by volume: Electric Perforators. Growing fastest: Disposable Perforators.
End User:
Customer type determines pricing tolerance and contract structure, with integrated delivery networks extracting multi-year service bundles distinct from spot purchases by independent facilities.
- Hospitals:Tertiary neurosurgical departments with high cranial procedure volumes specify premium perforators with navigation integration and preventive maintenance agreements. United States academic medical centers drive demand for instrumented cutting heads with real-time positional feedback.
- Ambulatory Surgical Centers:Outpatient facilities prioritize single-use perforators to circumvent sterilization infrastructure investments and reprocessing labor costs.
- Neuro Clinics:Specialized cranial access centers concentrate in urban clusters of Germany and Japan where elective procedure volumes support dedicated equipment.
- Research Laboratories:Cadaveric training facilities and biomechanical testing centers procure perforators for surgical simulation and device validation studies.
Hospitals command the largest installed base. Ambulatory Surgical Centers are climbing the fastest.
Technology:
Technology tier correlates with reimbursement complexity, as guided systems require additional CPT coding documentation for navigation add-on payments.
- Guided Technology:Frameless stereotactic integration with optical tracking arrays and instrumented cutting heads commands premium positioning in academic medical centers. Japan's PMDA mandates supplementary clinical evaluation for these motorized variants with integrated irrigation.
- Non-guided Technology:Conventional freehand perforators with mechanical depth stops retain share in emergency settings where navigation setup time is prohibitive.
- High-speed Technology:RPM-optimized cutting elements with thermal management systems reduce bone necrosis risk during extended cranial access procedures.
- Laser Technology:Experimental photonic ablation systems for non-mechanical bone removal remain pre-commercial in neurosurgical applications.
Guided Technology holds the premium tier. High-speed Technology is gaining share fastest.
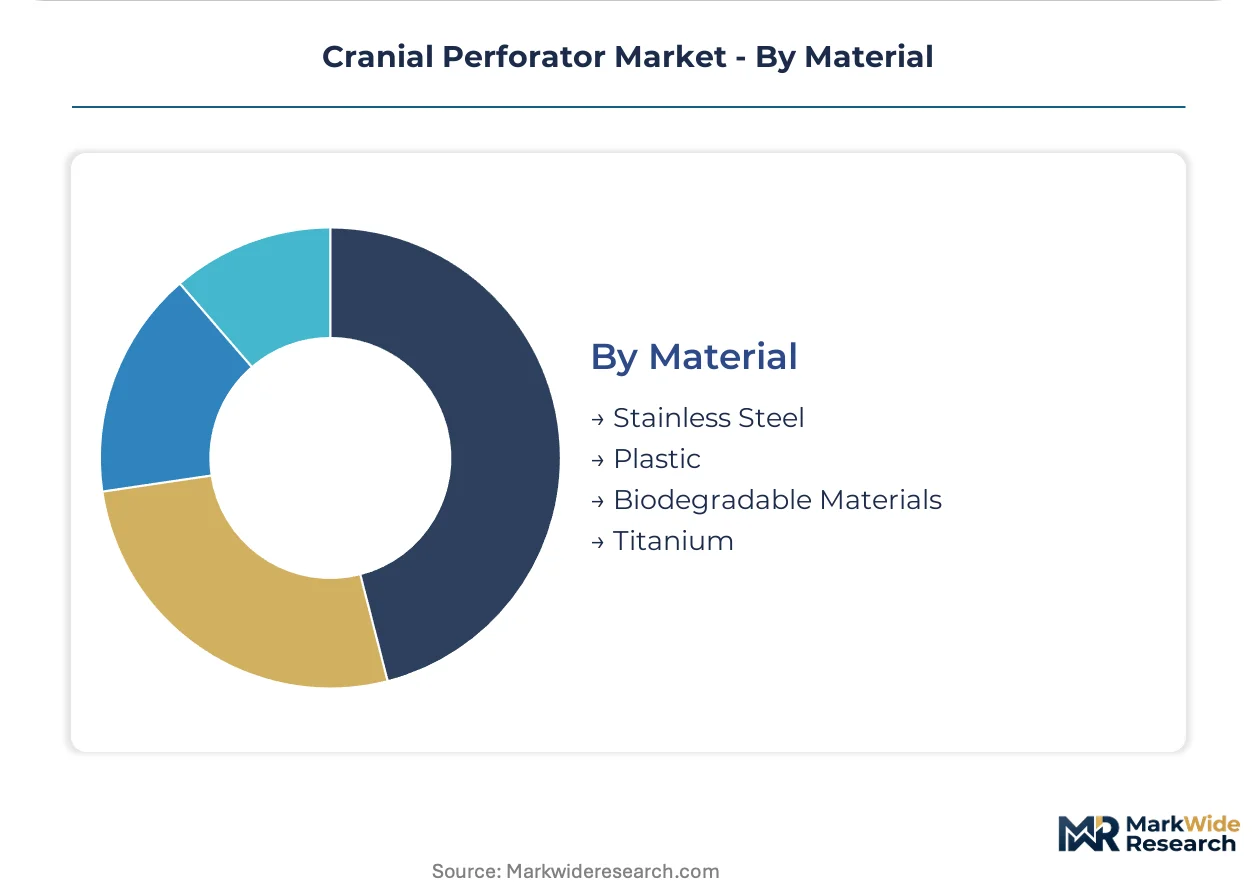
Material:
Material selection drives sterilization compatibility, biocompatibility certification burden, and supply chain exposure to commodity volatility.
- Stainless Steel:Austenitic grades with passivation layers dominate reusable perforator fabrication, though tungsten carbide insert dependence creates Chinese supply concentration risk.
- Titanium:Grade 5 Ti-6Al-4V alloys offer superior strength-to-weight ratios for extended surgical procedures with reduced operator fatigue.
- Plastic:Medical-grade polymers form housings and disposable cutting guards in single-use platforms.
- Biodegradable Materials:Polylactic acid and polyglycolic acid variants target experimental applications in temporary cranial access devices.
Stainless Steel anchors current production. Titanium shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Switzerland, and Japan where precision machining clusters serve neurosurgical instrument demand, while procedural volume leadership sits with the United States academic medical centers. Consumption patterns diverge sharply between high-volume tertiary hospitals in developed markets and resource-constrained secondary facilities in emerging economies.
United States
Tertiary neurosurgical departments at Mayo Clinic and Johns Hopkins drive demand for instrumented cutting heads with stereotactic navigation compatibility. FDA 510(k) clearance pathways for motorized perforators with embedded electronics impose substantial equivalence documentation burdens on new entrants. Boston and Rochester medical device corridors host service infrastructure supporting multi-year preventive maintenance contracts.
Germany
Academic medical centers in Heidelberg and Berlin specify premium electric perforators with real-time positional feedback for frameless guidance integration. EU MDR technical documentation requirements for Class IIa motorized devices accelerate multi-country market entry across France and Italy. Tuttlingen surgical instrument cluster anchors European production capacity for high-speed rotary cutting elements.
Japan
PMDA supplementary clinical evaluation standards for motorized perforators with integrated irrigation systems mandate post-market surveillance data submission for renewal approvals. Tokyo and Osaka neurosurgical centers pilot nitinol-based shape-memory alloy depth stops for emergency burr hole procedures. Kanto region device firms partner with local distributors to satisfy pharmacovigilance obligations.
Switzerland
Swissmedic quality management system oversight insulates incumbent manufacturers with established ISO 13485 certification against new entrant competition. Basel and Zurich precision engineering clusters specialize in brushless motor control firmware for next-generation rechargeable systems. Embedded systems engineering talent scarcity constrains firmware development velocity for safety interlock logic.
Brazil
ANVISA fast-track priority review designations for neurosurgical instruments with novel safety mechanisms offer accelerated access to Latin America's largest elective cranial procedure market. São Paulo and Rio de Janeiro hospital procurement committees unbundle service contracts from capital equipment purchases. Secondary hospitals in Northeast region retain manual trephine substitution where capital budgets remain restricted.
Cranial Perforator Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through integrated navigation ecosystems and multi-year service contracts, while mid-tier specialists compete on disposable platform scale and ambulatory surgery center penetration. The vendor base stratifies across three archetypes: diversified medtech conglomerates with neurosurgical portfolios, precision instrument specialists with regional manufacturing footprints, and disposable-focused entrants targeting outpatient workflows. Dominant competitive moves include preventive maintenance contract restructuring to capture recurring revenue and direct-to-hospital digital procurement platform deployment to disintermediate distributor networks.
Within the diversified medtech tier, Medtronic and Stryker Corporation exemplify service infrastructure scale, while Johnson & Johnson (DePuy Synthes) occupies a position emphasizing integrated operating room ecosystems. Among precision instrument specialists, NSK NAKANISHI INC. represents Japanese motor technology integration, and Nouvag AG anchors Swiss manufacturing heritage. These named entities sit within archetypes rather than defining them, with competitive dynamics driven by contract structure innovation and regulatory compliance velocity rather than product differentiation alone.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Integra LifeSciences |
| B. Braun |
| Zimmer Biomet |
| NSK NAKANISHI INC. |
| Nouvag AG |
| ACRA-CUT Inc. |
| Others |
Value Network & Pricing Analysis
Precision machining specialists in Tuttlingen and Basel anchor cranial perforator fabrication, with labor-cost differentials between Swiss firmware engineers and German metalworkers spreading pricing tiers across premium navigation-integrated systems and standard electric units.
Pricing Analysis
Margin tightening in mid-tier electric perforators reflects unbundling of service contracts by United States integrated delivery networks. Three-tier pricing structure across premium navigation-compatible, standard electric, and disposable economy levels stratifies the market. Pricing pressure accelerates as ambulatory surgery centers demand per-procedure economics over capital expenditure. Disposable adopters exhibit highest price sensitivity; academic medical centers purchasing navigation-integrated systems show lowest.
Supply Chain Analysis
Direct-to-hospital digital procurement platforms in Germany and Japan are compressing distributor margins while accelerating order cycles. Manufacturing concentrates in Germany, Switzerland, and Japan where precision machining clusters serve neurosurgical instrument demand. Cutting element fabrication draws from Chinese tungsten carbide powder metallurgy suppliers. Single-source vulnerability to export quota volatility constrains component security. Distribution runs through specialized surgical instrument marketplaces and traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
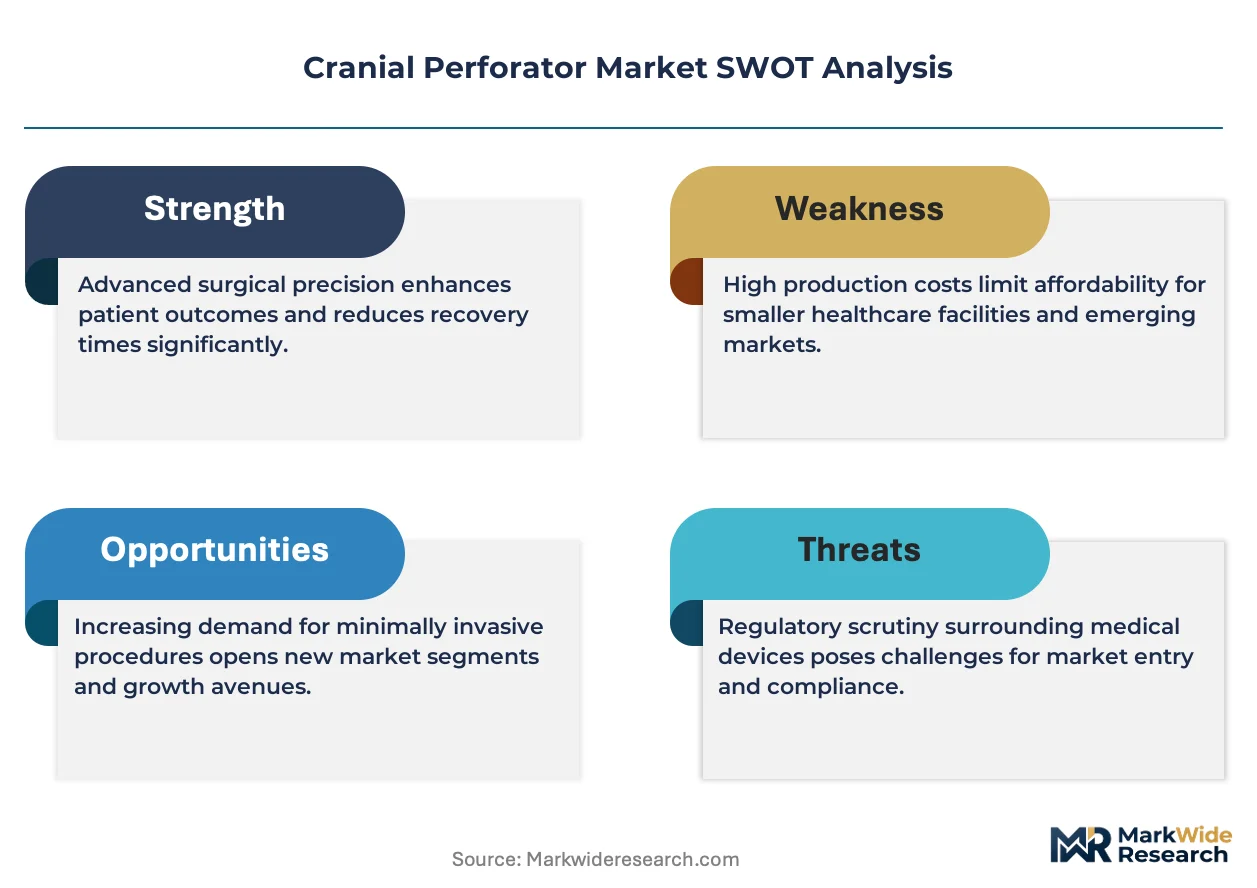
Cranial perforator competition is becoming a vertical-integration race, with firmware development capability and captive cutting element supply emerging as the decisive upstream levers.
For Market Incumbents: To counter disintermediation by direct-to-hospital procurement platforms, Medtronic and Stryker Corporation should deepen captive supply of tungsten carbide cutting elements through backward integration into powder metallurgy partnerships. Locking multi-year preventive maintenance contracts with United States academic medical centers defends against disposable platform erosion in ambulatory settings. For New Entrants and Emerging Players: ANVISA fast-track pathways in Brazil open a window for novel safety mechanism innovators to establish beachheads before diversified medtech conglomerates consolidate Latin American distribution. Targeting Brazilian secondary hospitals with rechargeable perforators bypasses sterilization infrastructure conflicts that burden electric variants. Partnership with local distributors satisfies pharmacovigilance obligations without capital-intensive regulatory affairs buildout. For Investors and Strategic Acquirers: Re-rating potential sits with precision instrument specialists possessing ISO 13485 certification and established Japanese regulatory affairs infrastructure given PMDA's supplementary clinical evaluation expansion for motorized variants. Long-term viability hinges on software-defined depth-limiting patent estates and predictive maintenance contract attach rates. Watch for ANVISA priority review designation announcements as inflection indicators for emerging market penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Substantial equivalence documentation for motorized variants with embedded electronics unlocks United States tertiary hospital access. |
| EU MDR Technical Documentation | Harmonized conformity assessment accelerates multi-country entry across Germany, France, and Italy. |
| Hospital System Partnership | Multi-year preventive maintenance agreements with academic medical centers insulate against disposable platform substitution. |
| Software Companion Development | Embedded usage analytics enable predictive maintenance contracting and recurring revenue capture. |
| Reimbursement Strategy | CPT coding documentation for navigation add-on payments supports guided technology premium positioning. |
Research Methodology
Independent corroboration across neurosurgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with regulatory affairs specialists at notified bodies and PMDA consultants cross-validated secondary sources including FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates.
Rate-of-change decomposition across product type, end user, technology tier, and material grade segments structured the analytical framework. CAGRs were derived from procedure volume elasticity to cranial access device replacement cycles and navigation system penetration curves. Forecast inputs incorporated stereotactic integration adoption trajectories and ambulatory surgery center expansion patterns across the analysis window.
Caveats apply where FDA predicate device dependencies, tungsten carbide export quota volatility, or lithium-ion battery sterilization protocol conflicts could materially shift the outlook. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Drills Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Blood Thawing System Market
Medical Devices
North America Wearable Medical Devices Market