
 Autologous Wound Patches Market | 2026-2036
Autologous Wound Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Autologous Wound Patches Market Intelligence
North American manufacturing capacity is tilting toward regenerative tissue platforms as domestic biologics infrastructure scales. PolarityTE leverages proprietary tissue engineering to anchor its position in autologous skin regeneration. Organogenesis sustains commercial scale through its established wound care portfolio, while Vericel Corporation differentiates via cell therapy specialization in burn and surgical applications.
Autologous wound patches are implantable or topical constructs derived from a patient's own cells or tissues, typically comprising keratinocytes, fibroblasts, or extracellular matrix proteins manufactured through bioreactor expansion or direct tissue harvesting techniques, designed to accelerate closure of full-thickness wounds and reduce rejection risk. Biological patches dominate current revenue given established reimbursement pathways, though cell therapy patches represent the fastest-expanding margin pool as personalized medicine protocols gain traction. Surgical wounds and chronic ulcers command the largest application volumes, while ambulatory surgical centers are emerging as a high-growth end user channel shifting procedures away from inpatient settings.
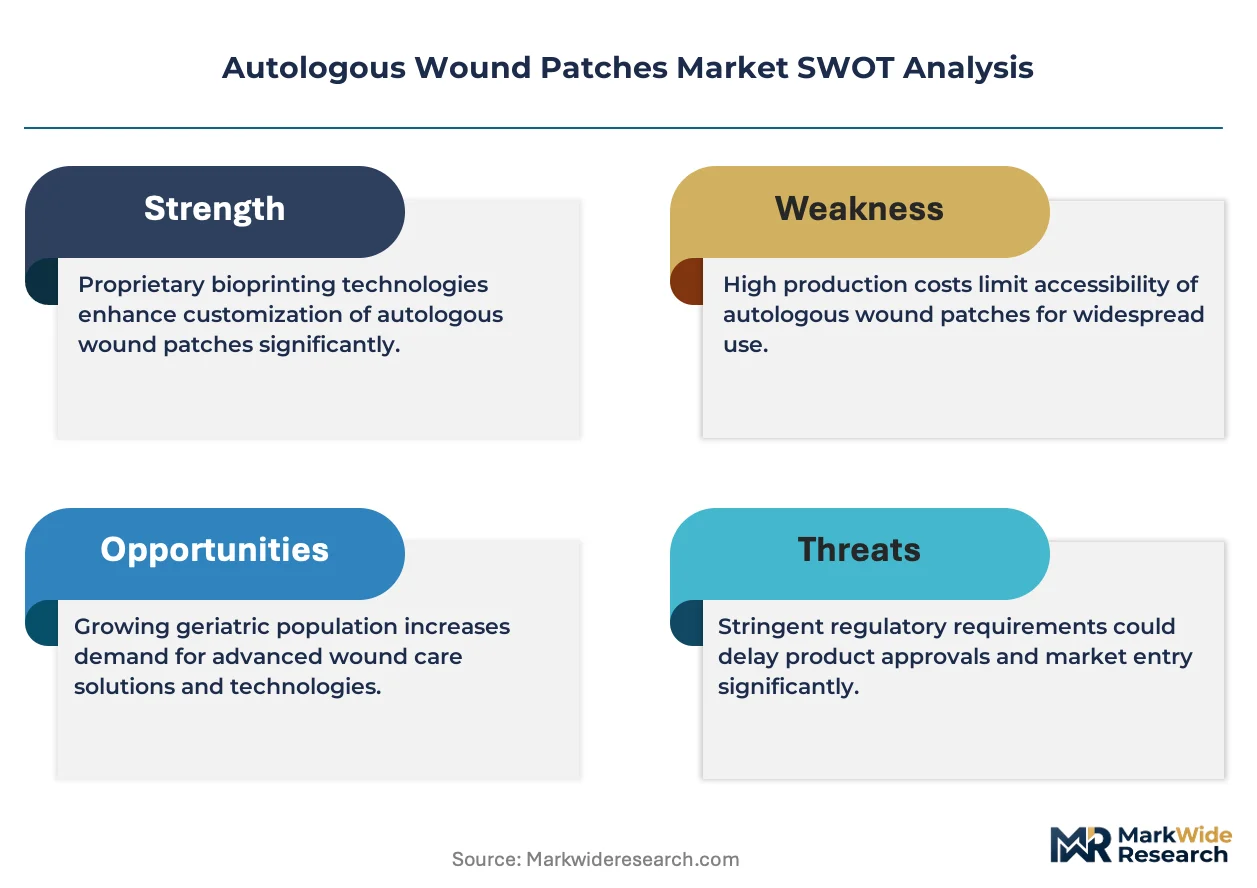
FDA oversight through its Center for Biologics Evaluation and Research shapes product development timelines and clinical trial requirements for autologous cell-based therapies in the United States. The EU Medical Device Regulation and EMA frameworks impose stringent quality system standards that filter market access for patch manufacturers seeking European commercialization. Stakeholders must monitor evolving regenerative medicine advanced therapy designations and parallel reimbursement negotiations across multiple jurisdictions to secure sustainable market positioning.
Market Dynamics
EU Medical Device Regulation compliance deadlines are compressing commercialization timelines for patch manufacturers, forcing simultaneous bioreactor scaling and quality system overhauls across European manufacturing networks.
Growth Catalysts
- Aging demographics:Japan's patient population above 65 drives concentrated demand for cell therapy patches in chronic ulcer management. Hospital procurement committees prioritize autologous solutions to reduce rejection complications.
- REACH-aligned biomaterial standards:European chemical safety frameworks accelerate adoption of synthetic extracellular matrix alternatives. Manufacturers reformulate patch substrates to preempt regulatory friction.
- Ambulatory surgical migration:Outpatient procedure volume expansion in German burn treatment centers creates dedicated procurement channels for point-of-care grafting systems.
Market Restraints
- Bioreactor capital intensity:Cell expansion infrastructure requires specialized stainless steel vessels and cleanroom suites. Equipment lead times extend 18-24 months from European suppliers.
- Fibroblast sourcing concentration:Donor tissue networks cluster in metropolitan hospital systems. Rural access gaps limit manufacturing site flexibility.
- Allogeneic substitute pressure:Cryopreserved cadaveric skin products compete on immediate availability. Price-sensitive health systems default to off-the-shelf alternatives for emergency coverage.
Strategic Opportunities
- India's CDSCO fast-track pathway:Regenerative medicine advanced therapy designations offer abbreviated clinical trial requirements. Early entrants secure manufacturing partnerships with domestic hospital chains.
- 3D bioprinting convergence:Layered deposition of patient-derived keratinocytes enables geometrically complex wound coverage. Research hospitals pilot integrated scanning-printing workflows.
- Direct-to-hospital distribution:Cold chain logistics platforms bypass wholesale intermediaries. Temperature-controlled last-mile networks preserve cell viability for same-day surgical scheduling.
Industry Challenges
- Cell culture technician scarcity:GMP-grade aseptic processing requires specialized certification. Training programs at German technical universities cannot match hiring demand from expanding manufacturing facilities.
- EMA variation procedure complexity:Post-approval manufacturing changes trigger multi-month review cycles. Process improvements for yield optimization face delayed implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autologous Wound Patches Market |
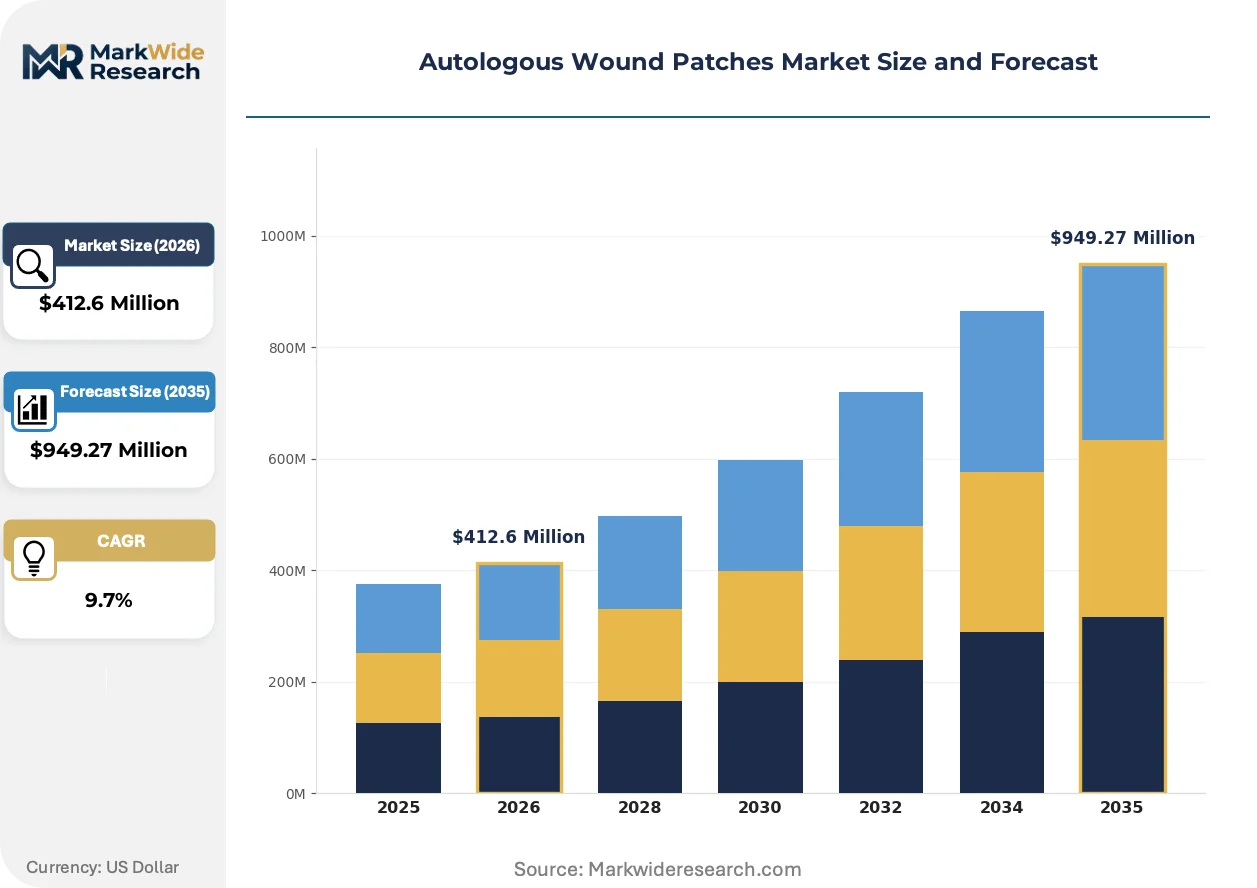
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological Patches, Synthetic Patches, Combination Patches, Cell Therapy Patches Application: Burn Treatment, Surgical Wounds, Chronic Ulcers, Traumatic Injuries Delivery Mode: Topical Application, Injectable Solutions, Surgical Implantation, Autologous Grafting End User: Hospitals, Ambulatory Surgical Centers, Dermatology Clinics, Home Care |
| Companies Covered | PolarityTE, Reapplix, Organogenesis, Terumo Corporation, Arthrex, Inc., MiMedx Group, Inc., Smith & Nephew, Integra LifeSciences Holdings Corporation, Vericel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autologous Wound Patches Market Strategic Shifts & Innovations
Digital integration across manufacturing and clinical workflows is compressing batch release timelines while enabling real-time quality monitoring throughout the autologous patch production chain.
Bioreactor control systems are digitizing process parameter tracking for temperature, pH, and dissolved oxygen across cell expansion phases. German manufacturers deploy these platforms to satisfy EMA audit requirements for continuous process verification. The technology is digitizing documentation burden, reducing manual batch record review from weeks to days.
EU MDR Article 10 technical documentation mandates force comprehensive clinical evidence packages for legacy patch products. Manufacturers must retrospectively compile post-market surveillance data or conduct new investigations. Burn treatment applications face the steepest compliance climb due to limited historical randomized trial infrastructure.
Hospital value analysis committees now require head-to-head cost-effectiveness modeling against standard of care. Procurement teams in Japanese academic medical centers demand episode-based budget impact projections. This behavioral shift favors vendors with health economics capabilities over traditional device sales organizations.
Autologous Wound Patches Market Segmentation
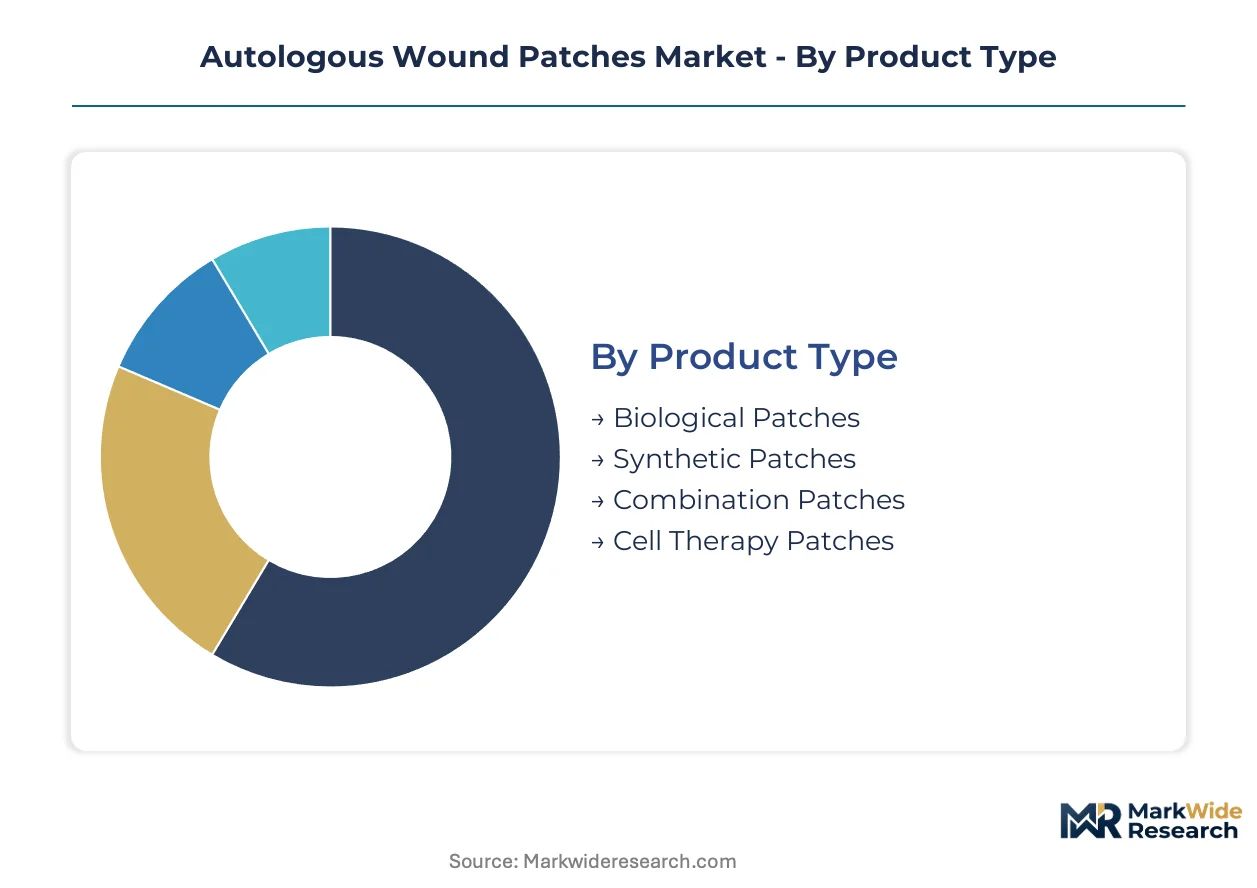
Segmentation in autologous wound patches reveals how reimbursement pathways, procedural settings, and cellular manufacturing complexity create distinct commercial battlegrounds. Each dimension carries divergent margin profiles and regulatory burdens that reshape vendor positioning.
Product Type:
Cost tiers separate legacy biological substrates from emerging cell therapy platforms with divergent manufacturing capital requirements.
- Biological Patches:Derived from autologous extracellular matrix proteins or processed dermal tissue, these constructs leverage established harvesting protocols and shorter production cycles. Hospital procurement committees in Germany prioritize these patches for burn treatment centers where reimbursement certainty outweighs premium pricing for novel platforms.
- Cell Therapy Patches:Manufactured through bioreactor expansion of patient-derived keratinocytes and fibroblasts, these personalized constructs require GMP-grade cleanroom infrastructure and 2-3 week turnaround timelines. Japan's aging patient population above 65 drives concentrated demand as academic medical centers adopt personalized medicine protocols for chronic ulcer management.
- Synthetic Patches:Engineered from biodegradable polymers mimicking native extracellular matrix architecture, offering standardized shelf stability and immediate availability.
- Combination Patches:Hybrid constructs integrating biological scaffolds with synthetic structural elements, targeting complex wound geometries requiring mechanical reinforcement.
Biological patches command the established base. The steepest expansion runs through cell therapy patches.
Application:
Procedure volume and wound severity create divergent customer relationships across acute versus chronic care pathways.
- Surgical Wounds:Post-operative incision management in orthopedic and cardiothoracic procedures generates predictable, high-volume demand. Ambulatory surgical centers in the United States are expanding procurement of point-of-care grafting systems as outpatient migration accelerates procedure volume outside traditional hospital settings.
- Burn Treatment:Full-thickness thermal injuries require immediate grafting coverage to prevent sepsis and contracture formation. German burn centers are expanding procurement of autologous grafting systems following EU Medical Device Regulation framework implementation, prioritizing rejection-risk reduction in pediatric and immunocompromised patient cohorts.
- Chronic Ulcers:Diabetic foot and venous stasis ulcers in elderly populations demand repeated application cycles, creating recurring revenue streams for wound care specialists.
- Traumatic Injuries:Acute mechanical tissue loss from industrial accidents or combat wounds requires rapid deployment capabilities and cold chain logistics for emergency surgical scheduling.
Surgical wounds anchor volume concentration. Burn treatment gains share fastest as specialized center networks expand procurement autonomy.
Delivery Mode:
Customer type and procedural setting dictate technical sophistication requirements and distribution channel complexity.
- Topical Application:Pre-formed sheet constructs applied directly to wound beds by clinical staff without surgical intervention, dominating dermatology clinic and home care segments.
- Surgical Implantation:Suture-integrated patches requiring operative suite placement, capturing premium pricing in hospital-based reconstructive procedures.
- Injectable Solutions:Cell suspensions delivered via syringe into wound margins, enabling minimally invasive application in outpatient settings with reduced anesthesia requirements.
- Autologous Grafting:Direct tissue harvest and immediate transfer protocols, preserving viability through specialized transport containers for same-day surgical scheduling.
Surgical implantation retains the premium tier. Injectable solutions climb the fastest as ambulatory migration reduces inpatient dependency.
End User:
Procurement authority and reimbursement mechanism concentration vary sharply across institutional versus decentralized care settings.
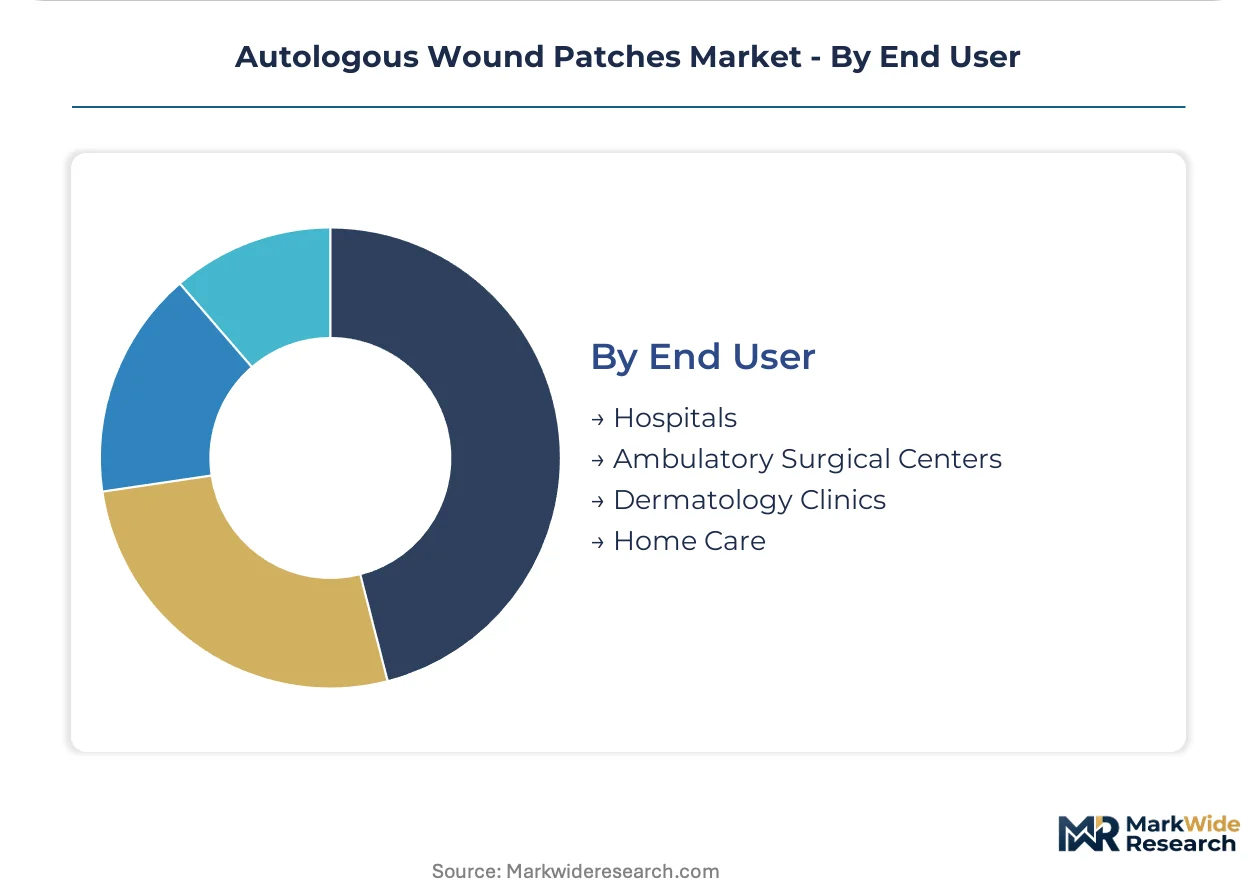
- Hospitals:Academic medical centers and integrated delivery networks command bulk purchasing leverage through value analysis committees demanding head-to-head cost-effectiveness modeling against standard of care.
- Ambulatory Surgical Centers:Freestanding outpatient facilities are emerging as high-growth channels shifting procedures away from inpatient settings, creating dedicated procurement pathways for point-of-care grafting systems with compressed scheduling requirements.
- Dermatology Clinics:Specialized wound care practices focusing on chronic ulcer management with recurring patient relationships and direct-to-physician distribution relationships.
- Home Care:Skilled nursing and patient-directed application settings requiring simplified handling protocols and extended shelf stability for non-clinical environments.
Hospitals maintain volume leadership. Ambulatory surgical centers represent the fastest-expanding channel as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioreactor manufacturing clusters concentrate in Germany and Japan where GMP-grade cleanroom infrastructure supports cell expansion workflows. United States academic medical centers anchor North American demand through specialized burn center networks. India's CDSCO fast-track pathway is drawing contract manufacturing investment from multinational patch developers.
United States
FDA Center for Biologics Evaluation and Research oversight shapes clinical trial timelines for autologous cell therapies. Hospital value analysis committees in academic medical centers demand head-to-head cost-effectiveness modeling against standard of care. Boston and San Diego biotech corridors host contract manufacturing organizations scaling GMP-grade cleanroom capacity for patch production.
Germany
Burn treatment centers in Munich and Berlin are expanding procurement of autologous grafting systems following EU Medical Device Regulation framework implementation. EMA quality system standards filter market access for patch manufacturers seeking European commercialization. Technical universities in Baden-Württemberg struggle to match hiring demand for GMP-certified cell culture technicians from expanding manufacturing facilities.
Japan
Patient population above 65 drives concentrated demand for cell therapy patches in chronic ulcer management at academic medical centers. PMDA regenerative medicine frameworks accelerate approval pathways for personalized autologous constructs. Osaka and Tokyo hospital procurement committees prioritize rejection-risk reduction in elderly diabetic foot ulcer cases.
India
CDSCO fast-track designations offer abbreviated clinical trial requirements for regenerative medicine advanced therapies. Domestic hospital chains in Maharashtra and Karnataka are securing manufacturing partnerships with early entrant patch developers. Mumbai pharmaceutical clusters provide contract bioreactor capacity for regional production scale-up.
United Kingdom
NHS specialized commissioning frameworks determine reimbursement access for advanced wound care biologics. MHRA post-Brexit regulatory autonomy enables tailored pathways for autologous tissue-engineered products. London and Cambridge regenerative medicine hubs coordinate clinical trial networks for patch efficacy validation.
Autologous Wound Patches Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying bioreactor vessels and cleanroom infrastructure. The vendor base stratifies across three tiers: multinational wound care conglomerates with established distribution networks, mid-cap cell therapy specialists with GMP manufacturing capabilities, and emerging biotech firms leveraging 3D bioprinting convergence. Dominant competitive moves include strategic partnerships between patch developers and hospital systems for direct-to-site distribution, plus capacity expansion into ambulatory surgical center channels.
Among tissue engineering specialists, PolarityTE and Vericel Corporation occupy positions in the autologous skin regeneration segment, while Organogenesis anchors the established wound care portfolio tier. These firms exemplify divergent strategic archetypes: proprietary platform development versus commercial scale through diversified biologics portfolios. Terumo Corporation represents the medical device conglomerate entry point, leveraging existing surgical product distribution for grafting system placement.
| Leading Market Players |
|---|
| PolarityTE |
| Reapplix |
| Organogenesis |
| Terumo Corporation |
| Arthrex, Inc. |
| MiMedx Group, Inc. |
| Smith & Nephew |
| Integra LifeSciences Holdings Corporation |
| Vericel Corporation |
| Others |
Cost & Logistics Intelligence
German bioreactor vessel manufacturers anchor upstream supply concentration, concentrating margin capture in stainless steel fabrication and cleanroom infrastructure while downstream patch developers compete on GMP certification tiers and turnaround speed.
Pricing Analysis
EU Medical Device Regulation dictates the pricing tier structure across biological, cell therapy, and synthetic patch categories. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified cell therapy platforms from processed dermal tissue constructs and off-the-shelf synthetic alternatives. Price differentiation centers on certification grade and volume scale, with academic medical centers commanding volume discounts while ambulatory surgical centers absorb premium markups for compressed scheduling. Pricing pressure stems from allogeneic substitute availability, as cryopreserved cadaveric skin products compete on immediate availability. Price-sensitive health systems in rural markets default to off-the-shelf alternatives, while pediatric and immunocompromised cohorts at German burn centers demonstrate lowest price sensitivity due to rejection-risk prioritization.
Supply Chain Analysis
Extended payment terms from German hospital procurement committees strain working capital for patch developers, forcing supply-chain finance facilities to bridge bioreactor scaling investments. Geographic supply concentrates in Germany, Japan, and the United States, with Munich and Berlin hosting GMP-grade cleanroom clusters, Osaka and Tokyo anchoring cell expansion infrastructure, and Boston and San Diego corridors scaling contract manufacturing. Raw material dependencies center on stainless steel bioreactor vessels, donor tissue networks, and synthetic extracellular matrix polymers. Single-source vulnerability runs through European equipment suppliers where 18-24 month lead times constrain capacity expansion. Distribution runs through direct-to-hospital cold chain logistics, bypassing wholesale intermediaries to preserve cell viability for same-day surgical scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autologous wound patches represent high-growth disruption as 3D bioprinting convergence and EU MDR compliance deadlines simultaneously compress commercialization timelines and expand addressable wound geometries.
For Market Incumbents: Build regulatory certification moats by accelerating EMA quality system investments ahead of Article 10 technical documentation mandates. Secure backward integration into donor tissue networks to preempt fibroblast sourcing concentration risks from metropolitan hospital systems. Add bioreactor capacity in Baden-Württemberg to capture GMP-certified technician pipelines before technical university output constraints worsen. Channel control through direct-to-hospital distribution partnerships defends margin position against allogeneic substitute pressure in price-sensitive health systems. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO fast-track pathway by securing manufacturing partnerships with domestic hospital chains in Maharashtra and Karnataka. Target ambulatory surgical centers in the United States as the most penetrable channel, where outpatient migration creates procurement autonomy absent from integrated delivery network value analysis committees. White-space exists in injectable cell suspension formats for dermatology clinics, where minimally invasive application reduces anesthesia requirements and infrastructure investment. Go-to-market angle should emphasize episode-based budget impact projections aligned with Japanese academic medical center procurement committee demands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap cell therapy specialists holding GMP manufacturing capabilities but lacking health economics infrastructure for hospital value analysis committee engagement. Long-term viability over the projection horizon hinges on regenerative medicine advanced therapy designation accumulation and parallel reimbursement negotiations across multiple jurisdictions. Acquisition target archetype: platform developers with proprietary tissue engineering IP and established burn center relationships. Signal to watch is EMA variation procedure throughput for post-approval manufacturing changes, indicating regulatory relationship depth and process improvement agility.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct-to-site distribution with German burn centers secures procurement commitment ahead of EU MDR compliance deadlines. |
| Manufacturing Scale-Up | GMP-grade cleanroom expansion in Baden-Württemberg addresses technician scarcity constraining bioreactor deployment. |
| Regulatory Approval Pathway | CDSCO fast-track designation in India abbreviates clinical trial requirements for regenerative medicine advanced therapies. |
| Platform Integration | 3D bioprinting convergence with patient-derived keratinocytes enables geometrically complex wound coverage workflows. |
| Reimbursement Strategy | Episode-based budget impact projections satisfy Japanese academic medical center value analysis committee demands. |
Research Approach
Initial hypotheses were tested against primary input from GMP manufacturing directors, hospital procurement managers, burn center clinicians, and cell culture technicians and refined through secondary validation. Primary interviews captured bioreactor scaling constraints, EMA audit preparation timelines, and value analysis committee behavioral shifts. Secondary sources included FDA Center for Biologics Evaluation and Research filings, EMA quality system guidance documents, EU Medical Device Regulation technical documentation requirements, and hospital procurement database contract terms. Bottom-up patch volume estimates by product type and application were triangulated against top-down market size calculations.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling patient population demographics, procedure migration trends, and manufacturing capacity expansion trajectories. Segmentation dimensions included product type, application, delivery mode, and end user, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from regression analysis of historical procurement data and forward-looking capacity announcements. Industry-specific forecast inputs captured bioreactor vessel lead times from European suppliers and CDSCO approval pathway throughput rates.
Sensitivities concentrate around EU MDR compliance deadline adherence, GMP-certified technician training program expansion rates, and allogeneic substitute pricing dynamics. Forecasts reflect assumptions regarding reimbursement pathway stability and regenerative medicine advanced therapy designation accumulation pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Global Active Wound Care Market
Wound Care
Wound Closure Strips Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
US Burn Care Centers Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Vascular Dressings Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Wound Cleanser Products Market
Wound Care
Wound Care Market
Wound Care
Pressure Bandages Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Advanced Wound Care and Dressings Market