
 Organ Preservation Solutions Market | 2026-2036
Organ Preservation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Preservation Solutions Market Outlook
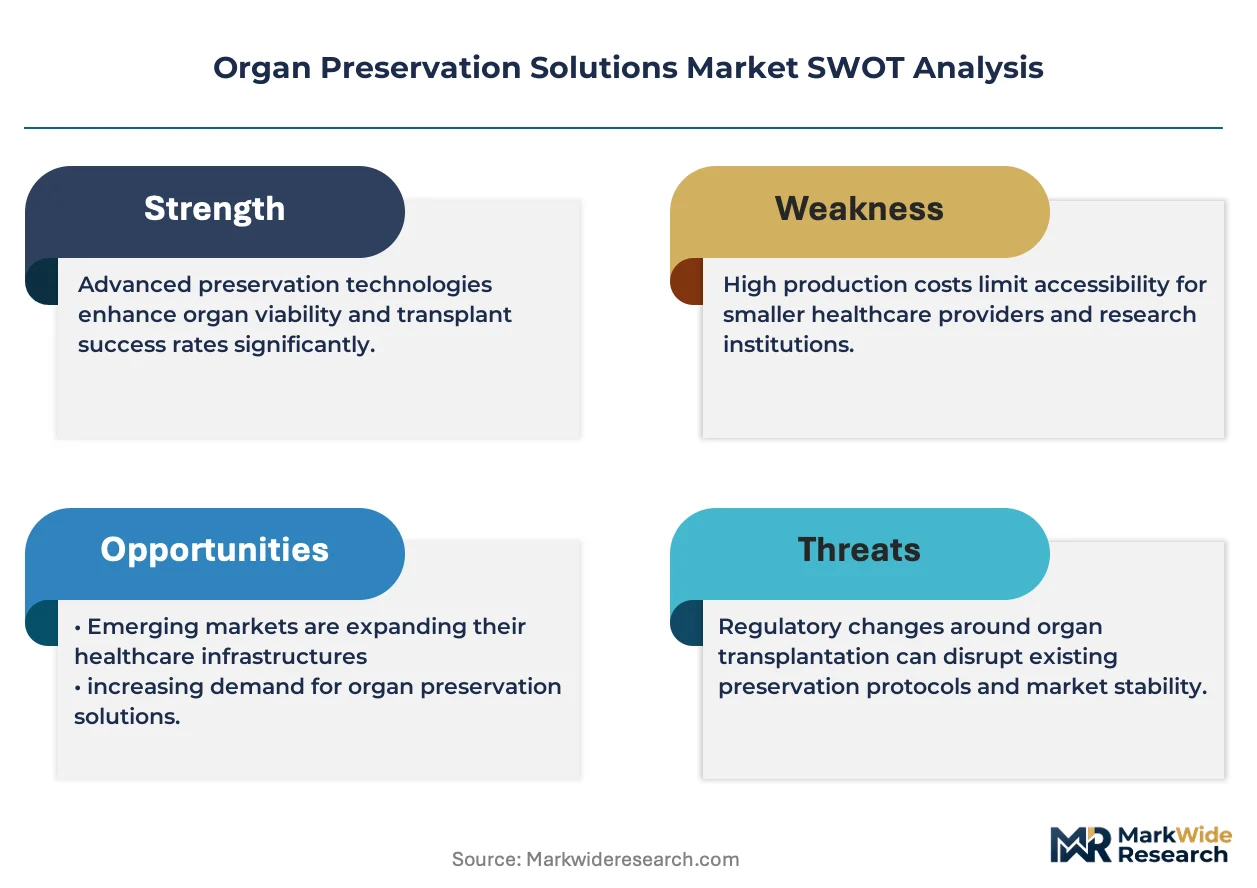
Machine perfusion technology is fragmenting the traditional cold-storage paradigm that has defined organ logistics for decades. TransMedics anchors its competitive stance through integrated organ care systems that extend viable preservation windows for hearts and lungs. XVIVO Perfusion specializes in ex-vivo lung perfusion platforms that differentiate its portfolio from conventional static solution vendors. Paragonix Technologies competes through proprietary hypothermic transport devices that control temperature gradients during donor organ transit.
Organ preservation solutions are sterile, biocompatible fluid formulations designed to maintain cellular viability and metabolic homeostasis in explanted organs during the interval between procurement and transplantation, typically containing colloids, electrolytes, and membrane-stabilizing agents to prevent ischemia-reperfusion injury. Static preservation solutions occupy the largest volume share due to their lower per-procedure cost and established clinical familiarity across transplant programs worldwide. Machine perfusion systems represent the fastest-expanding segment as evidence accumulates for improved graft survival in marginal donor organs, particularly in kidney and liver transplants where extended criteria donors are rising. Hypothermic preservation solutions sustain margin pools in emerging transplant programs that lack capital infrastructure for dynamic perfusion platforms.
FDA premarket notification pathways and EMA medical device regulations shape product development timelines and clinical evidence requirements for perfusion system manufacturers seeking multi-jurisdiction market access. CMS reimbursement codes in the United States and NICE technology appraisals in the United Kingdom directly influence hospital procurement decisions and adoption velocity for premium preservation technologies. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA on perfusion device classification standards, as divergence in clinical trial expectations could fragment commercialization strategies across Atlantic markets.
Market Dynamics
Machine perfusion systems are fragmenting the cold-storage paradigm that has dominated organ logistics for decades, creating parallel procurement tracks where transplant centers now evaluate static solutions against dynamic platforms based on donor organ quality rather than budget constraints alone.
Growth Catalysts
- CMS reimbursement expansion:Updated billing codes in the United States now cover machine perfusion for extended criteria donor kidneys, accelerating hospital capital investment cycles.
- Marginal donor utilization:Rising diabetes and obesity prevalence expands the pool of organs requiring dynamic preservation to remain transplantable.
- Hypothermic oxygenated perfusion:This technique is demonstrating superior graft function outcomes in liver transplantation, driving protocol adoption at academic medical centers.
Market Restraints
- Capital infrastructure requirements:Machine perfusion platforms demand USD 150,000-400,000 per unit plus dedicated technician staffing, freezing out programs in lower-middle-income health systems.
- Perfusion solution supply concentration:Three manufacturers control over 80% of proprietary perfusate formulations, creating single-source vulnerability for transplant programs.
- Cold ischemia time tolerance:Hearts and lungs remain technically constrained to four-hour preservation windows regardless of method, limiting addressable organ categories.
Strategic Opportunities
- Indian tertiary care expansion:Government-funded transplant infrastructure buildout creates first-mover advantage for perfusion system vendors willing to establish local service networks.
- Normothermic regional perfusion:Combining this technique with ex-vivo machine perfusion is opening donation-after-circulatory-death heart procurement previously deemed non-viable.
- Portable perfusion miniaturization:Battery-operated transportable units are enabling organ retrieval from remote donor hospitals lacking on-site preservation capability.
Industry Challenges
- Perfusionist workforce scarcity:Certified specialists capable of operating complex organ care systems number fewer than 2,000 globally, constraining program expansion velocity.
- FDA-EMA classification divergence:Perfusion devices face inconsistent regulatory pathways across Atlantic markets, forcing manufacturers to maintain parallel clinical evidence packages.
- Legacy cold storage integration:Hybrid workflows requiring coordination between static and dynamic preservation teams generate operational friction during multi-organ retrievals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Preservation Solutions Market |
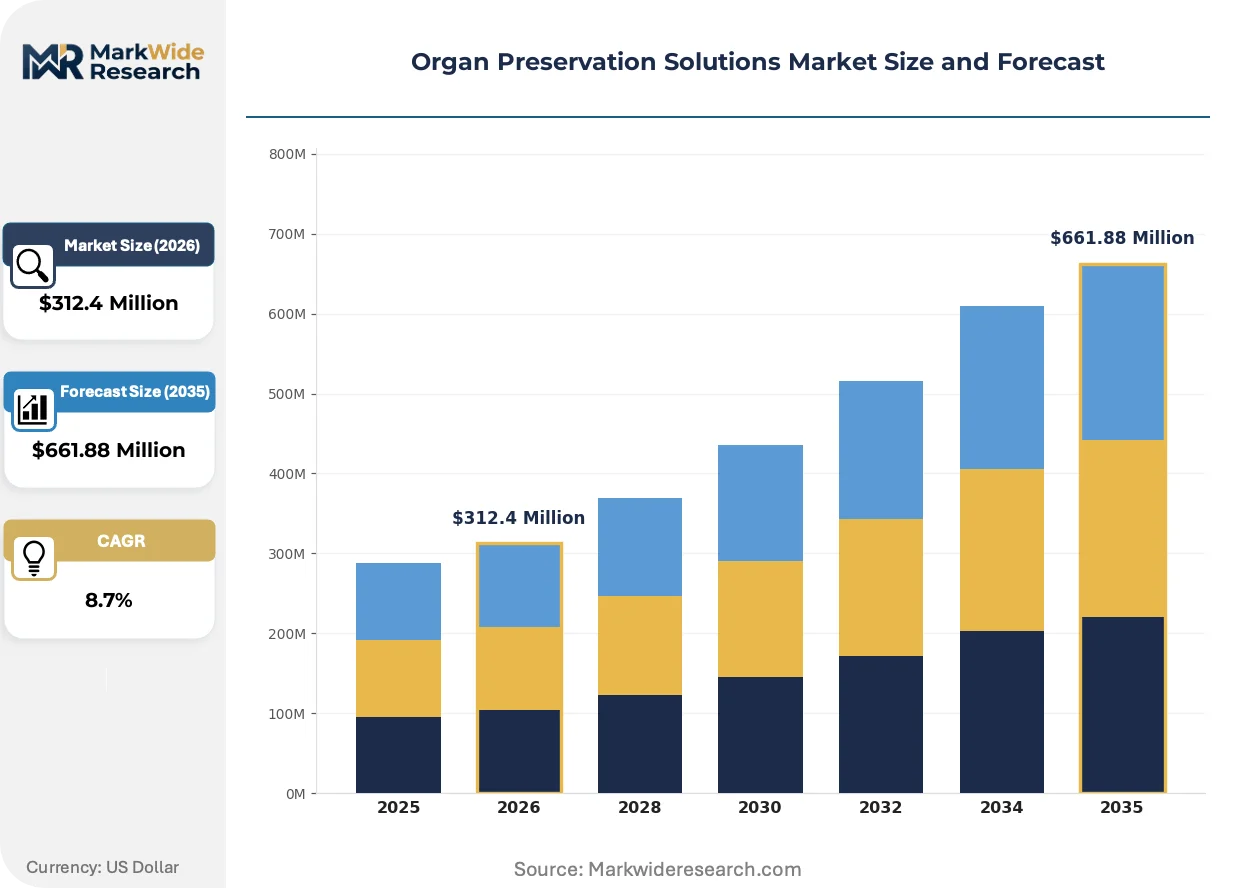
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Preservation Solutions, Dynamic Preservation Solutions, Hypothermic Preservation Solutions, Machine Perfusion Systems Application: Kidney Transplants, Liver Transplants, Heart Transplants, Lung Transplants End User: Hospitals, Organ Banks, Research Institutions, Transplant Centers Technology: Cooling Techniques, Preservation Solutions, Vitrification Methods, Transport Systems |
| Companies Covered | Waters Medical Systems LLC, XVIVO Perfusion, TransMedics, Preservation Solutions, Paragonix Technologies, OrganOx Limited, Dr. Franz Koehler Chemie GmbH, Bridge to Life Ltd., 21st Century Medicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Preservation Solutions Market Strategic Shifts
Preservation technology is converging with real-time metabolic monitoring, creating intelligent systems that adjust perfusate composition based on organ-specific biomarker feedback rather than fixed protocols.
Hypothermic machine perfusion is hybridizing with oxygenation control systems to create temperature-modulated preservation environments. Transplant programs in Germany and the Netherlands are adopting these platforms for liver grafts from donation-after-circulatory-death donors. The technology is compressing the historical trade-off between extended preservation duration and metabolic substrate delivery.
EMA's Medical Device Regulation is mandating clinical evidence standards for perfusion systems that exceed prior CE-marking requirements. Manufacturers must now submit prospective graft survival data rather than technical performance benchmarks. Kidney perfusion devices face the steepest compliance burden, as this segment hosts the most established clinical literature bases.
Transplant coordinators are consolidating procurement decisions through centralized organ procurement organizations rather than individual hospital purchasing committees. This concentration is displacing fragmented solution selection with standardized platform contracts. The United Kingdom's NHS Blood and Transplant exemplifies this shift, negotiating national supply agreements that override individual center preferences.
Organ Preservation Solutions Market Segmentation
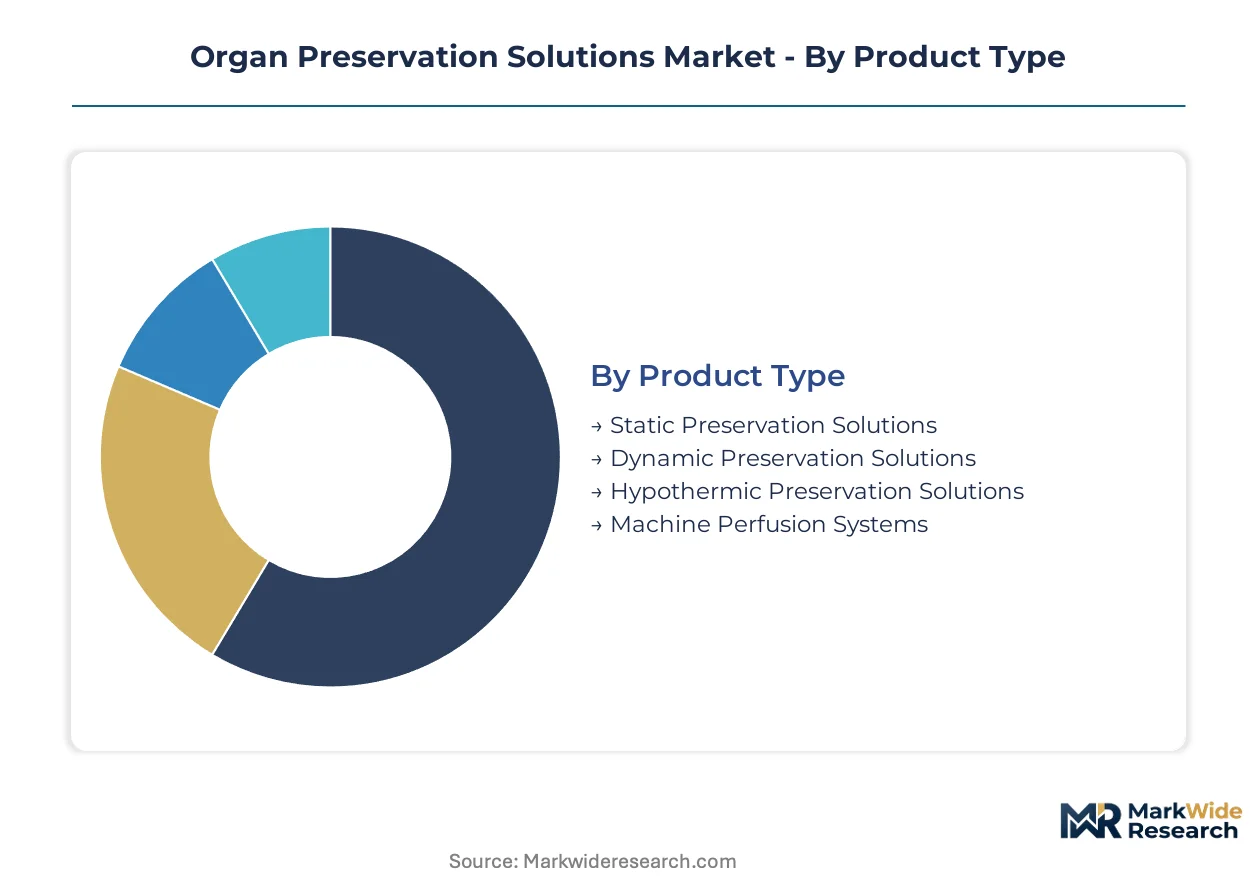
Organ preservation solutions fragment across four distinct axes that determine procurement priorities. Product type governs capital allocation cycles, while application specificity dictates formulation chemistry. End-user concentration shapes distribution channels, and technology maturity governs regulatory pathway complexity.
Product Type:
Static preservation solutions turn over inventory fastest due to single-use consumption, while machine perfusion systems cycle slowly through multi-year capital budgets.
- Static Preservation Solutions:These sterile, biocompatible fluid formulations contain colloids, electrolytes, and membrane-stabilizing agents to prevent ischemia-reperfusion injury during cold storage. Demand concentrates in India and Brazil where transplant programs lack capital infrastructure for dynamic platforms, though tertiary centers in both countries are beginning hybrid procurement.
- Machine Perfusion Systems:Integrated organ care platforms extend viable preservation windows through continuous perfusate circulation and metabolic monitoring. Procurement is accelerating at transplant centers in the United States and Germany following updated reimbursement frameworks from CMS and the German Federal Joint Committee.
- Dynamic Preservation Solutions:Formulations designed for active perfusion environments requiring precise oxygenation control and temperature modulation.
- Hypothermic Preservation Solutions:Temperature-modulated formulations sustaining viability in programs without normothermic capability.
Static preservation solutions dominate installed base. Machine perfusion systems represent where expansion concentrates most steeply.
Application:
Kidney transplants drive the highest procedure volume globally, while heart and lung applications command premium pricing due to shorter preservation tolerances.
- Kidney Transplants:Extended criteria donor kidneys increasingly require machine perfusion to remain transplantable amid rising diabetes prevalence. CMS reimbursement expansion in the United States specifically targets this segment, accelerating hospital capital investment cycles for perfusion-capable programs.
- Liver Transplants:Hypothermic oxygenated perfusion is demonstrating superior graft function outcomes in donation-after-circulatory-death donors, driving protocol adoption at academic medical centers in Germany and the Netherlands.
- Heart Transplants:Four-hour preservation windows constrain technical options regardless of method, limiting addressable technology categories.
- Lung Transplants:Ex-vivo lung perfusion platforms enable marginal donor utilization previously deemed non-viable.
Kidney transplants dominate procedure volume. Liver transplants are climbing the fastest in technology intensity.
End User:
Transplant centers consolidate procurement authority while organ banks standardize across networked agreements, creating divergent purchasing rhythms.
- Transplant Centers:Academic medical centers in the United States and Germany anchor demand for machine perfusion systems, leveraging updated reimbursement codes to justify capital expenditure. These facilities operate dedicated perfusionist staffing and protocol development capabilities.
- Hospitals:General hospital transplant programs in emerging markets prioritize static solutions due to lower per-procedure costs and established clinical familiarity.
- Organ Banks:Centralized procurement organizations in the United Kingdom's NHS Blood and Transplant negotiate national supply agreements that override individual center preferences.
- Research Institutions:Preclinical development programs drive demand for experimental vitrification methods and novel perfusate formulations.
Transplant centers concentrate premium technology adoption. Organ banks are gaining share fastest in procurement standardization.
Technology:
Cooling techniques retain the longest commercial history while preservation solution chemistry commands the steepest R&D investment cycles.
- Preservation Solutions:Proprietary perfusate formulations from concentrated manufacturers create single-source vulnerability for transplant programs, with three suppliers controlling over 80% of specialized compositions. EMA's Medical Device Regulation now mandates prospective graft survival data rather than technical performance benchmarks for these products.
- Machine Perfusion Systems:Battery-operated transportable units are enabling organ retrieval from remote donor hospitals lacking on-site preservation capability, expanding addressable donor geography.
- Cooling Techniques:Hypothermic transport devices control temperature gradients during donor organ transit, competing on reliability metrics.
- Vitrification Methods:Experimental cryopreservation approaches remain confined to research applications pending clinical validation.
Cooling techniques dominate legacy infrastructure. Machine perfusion systems are gaining share fastest in new capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports machine perfusion systems to transplant centers across the Netherlands and Austria, while the United States ships static preservation solutions to procurement networks in Canada and Mexico. This bilateral trade structure shapes regional competitive positioning and regulatory compliance requirements.
United States
Academic medical centers in Massachusetts and Illinois drive demand for integrated organ care platforms. CMS reimbursement expansion under updated billing codes now covers machine perfusion for extended criteria donor kidneys. The Cleveland Clinic and Mayo Clinic anchor procurement concentration in the Midwest, deploying capital budgets for perfusion-capable programs.
Germany
Transplant centers in Bavaria and North Rhine-Westphalia prioritize hypothermic oxygenated perfusion for liver grafts from donation-after-circulatory-death donors. The German Federal Joint Committee issued updated reimbursement frameworks that accelerate hospital investment cycles. Berlin and Heidelberg host the densest clustering of perfusion system vendors and clinical trial sites.
India
Government-funded transplant infrastructure buildout in Maharashtra and Tamil Nadu creates procurement volume for static preservation solutions. The CDSCO regulates medical device imports under streamlined pathways for life-critical equipment. Tertiary centers in Mumbai and Chennai are beginning hybrid procurement of dynamic systems alongside established cold-storage protocols.
United Kingdom
NHS Blood and Transplant consolidates procurement authority through national supply agreements that override individual center preferences. NICE technology appraisals directly influence adoption velocity for premium preservation technologies. London and Birmingham concentrate transplant coordinator networks that standardize platform selection across the National Health Service.
Netherlands
Academic hospitals in Amsterdam and Rotterdam adopt temperature-modulated preservation environments for marginal donor organs. EMA Medical Device Regulation mandates prospective graft survival data for perfusion systems seeking CE marking. The country serves as a clinical trial hub for German and Swiss manufacturers testing hypothermic machine perfusion protocols.
Organ Preservation Solutions Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Three manufacturers concentrate proprietary perfusate formulation supply, creating single-source vulnerability for transplant programs. The market structures around integrated system vendors, static solution formulators, and hypothermic transport device specialists. Dominant competitive moves include strategic partnerships with organ procurement organizations and geographic expansion through local service network establishment.
Within the integrated system tier, TransMedics and XVIVO Perfusion occupy positions exemplifying divergent technology anchoring. TransMedics represents the normothermic perfusion archetype through its organ care platform specialization. XVIVO Perfusion exemplifies the ex-vivo lung perfusion segment with platforms enabling marginal donor utilization. Among static solution formulators, Dr. Franz Koehler Chemie GmbH anchors European supply concentration. Waters Medical Systems LLC and Paragonix Technologies sit within the hypothermic transport device category, competing on temperature gradient control reliability.
| Leading Market Players |
|---|
| Waters Medical Systems LLC |
| XVIVO Perfusion |
| TransMedics |
| Preservation Solutions |
| Paragonix Technologies |
| OrganOx Limited |
| Dr. Franz Koehler Chemie GmbH |
| Bridge to Life Ltd. |
| 21st Century Medicine |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on proprietary perfusate formulations from three dominant manufacturers compresses pricing tier spreads while forcing transplant programs into multi-year supply commitments that reshape procurement flexibility and inventory risk allocation across hospital systems.
Pricing Analysis
The technology-generation pricing gap between static cold-storage solutions, hypothermic machine perfusion platforms, and normothermic organ care systems spans an order of magnitude in per-procedure economics. Three-tier pricing structure across premium organ care platforms, standard hypothermic perfusion systems, and economy static solutions reflects capital intensity differentials and certification grade requirements under FDA and EMA pathways. Cost compression in the static solution tier intensifies because Indian and Brazilian procurement committees prioritize per-unit economy over extended preservation windows. Academic medical centers in the United States and Germany demonstrate lowest price sensitivity, while general hospital programs in emerging markets anchor the demand curve at economy tiers.
Supply Chain Analysis
Tariff exposure between the United States and Germany for finished perfusion systems creates procurement friction for transplant centers sourcing across Atlantic markets. Manufacturing concentration in Germany, the United States, and Switzerland for proprietary perfusate formulations draws from specialized chemical synthesis capabilities and sterile filling infrastructure. Supply chain risk centers on single-source vulnerability for oxygenated perfusion solutions, where formulation complexity limits qualified suppliers. Distribution runs through centralized organ procurement organizations in the United Kingdom and hospital purchasing committees in the United States, with emerging markets relying on importer-distributor networks for static solution logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations that control scarce perfusionist workforce capacity and proprietary formulation chemistry, with competitive advantage tethered to clinical training infrastructure and regulatory certification velocity rather than manufacturing scale alone.
For Market Incumbents: Harden supply security by securing backward integration into perfusate raw material synthesis and expanding perfusionist training partnerships with academic medical centers in the United States and Germany. The threat of portable battery-operated units from specialized entrants demands defensive patent positioning around temperature modulation algorithms. Certification investment in EMA Medical Device Regulation compliance represents the critical lever for maintaining European market access. For New Entrants and Emerging Players: Pursue white-space opportunity in Indian tertiary care expansion, where government-funded infrastructure buildout lacks established perfusion system vendors with local service networks. The most penetrable segment lies in hybrid procurement models combining static solutions with entry-level hypothermic platforms for programs transitioning from cold storage. A go-to-market angle anchored to technician training programs and lease-to-own capital structures bypasses upfront budget constraints. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors platform-integrated vendors over component specialists. Long-term viability over the next decade rests on evidence generation capabilities for graft survival outcomes and reimbursement code capture. Acquisition target archetype: mid-cap perfusion system manufacturers with FDA premarket notification clearances and nascent European commercial presence. The signal to watch is CMS reimbursement expansion into liver and heart perfusion categories.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusionist Workforce Development | Training partnerships with Cleveland Clinic and Mayo Clinic address the global scarcity of certified specialists. |
| EMA Medical Device Regulation Compliance | Prospective graft survival data requirements exceed prior CE-marking standards for kidney perfusion devices. |
| Portable Perfusion Miniaturization | Battery-operated transportable units expand donor organ retrieval from remote hospitals lacking on-site preservation. |
| Reimbursement Strategy Development | CMS billing code expansion for extended criteria donor kidneys accelerates hospital capital investment cycles. |
| Local Service Network Establishment | Field engineering presence in Maharashtra and Tamil Nadu captures Indian government-funded transplant infrastructure buildout. |
Study Parameters
Cross-validation between primary interviews with transplant surgeons, perfusionists, hospital purchasing committee members, and biomedical engineers and secondary validation through FDA 510(k) filings, EMA CE-marking databases, CMS reimbursement code releases, and hospital procurement contract records anchors the qualitative findings. Bottom-up modeling of procedure volumes by organ type and preservation method converges with top-down market sizing through manufacturer revenue triangulation across the analysis window.
Calibration against historical adoption curves for machine perfusion systems in the United States and Germany informs the projection framework across product type, application specificity, end-user concentration, and technology maturity dimensions. CAGRs derive from segment-level growth rate blending weighted by installed base evolution and capital replacement cycles. Forecast inputs incorporate reimbursement policy trajectories from CMS and the German Federal Joint Committee alongside extended criteria donor organ volume trends.
Sensitivities concentrate around regulatory divergence between FDA and EMA on perfusion device classification standards and workforce scarcity constraints on program expansion velocity. Forecasts reflect assumptions about reimbursement code stability and clinical evidence generation timelines without guaranteeing specific adoption trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Cryoablation System Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Manometry System Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Intubation Tubes Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Implantable Port Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Telehealth Device Market
Medical Devices
Global Cardiac Pacemakers Market