
 Transcranial Doppler Ultrasounds System Market | 2026-2036
Transcranial Doppler Ultrasounds System Market Size, Share, and Industry Trends Forecast 2026-2036
Transcranial Doppler Ultrasounds System Market Analytics
Aftermarket service revenue is tilting toward remote monitoring and predictive maintenance contracts rather than traditional break-fix arrangements. Natus Medical Incorporated leverages its installed base of neurodiagnostic equipment to sustain recurring revenue streams through extended service agreements. Compumedics Limited anchors its competitive stance in sleep and neuro markets with specialized technical support networks that differentiate its TCD offerings from generalist ultrasound vendors.
Transcranial Doppler Ultrasounds Systems employ low-frequency ultrasound, typically 2 MHz, to measure blood flow velocity through the thin temporal bone and other acoustic windows of the skull. These devices serve primarily to detect emboli, assess vasospasm after subarachnoid hemorrhage, and monitor cerebral autoregulation in critical care settings. Portable units command expanding interest as point-of-care neurology programs proliferate in emergency departments and mobile stroke units, while standalone systems retain dominance in dedicated neurovascular laboratories where comprehensive hemodynamic assessment protocols require full diagnostic feature sets. Pulsed wave technology leads the technology segmentation due to its depth discrimination capabilities essential for intracranial vessel targeting.
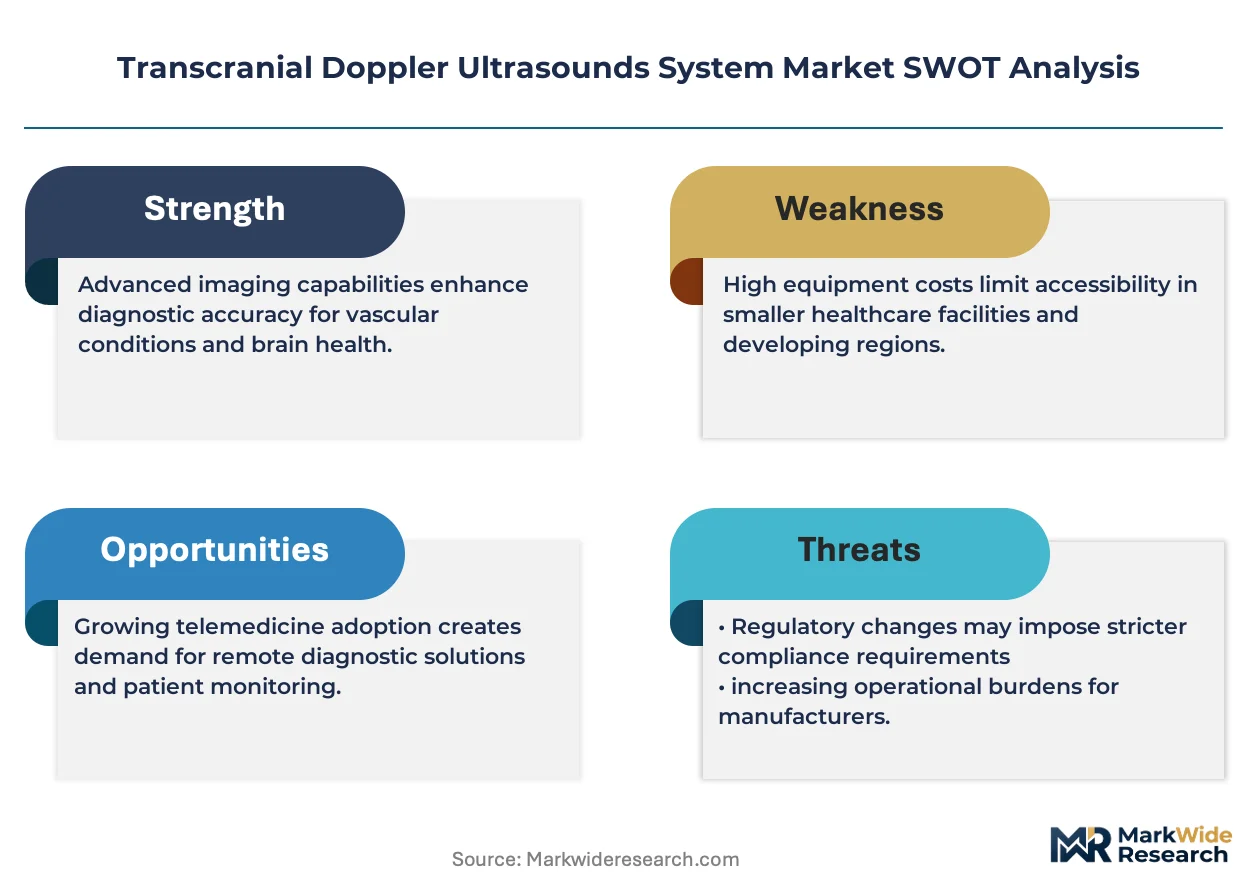
FDA 510(k) premarket notification requirements govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking access to European markets. ISO 13485 quality management certification functions as a baseline expectation for supplier qualification by hospital procurement committees evaluating TCD vendors. Stakeholders must monitor evolving reimbursement codes for transcranial Doppler studies across public and private payers, as coverage determinations directly influence capital equipment purchasing cycles and technology refresh timelines.
Market Dynamics
Hospital neurology departments are consolidating diagnostic workflows around portable point-of-care systems, compressing capital cycles for standalone laboratory equipment as emergency departments and mobile stroke units prioritize rapid cerebrovascular assessment capabilities.
Growth Catalysts
- Mobile stroke unit deployment:Emergency medical services in the United States are integrating TCD systems into prehospital care protocols, expanding addressable clinical settings beyond traditional hospital laboratories.
- FDA 510(k) pathway efficiency:Class II medical device clearance timelines for TCD hardware modifications enable faster feature iteration compared to de novo classification routes, accelerating product refresh cycles.
- Subarachnoid hemorrhage monitoring protocols:Neurocritical care units have standardized vasospasm surveillance using serial transcranial Doppler examinations, embedding devices into routine post-bleed management pathways.
Market Restraints
- Piezoelectric crystal supply concentration:Specialized 2 MHz transducer manufacturing depends on concentrated ceramic substrate suppliers in East Asia, exposing procurement to single-source fragility.
- Operator skill dependency:Accurate insonation through the temporal bone acoustic window requires substantial sonographer training, limiting deployment in facilities without dedicated neurovascular technologists.
- CT angiography substitution:High-resolution vascular imaging alternatives capture diagnostic share in stroke triage protocols where immediate hemorrhage exclusion takes precedence over hemodynamic monitoring.
Strategic Opportunities
- Remote monitoring service contracts:Predictive maintenance telemetry for installed TCD bases creates recurring revenue streams that decouple vendor economics from capital equipment replacement cycles.
- EU MDR clinical evidence requirements:Stricter CE marking standards for Class IIa neurological devices favor established manufacturers with robust quality management systems, consolidating competitive position against emerging entrants.
- Artificial intelligence waveform interpretation:Machine learning algorithms for automated emboli detection and velocity measurement standardization address operator variability constraints in high-throughput screening environments.
Industry Challenges
- Neurovascular sonographer certification bottlenecks:Limited accredited training programs for transcranial Doppler technique create workforce gaps that constrain equipment utilization rates in expanded deployment settings.
- Legacy EMR integration complexity:DICOM compatibility and HL7 FHIR connectivity requirements demand substantial software engineering resources to achieve seamless data flow with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcranial Doppler Ultrasounds System Market |
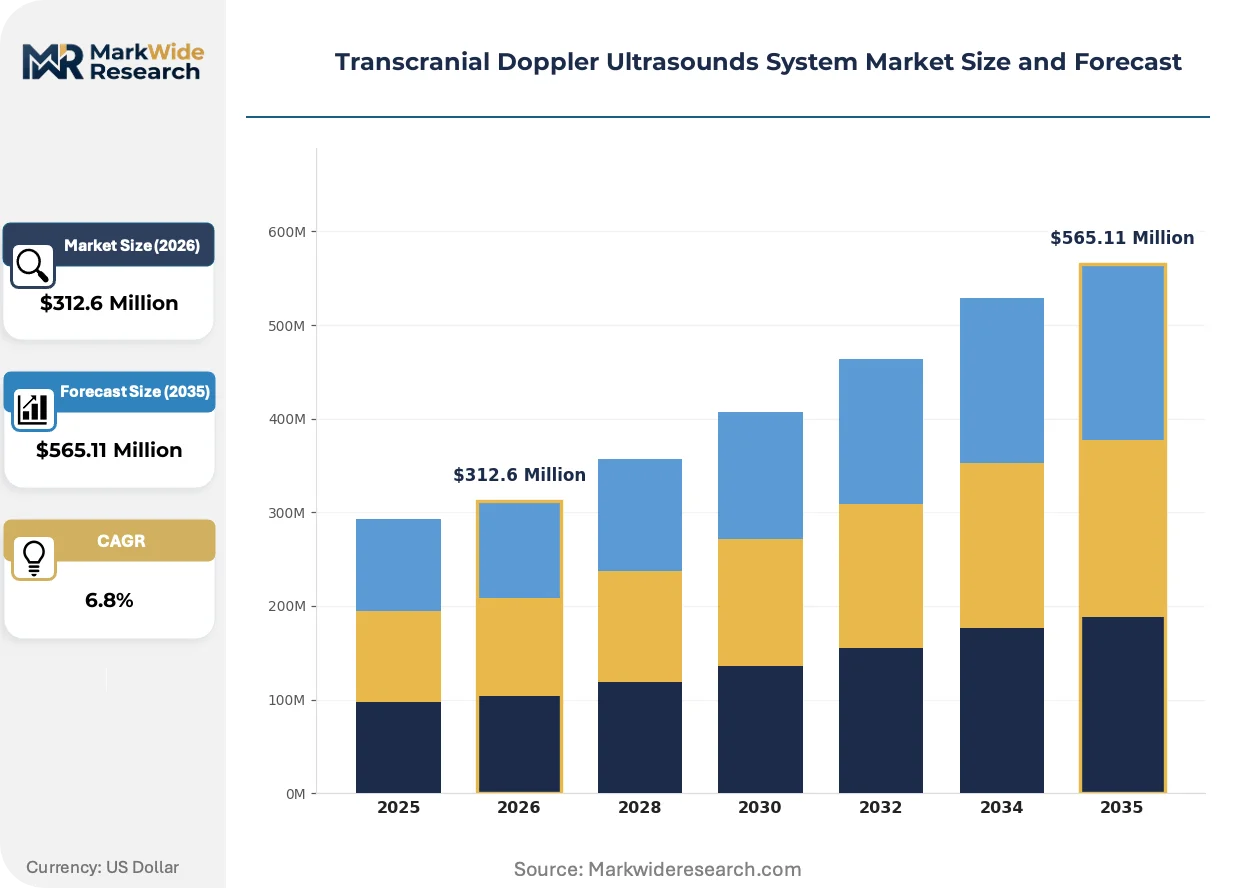
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Portable Units, Combined Devices, Accessories End User: Hospitals, Clinics, Research Labs, Rehabilitation Centers Technology: Pulsed Wave, Continuous Wave, 3D Imaging, Doppler Imaging Application: Stroke Detection, Cerebral Blood Flow Monitoring, Research Studies, Hemodynamic Assessment |
| Companies Covered | Natus Medical Incorporated, Compumedics Limited, Viasonix, Atys Medical, Rimed Ltd., Mindray, GE HealthCare, Koninklijke Philips N.V., DWL Elektronische Systeme GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcranial Doppler Ultrasounds System Market Evolving Landscape
Digital signal processing architectures are displacing analog front-end designs across the TCD hardware landscape, enabling real-time spectral analysis and automated measurement algorithms that reduce operator interpretation burden.
Robotic probe positioning systems are hybridizing with conventional manual transducer manipulation, allowing remote specialist oversight of examinations performed by less-trained bedside personnel in intensive care units and emergency departments. Academic medical centers in Germany and the United States are piloting these tele-sonography configurations to extend neurovascular coverage across satellite hospitals lacking on-site expertise. The structural consequence is a compression of the traditional specialist-performed examination model toward technician-supported, remotely supervised workflows.
EU MDR Article 10 clinical evaluation requirements are tightening evidentiary standards for transcranial Doppler device renewals, compelling manufacturers to generate post-market surveillance data that was previously unnecessary under the Medical Device Directive. Manufacturers targeting European markets must now maintain systematic literature reviews and clinical follow-up regimens that increase regulatory compliance costs. Small-to-mid-sized device firms without dedicated clinical affairs infrastructure are responding by narrowing product portfolios to concentrate resources on core platform submissions.
Service contract unbundling is fragmenting the traditional capital-plus-maintenance procurement bundle, with hospital materials management departments negotiating remote monitoring subscriptions separately from hardware acquisition. Group purchasing organizations in the United States are standardizing these modular contract structures across member health systems, pressuring vendors to disclose software-enabled feature roadmaps and telemetry pricing independently of equipment list prices. The behavioral shift is most pronounced in integrated delivery networks with centralized neurodiagnostic service lines spanning multiple facilities.
Transcranial Doppler Ultrasounds System Market Segmentation
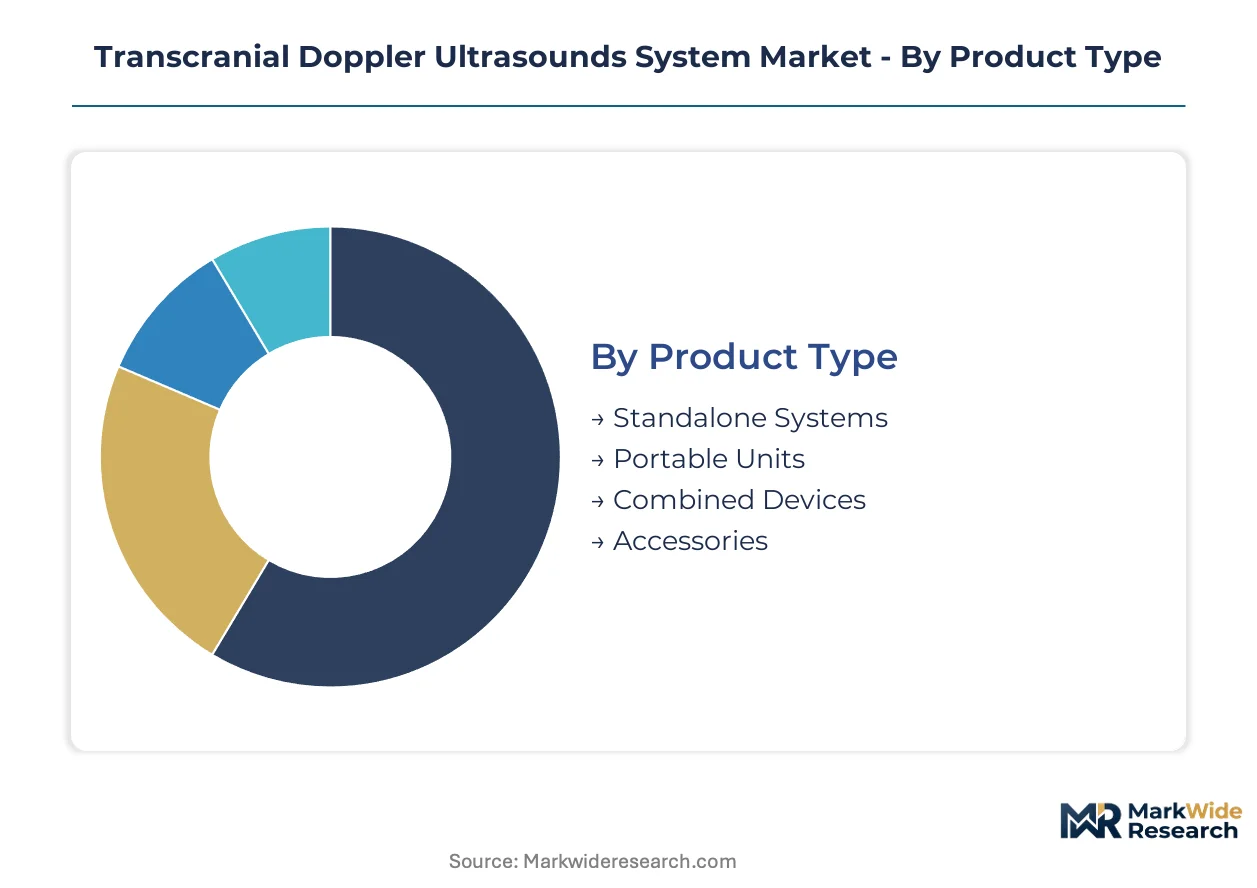
Transcranial Doppler system configurations diverge sharply between high-throughput laboratory environments and point-of-care deployment settings. Vendors must align hardware specifications, software architectures, and service models to distinct clinical workflows rather than pursuing universal platform strategies.
Product Type:
Mature laboratory installations coexist with rapidly emerging portable formats as point-of-care neurology programs expand across emergency departments and mobile stroke units.
- Standalone Systems:Full-featured cart-based configurations integrate multi-depth sampling, emboli detection algorithms, and comprehensive reporting suites for dedicated neurovascular laboratories. Academic medical centers in the United States anchor procurement volume for these systems as stroke center certification requirements mandate comprehensive cerebrovascular diagnostic capabilities.
- Portable Units:Battery-powered handheld devices sacrifice some spectral resolution for deployment flexibility in intensive care units and prehospital settings. Emergency medical services integration in Germany and the United States is accelerating demand as mobile stroke units require rapid cerebrovascular assessment outside traditional laboratory confines.
- Combined Devices:Hybrid platforms merge TCD functionality with electroencephalography or evoked potential modules for consolidated neurodiagnostic workstations. These configurations appeal to hospitals optimizing capital expenditure across constrained neurology department budgets.
- Accessories:Specialized 2 MHz transducer probes, headframe mounting systems, and disposable acoustic coupling gels constitute recurring revenue streams. Supply concentration for piezoelectric ceramic substrates in East Asia creates procurement vulnerability for transducer replacement cycles.
Standalone systems handle the majority of throughput; portable units are gaining share fastest as point-of-care deployment expands beyond traditional laboratory settings.
End User:
Procurement authority concentrates in hospital materials management departments, though clinical workflow requirements vary substantially across facility types and patient acuity levels.
- Hospitals:Comprehensive stroke centers and academic medical centers deploy TCD systems across neurocritical care units, emergency departments, and dedicated vascular laboratories. United States hospital systems prioritize FDA 510(k) cleared devices with established reimbursement codes for transcranial Doppler studies.
- Clinics:Outpatient neurology practices and ambulatory surgical centers utilize portable configurations for cerebrovascular screening in transient ischemic attack follow-up protocols. These settings emphasize rapid examination turnaround over comprehensive hemodynamic mapping.
- Research Labs:Academic institutions and pharmaceutical research organizations employ TCD systems for cerebral autoregulation studies and drug trial endpoints. Specialized software modules for continuous monitoring and data export to statistical platforms differentiate research-oriented configurations.
- Rehabilitation Centers:Post-stroke recovery facilities deploy TCD for monitoring cerebral blood flow during therapeutic interventions. Demand concentrates in facilities affiliated with comprehensive stroke centers requiring longitudinal cerebrovascular surveillance.
Hospitals absorb the dominant share of capital expenditure; clinics are expanding most quickly as ambulatory cerebrovascular assessment protocols proliferate.
Technology:
Signal processing architectures determine depth discrimination capabilities and operator interpretation burden across distinct clinical applications.
- Pulsed Wave:Depth-gated sampling enables precise intracranial vessel targeting through the temporal bone acoustic window. This modality dominates neurocritical care applications where vasospasm monitoring requires serial velocity measurements at specific arterial segments.
- Continuous Wave:Uninterrupted signal transmission provides velocity data without depth discrimination, limiting utility to superficial vascular assessment. Lower hardware costs sustain niche deployment in screening applications where precise anatomical localization is secondary to flow detection.
- 3D Imaging:Volumetric reconstruction capabilities remain emergent in TCD applications, with limited commercial availability compared to conventional B-mode ultrasound. Research institutions pilot these configurations for complex cerebrovascular anatomy visualization.
- Doppler Imaging:Color-coded flow mapping overlays velocity information on anatomical references to reduce operator dependency in vessel identification. This technology is climbing fastest in adoption as sonographer training bottlenecks constrain deployment of conventional spectral TCD.
Pulsed wave systems command the installed base; Doppler imaging configurations are expanding most rapidly as workflow efficiency pressures mount.
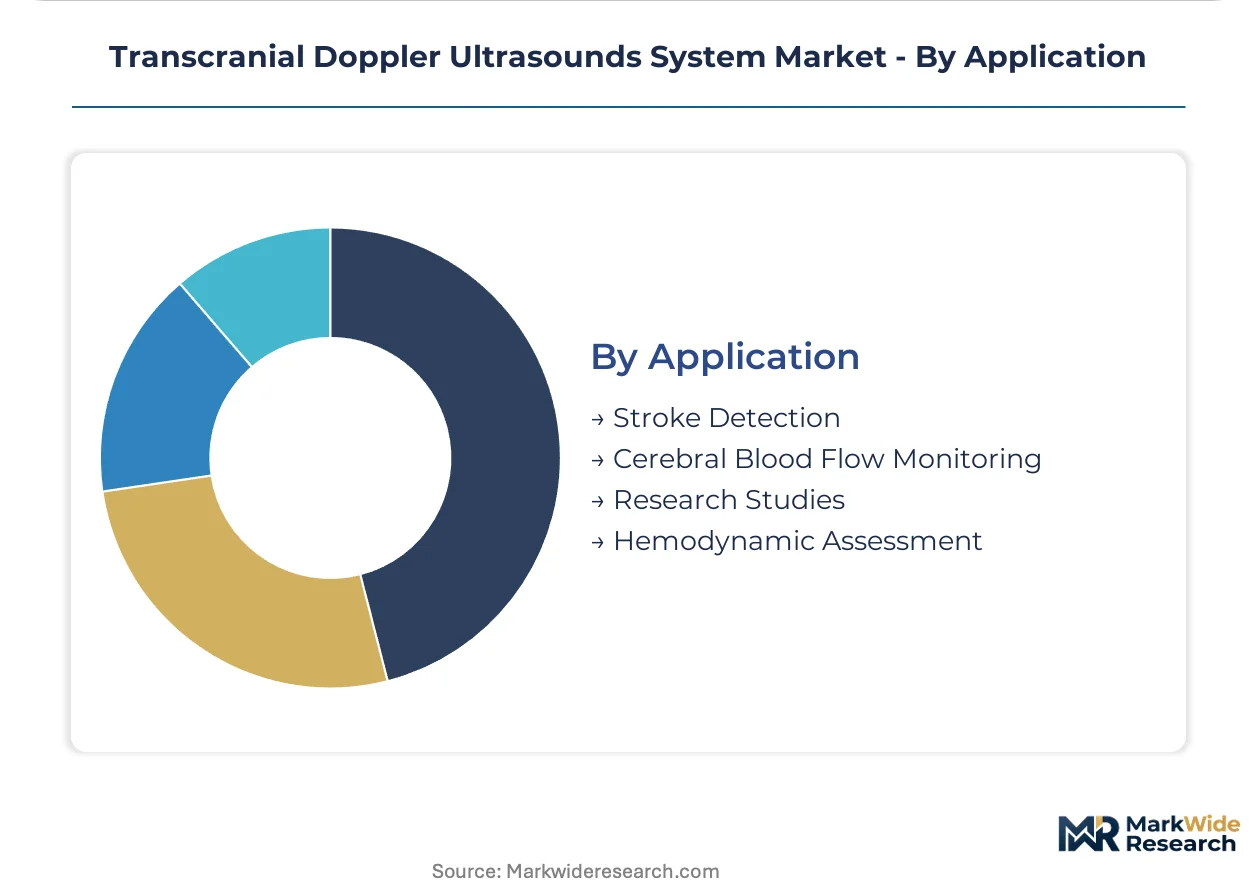
Application:
Clinical utility spans acute intervention, chronic monitoring, and investigational protocols with divergent reimbursement and regulatory pathways.
- Stroke Detection:Emergency department triage protocols employ TCD for rapid cerebrovascular assessment when computed tomography angiography is unavailable or contraindicated. Mobile stroke unit deployment in the United States and Germany is embedding these systems into prehospital care pathways.
- Cerebral Blood Flow Monitoring:Neurocritical care units utilize serial TCD examinations for vasospasm surveillance following subarachnoid hemorrhage. Standardized monitoring protocols at major stroke centers create predictable replacement demand for device manufacturers.
- Research Studies:Cerebral autoregulation assessment and carbon dioxide reactivity testing support academic publications and pharmaceutical trial endpoints. These applications require specialized software for continuous data acquisition and statistical export.
- Hemodynamic Assessment:Comprehensive evaluation of intracranial pressure dynamics and cerebral perfusion pressure guides therapeutic interventions in traumatic brain injury management. Demand concentrates in level I trauma centers with dedicated neurocritical care capabilities.
Stroke detection generates the highest examination volume; cerebral blood flow monitoring maintains the steepest expansion trajectory as neurocritical care unit bed counts increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany exhibit the lowest price elasticity, prioritizing ISO 13485 certification and MDR compliance over capital cost, while outpatient clinics in India and Southeast Asia drive volume through portable unit affordability.
United States
Academic medical centers in Boston and Houston anchor demand for standalone laboratory systems as stroke center certification requirements mandate comprehensive cerebrovascular diagnostics. FDA 510(k) clearance pathways shape product development timelines for Class II medical devices targeting neurocritical care units. Major integrated delivery networks in the Midwest negotiate remote monitoring subscriptions separately from hardware acquisition.
Germany
Neurovascular laboratories at university hospitals in Berlin and Munich standardize vasospasm surveillance protocols using serial TCD examinations following subarachnoid hemorrhage. EU MDR Article 10 clinical evaluation requirements tighten evidentiary standards for device renewals, compelling manufacturers to maintain systematic post-market surveillance. The Eindhoven-to-Dresden medical technology corridor concentrates robotic probe positioning development for tele-sonography applications.
China
Provincial hospital systems in Shanghai and Guangzhou expand neurocritical care unit bed counts, embedding cerebral blood flow monitoring into routine post-bleed management. NMPA regulatory pathways for Class II neurological devices emphasize clinical trial data requirements that extend product registration timelines. Domestic manufacturers in Shenzhen leverage local piezoelectric ceramic supply chains to reduce transducer procurement costs.
Japan
Metropolitan stroke centers in Tokyo and Osaka deploy portable TCD units into emergency department triage protocols where rapid cerebrovascular assessment precedes CT angiography. PMDA quality management expectations align with ISO 13485 standards for supplier qualification by hospital procurement committees. The Kansai region anchors research applications for cerebral autoregulation studies at pharmaceutical trial endpoints.
India
Outpatient neurology practices in Maharashtra and Karnataka utilize handheld configurations for transient ischemic attack follow-up protocols where examination turnaround trumps comprehensive hemodynamic mapping. CDSCO medical device regulations for neurological diagnostics impose documentation requirements that favor established importers over emerging domestic entrants. Hyderabad's medical device cluster concentrates assembly operations for portable units targeting price-sensitive clinic segments.
Transcranial Doppler Ultrasounds System Market Competitive Landscape
Capability concentration sits with specialized neurodiagnostic manufacturers; scale advantage sits with diversified imaging conglomerates. The vendor base stratifies across three tiers: pure-play neurology specialists with dedicated technical support networks, diversified ultrasound vendors leveraging cross-modal R&D platforms, and emerging regional fabricators competing on portable unit cost structures. Dominant competitive moves include portfolio diversification into combined EEG-TCD platforms and strategic partnerships with group purchasing organizations to secure multi-hospital system contracts.
Among neurodiagnostic specialists, Natus Medical Incorporated and Compumedics Limited exemplify the installed-base service model, anchoring recurring revenue through extended technical support agreements. Viasonix occupies a position within the European specialist tier, while DWL Elektronische Systeme GmbH represents German engineering-focused fabrication. At the diversified imaging end, GE HealthCare and Koninklijke Philips N.V. leverage cross-modal ultrasound platforms to bundle TCD functionality with broader radiology procurement cycles. Mindray exemplifies the scale-driven emerging market strategy, competing on portable unit affordability in price-sensitive geographies.
| Leading Market Players |
|---|
| Natus Medical Incorporated |
| Compumedics Limited |
| Viasonix |
| Atys Medical |
| Rimed Ltd. |
| Mindray |
| GE HealthCare |
| Koninklijke Philips N.V. |
| DWL Elektronische Systeme GmbH |
| Others |
Value Network & Pricing Analysis
The Shenzhen-to-Rotterdam maritime corridor carries piezoelectric ceramic substrates and ultrasound transducer assemblies from East Asian foundries to European and North American assembly plants, with freight cost volatility amplifying margin compression for manufacturers while enabling price differentiation between ISO 13485-certified premium tiers and economy portable units sourced through alternative logistics routes.
Pricing Analysis
Extended service agreements and predictive maintenance subscriptions generate lifetime value exceeding hardware margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance status and ISO 13485 certification grade. Cost compression in portable unit segments intensifies as domestic Chinese manufacturers exploit local ceramic supply chains. Outpatient clinics in India and Southeast Asia exhibit highest price sensitivity; German university hospitals show lowest elasticity.
Supply Chain Analysis
Electronics manufacturing services in Shenzhen, Dongguan, and Suzhou hold dominant capacity for ultrasound system assembly and transducer fabrication. Supply draws from concentrated piezoelectric ceramic substrate production in East Asia, specialized 2 MHz crystal growth facilities, and precision acoustic coupling gel chemical processors. Single-source vulnerability for ceramic substrates exposes procurement to geopolitical disruption. Distribution runs through hospital group purchasing organizations in the United States, specialized medical device distributors in Europe, and direct OEM relationships in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs defensive moats in this market, as FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create multi-year barriers against emerging competitors lacking dedicated clinical affairs infrastructure.
For Market Incumbents: Build switching-cost moats through embedded software companion development that tightens EMR integration and locks hospital systems into proprietary data formats. Deepen backward integration into transducer manufacturing to reduce ceramic substrate supply risk. Counter CT angiography substitution threats by expanding portable TCD deployment into emergency departments where immediate hemodynamic monitoring precedes imaging decisions.
For New Entrants and Emerging Players: Build out AI-powered waveform interpretation capabilities to address neurovascular sonographer certification bottlenecks in high-throughput screening environments. Target mobile stroke unit deployments in prehospital care settings where established vendors lack specialized configurations. Pursue reimbursement strategy partnerships with emergency medical services networks to secure preferred vendor status before hospital system consolidation.
For Investors and Strategic Acquirers: Specialist neurodiagnostic firms with installed-base service revenue streams and ISO 13485 certification infrastructure represent priority acquisition targets. Long-term viability hinges on regulatory compliance scalability across FDA, EU MDR, and NMPA jurisdictions. Monitor CDSCO registration progress by emerging domestic Indian manufacturers as inflection indicator for price competition intensity in portable segments.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Article 10 clinical evaluation requirements favor established manufacturers with post-market surveillance infrastructure. |
| Hospital System Partnership | Group purchasing organization contracts secure multi-facility procurement across integrated delivery networks. |
| Software Companion Development | AI-powered emboli detection algorithms reduce operator dependency and accelerate emergency department adoption. |
| Reimbursement Strategy | Coverage determination advocacy with CMS and private payers directly influences capital equipment purchasing cycles. |
| Backward Integration | In-house piezoelectric ceramic production mitigates East Asian supply concentration risk for transducer manufacturing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across neurocritical care unit directors, hospital biomedical engineers, group purchasing organization contract managers, neurovascular sonographers, and medical device regulatory affairs specialists. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR Article 10 clinical evaluation submissions, hospital procurement records, and CMS reimbursement coding determinations. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation anchored market sizing.
Calibration against historical replacement cycles and neurocritical care unit bed expansion trajectories shaped projections across the analysis window. Segmentation dimensions modeled include product configuration, end-user facility type, signal processing technology, and clinical application. CAGRs derived from equipment replacement velocity, point-of-care deployment penetration, and service contract renewal patterns. Forecast inputs incorporated mobile stroke unit deployment schedules and EU MDR transition timelines.
Stress conditions across ceramic substrate supply disruption, CT angiography substitution acceleration, and neurovascular sonographer workforce contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of NMPA registration approvals, CDSCO medical device rule amendments, and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Ehealth Devices Market
Medical Devices
APAC AMH Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Smart Wheelchairs Market