
 Global Medical Loupes Market | 2026-2036
Global Medical Loupes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Loupes Market Foresight
EU MDR is decoupling optical certification from legacy CE pathways, forcing manufacturers to rebuild clinical evidence dossiers. Carl Zeiss Meditec AG anchors its position through captive lens grinding facilities in Germany. Designs for Vision, Inc. specializes in custom through-the-lens configurations for dental microsurgery. HEINE Optotechnik GmbH & Co. KG extends its reach via direct service networks across European hospital purchasing consortia.
Medical loupes are binocular magnification devices built from coated glass or polymer optics mounted on adjustable frames, typically offering 2.0x to 8.0x magnification with working distances of 300-550 mm to reduce clinician musculoskeletal strain during prolonged procedures. Galilean configurations dominate volume sales in dentistry due to lower weight and adequate field depth for routine restorations. Prismatic variants capture expanding margin pools in microsurgery and dermatology where higher magnification and edge-to-edge clarity justify premium positioning. Through-the-lens deployments are maturing in veterinary settings where shared equipment across multiple practitioners demands fixed interpupillary calibration.
FDA 510(k) clearance timelines, EMDR vigilance reporting obligations, and Japan's PMDA foreign manufacturer registration requirements collectively shape product development roadmaps and geographic launch sequencing. ISO 13485 quality management certification has become a non-negotiable threshold for contract manufacturing partnerships with major distributors. Stakeholders must monitor evolving optical performance test methods under harmonized standards to anticipate which magnification platforms will retain reimbursement eligibility.
Market Dynamics
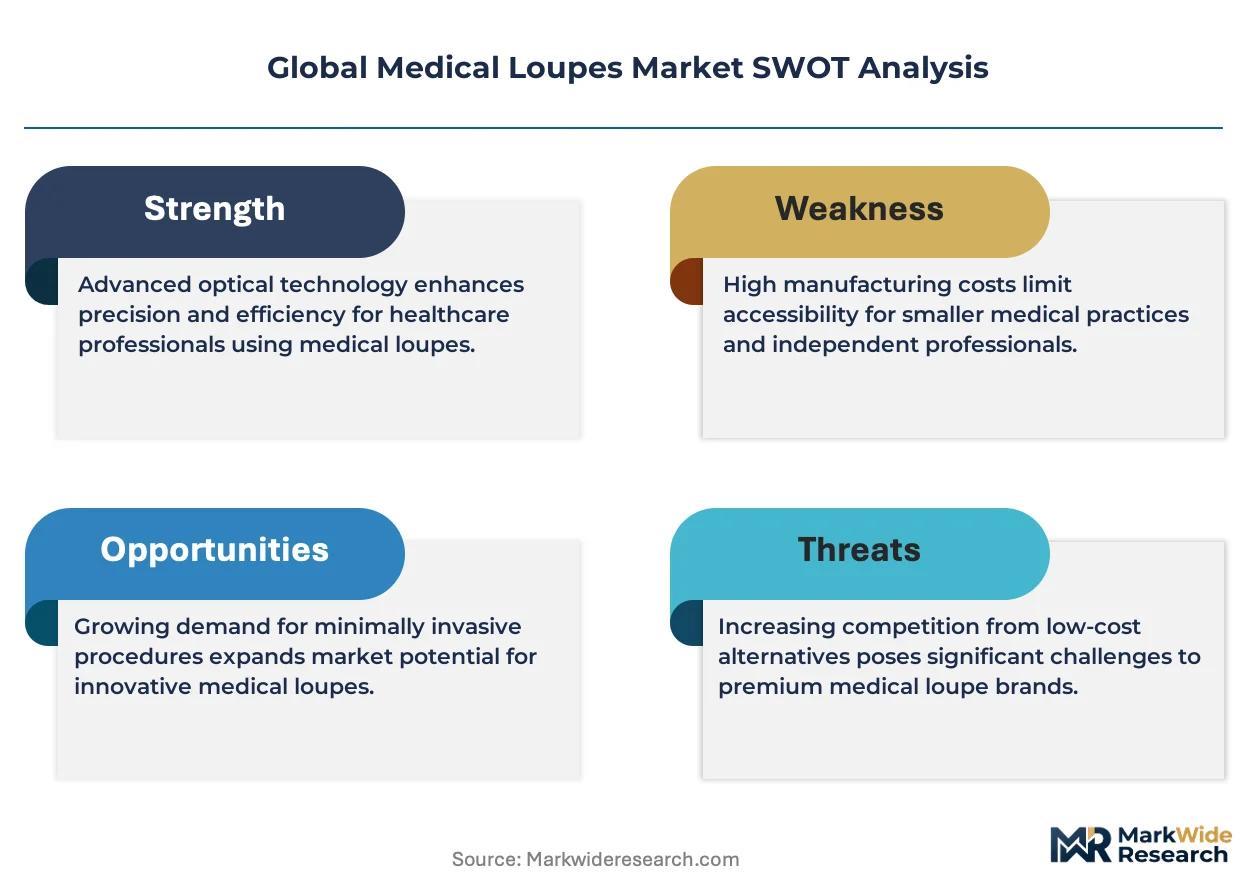
EU MDR optical certification decoupling is forcing manufacturers to rebuild clinical evidence dossiers from scratch, elevating compliance costs while compressing legacy product timelines and accelerating prismatic loupe development cycles.
Growth Catalysts
- Precision Surgery Mandates:German dental clinics are expanding prismatic loupe procurement as surgical standards tighten for microsurgical procedures requiring edge-to-edge optical clarity.
- Reimbursement Architecture:US surgical centers benefit from capital equipment upgrade policies that favor magnification device investments in orthopedic and dermatology suites.
- ISO 13485 Harmonization:Quality management certification requirements are consolidating contract manufacturing partnerships around certified optical component suppliers.
Market Restraints
- Optical Glass Supply Concentration:German and Japanese lens grinding facilities control premium coated glass substrate availability, creating bottlenecks for prismatic variant scaling.
- Polymer Degradation Limits:Polymer optic alternatives suffer clarity degradation under repeated sterilization cycles, restricting their deployment in high-throughput surgical environments.
- EMDR Vigilance Burden:European vigilance reporting obligations for optical device failures are extending post-market surveillance timelines and elevating liability exposure.
Strategic Opportunities
- Veterinary Equipment Sharing:Through-the-lens configurations with fixed interpupillary calibration are penetrating veterinary clinics in Australia and Canada where multi-practitioner equipment pools dominate.
- PMDA Registration Pathway:Japan's foreign manufacturer registration requirements, once cleared, unlock procurement channels within METI-influenced hospital purchasing consortia.
- Head-Up Display Convergence:Integration of augmented reality overlays with Galilean loupe frames is creating new product categories for navigated implantology procedures.
Industry Challenges
- Optical Metrology Talent Scarcity:Edge-to-edge clarity testing requires specialized technicians trained in ISO 10993-adjacent biocompatibility protocols, constraining quality control scaling.
- 510(k) Timeline Compression:FDA clearance backlogs for modified magnification platforms are delaying product launches in the US surgical center channel by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Loupes Market |
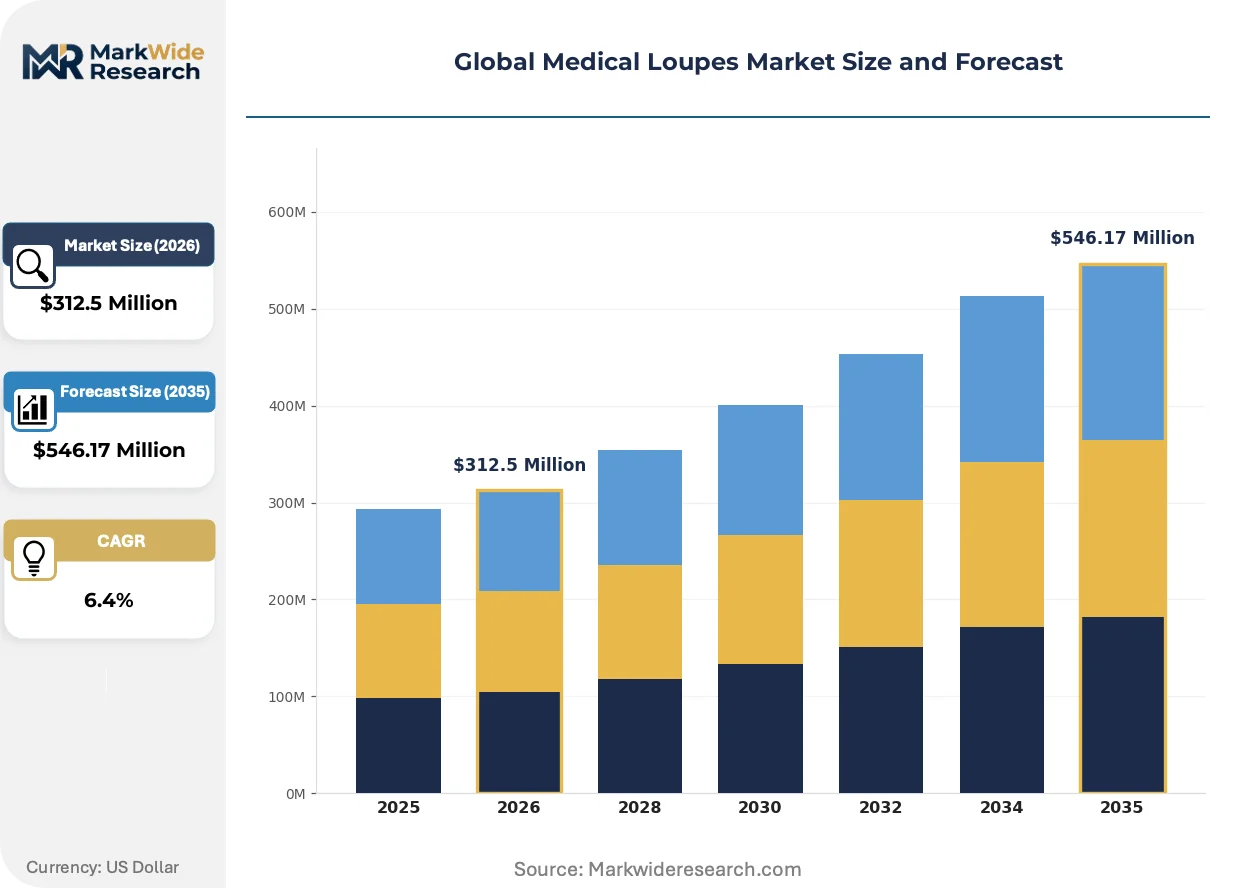
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lens, Galilean, Prismatic, Through-the-Lens Application: Dentistry, Surgery, Dermatology, Veterinary Medicine End User: Dental Clinics, Surgical Centers, Skin Care Facilities, Animal Care Clinics Deployment: Fixed Frame, Flip-up Frame, Helmet Mounted, Headband Mounted |
| Companies Covered | Enova Illumination, Orascoptic, Carl Zeiss Meditec AG, L.A. Lens, Rose Micro Solutions, Designs for Vision, Inc., SurgiTel, HEINE Optotechnik GmbH & Co. KG, Den-Mat Holdings, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Loupes Market Shifts & Advancements
Active alignment between optical engineering and digital overlay technologies is compressing product development cycles while fragmenting the vendor base into specialized component suppliers and integrated system architects.
Head-mounted augmented reality guidance is automating surgical navigation workflows in dental implantology suites. Oral surgeons in South Korea and Spain are piloting AR-integrated prismatic loupes that overlay 3D scan data onto the operative field. This convergence is automating depth-perception calibration tasks previously requiring manual loupe adjustment, reducing chair time variability.
EU MDR Article 10 clinical evidence requirements are elevating optical performance documentation burdens for prismatic loupe manufacturers. The regulation mandates edge-to-edge resolution testing under standardized working distances, forcing redesigns of legacy Galilean platforms. German and Italian manufacturers are responding by establishing captive metrology laboratories to accelerate technical file compilation.
Hospital purchasing consortia are consolidating magnification device procurement through centralized optical equipment frameworks. European hospital purchasing consortia in France and the Netherlands are unbundling loupe sales from service contracts, favoring vendors with direct technical support networks. This pattern is most visible in German university hospital systems where standardization committees now mandate interchangeable loupe frames across surgical departments.
Global Medical Loupes Market Segmentation
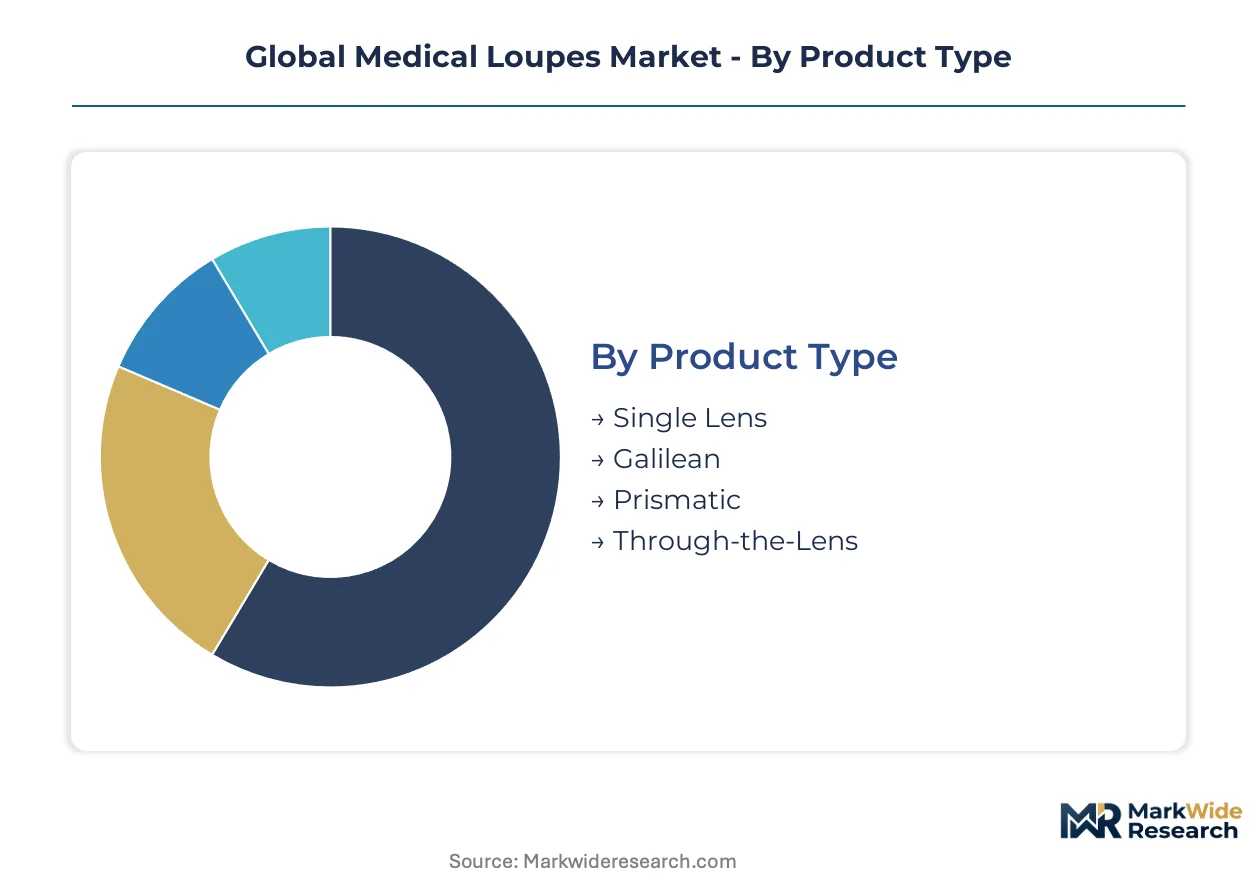
Medical loupe segmentation reveals how optical engineering choices cascade into regulatory pathways and procurement channels. Certification requirements fragment sharply across magnification architectures, with prismatic variants demanding rebuilt clinical evidence dossiers under EU MDR while Galilean configurations leverage grandfathered CE frameworks.
Product Type:
EU MDR optical certification decoupling imposes divergent evidence burdens: Galilean platforms retain streamlined technical files, while prismatic and through-the-lens variants face de novo clinical performance documentation.
- Single Lens:Monocular magnification devices using single coated glass elements, typically 2.0x-3.5x, dominate veterinary field applications in Australia where cost constraints override stereoscopic depth requirements. Procurement concentrates in mobile animal care units serving remote agricultural regions.
- Galilean:Binocular systems employing converging objective and diverging eyepiece lenses deliver 2.5x-4.0x magnification at weights under 45 grams. German dental clinics drive volume demand for routine restorations where adequate field depth and reduced musculoskeletal strain outweigh premium optical specifications.
- Prismatic:Keplerian optical architectures with Schmidt-Pechan or Abbe-König prism assemblies achieve 4.0x-8.0x magnification with edge-to-edge clarity. Microsurgical suites in Japan and dermatology practices in Brazil absorb premium pricing as procedural precision standards tighten.
- Through-the-Lens:Fixed prescription-integrated optics mounted within carrier lenses, requiring precise interpupillary calibration. Veterinary equipment pools across Canada favor this configuration for multi-practitioner sharing protocols.
Galilean configurations sit at the top of the volume ranking, with prismatic variants climbing the fastest.
Application:
Reimbursement architectures determine capital equipment allocation across clinical specialties, with US surgical centers capturing favorable depreciation schedules for magnification investments.
- Dentistry:Restorative and endodontic procedures consume the largest installed base, with South Korean implantology suites piloting AR-integrated overlays for navigated surgery workflows.
- Surgery:Orthopedic and plastic microsurgery demand edge-to-edge resolution at extended working distances. Spanish hospital purchasing consortia are consolidating procurement through centralized optical equipment frameworks.
- Dermatology:Mohs micrographic surgery and cosmetic procedures justify premium prismatic investments. Italian manufacturers are establishing captive metrology laboratories to accelerate EU MDR technical file compilation for this segment.
- Veterinary Medicine:Mixed-animal practices in rural Canada and Australia drive demand for durable, shared-equipment configurations with simplified sterilization protocols.
Dentistry commands the dominant revenue share, while dermatology applications are expanding most quickly.
End User:
Customer procurement authority varies by ownership structure: independent clinics exercise direct purchasing discretion while hospital systems route decisions through standardization committees.
- Dental Clinics:Independent practices in Germany and Brazil select loupes based on individual ergonomic fit, with prismatic variants gaining traction among specialists performing microsurgical procedures.
- Surgical Centers:US ambulatory surgery centers leverage capital equipment upgrade policies favoring magnification device investments. Reimbursement codes for orthopedic and dermatology procedures explicitly cover optical equipment depreciation.
- Skin Care Facilities:Cosmetic dermatology and medspa operators prioritize lightweight Galilean configurations for high-volume aesthetic procedures requiring moderate magnification.
- Animal Care Clinics:Multi-location veterinary groups in Australia standardize on through-the-lens deployments with fixed interpupillary calibration to enable equipment rotation across rotating practitioners.
Dental clinics represent the largest addressable base, with surgical centers showing the steepest expansion trajectory.
Deployment:
Frame architecture selection reflects procedural duration, sterilization frequency, and integration requirements with personal protective equipment.
- Fixed Frame:Non-adjustable loupe-to-eye positioning optimized for single-practitioner dedicated use. German university hospital systems mandate interchangeable frames across surgical departments.
- Flip-up Frame:Hinge mechanisms enabling rapid transition between magnified and direct vision. French hospital purchasing consortia unbundle flip-up loupe sales from service contracts, favoring vendors with direct technical support networks.
- Helmet Mounted:Integrated head protection for trauma and emergency surgical environments requiring simultaneous magnification and impact resistance.
- Headband Mounted:Adjustable circumferential straps distributing weight across the cranium rather than nasal bridges, preferred for extended microsurgical procedures exceeding four hours.
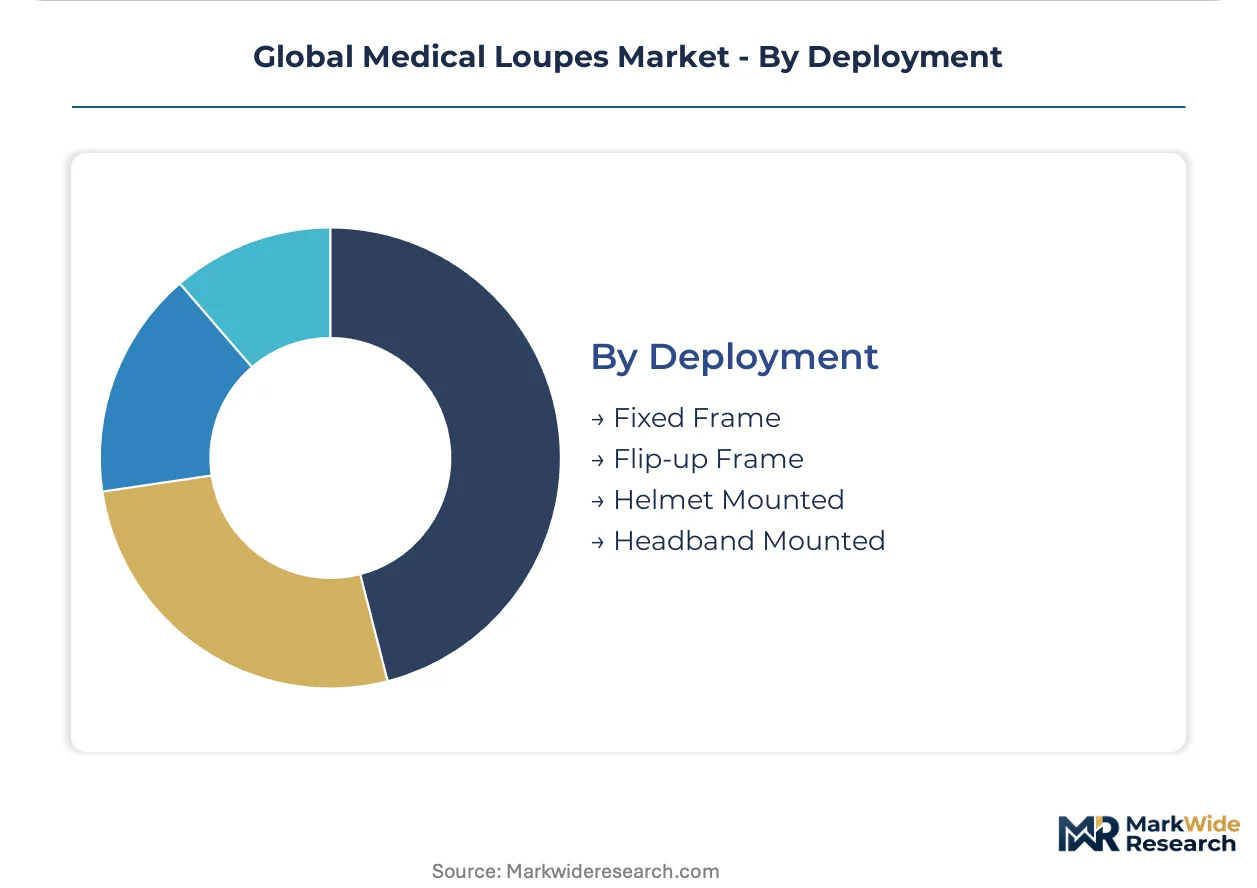
Fixed frame configurations retain the highest installed base, with flip-up variants gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical engineers and Japanese precision machinists anchor the industry's technical workforce, concentrating advanced lens grinding and metrology capabilities in Stuttgart and Osaka manufacturing corridors.
United States
Ambulatory surgical centers in Texas and Florida drive capital equipment procurement as reimbursement codes explicitly cover optical depreciation for orthopedic and dermatology procedures. FDA 510(k) clearance timelines for modified magnification platforms currently stretch 8-14 months, delaying product launches. The Greater Boston cluster hosts precision optics R&D facilities serving dental and microsurgical equipment manufacturers.
Germany
University hospital systems in Bavaria and Baden-Württemberg mandate interchangeable loupe frames across surgical departments, standardizing procurement through centralized optical equipment frameworks. EU MDR Article 10 clinical evidence requirements force manufacturers to rebuild technical files from scratch, elevating compliance costs. Stuttgart's captive lens grinding facilities supply coated glass substrates for prismatic variants.
Japan
Oral surgeons in Tokyo and Osaka implantology suites pilot AR-integrated prismatic loupes overlaying 3D scan data onto operative fields. METI-influenced hospital purchasing consortia require PMDA foreign manufacturer registration for procurement eligibility, creating a structured pathway for vendors. The Nagoya precision manufacturing corridor produces Schmidt-Pechan prism assemblies for Keplerian optical architectures.
Brazil
Dermatology practices in São Paulo and Rio de Janeiro absorb premium prismatic investments as procedural precision standards tighten for Mohs micrographic surgery. ANVISA medical device registration requirements shape product launch sequencing for imported optical equipment. The Campinas medical device cluster hosts service networks for European and North American loupe manufacturers.
Australia
Mixed-animal veterinary practices in New South Wales and Queensland drive demand for through-the-lens configurations with fixed interpupillary calibration enabling equipment rotation across practitioners. TGA medical device regulations govern optical equipment importation and post-market surveillance. Sydney's veterinary equipment distribution hubs serve mobile animal care units across remote agricultural regions.
Global Medical Loupes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across magnification device categories, creating a tiered structure where captive optical component production separates premium positioning from commodity volume. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with captive lens grinding capabilities, specialized dental and surgical optics pure-plays, and contract manufacturers serving private-label distributors. M&A activity concentrates on optical metrology laboratories and AR software integration capabilities, while geographic expansion targets PMDA-registered access to Japanese hospital purchasing consortia.
Among diversified medical technology conglomerates, Carl Zeiss Meditec AG exemplifies the captive supply archetype through German-based precision optics manufacturing. Designs for Vision, Inc. and HEINE Optotechnik GmbH & Co. KG occupy positions within the specialized pure-play tier, with the former representing North American custom configuration capabilities and the latter anchoring European direct service network strategies. These three entities illustrate how optical engineering depth and regulatory compliance infrastructure separate sustainable competitive positioning from transactional component supply.
| Leading Market Players |
|---|
| Enova Illumination |
| Orascoptic |
| Carl Zeiss Meditec AG |
| L.A. Lens |
| Rose Micro Solutions |
| Designs for Vision, Inc. |
| SurgiTel |
| HEINE Optotechnik GmbH & Co. KG |
| Den-Mat Holdings, LLC |
| Others |
Supply & Pricing Matrix
German precision optics engineers and Japanese lens grinding specialists concentrate in Stuttgart and Osaka manufacturing corridors, creating labor-cost differentials that widen pricing-tier spreads between premium prismatic variants and economy Galilean configurations. Their specialized metrology training commands compensation premiums that feed directly into landed costs for edge-to-edge clarity platforms.
Pricing Analysis
The bundled-versus-unbundled service split separates European hospital purchasing consortia from independent dental clinic procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and captive lens grinding capabilities. Price differentiation hinges on after-sales service bundling and direct technical support networks. Cost compression in economy tiers is intensifying because polymer optic alternatives degrade under sterilization cycles. Independent veterinary clinics in Australia exhibit highest price sensitivity; Japanese microsurgical suites show least.
Supply Chain Analysis
Workforce availability for specialized optical metrology technicians constrains scaling in Stuttgart, Osaka, and Nagoya manufacturing corridors. German and Japanese lens grinding facilities control coated glass substrate supply, drawing from barium crown glass and rare-earth coating chemistries. Single-source vulnerability concentrates in Schmidt-Pechan prism assembly production. Distribution runs through hospital purchasing consortia in Europe and GPO contracts in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shift toward prismatic variants as EU MDR decoupling eliminates grandfathered economy-platform advantages. Cost-down drivers center on captive metrology laboratory establishment reducing third-party certification timelines.
For Market Incumbents: Anchor competitive position through backward integration into coated glass substrate production and captive ISO 10993-adjacent biocompatibility testing facilities. AR overlay integration threatens legacy Galilean platforms; defend through accelerated PMDA registration for Japanese hospital purchasing consortia access. Prioritize direct service network density in European university hospital systems where standardization committees mandate interchangeable frame procurement. For New Entrants and Emerging Players: Mobile animal care units in rural Australia represent an underserved buyer archetype with unmet demand for durable, simplified sterilization configurations. Veterinary equipment pools across Canada offer penetrable white-space with fixed interpupillary calibration requirements. Pursue contract manufacturing partnerships with ISO 13485-certified optical component suppliers to bypass captive facility capital requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers lacking direct hospital purchasing consortia relationships. Long-term viability over the next decade hinges on AR software integration capabilities and regulatory compliance infrastructure rather than pure optical engineering scale. Watch FDA 510(k) clearance timeline compression as inflection indicator for US surgical center channel access.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Rebuild | Accelerates market access for prismatic variants through de novo clinical evidence dossiers. |
| PMDA Foreign Manufacturer Registration | Unlocks procurement channels within METI-influenced Japanese hospital purchasing consortia. |
| AR Overlay Software Development | Creates navigated implantology product category for South Korean and Spanish oral surgeons. |
| Captive Metrology Laboratory Establishment | Reduces third-party edge-to-edge clarity testing bottlenecks for EU Article 10 compliance. |
| Direct Service Network Expansion | Captures French and Dutch hospital purchasing consortia unbundling loupe sales from contracts. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and dental clinic procurement officers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EUDAMED vigilance reports, PMDA foreign manufacturer registration databases, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down reimbursement code analysis across the analysis window.
Segment-level outputs across product type, application, end user, and deployment architecture fed into regional adoption pattern modeling. CAGRs derived from procedure volume elasticity to magnification device penetration rates and capital equipment depreciation schedule changes. Forecast inputs incorporated EU MDR implementation timelines and PMDA registration pathway completion rates.
Inputs from EUDAMED and PMDA registration databases were available through the study window; gaps in real-time hospital procurement contract pricing introduce uncertainty bands around premium-tier volume assumptions. Forecasts reflect documented assumptions on reimbursement code stability and optical glass substrate supply continuity. Material deviation in FDA 510(k) timeline compression or EU MDR vigilance reporting burden warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Global Prosthetics Market
Medical Devices
Colposcopes Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Asthma Spacers Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Global Pupillometer Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Oxygenator Market