
 Photopheresis Products Market | 2026-2036
Photopheresis Products Market Size, Share, and Industry Trends Forecast 2026-2036
Photopheresis Products Market Outlook
Germany is reshaping European photopheresis capacity through specialized apheresis centers and academic hospital networks. Fresenius Kabi AG leverages its dialysis and blood management heritage to dominate consumable supply chains across Central Europe. Haemonetics Corporation anchors North American installed base expansion through its cell salvage and therapeutic apheresis platform integration. Terumo Corporation competes in Asia-Pacific markets with automated collection systems that interface with photopheresis workflows.
Photopheresis products comprise devices, consumables, kits, and software designed to perform extracorporeal photochemotherapy, a procedure involving leukapheresis, photoactivation with UVA light and psoralen derivatives, and reinfusion to modulate immune responses. The process requires sterile disposable sets, calibrated irradiation chambers, and specialized photosensitizers to achieve therapeutic lymphocyte apoptosis. Devices and consumables command the dominant revenue share due to recurring kit requirements and capital equipment replacement cycles. Extracorporeal photopheresis technology leads clinical adoption in graft-versus-host disease and cutaneous T-cell lymphoma, while monoclonal antibodies and biologic agents represent adjacent therapeutic competition that shapes procedure volume growth.
FDA oversight of photopheresis devices as combination products creates dual regulatory pathways requiring both device and biologic compliance demonstrations. The EU Medical Device Regulation and EMA guidance on advanced therapy medicinal products impose clinical evidence standards that filter market entrants across Europe. Blood banks and transplant centers in the United States must navigate CMS reimbursement determinations that influence capital procurement timelines. Stakeholders must monitor evolving real-world evidence requirements that will determine competitive positioning in next-generation photopheresis system approvals.
Market Dynamics
Photopheresis product demand concentrates in transplant centers where FDA combination product pathways create dual qualification burdens for device manufacturers seeking biologic-device approvals.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage determinations for extracorporeal photopheresis in graft-versus-host disease treatment accelerate capital procurement cycles at US academic medical centers.
- EMA Advanced Therapy Pathways:The EU Medical Device Regulation harmonization with EMA guidance streamlines market access for next-generation photosensitizer-integrated disposable sets.
- Apheresis Center Density:University hospital networks in Germany establish regional photopheresis hubs that concentrate procedure volumes and drive consumable pull-through economics.
Market Restraints
- Psoralen Supply Concentration:Photosensitizer API production concentrates among three European contract manufacturers, creating input vulnerability for kit assemblers.
- FDA Dual-Pathway Friction:The Center for Devices and Radiological Health and Center for Biologics Evaluation and Research coordination requirements extend qualification timelines by 18-24 months.
- Monoclonal Antibody Substitution:Biologic agents for cutaneous T-cell lymphoma displace photopheresis procedures in second-line therapy positioning.
Strategic Opportunities
- Asia-Pacific Regulatory Alignment:Japan's PMDA cellular therapy framework revisions create first-mover positioning for automated photopheresis collection systems.
- Home-Based Care Extension:Portable irradiation chamber designs enable outpatient photopheresis delivery, opening ambulatory infusion center channels.
- Software-as-Service Integration:Cloud-based treatment protocol management platforms attach recurring revenue to capital equipment placements.
Industry Challenges
- Apheresis Specialist Scarcity:Trained operators for leukapheresis-photopheresis workflows remain concentrated in established academic centers, limiting geographic expansion.
- Legacy System Interoperability:Proprietary disposable set interfaces with third-party cell separators create integration friction during multi-vendor procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photopheresis Products Market |
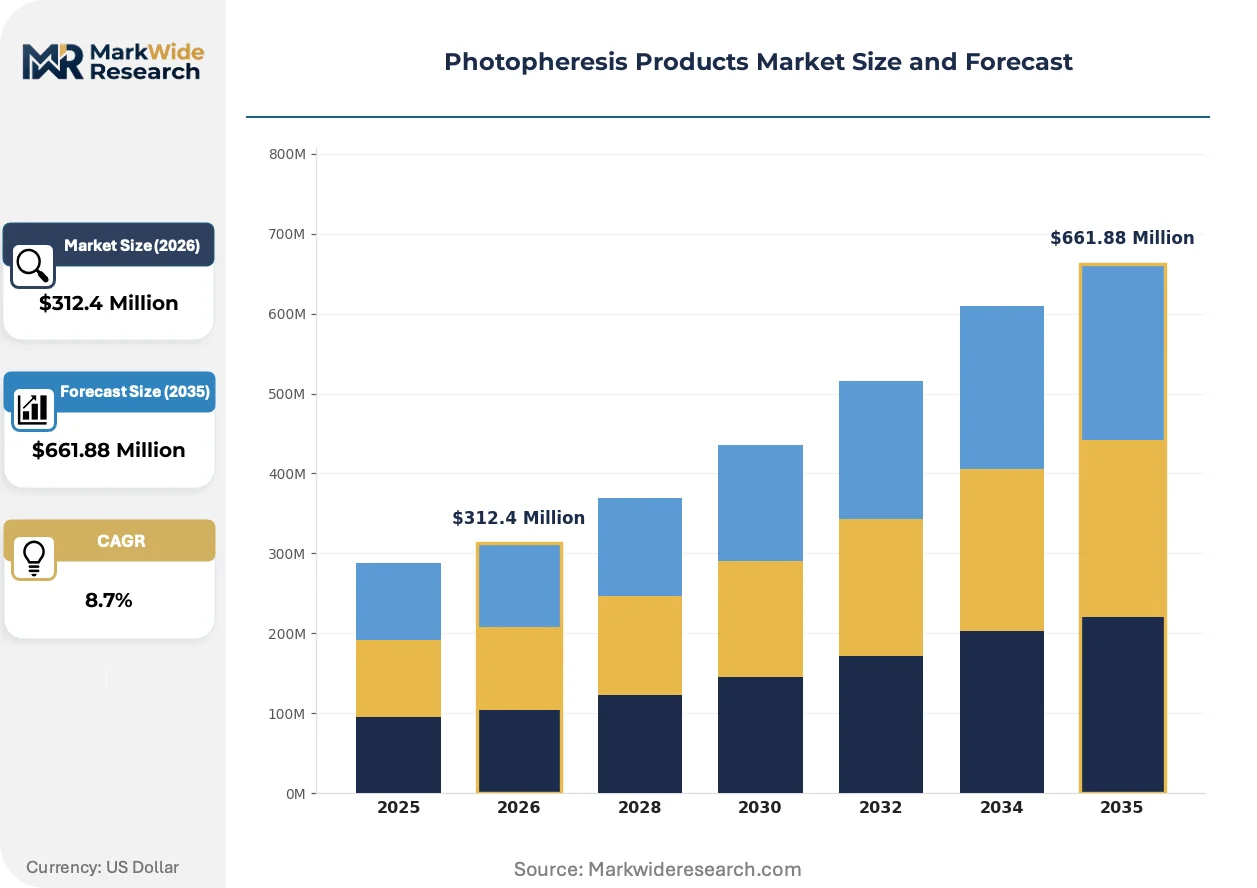
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Consumables, Kits, Software Application: Oncology, Dermatology, Organ Transplantation, Autoimmune Disorders End User: Hospitals, Clinics, Research Institutions, Blood Banks Technology: Extracorporeal Photopheresis, Photosensitizers, Monoclonal Antibodies, Biologic Agents |
| Companies Covered | Haemonetics Corporation, Fresenius Kabi AG, Macopharma, Mallinckrodt Pharmaceuticals, PIT Medical Systems, Terumo Corporation, Med Tech Solutions GmbH, Cerus Corporation, Asahi Kasei Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photopheresis Products Market Strategic Shifts
Closed-system automation and real-time lymphocyte monitoring are compressing treatment variability while regulatory convergence between device and biologic frameworks is reshaping competitive entry requirements.
Next-generation photopheresis platforms are hybridizing leukapheresis collection, photoactivation, and reinfusion into single-disposable workflows that eliminate open-handling steps. Transplant centers in the United States adopt these integrated systems to reduce operator training burden and standardize treatment protocols. This consolidation is compressing the addressable market for standalone irradiation chamber manufacturers while elevating kit economics as the primary margin driver.
The EU Medical Device Regulation's clinical evidence requirements for combination products now mandate post-market surveillance data that EMA coordinates with notified body assessments. Device manufacturers must maintain quality management systems that satisfy both MDR technical documentation and advanced therapy medicinal product traceability standards. This regulatory convergence most affects consumable suppliers seeking CE marking for photosensitizer-integrated disposables, forcing investment in dual-competency regulatory affairs teams.
Hospital procurement departments now unbundle photopheresis service contracts from capital equipment leases, separating disposable supply agreements from maintenance and software licensing. This disintermediation pressures device manufacturers to compete on per-procedure kit pricing rather than bundled system economics. The shift is most visible in German university hospital networks where centralized apheresis programs negotiate multi-site volume contracts with standardized protocol requirements.
Photopheresis Products Market Segmentation
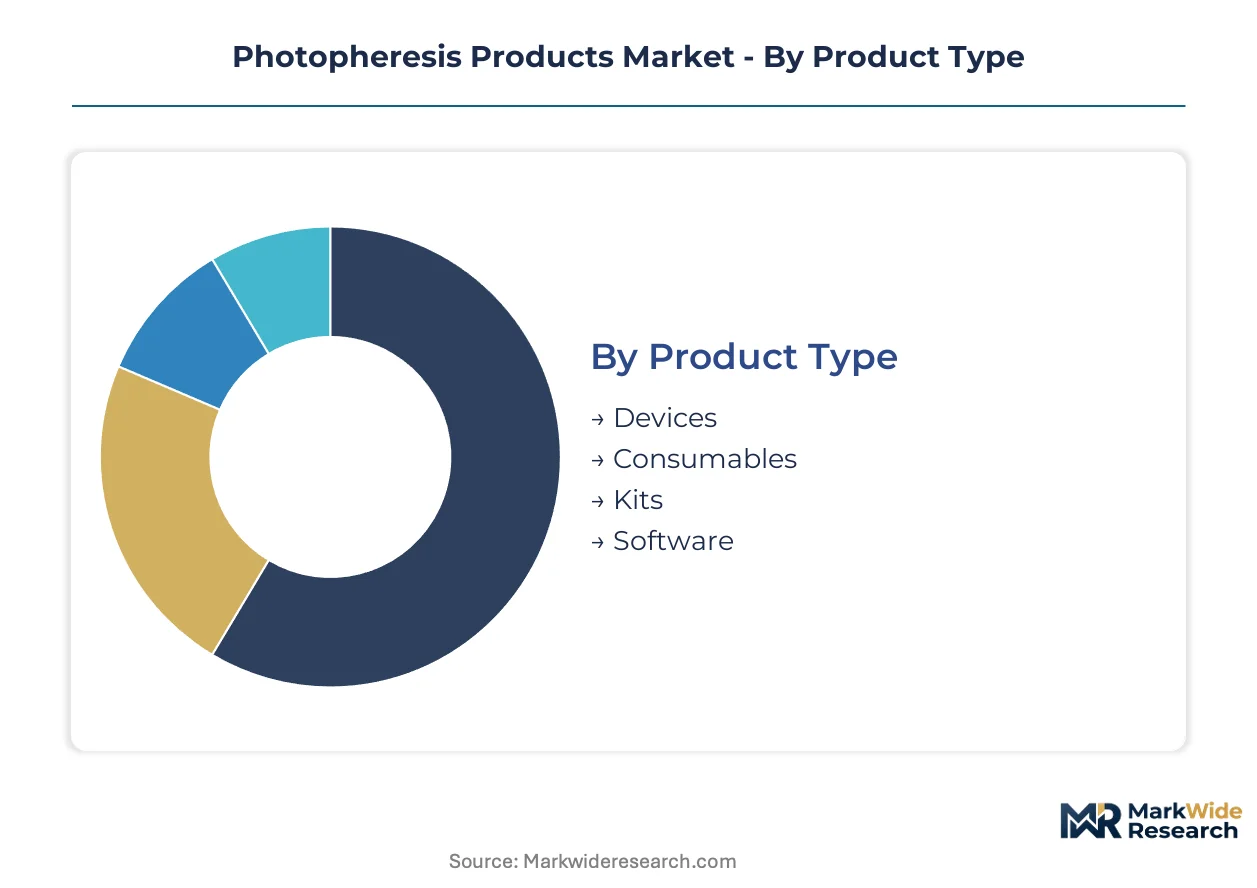
Photopheresis product segmentation reflects the dual nature of this combination therapy market, where capital equipment durability contrasts with recurring consumable demand and where clinical application diversity drives technology specialization across transplant and oncology settings.
Product Type:
Cost tier differentiation separates capital-intensive equipment from recurring consumable revenue streams in photopheresis system economics.
- Devices:Irradiation chambers, cell separators, and integrated system platforms constitute the capital foundation. Transplant centers in the United States prioritize FDA-qualified systems that satisfy combination product pathways, extending procurement cycles but locking in long-term service relationships.
- Consumables:Sterile disposable sets, tubing circuits, and collection containers generate recurring revenue per procedure. German university hospital networks negotiate multi-site volume contracts that standardize protocol requirements across regional apheresis hubs.
- Kits:Pre-assembled procedure packages integrate photosensitizer vials with disposable hardware for streamlined workflow execution.
- Software:Treatment protocol management platforms and cloud-based monitoring systems attach subscription revenue to installed equipment bases.
Consumables command the established base. The steepest expansion runs through integrated kit offerings that compress procedure variability.
Application:
Clinical application diversity spans malignant, autoimmune, and iatrogenic conditions with distinct reimbursement and protocol maturity profiles.
- Oncology:Cutaneous T-cell lymphoma represents the original photopheresis indication with established Medicare coverage. Academic medical centers maintain dedicated protocols, though biologic agent substitution pressures second-line positioning.
- Organ Transplantation:Graft-versus-host disease prophylaxis and treatment drives procedure volume acceleration. CMS reimbursement expansion for extracorporeal photopheresis in this indication compresses capital procurement timelines at US transplant centers.
- Dermatology:Autoimmune skin conditions including scleroderma and epidermolysis bullosa comprise niche applications with evolving evidence bases.
- Autoimmune Disorders:Systemic lupus erythematosus and inflammatory bowel disease represent investigational extensions with protocol development ongoing.
Organ transplantation commands the established base. The steepest expansion runs through oncology applications facing biologic competition.
End User:
Customer type concentration reflects the specialized infrastructure and operator training requirements that limit photopheresis to institutional settings.
- Hospitals:Academic medical centers and transplant institutes concentrate installed base capacity. Apheresis specialist scarcity constrains geographic expansion beyond established university networks.
- Clinics:Ambulatory infusion centers represent emerging channels as portable irradiation chamber designs enable outpatient delivery.
- Research Institutions:Protocol development and clinical trial execution drive specialized system configurations with enhanced data capture capabilities.
- Blood Banks:Therapeutic apheresis programs leverage existing cell separation infrastructure for photopheresis service line extension.
Hospitals command the established base. The steepest expansion runs through clinic channels enabled by workflow miniaturization.
Technology:
Technology maturity spans from established photochemotherapy platforms to adjacent biologic modalities that compete for therapeutic positioning.
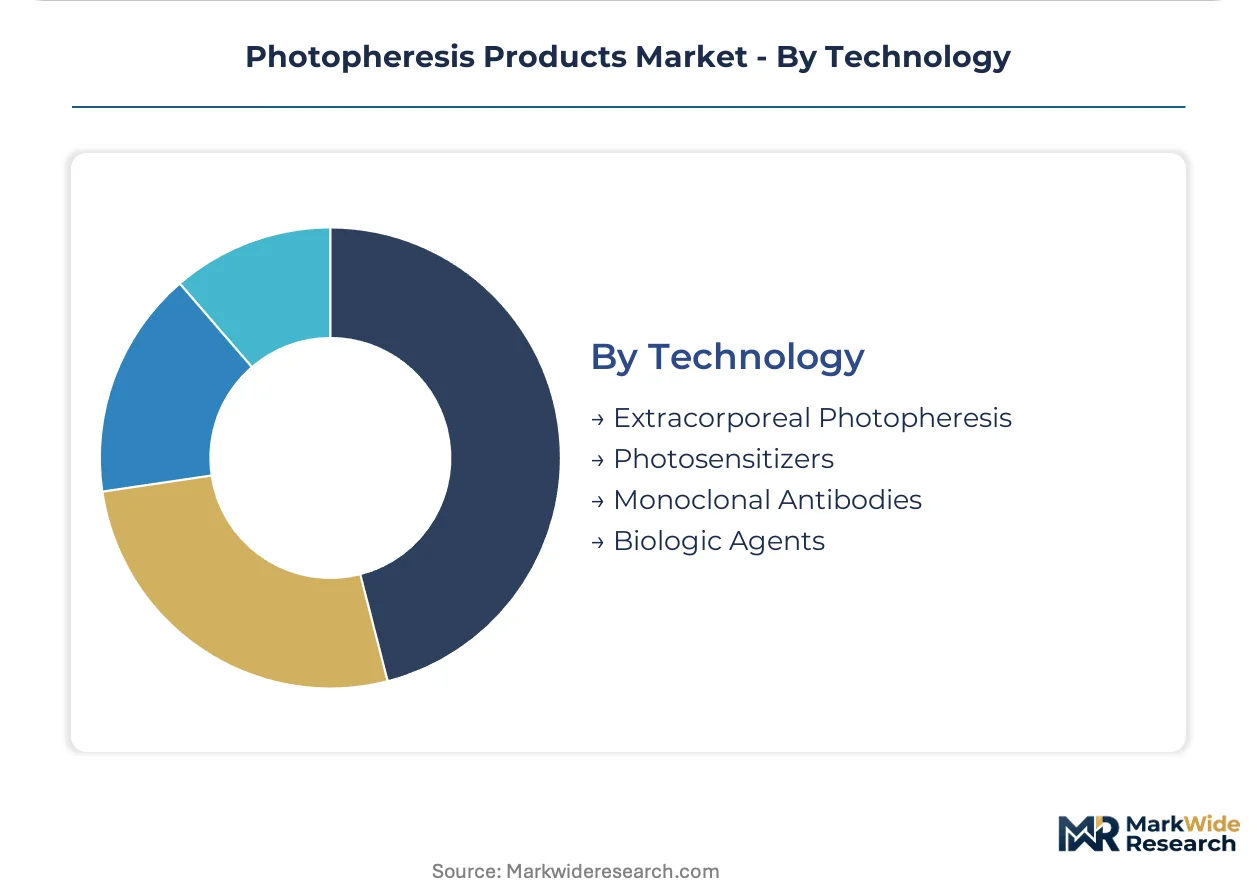
- Extracorporeal Photopheresis:The core procedure combining leukapheresis, UVA photoactivation, and reinfusion dominates clinical adoption. EMA advanced therapy pathway harmonization with MDR requirements streamlines European market access for next-generation disposable integrations.
- Photosensitizers:Psoralen derivatives including 8-methoxypsoralen enable lymphocyte photoactivation. API production concentration among three European contract manufacturers creates input vulnerability for kit assemblers.
- Monoclonal Antibodies:Alemtuzumab and rituximab displace photopheresis in select lymphoma protocols.
- Biologic Agents:Brentuximab vedotin and mogamulizumab reshape cutaneous T-cell lymphoma treatment algorithms.
Extracorporeal photopheresis commands the established base. The steepest expansion runs through photosensitizer-integrated disposable innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photosensitizer API manufacturing concentrates among three European contract manufacturers, creating input vulnerability for kit assemblers worldwide. This supply-side clustering shapes procurement patterns across transplant centers and academic medical networks.
United States
FDA dual-pathway coordination between CDRH and CBER extends device qualification timelines by 18-24 months. CMS reimbursement determinations for extracorporeal photopheresis in graft-versus-host disease accelerate capital procurement at academic medical centers. Transplant institutes in Boston and Pittsburgh operate established apheresis programs with dedicated photopheresis protocols.
Germany
University hospital networks establish regional photopheresis hubs that concentrate procedure volumes and drive consumable economics. EMA advanced therapy pathway harmonization with MDR requirements streamlines CE marking for photosensitizer-integrated disposable sets. Apheresis centers in Munich and Heidelberg maintain standardized protocols across multi-site volume contracts.
Japan
PMDA cellular therapy framework revisions create first-mover positioning for automated photopheresis collection systems. METI funding for advanced medical device development supports domestic manufacturing capability. Tokyo and Osaka transplant centers pilot integrated workflow platforms with real-time lymphocyte monitoring.
United Kingdom
NHS specialized commissioning frameworks determine photopheresis service availability across transplant networks. MHRA post-Brexit regulatory alignment with MDR technical documentation requirements filters market entrants. London teaching hospitals anchor national procedure volume with dedicated cutaneous T-cell lymphoma protocols.
France
ANSM oversight of combination products imposes dual device-biologic compliance demonstrations for market access. Hospital procurement centralization through regional health agencies consolidates disposable set purchasing power. Paris and Lyon academic centers coordinate multicenter photopheresis trials through the French Society of Apheresis.
Photopheresis Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in photosensitizer and disposable manufacturing. The market structures around three tiers: multinational medical device conglomerates with apheresis heritage, mid-scale European kit assemblers with regional hospital relationships, and niche consumable suppliers focused on photosensitizer integration. Dominant competitive moves include strategic partnerships between device manufacturers and photosensitizer suppliers, plus geographic expansion into Asia-Pacific regulatory environments.
Among diversified medical technology conglomerates, Haemonetics Corporation and Fresenius Kabi AG exemplify platform integrators with apheresis system legacies. Terumo Corporation represents the Asia-Pacific vector with automated collection expertise. Mid-scale specialists including Macopharma and Mallinckrodt Pharmaceuticals occupy positions in European consumable supply, while PIT Medical Systems and Med Tech Solutions GmbH exemplify regional kit assemblers with concentrated academic hospital relationships.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Fresenius Kabi AG |
| Macopharma |
| Mallinckrodt Pharmaceuticals |
| PIT Medical Systems |
| Terumo Corporation |
| Med Tech Solutions GmbH |
| Cerus Corporation |
| Asahi Kasei Medical |
| Others |
Value Chain & Pricing Dynamics
Photosensitizer API production concentrates among three European contract manufacturers, anchoring margin capture in the consumable tier while device manufacturers compete on bundled system economics. This upstream clustering shapes procurement leverage for kit assemblers and creates pricing power asymmetries across the photopheresis value chain.
Pricing Analysis
FDA combination product pathways dictate the pricing tier structure across photopheresis systems, with dual-pathway compliance costs elevating premium tiers for FDA-qualified platforms while standard tiers serve European CE-marked alternatives. Three-tier pricing separates premium integrated systems from standard modular configurations and economy standalone irradiation chambers, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in the standard tier is intensifying because hospital procurement departments now unbundle service contracts from equipment leases. Academic medical centers exhibit lowest price sensitivity due to reimbursement coverage, while ambulatory clinics face highest sensitivity to per-procedure kit costs.
Supply Chain Analysis
European contract manufacturers hold photosensitizer API capacity, with production clustering in Germany, Italy, and Switzerland for psoralen derivative synthesis. Kit assembly draws from specialized tubing and sterile disposable suppliers in France and the Netherlands, with irradiation chamber fabrication concentrated in Germany and Japan. Single-source vulnerability runs through the three API manufacturers, where any disruption would cascade to global kit assemblers. Distribution runs through regional apheresis hub networks that consolidate multi-site volume contracts, with German university hospital networks setting procurement templates adopted across Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photopheresis incumbents face substitution pressure from monoclonal antibodies and biologic agents in cutaneous T-cell lymphoma protocols, requiring defensive positioning around procedure workflow integration and operator training lock-in.
For Market Incumbents: Pre-empt biologic substitution by embedding photopheresis protocols deeper into transplant center workflows through software-as-service platforms that attach recurring revenue to capital placements. Secure backward integration into photosensitizer supply through exclusive API sourcing agreements with European contract manufacturers, reducing input vulnerability while capturing margin upstream. FDA dual-pathway friction represents both barrier and moat—extend qualification timelines for competitors while accelerating own submissions through pre-submission meetings with CDRH-CBER coordination staff. For New Entrants and Emerging Players: Pursue Asia-Pacific regulatory alignment as the most penetrable expansion corridor, where Japan's PMDA cellular therapy framework revisions create first-mover positioning for automated collection systems. Target clinic channels enabled by portable irradiation chamber miniaturization, where outpatient photopheresis delivery remains underdeveloped and procurement decisions sit with ambulatory infusion center operators rather than centralized hospital committees. A reimbursement strategy anchored to CMS coverage expansion for graft-versus-host disease offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale kit assemblers with established European academic hospital relationships and regulatory affairs teams competent in both MDR technical documentation and EMA advanced therapy medicinal product standards. Long-term viability hinges on consolidation of fragmented consumable supply tiers, with photosensitizer-integrated disposable innovation representing the primary margin expansion vector. Watch for inflection in monoclonal antibody pricing and reimbursement positioning as signal of substitution pressure intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coverage expansion for graft-versus-host disease accelerates capital procurement cycles at US academic medical centers. |
| Regulatory Approval Pathway | FDA dual-pathway coordination with CDRH and CBER extends timelines but locks in premium positioning for qualified systems. |
| Backward Integration | Exclusive API sourcing agreements with European contract manufacturers reduce photosensitizer supply vulnerability. |
| Software Companion Development | Cloud-based protocol management platforms attach recurring revenue to installed equipment bases. |
| Hospital System Partnership | German university hospital networks standardize multi-site volume contracts across regional apheresis hubs. |
Study Parameters
A standing panel of apheresis specialists, transplant center procurement managers, biomedical engineers, and regulatory affairs directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA advanced therapy medicinal product submissions, CMS Medicare coverage determinations, and hospital procurement database extracts. Bottom-up procedure volume modeling triangulated against top-down market sizing from capital equipment installed base estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, clinical application, end-user infrastructure tier, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, equipment replacement cycles, and consumable pull-through economics modeled separately for transplant and oncology indications. Forecast inputs incorporated photosensitizer supply constraints, apheresis specialist scarcity, and evolving real-world evidence requirements for combination product approvals.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, reimbursement policy shifts, or biologic pricing would shift the trajectory. Forecasts reflect documented assumptions regarding procedure volume growth, regulatory pathway timelines, and competitive entry patterns. Quarterly review of CMS national coverage determinations, EMA advanced therapy pathway guidance updates, and monoclonal antibody clinical trial readouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Light Therapy Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Global Bone Cement Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Water Flosser Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
US Stethoscope Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Cryosurgery Devices Market