
 Cerebral Vascular Stent Market | 2026-2036
Cerebral Vascular Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Vascular Stent Market Analysis
Germany is narrowing its manufacturing gap in cerebral stent production through precision nitinol processing clusters in the Baden-Württemberg region. Stryker Corporation leverages its neurovascular portfolio breadth to sustain integrated supply chains across European and North American stroke centers. Medtronic plc anchors its position through deep R&D investment in self-expanding platform architectures. Boston Scientific Corporation competes on catheter-based delivery system refinement for tortuous intracranial anatomy.
A cerebral vascular stent is a tubular implantable device, typically fabricated from nickel-titanium alloys or cobalt-chromium, designed to scaffold intracranial arteries and maintain luminal patency following endovascular revascularization for ischemic stroke or cerebral aneurysm management. The device deploys via microcatheter systems under fluoroscopic guidance, with radial force and fatigue resistance as critical functional parameters governing clinical performance. Self-expanding stents dominate procedural volume in tortuous vessel anatomy where conformability outweighs precise diameter control, while balloon-expandable platforms capture higher-margin cases requiring exact landing zone apposition. Endovascular delivery mode generates the fastest growth trajectory as transfemoral and transradial access techniques displace open surgical revascularization in eligible patients.
FDA premarket approval and EU MDR notified body conformity assessment create divergent evidence burdens, with the latter demanding more extensive clinical follow-up datasets for nitinol-based permanent implants. Japan's PMDA imposes additional pharmacovigilance reporting requirements that shape post-market surveillance investment by manufacturers. China's NMPA accelerates review timelines for innovative devices through its priority review pathway, altering market access sequencing for multinational firms. Stakeholders must monitor how reimbursement recalibration for thrombectomy-plus-stenting protocols against stenting-alone indications reshapes hospital purchasing criteria and procedure economics across major markets.
Market Dynamics
Stroke center network expansion is compressing device procurement timelines as hospital systems consolidate neurointerventional purchasing authority under centralized supply chain committees.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter conformity assessment requirements for nitinol implants are accelerating manufacturer investment in post-market surveillance infrastructure.
- Transradial access protocols:Adoption of wrist-based catheter entry is expanding eligible patient pools beyond traditional transfemoral candidates.
- Japan's aging cerebrovascular burden:PMDA pharmacovigilance frameworks are driving procedural volume in metropolitan stroke centers.
Market Restraints
- Nitinol raw material concentration:Precision alloy processing capabilities cluster in Baden-Württemberg and select East Asian suppliers.
- FDA premarket approval timelines:Extended review cycles for novel intracranial platforms delay commercialization by 18-36 months.
- Microcatheter supply dependency:Tortuous anatomy delivery systems rely on concentrated polymer extrusion expertise.
Strategic Opportunities
- China NMPA priority review:Accelerated pathways for innovative devices enable earlier market access sequencing.
- Self-expanding platform convergence:Integration of flow-diverting and stenting functions creates hybrid procedure categories.
- Rural stroke center penetration:Underserved regions in India and Southeast Asia lack neurointerventional infrastructure.
Industry Challenges
- Interventional neuroradiologist scarcity:Fellowship-trained specialists remain concentrated in tertiary academic centers.
- Fluoroscopy suite capex requirements:Biplane angiography systems demand seven-figure capital commitments.
- EU MDR notified body capacity:Bottlenecked conformity assessment queues delay certificate renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Vascular Stent Market |
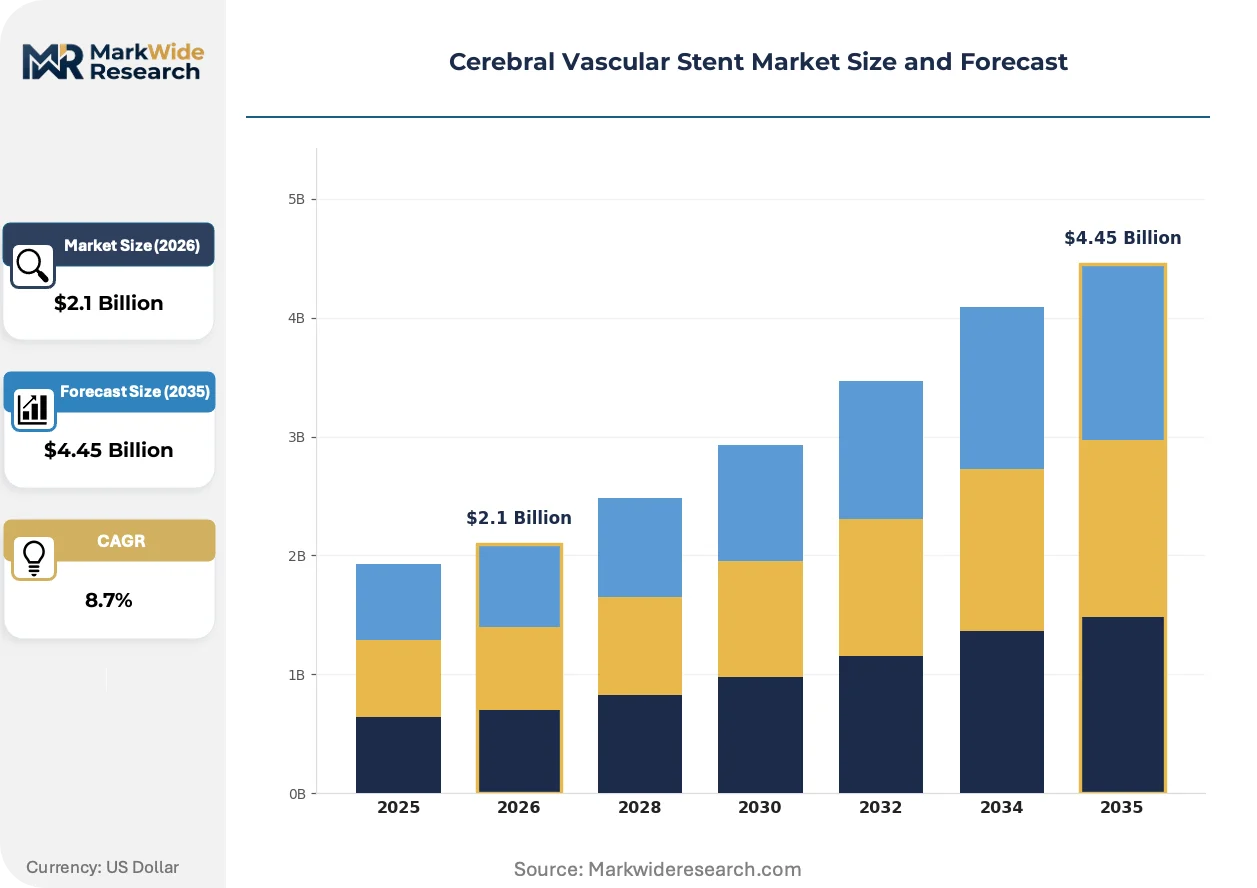
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Coated Stents, Bioresorbable Stents End User: Hospitals, Outpatient Clinics, Surgical Centers, Rehabilitation Facilities Material: Stainless Steel, Cobalt-Chromium Alloys, Polymer, Nickel-Titanium Delivery Mode: Transfemoral, Transradial, Open Surgery, Endovascular |
| Companies Covered | Stryker Corporation, Boston Scientific Corporation, Medtronic plc, Johnson & Johnson Services, Inc., Terumo Corporation, Abbott Laboratories, Penumbra, Inc., Acandis GmbH, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Vascular Stent Market Emerging Trajectories
Device architecture is converging around conformability and fatigue resistance as tortuous intracranial anatomy demands more from implant materials and delivery mechanics.
Bioresorbable magnesium alloys are collapsing the distinction between temporary scaffolding and permanent implant strategies in cerebral revascularization. Academic medical centers in Germany and Japan are piloting these platforms in aneurysm neck reconstruction cases. The technology is collapsing long-term antiplatelet pharmacotherapy burdens that currently constrain procedural candidacy.
EU MDR post-market clinical follow-up requirements are extending evidence generation timelines for nitinol-based permanent implants. Manufacturers must now maintain 10-15 year patient registries to support continued CE marking. High-volume stroke centers in France and the Netherlands are restructuring procurement contracts to accommodate device-specific surveillance obligations.
Hospital purchasing committees are consolidating neurointerventional device authority under system-wide value analysis teams. Independent community hospitals are ceding vendor negotiation to integrated delivery networks with centralized supply chain leverage. This concentration is most visible in United States metropolitan markets where stroke center certification drives network affiliation decisions.
Cerebral Vascular Stent Market Segmentation
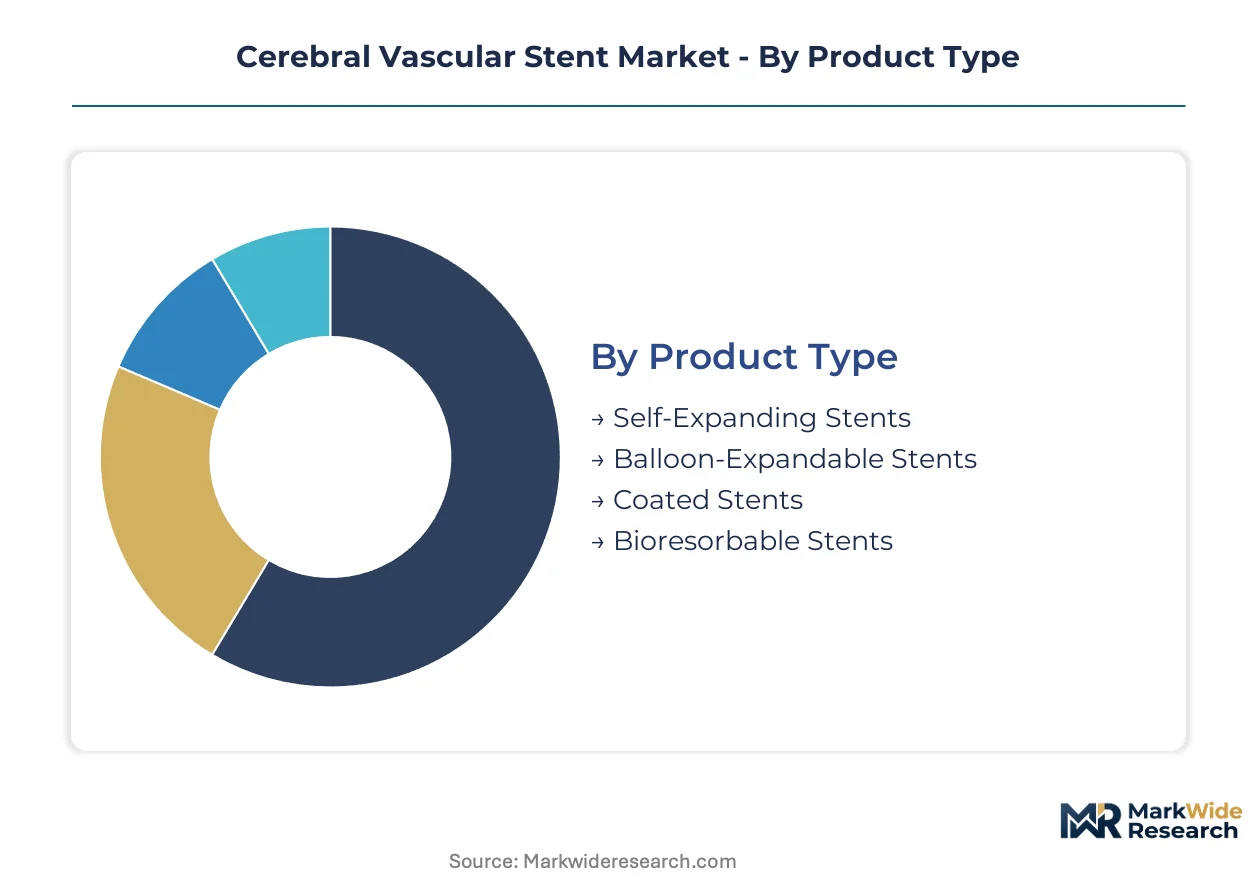
Segmentation in cerebral vascular stents reveals how device architecture, access technique, and care setting interact to determine procedural economics. Manufacturers configure platform portfolios around specific anatomical challenges and reimbursement pathways rather than pursuing universal designs.
Product Type:
Mature self-expanding platforms anchor procedural volume while emerging bioresorbable technologies reshape long-term antiplatelet management.
- Self-Expanding Stents:Nitinol-based architectures deliver radial force through superelastic deformation, conforming to tortuous intracranial geometry without balloon assistance. Stryker and Medtronic concentrate manufacturing in Baden-Württemberg precision clusters to serve European and North American stroke center networks. These devices handle the majority of ischemic stroke revascularization where vessel tortuosity exceeds balloon-expandable navigability.
- Bioresorbable Stents:Magnesium alloy scaffolds provide temporary luminal support before dissolving into biocompatible byproducts, eliminating permanent foreign body burden. Academic medical centers in Germany and Japan pilot these in aneurysm neck reconstruction cases where lifelong antiplatelet therapy would compromise patient candidacy. This segment is gaining share fastest as EU MDR post-market surveillance frameworks mature for absorbable implants.
- Balloon-Expandable Stents:Cobalt-chromium platforms enable precise diameter control at landing zones with less favorable vessel compliance.
- Coated Stents:Drug-eluting or thromboresistant surface modifications target restenosis reduction in recurrent stenosis cases.
Self-expanding stents handle the majority of throughput; bioresorbable stents are the fastest mover on share.
End User:
Care setting stratification follows stroke center certification tiers and capital equipment concentration patterns.
- Hospitals:Comprehensive stroke centers with biplane angiography suites perform the full spectrum of neurointerventional procedures. These facilities in the United States, Germany, and Japan capture complex aneurysm and tandem occlusion cases requiring multidisciplinary ICU support. Hospital purchasing committees consolidate device procurement authority under centralized value analysis teams, compressing vendor negotiation leverage.
- Outpatient Clinics:Ambulatory settings with C-arm fluoroscopy capability handle elective diagnostic cerebral angiography and low-risk stenting surveillance. Metropolitan markets in Japan leverage these clinics to manage post-procedural follow-up without tertiary center congestion. This segment climbs the fastest as transradial protocols reduce recovery monitoring requirements.
- Surgical Centers:Focused facilities concentrate on scheduled aneurysm embolization with overnight observation capacity.
- Rehabilitation Facilities:Post-acute settings manage functional recovery coordination following successful revascularization.
Hospitals dominate absolute procedural volume; outpatient clinics show the steepest expansion trajectory.
Material:
Alloy selection trades off between fatigue resistance, magnetic resonance imaging compatibility, and manufacturing process control.
- Nickel-Titanium:Superelastic nitinol dominates self-expanding platforms through its ability to recover substantial deformation without permanent strain. Baden-Württemberg processing clusters supply precision alloy tubing to Stryker and Medtronic manufacturing lines. Raw material concentration in select East Asian and German suppliers creates supply vulnerability.
- Cobalt-Chromium Alloys:High radial strength and thin strut profiles enable balloon-expandable designs with minimal crossing profiles. These alloys serve cases requiring exact apposition at vessel origins and bifurcations. Demand concentrates in stroke centers performing carotid-subclavian interventions.
- Stainless Steel:Legacy platform material with established fatigue characterization but inferior conformability.
- Polymer:Bioresorbable scaffolds and temporary flow diverters employ absorbable polymers with controlled degradation kinetics.
Nickel-titanium handles the majority of throughput; cobalt-chromium alloys are the fastest mover on share.
Delivery Mode:
Access technique evolution is displacing open surgical revascularization in eligible anatomies.
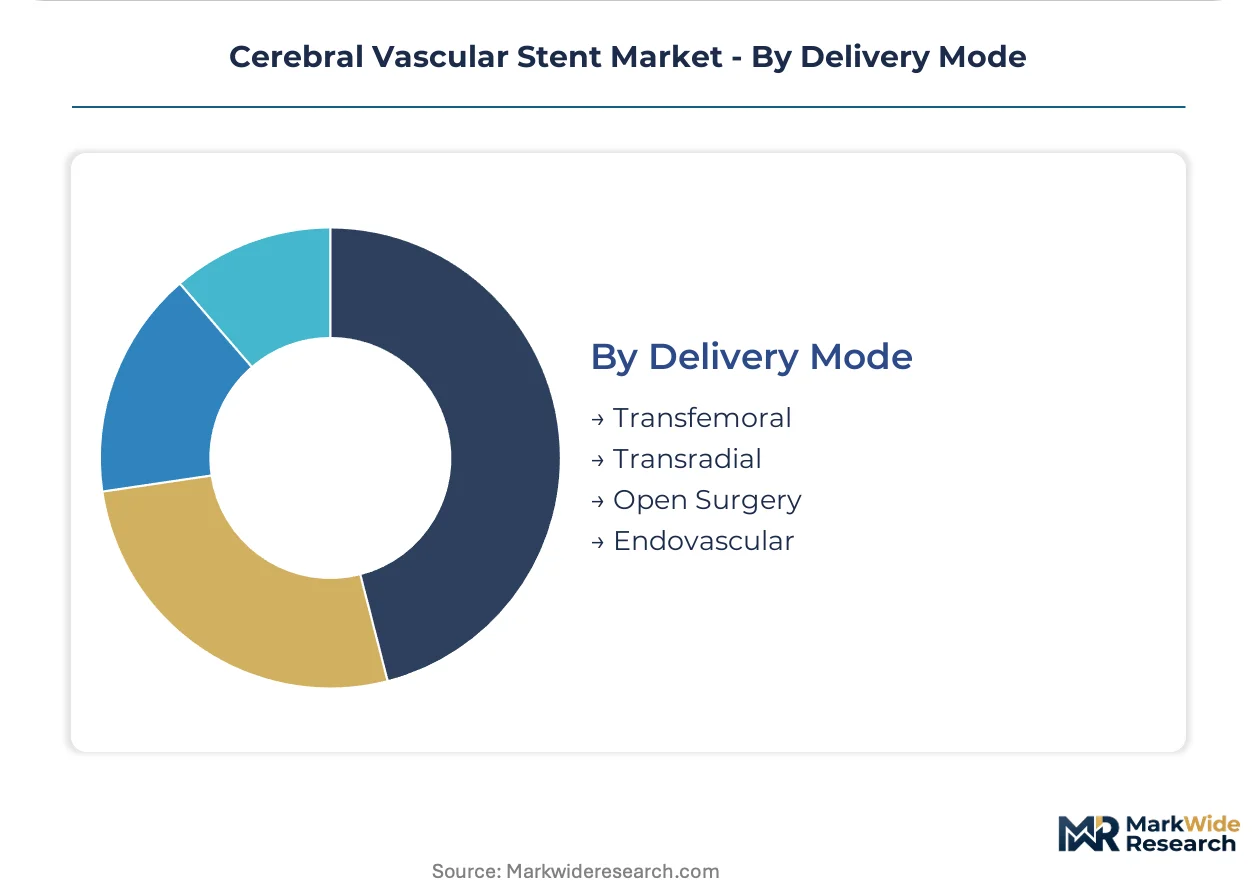
- Endovascular:Catheter-based deployment via transfemoral or transradial access has become the default approach for intracranial stenosis and aneurysm management. Fluoroscopic guidance with roadmap angiography enables precise positioning without craniotomy. This mode captures the steepest expansion trajectory as device miniaturization extends treatable anatomy.
- Transradial:Wrist-based catheter entry reduces groin complications and enables same-day discharge protocols. Japanese stroke centers pioneered systematic transradial neurointervention; United States networks are replicating these workflows. This segment expands most quickly as operator training curricula standardize.
- Transfemoral:Traditional groin access remains the fallback for tortuous aortic arches and large-bore device requirements.
- Open Surgery:Craniotomy with direct vessel access persists for giant aneurysms and failed endovascular cases.
Endovascular delivery handles the majority of throughput; transradial access is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Maasvlakte medical device corridor anchors European neurointerventional distribution, while the Yokohama-Kawasaki industrial belt underwrites Japanese precision manufacturing for cerebral stent platforms.
United States
Comprehensive stroke center certification drives hospital network consolidation across metropolitan markets. FDA premarket approval pathways impose 18-36 month review cycles for novel intracranial platforms. The Minneapolis-Saint Paul corridor concentrates Medtronic's self-expanding stent R&D infrastructure.
Germany
Baden-Württemberg's nitinol processing clusters supply precision alloy tubing to Stryker and Medtronic manufacturing lines. EU MDR notified body conformity assessments demand 10-15 year post-market clinical follow-up for permanent implants. The Stuttgart-Tübingen medical technology corridor deepens vertical integration into superelastic alloy fabrication.
Japan
PMDA pharmacovigilance frameworks shape post-market surveillance investment by manufacturers serving aging cerebrovascular patient populations. METI industrial policy supports domestic production of bioresorbable magnesium scaffolds. The Osaka-Kobe medical device cluster pilots hybrid flow-diverting stent platforms in academic medical centers.
China
NMPA priority review pathways accelerate market access for innovative intracranial devices through compressed regulatory timelines. The Shanghai-Suzhou medical technology corridor attracts multinational manufacturing relocation for nitinol-based platforms. Domestic firms leverage cost positioning to capture volume in tier-2 and tier-3 hospital stroke centers.
India
CDSCO medical device regulations tighten import quality requirements for neurointerventional implants while streamlining domestic manufacturing approvals. The Maharashtra-Gujarat pharmaceutical and device corridor develops catheter-based delivery system capabilities. Mumbai and Ahmedabad tertiary centers expand neurointerventional fellowship programs to address specialist scarcity.
Cerebral Vascular Stent Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision alloy tubing and polymer extrusion expertise. The vendor base organizes around three strategic archetypes: diversified medtech conglomerates with neurovascular portfolio breadth, pure-play neurointerventional specialists, and emerging domestic champions in China and India. Competitive positioning hardens through M&A consolidation of stroke center distribution networks and backward integration into nitinol raw material processing.
Among diversified conglomerates, Stryker Corporation and Medtronic plc exemplify platform integrators leveraging manufacturing scale across European and North American stroke center networks. Boston Scientific Corporation occupies a position refining catheter-based delivery systems for tortuous intracranial anatomy. Acandis GmbH represents the specialist archetype, anchoring precision engineering capabilities within German industrial clusters.
| Leading Market Players |
|---|
| Stryker Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| Johnson & Johnson Services, Inc. |
| Terumo Corporation |
| Abbott Laboratories |
| Penumbra, Inc. |
| Acandis GmbH |
| MicroPort Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's precision nitinol processing clusters concentrate superelastic alloy tubing supply for Stryker and Medtronic manufacturing lines, anchoring margin capture upstream while hospital purchasing committees compress vendor leverage downstream through centralized stroke center procurement.
Pricing Analysis
FDA premarket approval pathways dictate the pricing tier structure across cerebral vascular stent platforms. Three-tier pricing structure across premium, standard, and economy levels separates flow-diverting hybrid devices from conventional self-expanding platforms and commodity balloon-expandable alternatives. Price differentiation hinges on CE marking tier under EU MDR and volume scale through integrated delivery network contracts. Cost compression in standard-tier nitinol stents is intensifying because Baden-Württemberg suppliers face capacity constraints. Tier-2 hospital stroke centers in China and India exhibit highest price sensitivity; comprehensive stroke centers in Germany and Japan demonstrate lowest sensitivity due to reimbursement clarity.
Supply Chain Analysis
Precision nitinol tubing contract manufacturers in Baden-Württemberg and select East Asian suppliers hold captive capacity for superelastic alloy processing. Raw material sourcing draws from nickel and titanium concentrate suppliers in Australia, Indonesia, and Canada. Polymer extrusion expertise for microcatheter delivery systems clusters in Massachusetts and Osaka-Kobe medical device corridors. Single-source vulnerability concentrates in EU MDR notified body capacity for conformity assessment renewals. Distribution runs through stroke center network procurement committees with consolidated vendor negotiation authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioresorbable magnesium alloy platforms are disrupting permanent nitinol implant economics, with EU MDR post-market surveillance frameworks accelerating evidence generation timelines that reshape competitive positioning.
For Market Incumbents: Build regulatory data moats through 10-15 year patient registries required for EU MDR CE marking renewal of permanent nitinol implants. Backward integration into Baden-Württemberg precision alloy processing secures supply continuity against East Asian competitor expansion. Hospital purchasing committee consolidation threatens vendor negotiation leverage; GPO contract penetration becomes essential.
For New Entrants and Emerging Players: Build out bioresorbable scaffold manufacturing capabilities targeting aneurysm neck reconstruction cases where lifelong antiplatelet therapy disqualifies permanent implant candidates. Rural stroke center penetration in India and Southeast Asia offers the most penetrable geography given neurointerventional infrastructure gaps. Transradial access training partnerships with Japanese stroke centers provide differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German precision engineering specialists holding EU MDR notified body relationships and nitinol processing expertise. The 5-10 year viability window favors platforms with hybrid flow-diverting and stenting convergence. Monitor NMPA priority review pathway acceleration as inflection signal for China market access sequencing shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Clinical Follow-Up Investment | Ten-year patient registries satisfy notified body demands for permanent nitinol implant CE marking continuity. |
| Transradial Access Protocol Standardization | Wrist-based catheter entry expands eligible patient pools beyond traditional transfemoral candidates in Japanese stroke centers. |
| Bioresorbable Magnesium Alloy Platform Development | Temporary scaffolding eliminates permanent foreign body burden in aneurysm neck reconstruction cases. |
| Baden-Württemberg Precision Cluster Expansion | Captive nitinol tubing supply insulates against East Asian raw material concentration risks. |
| China NMPA Priority Review Pathway Engagement | Accelerated regulatory timelines enable earlier market access sequencing for innovative intracranial devices. |
Methodological Framework
Desk research of FDA premarket approval filings, EU MDR notified body guidance documents, and PMDA pharmacovigilance frameworks preceded structured interviews with interventional neuroradiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement data, and stroke center certification records. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data.
Assumptions held EU MDR notified body capacity constraints and FDA review cycle durations within observed patterns while varying China NMPA priority review pathway adoption rates and transradial access protocol diffusion speeds across the projection horizon. Segmentation modeling incorporated product architecture, delivery mode, material alloy, and stroke center certification tier. CAGRs derived from procedural volume elasticities against aging demographic projections and reimbursement pathway stability.
The forecast holds incumbent behavior within observed patterns; aggressive bioresorbable platform investment by emerging domestic champions would shift outcomes beyond modeled ranges. Quarterly review of EU MDR certificate renewal queues and NMPA priority review granting rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
Shock Wave Therapy Devices Market