
 Medical Manifolds Market | 2026-2036
Medical Manifolds Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Manifolds Market Outlook
Hospital procurement of fluid management systems is consolidating around fewer approved vendors with full-line capabilities. Merit Medical Systems leverages its vertical manufacturing footprint to sustain catheter lab share across integrated manifold sets. B. Braun Melsungen AG anchors European hospital contracts through reusable manifold platforms with validated sterilization protocols. Smiths Medical competes on anesthesia manifold specialization, dominating UK and North American acute care installations.
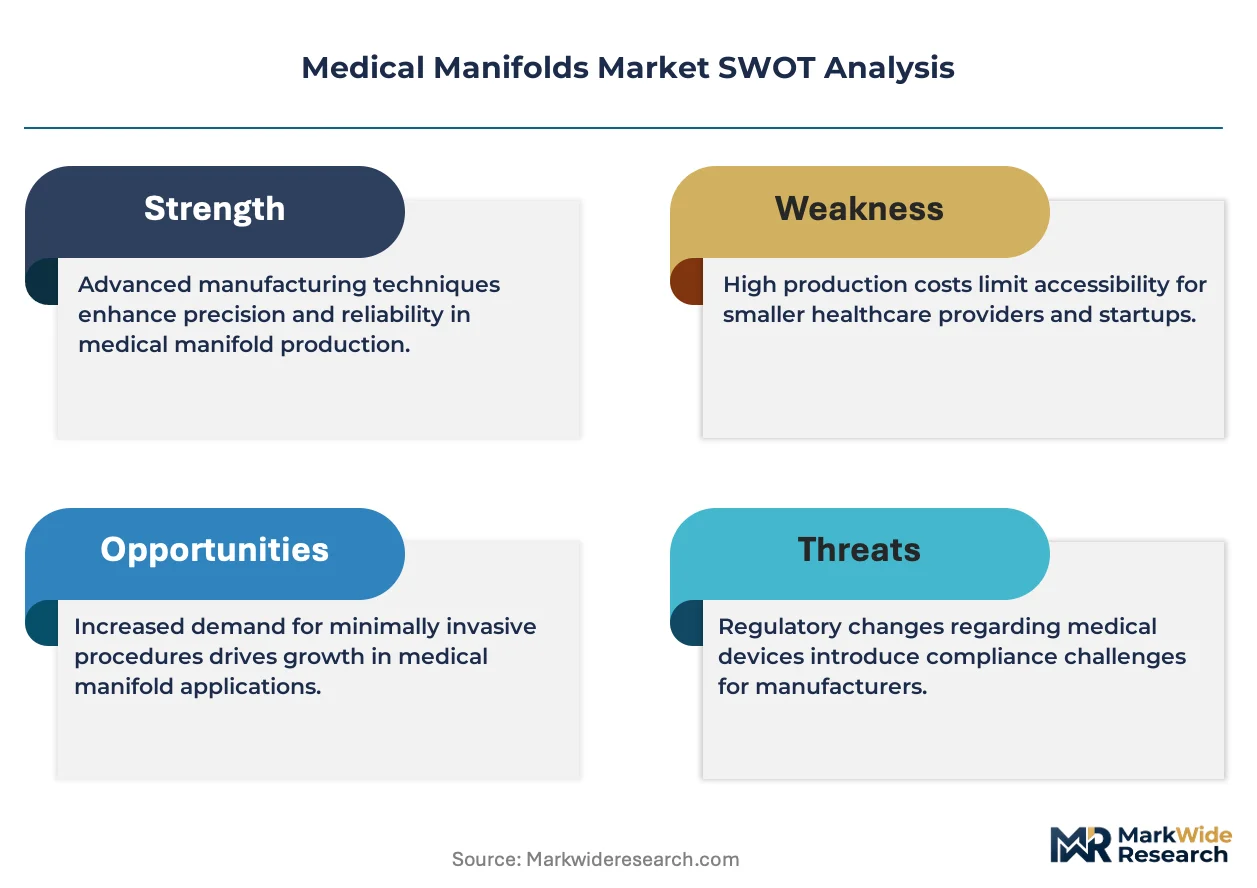
Medical manifolds are precision-machined or molded polymeric assemblies that channel, divert, or mix fluids and gases in critical care circuits, typically incorporating multiple Luer-lock ports, check valves, and pressure-rated seals to maintain sterile isolation between patient and machine. Their primary purpose is to consolidate multiple fluid lines into controlled, leak-proof pathways for anesthesia delivery, dialysis, and cardiac bypass procedures. Single-use manifolds command the largest revenue pool given infection control mandates, while 3D-printed customizable variants represent the fastest-growing technology segment as point-of-care manufacturing reduces sterilization logistics. Automated manifold systems with embedded flow sensors carry premium positioning in cardiac surgery applications where real-time pressure monitoring reduces perfusionist workload.
The FDA enforces 510(k) premarket notification for Class II fluid management devices, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for manifold systems sold under CE marking. ISO 13485 quality management and ISO 80369 small-bore connector standards shape design verification protocols, with non-compliance blocking market access in both jurisdictions. Stakeholders must monitor evolving biocompatibility testing requirements for novel polymer blends as regulators tighten extractables and leachables thresholds for extended patient contact devices.
Market Dynamics
Hospital procurement teams are consolidating fluid management vendors to reduce qualification overhead, compressing the supplier base around manufacturers with captive polymer molding and in-house sterilization validation.
Growth Catalysts
- Ambulatory surgical center expansion:United States outpatient catheterization labs are adding procedural capacity, driving manifold consumption for diagnostic and interventional cardiology workflows.
- FDA 510(k) pathway evolution:Streamlined premarket notification for Class II fluid management devices accelerates product clearance timelines for sterilization-validated single-use designs.
- Polymer biocompatibility advances:Medical-grade thermoplastic elastomers with enhanced leachables profiles enable extended patient contact applications in cardiac bypass circuits.
Market Restraints
- Specialty resin supply concentration:Medical-grade polycarbonate and cyclic olefin polymer supply chains concentrate among Asian petrochemical producers, exposing molders to feedstock allocation risk.
- EU MDR clinical evaluation burden:The European Medical Device Regulation mandates costly post-market surveillance systems for CE-marked manifolds, elevating compliance costs for mid-tier manufacturers.
- Reusable manifold substitution:European hospital groups with validated central sterilization departments retain preference for steam-sterilizable aluminum manifolds in high-volume anesthesia departments.
Strategic Opportunities
- Point-of-care 3D printing:Hospital-based additive manufacturing cells enable same-day production of patient-specific manifold geometries, eliminating sterilization logistics for complex cardiac procedures.
- India surgical infrastructure buildout:Government hospital modernization programs under the Ayushman Bharat scheme create first-time demand for integrated anesthesia delivery systems in tier-2 cities.
- Embedded sensor convergence:Microfluidic pressure transducers and flow sensors are integrating into manifold bodies, creating premium positioning in perfusion monitoring applications.
Industry Challenges
- ISO 80369 connector transition:Small-bore connector standardization requires complete product line redesigns, forcing molders to retool Luer-lock interfaces across anesthesia and dialysis portfolios.
- Polymer validation timeline compression:Extractables and leachables testing protocols for novel polymer blends now extend 18-24 months, delaying product launches despite completed mechanical design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Manifolds Market |
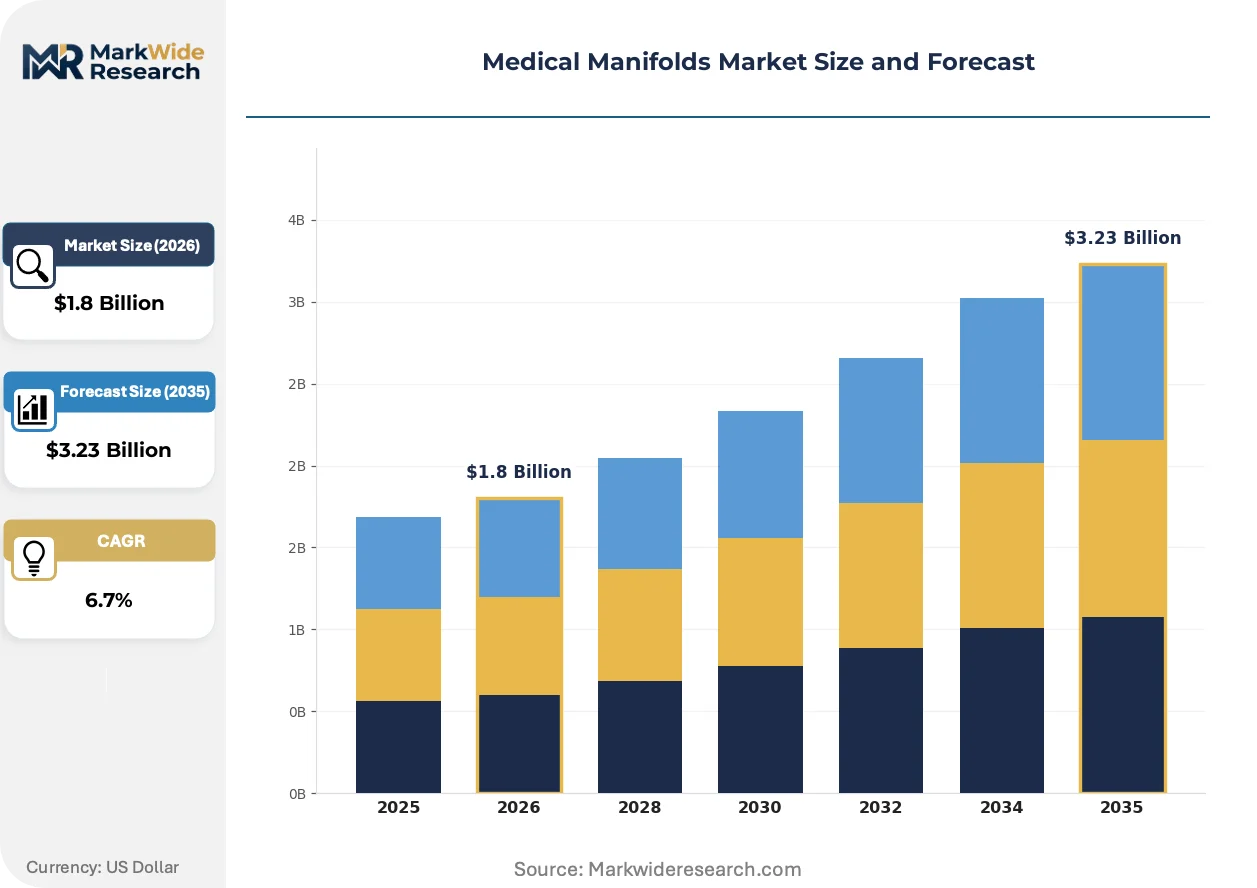
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Reusable, Customizable, Automated Application: Anesthesia, Ventilation, Cardiac Surgery, Dialysis End User: Hospitals, Clinics, Home Care, Surgical Centers Technology: 3D Printed, Molding, Machining, Composite |
| Companies Covered | Merit Medical Systems, Smiths Medical, B. Braun Melsungen AG, Medtronic, Teleflex Incorporated, Boston Scientific Corporation, Cardinal Health, Cook Medical, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Manifolds Market Strategic Shifts
Fluid management hardware is converging with digital monitoring layers, transforming passive manifolds into sensor-embedded platforms that feed real-time data into surgical workflow systems.
Automated manifold systems with embedded flow sensors are integrating pressure monitoring directly into cardiac bypass circuits, enabling perfusionists to track volumetric delivery without external transducer sets. Academic medical centers in Germany and the United States are piloting these platforms in high-complexity procedures. The technology is integrating hardware and software layers that previously operated as separate capital purchases.
The EU Medical Device Regulation is tightening clinical evidence requirements for Class IIa fluid management devices, forcing manufacturers to compile post-market surveillance data from legacy product generations. Notified bodies in Germany and the Netherlands are applying heightened scrutiny to biocompatibility documentation for extended patient contact applications. Manifold suppliers are responding by building dedicated regulatory affairs teams in Brussels to manage Technical File maintenance.
Hospital supply chain directors are consolidating vendor panels around full-line fluid management providers capable of delivering integrated manifold sets with matched connector standards. Group purchasing organizations in the United States are awarding sole-source contracts covering anesthesia, dialysis, and interventional cardiology manifold requirements. This concentration is most visible in the southeastern United States, where health system mergers have collapsed supplier rosters from twelve to three approved vendors.
Medical Manifolds Market Segmentation
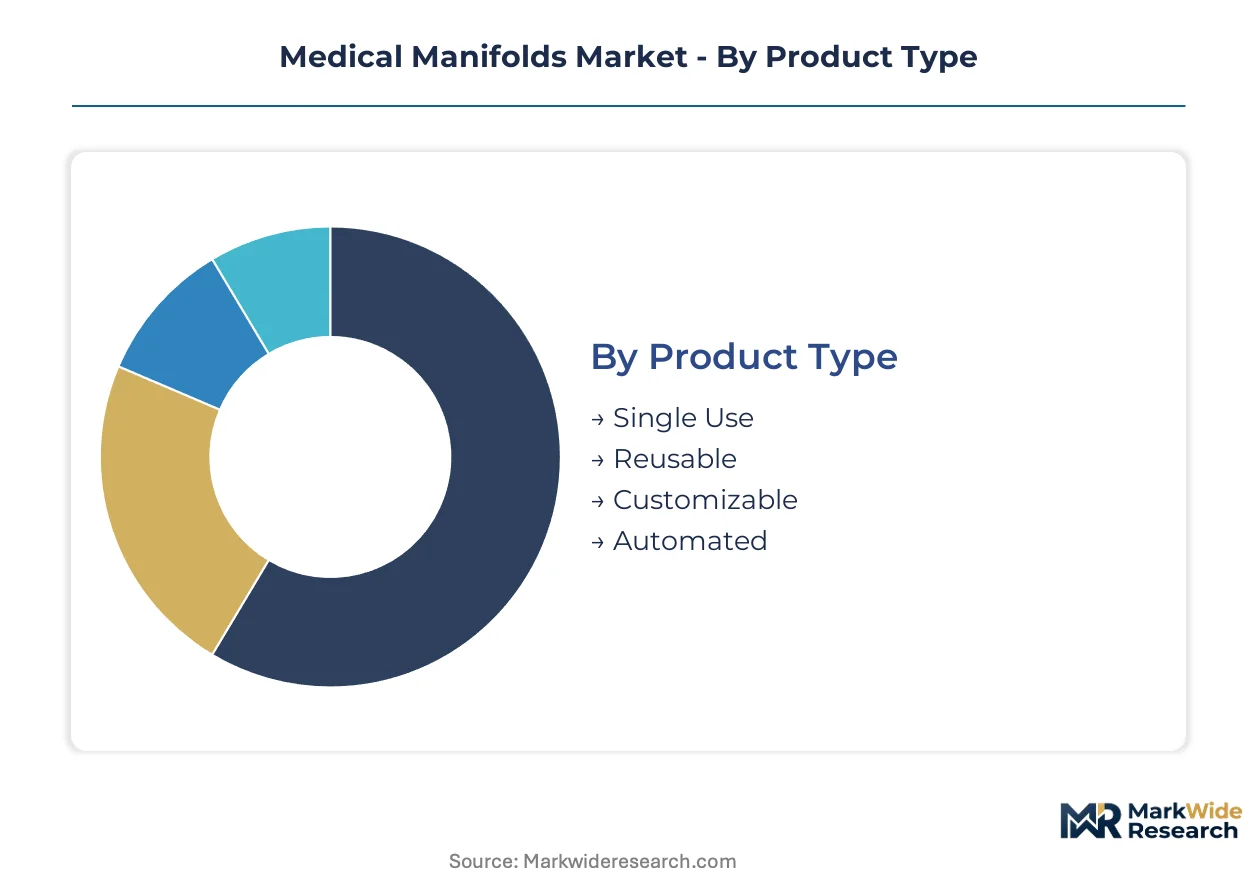
Medical manifold segmentation tracks procurement patterns across infection control mandates, procedural complexity tiers, and sterilization infrastructure maturity. Hospital capital planning cycles and regulatory clearance pathways determine upgrade velocity for each category.
Product Type:
Replacement cycles accelerate where sterilization validation burdens outweigh per-unit economics, tilting procurement toward disposable formats.
- Single Use:Polypropylene and polycarbonate assemblies with bonded Luer-lock interfaces eliminate cross-contamination risk in interventional suites. United States ambulatory surgical centers are standardizing on these formats to bypass central sterilization bottlenecks.
- Reusable:Anodized aluminum manifolds with steam-sterilizable seals anchor anesthesia departments in German and French hospital networks with validated central sterile processing departments. These platforms carry higher upfront capital costs but reduce per-procedure material spend in high-volume settings.
- Customizable:Patient-specific geometries produced via point-of-care additive manufacturing address complex cardiac bypass configurations.
- Automated:Sensor-embedded platforms with integrated pressure transducers for real-time perfusion monitoring.
Single Use sits at the top of the volume ranking, with Automated climbing the fastest.
Application:
Procedure reimbursement rates and clinical outcome liability shape manifold specification intensity across surgical disciplines.
- Anesthesia:Gas diversion circuits with multiple check valves and pressure-rated seals maintain precise volatile anesthetic delivery. North American acute care hospitals prioritize integrated manifold sets that consolidate gas scavenging and breathing circuit functions.
- Cardiac Surgery:Multi-port perfusion manifolds with pressure-monitoring capabilities enable volumetric control during cardiopulmonary bypass. German academic medical centers are piloting sensor-embedded variants that feed real-time data into surgical workflow systems.
- Ventilation:Oxygen blending and humidification circuits for mechanical respiratory support.
- Dialysis:Blood and dialysate channeling assemblies for extracorporeal renal replacement.
Anesthesia commands the largest installed base, while Cardiac Surgery shows the steepest expansion trajectory.
End User:
Capital availability and sterilization infrastructure determine manifold format selection across care delivery settings.
- Hospitals:Comprehensive fluid management platforms spanning anesthesia, dialysis, and cardiac surgery with dedicated biomedical engineering support. United States health system mergers are consolidating supplier rosters around full-line vendors capable of serving integrated delivery networks.
- Surgical Centers:Procedure-specific disposable manifolds for outpatient catheterization and endoscopy. Southeastern United States ASC expansion is driving consumption of single-use interventional cardiology sets.
- Clinics:Limited-procedure configurations for diagnostic and minor interventional workflows.
- Home Care:Simplified disposable formats for peritoneal dialysis and respiratory therapy.
Hospitals retain dominant procurement volume, with Surgical Centers expanding most quickly.
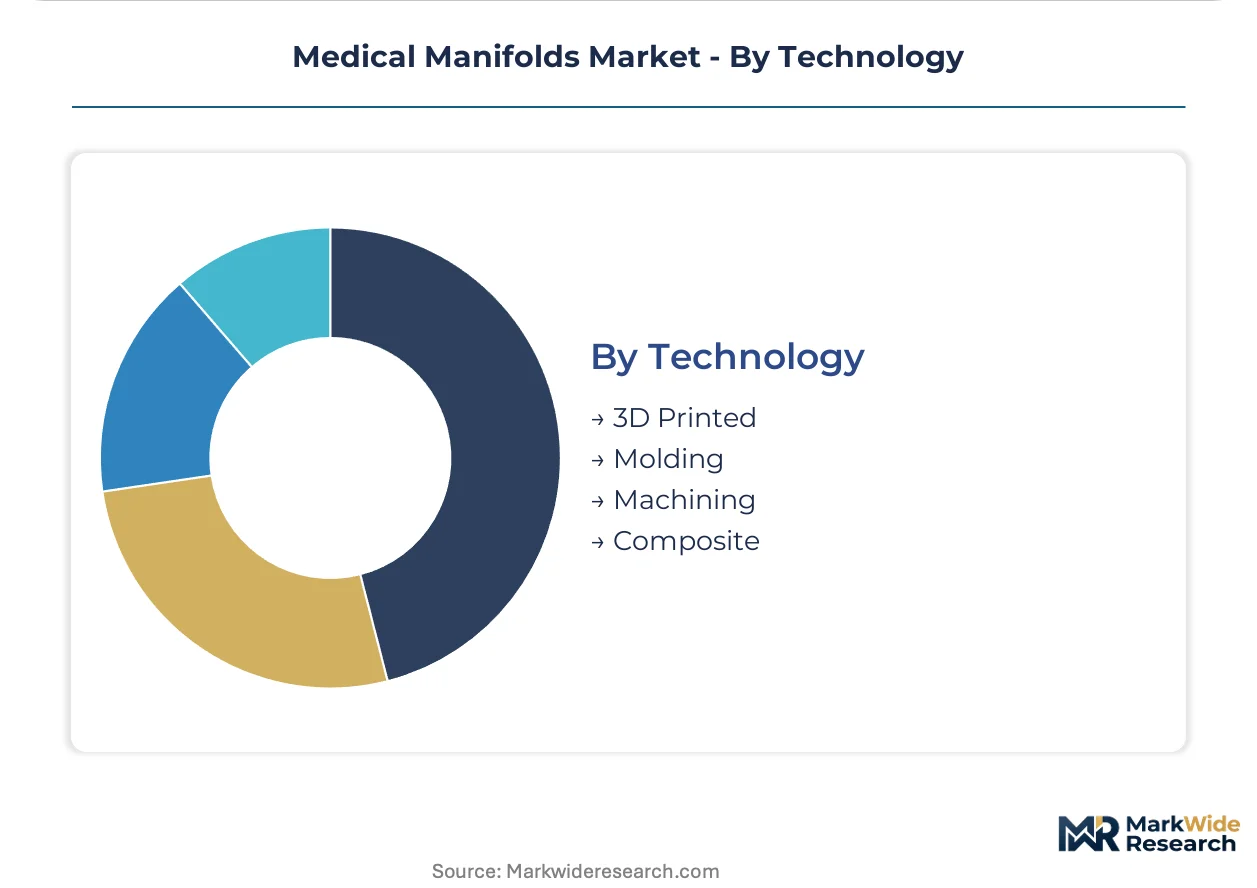
Technology:
Manufacturing process selection balances geometric complexity, material performance, and regulatory validation timelines.
- 3D Printed:Laser sintering and material extrusion of medical-grade photopolymers enable patient-specific geometries without hard tooling investment. United States academic medical centers are establishing hospital-based additive manufacturing cells for complex cardiac procedure support.
- Molding:Injection molding of medical-grade polycarbonate and cyclic olefin polymer delivers high-volume production economics for standardized anesthesia and dialysis configurations. Asian petrochemical supply concentration creates feedstock allocation risk for molders.
- Machining:CNC manufacturing of aluminum and stainless steel for reusable platforms with tight dimensional tolerances.
- Composite:Hybrid polymer-metal assemblies combining molding efficiency with structural reinforcement.
Molding leads production volume, with 3D Printed gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ambulatory surgical centers consume more single-use manifolds per capita than German hospital networks deploy reusable platforms, reflecting divergent sterilization infrastructure investment cycles across Atlantic markets.
United States
Southeastern health system mergers collapsed supplier rosters from twelve to three approved vendors, concentrating procurement around full-line fluid management providers. FDA 510(k) pathway streamlining accelerates clearance timelines for sterilization-validated single-use designs. Dallas and Houston catheterization labs drive consumption of disposable interventional cardiology sets.
Germany
Academic medical centers in Munich and Berlin pilot sensor-embedded perfusion platforms that integrate pressure monitoring into cardiac bypass circuits. EU MDR clinical evaluation mandates elevate compliance costs for mid-tier manufacturers seeking CE marking renewal. The Baden-Württemberg medical technology cluster anchors reusable manifold sterilization protocol development.
India
Government hospital modernization under Ayushman Bharat creates first-time demand for integrated anesthesia delivery systems in tier-2 cities. CDSCO medical device registration requirements tighten quality management system documentation for imported manifold assemblies. The Maharashtra pharmaceutical manufacturing corridor attracts molders establishing regional sterilization validation capabilities.
China
Domestic catheter lab expansion in provincial capitals drives consumption of precision-molded polycarbonate manifolds for diagnostic cardiology workflows. NMPA Class II medical device registration mandates biocompatibility testing protocols aligned with ISO 10993 standards. The Yangtze River Delta concentration of medical-grade polymer compounders supplies molders serving domestic and export markets.
Japan
Metropolitan Tokyo hospitals prioritize automated manifold systems with embedded flow sensors for perfusion monitoring in high-complexity cardiac procedures. PMDA quality management system inspections enforce ISO 13485 compliance for foreign manufacturers seeking market authorization. The Osaka-Kobe medical device manufacturing cluster specializes in miniaturized Luer-lock interfaces for dialysis applications.
Medical Manifolds Market Competitive Environment
United States producers anchor the premium disposable tier; German specialists hold the reusable platform segment through validated sterilization protocols. Hospital procurement consolidation around full-line vendors compresses the mid-tier supplier base, eliminating single-product competitors from group purchasing organization panels. Three archetypes dominate: vertically integrated polymer molders with captive sterilization, precision machining houses serving reusable anesthesia platforms, and point-of-care additive manufacturing cells. Competitive positioning hardens through M&A capture of regulatory clearance portfolios and strategic partnerships with academic medical centers for clinical validation.
Within the integrated disposable tier, Merit Medical Systems and Smiths Medical occupy positions shaped by catheter lab specialization and anesthesia manifold dominance respectively. B. Braun Melsungen AG anchors the reusable platform archetype through European hospital contracts with validated central sterilization departments. These three entities exemplify how geographic manufacturing footprint and regulatory affairs infrastructure determine vendor consolidation outcomes.
| Leading Market Players |
|---|
| Merit Medical Systems |
| Smiths Medical |
| B. Braun Melsungen AG |
| Medtronic |
| Teleflex Incorporated |
| Boston Scientific Corporation |
| Cardinal Health |
| Cook Medical |
| Getinge AB |
| Others |
Value Chain & Pricing Dynamics
Group purchasing organization consolidation in the southeastern United States has collapsed supplier rosters from twelve to three approved vendors, concentrating procurement leverage around full-line fluid management providers and compressing margins through sole-source contract structures.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for medical-grade polycarbonate manifolds, intensifying competition among Asian molders serving export markets. Pricing stratifies across FDA-validated premium tiers, ISO 13485-certified standard tiers, and economy tiers for non-regulated markets, with differentiation driven by sterilization validation depth and biocompatibility documentation completeness. Cost compression in the economy tier is intensifying because Indian and Southeast Asian molders are qualifying for CDSCO and NMPA registrations. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure budget constraints, while German academic medical centers prioritize premium sensor-embedded platforms regardless of unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States health system procurement committees are forcing molders to qualify secondary polymer compounders beyond their primary Asian feedstock suppliers. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies on medical-grade polycarbonate, cyclic olefin polymer, and thermoplastic elastomer resin streams. Single-source vulnerability persists in laser-sintering photopolymer feedstocks for point-of-care 3D printing applications. Distribution runs through group purchasing organization contracts to hospital systems, with direct-to-surgical-center channels expanding for single-use interventional cardiology sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR clinical evaluation mandates and FDA 510(k) pathway evolution are accelerating compliance investment requirements and consolidating vendor viability around cleared regulatory portfolios.
For Market Incumbents: Acquire sterilization validation assets and regulatory clearance portfolios to defend against emerging point-of-care additive manufacturing entrants and reusable platform specialists. Consolidate backward integration into medical-grade polymer compounding to secure feedstock allocation priority amid Asian supply concentration. Prioritize CE marking renewal investments to maintain European hospital contract access under heightened notified body scrutiny. For New Entrants and Emerging Players: Sensor-embedded automated manifolds with integrated pressure transducers offer the most penetrable white-space target, as academic medical centers in Germany and the United States pilot real-time perfusion monitoring platforms. Target ambulatory surgical center expansion in the southeastern United States with disposable interventional cardiology sets that bypass central sterilization infrastructure. Pursue hospital-based additive manufacturing cell partnerships as a go-to-market angle for patient-specific cardiac bypass configurations. For Investors and Strategic Acquirers: Vertically integrated medical device conglomerates with captive polymer molding and in-house sterilization validation are the most active acquirers in this space, seeking to compress supplier rosters through full-line capability consolidation. The viable acquisition window spans the medium-term horizon where regulatory compliance costs eliminate mid-tier competitors lacking dedicated Brussels-based regulatory affairs teams. Target molders with validated ISO 80369 small-bore connector transitions and completed extractables-leachables testing protocols. Watch FDA 510(k) clearance timeline compression as the signal indicating accelerated product launch velocity and vendor consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance secures German and French hospital network contracts under notified body scrutiny. |
| Hospital System Partnership | United States GPO sole-source awards consolidate procurement around full-line fluid management vendors. |
| Backward Integration into Polymer Compounding | Captive medical-grade resin supply mitigates Asian petrochemical allocation risk for molders. |
| Software Companion Development | Embedded flow sensor data integration into surgical workflow systems creates premium positioning. |
| Reimbursement Strategy | CMS outpatient procedure coding alignment accelerates ambulatory surgical center manifold adoption. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EU MDR Technical File databases, and hospital procurement records; plus trade data from medical-grade polymer customs classifications — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory parameters.
Cross-referencing supply-side capacity disclosures from polymer compounders with demand-side procedure volume projections from catheterization lab expansion databases anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application specialty, end-user setting, and manufacturing technology, with CAGRs derived from weighted average procedure growth rates and per-procedure manifold consumption intensities. Forecast inputs incorporated ISO 80369 connector transition timelines and sterilization validation protocol completion schedules.
The model holds under stable regulatory clearance timelines and continued hospital procurement consolidation; deviation in FDA 510(k) review duration or EU MDR notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Creatinine Meter Market