
 Robotic Aseptic Syringe Filler Capper Market | 2026-2036
Robotic Aseptic Syringe Filler Capper Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Aseptic Syringe Filler Capper Market Analytics
ISO 5 cleanroom specification upgrades are redrawing procurement criteria across the robotic aseptic syringe filler capper landscape. Syntegon Technology GmbH leverages its Stuttgart engineering base to dominate high-speed vaccine filling lines for European pharmaceutical manufacturers. Marchesini Group S.p.A. anchors Italian packaging automation heritage while extending robotic isolator integration capabilities. Vanrx Pharmasystems Inc specializes in gloveless robotic isolator technology that eliminates human intervention during critical aseptic operations.
Robotic aseptic syringe filler capper equipment combines precision servo-driven robotics with restricted access barrier systems to deposit sterile drug product into pre-sterilized syringes under ISO 5 unidirectional airflow conditions, achieving fill accuracy within ±1% for high-value biologics. Automatic systems lead installed capacity due to throughput requirements in commercial vaccine manufacturing, while hybrid configurations represent the fastest-growing segment as facilities retrofit existing lines with collaborative robotic modules. Servo-driven technology commands premium positioning owing to repeatable motion control and reduced particle generation versus legacy pneumatic alternatives.
FDA sterility guidance and EU GMP Annex 1 revisions mandate continuous viable and non-viable environmental monitoring integrated directly into filling isolators, reshaping equipment specification sheets and validation protocols. The European Medicines Agency enforces stricter barrier separation standards that disqualify semi-automatic equipment from new biologics license applications. Stakeholders must weigh total cost of ownership against regulatory compliance timelines when selecting between greenfield robotic installations and phased hybrid retrofits.
Market Dynamics
ISO 5 cleanroom specification upgrades are redrawing procurement criteria across the robotic aseptic syringe filler capper landscape, forcing manufacturers to choose between full robotic isolator replacements and modular retrofits before compliance deadlines.
Growth Catalysts
- EMA barrier separation standards:The European Medicines Agency enforces stricter isolator requirements that disqualify semi-automatic equipment from new biologics license applications, accelerating capital deployment toward gloveless robotic systems.
- mRNA vaccine manufacturing scale-up:Biopharmaceutical producers are expanding aseptic filling capacity to meet sustained demand for nucleic acid therapeutics and personalized cancer vaccines.
- Servo-driven motion control:Precision electromechanical actuation reduces particle generation versus pneumatic alternatives, aligning with FDA sterility guidance for critical aseptic operations.
Market Restraints
- Stainless steel and high-grade alloy input costs:Equipment fabricators face volatile pricing for pharmaceutical-grade 316L stainless steel and specialized isolator glazing materials.
- Specialized machine builder concentration:Engineering expertise clusters around Stuttgart and Frankfurt in Germany, creating supply bottlenecks for complex isolator integration projects.
- Validation timeline compression:EU GMP Annex 1 revision deadlines compress installation-to-qualification windows, extending project risk exposure.
Strategic Opportunities
- Hybrid retrofit configurations:Collaborative robotic modules enable phased automation of legacy filling lines without complete greenfield replacement, preserving capital for mid-tier manufacturers.
- Continuous environmental monitoring integration:Viable and non-viable particle detection systems embedded directly into isolator architectures create aftermarket service revenue streams.
- India biologics manufacturing expansion:CDSCO regulatory alignment with international standards positions Indian pharmaceutical producers for robotic aseptic equipment adoption.
Industry Challenges
- Mechatronics and isolator engineering talent scarcity:The intersection of precision robotics, pharmaceutical process engineering, and contamination control expertise limits qualified workforce availability.
- Legacy line integration complexity:Retrofitting existing filling infrastructure with restricted access barrier systems requires custom mechanical and control system interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Aseptic Syringe Filler Capper Market |
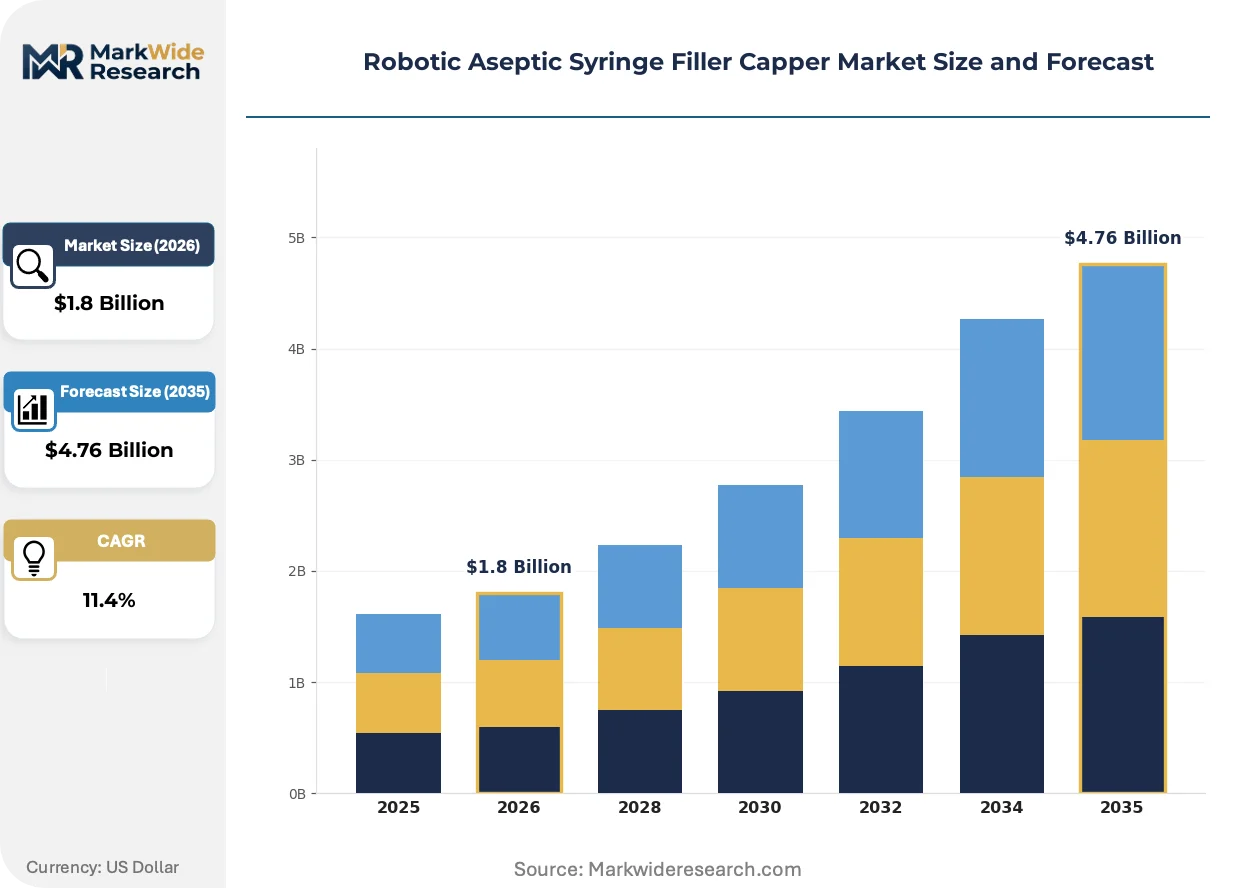
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid End User: Pharmaceutical Manufacturers, Biotech Companies, Contract Packagers, Hospitals Application: Vaccines, Injectable Drugs, Blood Derivatives, Hormones Technology: Pneumatic, Electric, Servo-driven, Hydraulic |
| Companies Covered | Syntegon Technology GmbH, Marchesini Group S.p.A., IMA Group, Vanrx Pharmasystems Inc, Bausch + Ströbel, ESS Technologies, Steriline Srl, AST Inc, Groninger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Aseptic Syringe Filler Capper Market Evolving Landscape
Gloveless robotic isolator architectures are displacing conventional barrier designs by eliminating human intervention during critical aseptic operations, reshaping equipment specification and facility layout planning.
Collaborative robotic modules with force-limited articulation and isolator-integrated safety systems are fragmenting the traditional dichotomy between fully automatic high-speed lines and manual semi-automatic operations. Mid-scale biopharmaceutical manufacturers in Germany and Switzerland are adopting these systems to bridge throughput gaps without complete line replacement. The technology is fragmenting vendor market positions by enabling niche specialists to compete against integrated line builders on retrofit projects.
FDA sterility guidance revisions mandate continuous viable and non-viable environmental monitoring integrated directly into filling isolators, reshaping equipment specification sheets and validation protocols. Pharmaceutical manufacturers must now specify isolator-embedded particle counters and active air sampling systems at the procurement stage. Commercial vaccine manufacturing facilities in the United States face the most acute compliance pressure due to prior inspection observations and consent decree histories.
Biopharmaceutical procurement teams are consolidating vendor relationships toward full-line integration partners capable of delivering isolator, robotics, and process analytics as unified systems. This pattern displaces the historical practice of sourcing filling, capping, and inspection modules from separate specialists. The shift is most pronounced among mRNA vaccine producers in Germany and contract manufacturing organizations serving European markets.
Robotic Aseptic Syringe Filler Capper Market Segmentation
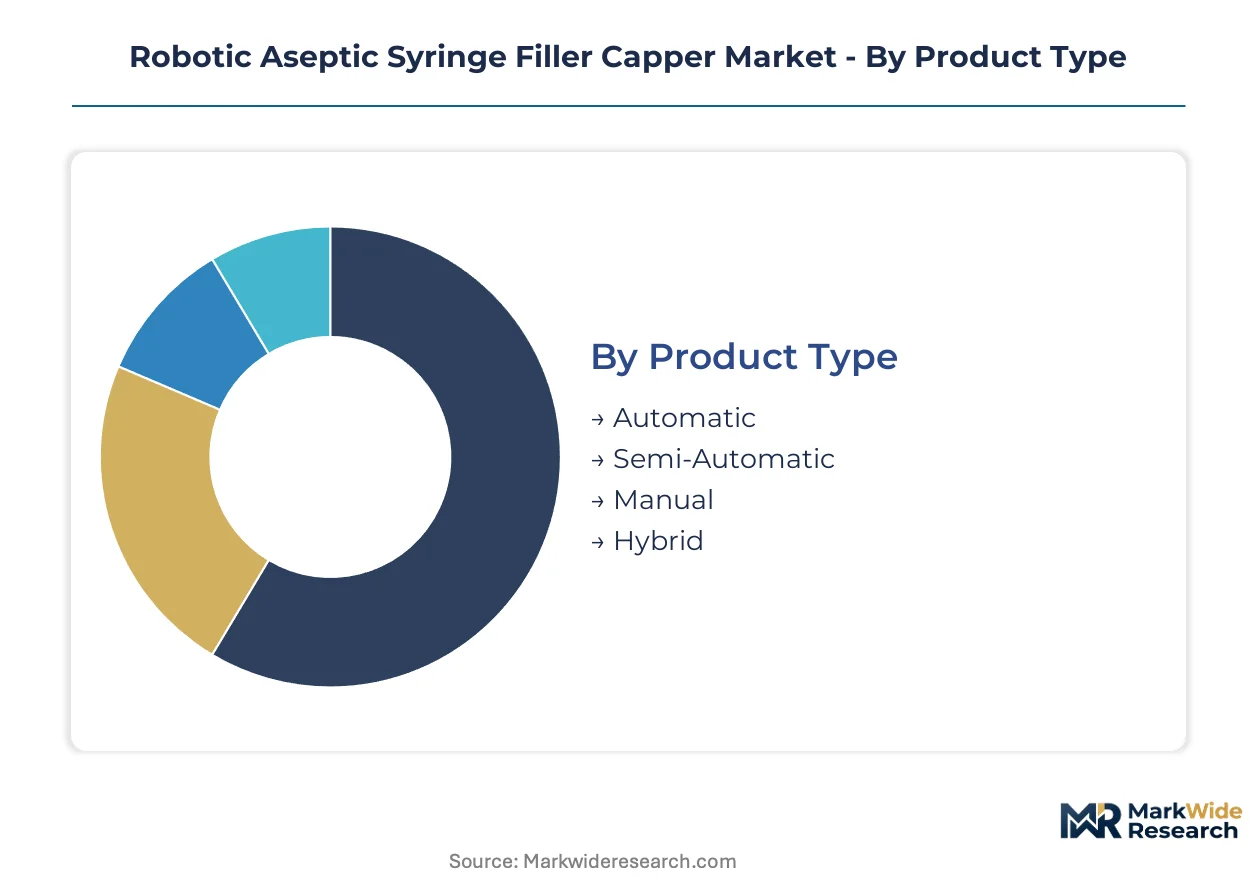
Segmentation in the robotic aseptic syringe filler capper market reveals distinct procurement channels and specification requirements across automation tiers. Pharmaceutical manufacturers navigate equipment selection through four intersecting dimensions: automation level, end-user operational model, therapeutic application, and motion control technology.
Product Type:
Channel distribution varies sharply by automation tier, with direct OEM sales dominating high-throughput automatic lines while hybrid systems flow through systems integrators serving retrofit markets.
- Automatic:Fully integrated servo-driven lines achieve fill accuracy within ±1% under ISO 5 unidirectional airflow, commanding direct procurement from Syntegon and Marchesini by commercial vaccine manufacturers in Germany and Switzerland facing EMA compliance deadlines.
- Hybrid:Collaborative robotic modules with force-limited articulation enable phased automation of legacy filling infrastructure without greenfield replacement, attracting mid-tier biopharmaceutical producers in India and contract manufacturing organizations seeking capital preservation.
- Semi-Automatic:Restricted access barrier systems with partial robotic integration serve niche biologics producers with lower throughput requirements.
- Manual:Conventional aseptic processing equipment persists only in research-scale operations and developing market hospital pharmacies.
By volume, Automatic leads installed capacity across commercial manufacturing. By growth pace, Hybrid is expanding most quickly as facilities retrofit ahead of regulatory deadlines.
End User:
Cost tier stratification separates capital-intensive greenfield investments from operational expenditure models favoring leased or contracted capacity.
- Pharmaceutical Manufacturers:Integrated multinationals in Germany and Switzerland deploy full robotic isolator lines with embedded environmental monitoring, absorbing upfront capital for long-term compliance positioning against FDA sterility guidance and EU GMP Annex 1 revisions.
- Contract Packagers:CDMOs serving European markets consolidate vendor relationships toward full-line integration partners capable of delivering isolator, robotics, and process analytics as unified systems, displacing modular sourcing strategies.
- Biotech Companies:Emerging nucleic acid therapeutic developers prioritize flexible hybrid configurations to accommodate pipeline volatility and personalized medicine scale requirements.
- Hospitals:Institutional pharmacies with compounding operations represent limited demand concentrated in automated vial-to-syringe transfer systems for patient-specific dosing.
Pharmaceutical Manufacturers command the largest equipment procurement budgets. Contract Packagers are gaining share fastest as outsourcing trends accelerate across mRNA vaccine and complex biologics production.
Application:
Application-driven specification divergence centers on fill volume precision, container closure integrity requirements, and batch size flexibility across therapeutic categories.
- Vaccines:High-speed rotary filling lines with 600+ units per minute throughput serve pandemic preparedness and seasonal influenza manufacturing, with German producers scaling capacity for mRNA and viral vector platforms.
- Injectable Drugs:Monoclonal antibody and protein therapeutic filling demands gloveless isolator architectures with continuous viable particle monitoring, driving specification upgrades across North American and European facilities.
- Blood Derivatives:Plasma-derived product lines require specialized handling protocols for temperature-sensitive biologics with extended fill cycles.
- Hormones:Potent compound containment drives demand for isolator-integrated containment strategies with occupational exposure band compliance.
Injectable Drugs generates the highest equipment revenue per installed line. Vaccines shows the steepest volume expansion trajectory driven by sustained mRNA manufacturing scale-up.
Technology:
Margin structure separates premium electromechanical positioning from legacy pneumatic alternatives facing particle generation constraints under revised FDA guidance.
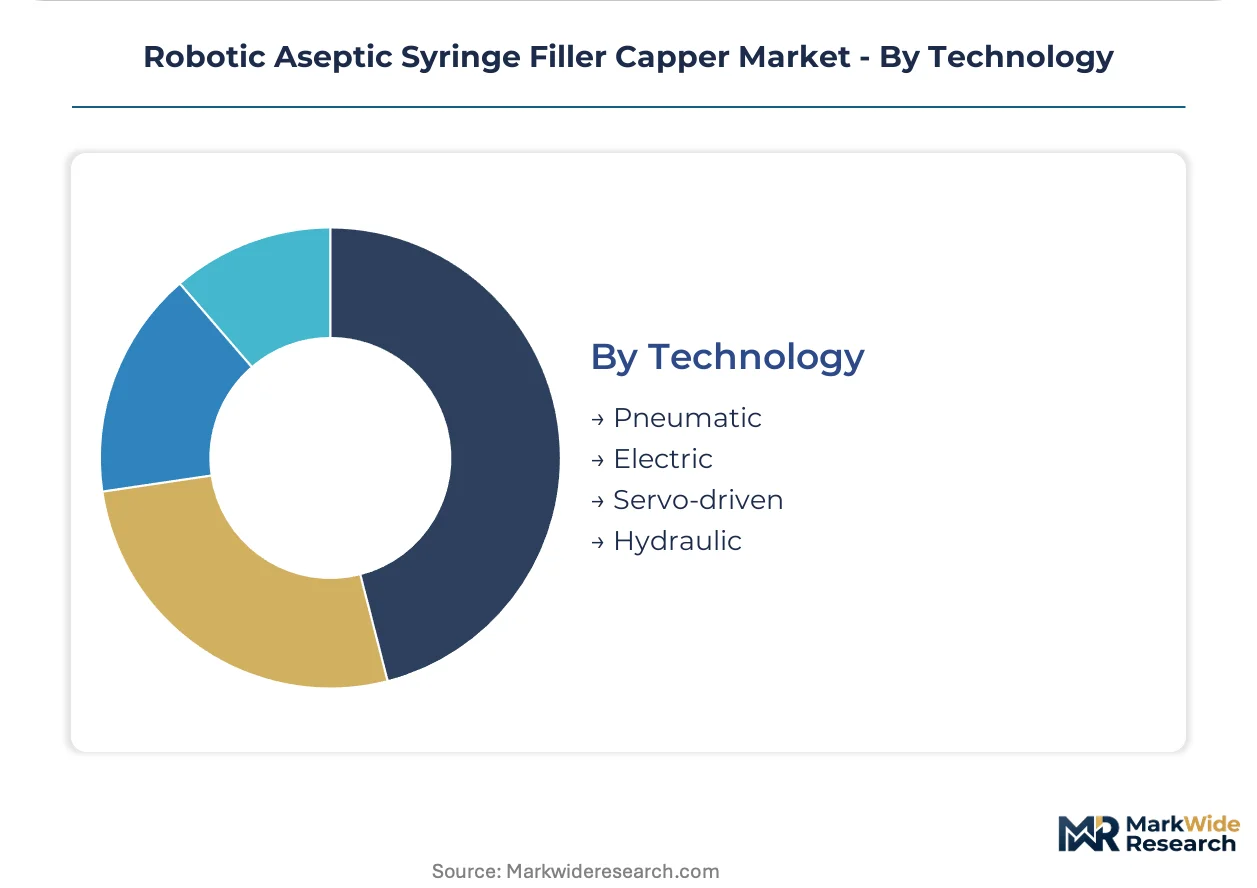
- Servo-driven:Precision electromechanical actuation with closed-loop motion control reduces particle generation versus pneumatic alternatives, aligning with sterility requirements for critical aseptic operations and commanding 40-60% price premiums over legacy systems.
- Electric:Stepper and brushless DC motor configurations serve mid-speed applications with moderate precision requirements, bridging cost and performance gaps in emerging market installations.
- Pneumatic:Compressed air actuation persists in legacy equipment facing replacement pressure from EU GMP Annex 1 barrier separation standards that disqualify semi-automatic configurations from new biologics license applications.
- Hydraulic:High-force fluid power systems remain confined to specialized capping torque applications requiring sustained pressure delivery.
Servo-driven technology captures the highest average selling prices per filling station. Electric systems are climbing fastest as Indian and Southeast Asian manufacturers enter compliance upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment engineering expertise clusters heavily in southwestern Germany, where Stuttgart and Frankfurt anchor specialized machine builder networks. This geographic concentration shapes procurement timelines and service accessibility for pharmaceutical manufacturers worldwide.
United States
Commercial vaccine producers face acute FDA sterility guidance compliance pressure following prior inspection observations and consent decree histories. The Agency mandates continuous viable and non-viable environmental monitoring integrated directly into filling isolators. Boston and Research Triangle Park host nucleic acid therapeutic developers scaling robotic capacity for personalized cancer vaccines.
Germany
Integrated multinationals deploy full robotic isolator lines with embedded process analytics to secure long-term positioning against EU GMP Annex 1 revision deadlines. The European Medicines Agency enforces stricter barrier separation standards that disqualify semi-automatic equipment from new biologics license applications. Stuttgart-based engineering groups dominate high-speed vaccine filling specifications for European pharmaceutical manufacturers.
Switzerland
Mid-scale biopharmaceutical manufacturers adopt collaborative robotic modules to bridge throughput gaps without complete line replacement. Swissmedic maintains alignment with EMA barrier separation standards while permitting phased compliance approaches for legacy facility retrofits. Basel and Zurich clusters concentrate monoclonal antibody filling operations requiring gloveless isolator architectures.
India
CDSCO regulatory alignment with international standards positions domestic pharmaceutical producers for robotic aseptic equipment adoption. Contract manufacturing organizations seek capital-preserving hybrid configurations rather than greenfield robotic installations. Ahmedabad and Hyderabad manufacturing corridors attract mid-tier biologics producers entering compliance upgrade cycles.
China
NMPA standards convergence with PIC/S guidelines accelerates isolator technology procurement for domestic vaccine and injectable drug manufacturers. Yangtze River Delta pharmaceutical clusters invest in servo-driven motion control systems to reduce particle generation versus legacy pneumatic alternatives. Shanghai and Suzhou facilities concentrate biologics filling capacity serving both domestic and export markets.
Robotic Aseptic Syringe Filler Capper Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the robotic aseptic syringe filler capper landscape. The market structure separates into three tiers: integrated line builders delivering full isolator-robotics-analytics systems, specialized isolator technology developers, and regional fabricators serving retrofit markets. Dominant competitive moves include strategic partnerships for continuous environmental monitoring integration and geographic expansion through local service network establishment.
Among German engineering groups, Syntegon Technology GmbH and Bausch + Ströbel occupy positions within the integrated line builder tier, representing comprehensive system delivery capabilities. Marchesini Group S.p.A. exemplifies the European packaging automation heritage archetype, while Vanrx Pharmasystems Inc anchors the specialized isolator technology segment focused on gloveless robotic architectures.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| Marchesini Group S.p.A. |
| IMA Group |
| Vanrx Pharmasystems Inc |
| Bausch + Ströbel |
| ESS Technologies |
| Steriline Srl |
| AST Inc |
| Groninger |
| Others |
Value Network & Pricing Analysis
Servo-driven actuation displacing pneumatic systems redraws procurement economics and supplier geography simultaneously, compressing margins on legacy equipment while concentrating premium component sourcing around Stuttgart engineering clusters serving EMA-compliant facilities.
Pricing Analysis
EU GMP Annex 1 dictates the pricing tier structure across the robotic aseptic syringe filler capper landscape. Three-tier pricing stratifies across gloveless isolator systems, hybrid collaborative modules, and semi-automatic legacy configurations, with FDA certification tier and servo precision grade as primary differentiation drivers. Cost compression in pneumatic equipment intensifies as barrier separation standards disqualify older configurations from new biologics licenses. Mid-tier biopharmaceutical manufacturers in India exhibit highest price sensitivity, while integrated multinationals in Germany absorb premium positioning for compliance certainty.
Supply Chain Analysis
Strategic stockpiling of pharmaceutical-grade 316L stainless steel and specialized isolator glazing materials prevails over just-in-time approaches given volatile alloy pricing and EMA deadline compression. Component fabrication concentrates in Germany, Italy, and Switzerland, with precision servo motors and restricted access barrier systems drawing from specialized machine builder networks around Stuttgart and Frankfurt. Single-source vulnerability runs through isolator-integrated environmental monitoring subassemblies. Distribution feeds from direct OEM relationships for high-throughput automatic lines and systems integrator channels for hybrid retrofit configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
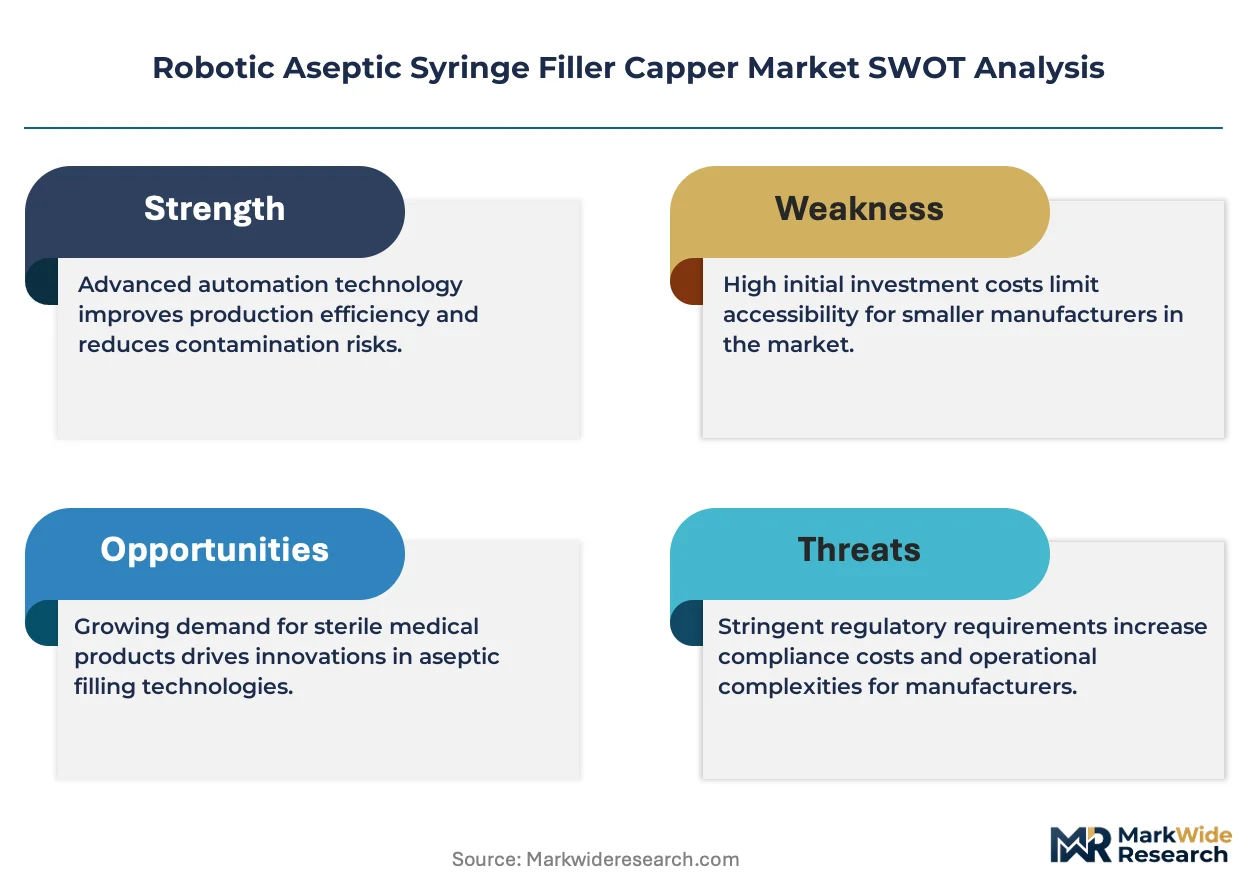
Robotic aseptic syringe filler capper demand is accelerating through a regulatory inflection as FDA sterility guidance and EU GMP Annex 1 revisions force wholesale equipment replacement cycles across North American and European pharmaceutical manufacturing.
For Market Incumbents: Fortify market position through captive supply of servo-driven motion control components and embedded environmental monitoring technologies, insulating against emerging isolator specialists while deepening technical service networks in Germany and Switzerland to compress installation-to-qualification timelines for EMA compliance deadlines. For New Entrants and Emerging Players: Lead with collaborative robotic module architectures targeting mid-tier Indian pharmaceutical manufacturers and European contract manufacturing organizations seeking capital-preserving hybrid retrofits, positioning through systems integrator partnerships rather than direct OEM competition against integrated line builders. For Investors and Strategic Acquirers: Capital is best deployed toward specialized isolator technology developers with gloveless robotic architectures and continuous environmental monitoring integration capabilities, as long-term viability across the projection horizon hinges on regulatory compliance technology depth rather than scale manufacturing; the signal to watch is CDSCO regulatory alignment progress accelerating Indian market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Gloveless Isolator Technology Development | Eliminates human intervention during critical aseptic operations, aligning with FDA sterility guidance. |
| Continuous Environmental Monitoring Integration | Embeds viable and non-viable particle detection directly into isolator architectures for EMA compliance. |
| Hybrid Retrofit Configuration Expansion | Enables phased automation of legacy filling lines without greenfield replacement for capital-constrained manufacturers. |
| Servo-Driven Motion Control Advancement | Reduces particle generation versus pneumatic alternatives, commanding premium positioning in high-value biologics filling. |
| Regional Service Network Establishment | Compresses installation-to-qualification timelines for EU GMP Annex 1 deadline compliance in Germany and Switzerland. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with pharmaceutical manufacturing executives, regulatory affairs specialists, cleanroom engineering consultants, and equipment procurement managers; and secondary validation through FDA 483 observation databases, EMA GMP inspection reports, pharmaceutical facility capital expenditure disclosures, and ISO 14644 cleanroom standard documentation. Bottom-up equipment shipment tallies by automation tier and geography were triangulated against top-down pharmaceutical manufacturing capacity expansion announcements.
Across the analysis window, the forecasting framework modeled segmentation dimensions including automation level, end-user operational model, therapeutic application, and motion control technology, with CAGRs derived from regression analysis of historical capital equipment procurement patterns against regulatory compliance deadline schedules. Industry-specific forecast inputs incorporated mRNA vaccine manufacturing scale-up trajectories and EU GMP Annex 1 revision implementation timelines.
Forecasts assume regulatory continuity in FDA sterility guidance and EMA barrier separation standards; material policy shifts would require re-modeling. Revision becomes warranted when CDSCO regulatory alignment progress or stainless steel alloy price volatility crosses thresholds that alter capital deployment patterns among mid-tier biopharmaceutical manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Holter ECG Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Global Veress Needle Market
Medical Devices
Global Neurovascular Guidewires Market