
 Thrombectomy System Market | 2026-2036
Thrombectomy System Market Size, Share, and Industry Trends Forecast 2026-2036
Thrombectomy System Market Analytics
Hospital procurement for thrombectomy systems is broadening from elite comprehensive stroke centers to mid-tier community hospitals seeking 24/7 mechanical thrombectomy capability. Medtronic leverages its neurovascular portfolio depth to sustain catheter-based technology leadership across multiple geographies. Stryker Corporation anchors its position through manufacturing scale in aspiration and stent retriever platforms. Penumbra, Inc. differentiates via specialized engineering in large-bore aspiration systems for acute ischemic stroke intervention.
A thrombectomy system comprises catheters, aspiration tubing, stent retrievers, and suction pumps engineered to extract occlusive blood clots from cerebral or peripheral vasculature, typically requiring 0.054-inch to 0.088-inch catheter lumen diameters and aspiration pressures exceeding 700 mmHg to achieve rapid revascularization. Mechanical devices occupy the dominant revenue position due to established reimbursement pathways and proven clinical outcomes in randomized trials, while aspiration devices represent the fastest-expanding category as physicians adopt direct aspiration first-pass techniques. Endovascular technology commands premium pricing relative to intravenous alternatives, reflecting the specialized training and capital equipment required for catheter-based intervention.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and commercial launch sequencing for device manufacturers seeking multi-regional market access. The FDA breakthrough devices program accelerates review for thrombectomy innovations demonstrating substantial improvement over standard of care, while EU MDR technical documentation requirements extend certification cycles for Class III implantable devices. Japan's PMDA consultative review process adds a third regulatory gate for companies targeting Asia-Pacific expansion. Stakeholders must monitor evolving CMS reimbursement decisions for mechanical thrombectomy in extended time-window stroke patients, as coverage determinations directly influence hospital capital allocation and device procurement volumes.
Market Dynamics
Mechanical thrombectomy device adoption is modularizing across hospital tiers as community hospitals build 24/7 stroke intervention capabilities, compressing the traditional concentration of procedures at academic medical centers and redistributing capital equipment demand toward mid-tier facilities.
Growth Catalysts
- Extended treatment window reimbursement:CMS coverage determinations for mechanical thrombectomy beyond six hours post-onset are expanding eligible patient populations and justifying capital investment at secondary stroke centers.
- FDA breakthrough device pathway:Expedited review timelines for thrombectomy innovations demonstrating substantial improvement over standard of care are compressing product development cycles and accelerating commercialization.
- Comprehensive stroke center network expansion:Germany, Japan, and the United States are certifying additional facilities, creating concentrated demand clusters for aspiration and stent retriever platforms.
Market Restraints
- Nitinol supply concentration:Stent retriever manufacturing depends on specialized nitinol wire from limited suppliers, creating input vulnerability for device producers.
- EU MDR technical documentation:Extended certification cycles for Class III implantable devices are delaying commercial launch sequencing and increasing regulatory compliance costs.
- Intravenous thrombolysis persistence:Tissue plasminogen activator remains first-line therapy at non-capable centers, limiting mechanical thrombectomy penetration in rural and under-resourced settings.
Strategic Opportunities
- Peripheral thrombectomy extension:Venous thromboembolism and deep vein thrombosis applications represent underpenetrated clinical indications with distinct reimbursement pathways.
- Japan PMDA consultative review:Structured pre-submission engagement is enabling faster Asia-Pacific market entry for companies with US or EU regulatory precedent.
- Artificial intelligence integration:Convergence of imaging analysis algorithms with catheter navigation systems is enabling real-time clot characterization and device selection optimization.
Industry Challenges
- Neurointerventionalist training pipelines:The specialized skill set required for endovascular stroke intervention creates workforce bottlenecks that constrain procedure volume expansion.
- Capital equipment amortization:Biplane angiography systems require substantial upfront investment that strains community hospital budgets and extends payback periods.
- Legacy device compatibility:Aspiration pump and catheter interoperability standards remain fragmented, complicating multi-vendor procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrombectomy System Market |
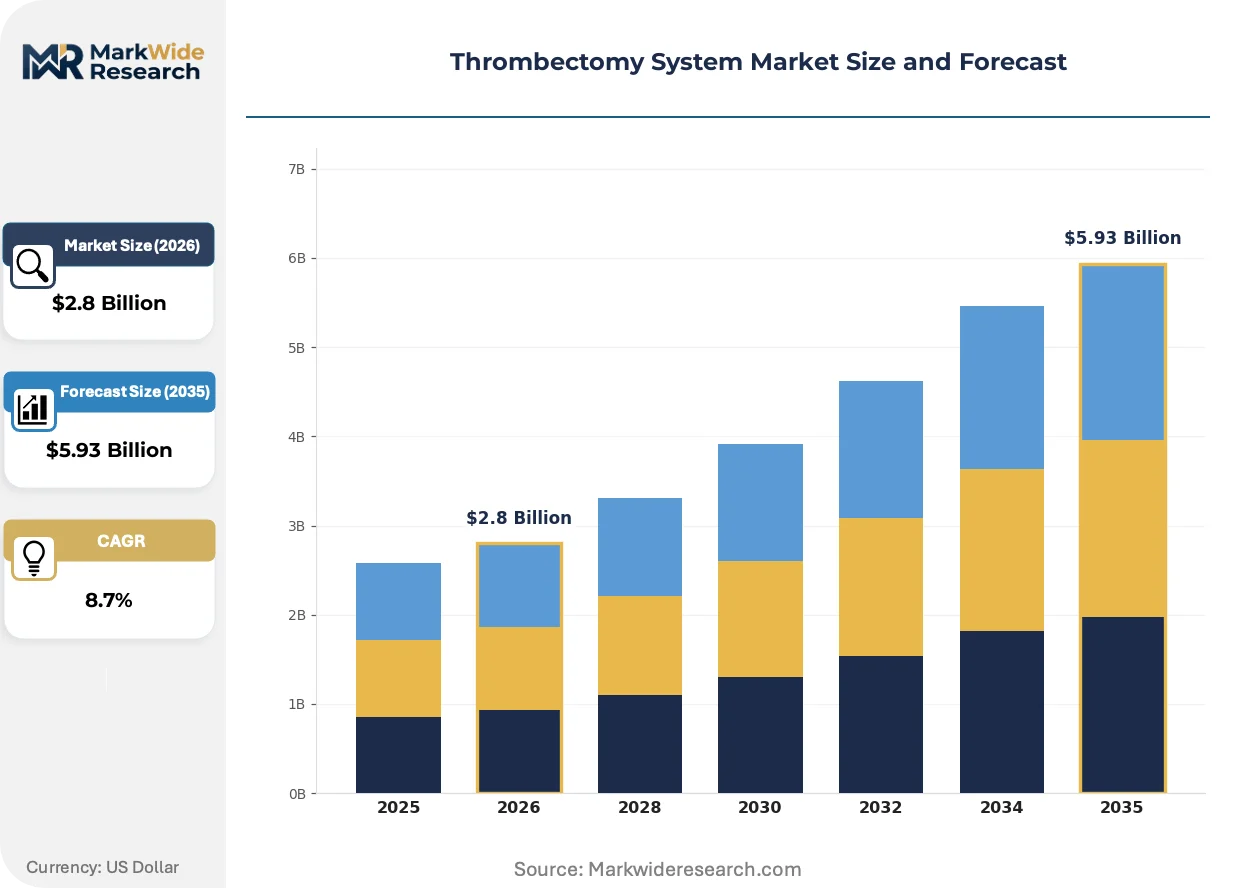
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Devices, Mechanical Devices, Aspiration Devices, Combination Devices Technology: Catheter-Based, Intravenous, Endovascular, Device-Assisted End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Application: Acute Ischemic Stroke, Peripheral Vascular Disease, Myocardial Infarction, Thromboembolic Disorders |
| Companies Covered | Penumbra, Inc., Medtronic, Stryker Corporation, Boston Scientific Corporation, Terumo Corporation, Johnson & Johnson, AngioDynamics, Koninklijke Philips N.V., BD Interventional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrombectomy System Market Evolving Landscape
Catheter engineering and procedural technique evolution are compressing revascularization times while regulatory frameworks and procurement models adapt to accommodate broader clinical adoption.
Large-bore aspiration catheter technology is modularizing. These 0.088-inch lumen devices enable direct aspiration first-pass techniques that reduce procedure steps and device exchanges. Community hospitals adopting this platform are consolidating vendor relationships around integrated aspiration pump and catheter systems. The technology is modularizing purchasing decisions by separating aspiration hardware from retriever accessories.
EU MDR conformity assessment requirements are extending certification timelines for Class III neurovascular devices. Technical documentation demands for clinical evidence and post-market surveillance are increasing regulatory investment thresholds. Manufacturers with existing CE-marked portfolios are prioritizing MDR transition over new product launches, affecting competitive launch sequencing in European markets.
Hospital purchasing committees are consolidating thrombectomy device procurement under value-analysis frameworks that evaluate total procedure cost rather than device unit price. Bundled payment models for stroke care are replacing fee-for-service reimbursement at integrated delivery networks. This behavioral shift is most visible in United States markets where CMS accountable care organization participation is highest.
Thrombectomy System Market Segmentation
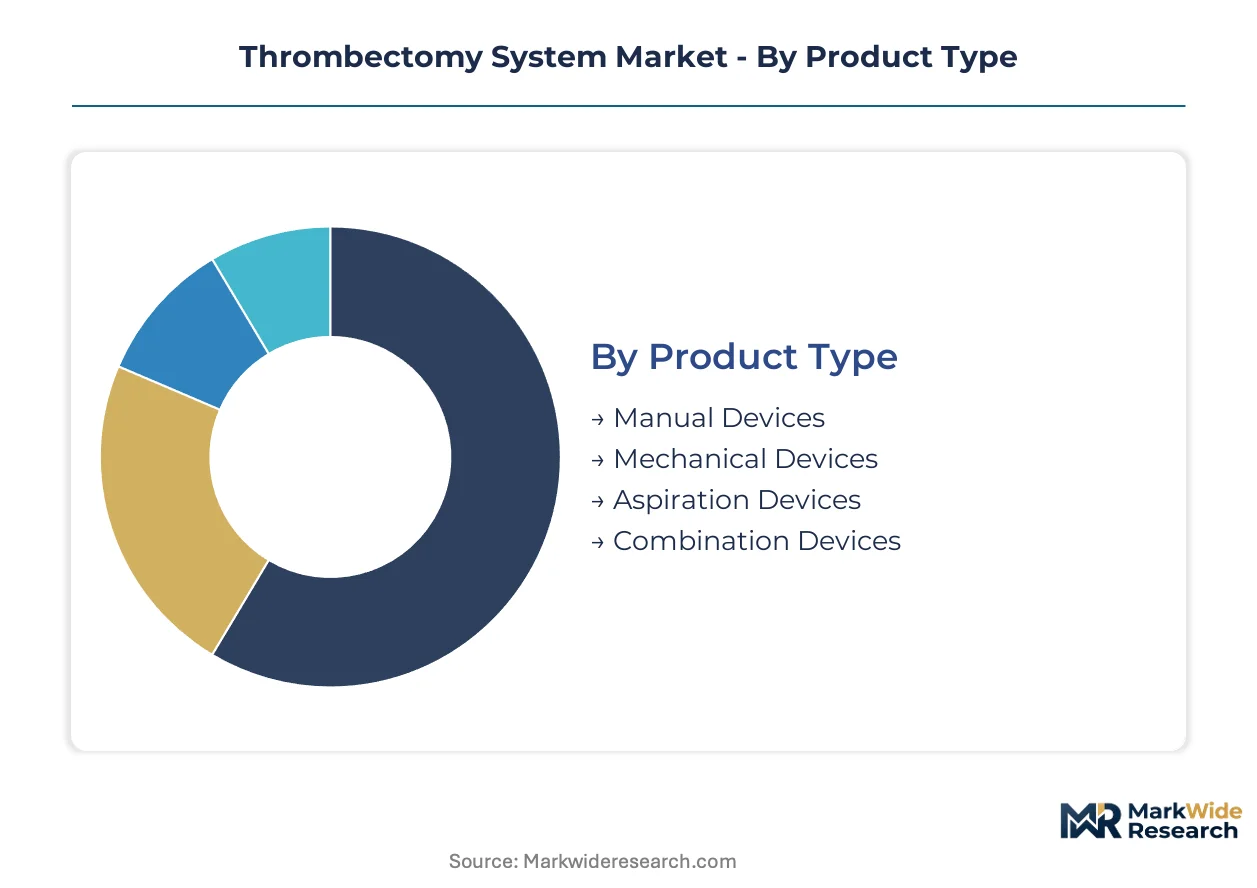
Thrombectomy system procurement varies sharply across clinical settings and procedural requirements. Device specifications, reimbursement pathways, and operator training levels create distinct demand profiles that manufacturers must address through targeted platform configurations.
Product Type:
Customization intensity spans from hand-operated manual instruments to fully integrated aspiration-retriever combinations, with standardization increasing as capital equipment requirements rise.
- Manual Devices:Hand-operated syringes and basic aspiration tools requiring minimal capital investment. Demand concentrates in resource-constrained hospitals in India and Brazil where biplane angiography infrastructure remains limited, constrained by operator-dependent consistency and longer procedure times.
- Mechanical Devices:Stent retrievers and clot retrieval systems deploying self-expanding nitinol frameworks. Academic medical centers in Germany and the United States drive procurement, supported by Level I stroke center certification requirements and established CPT reimbursement codes.
- Aspiration Devices:Large-bore catheter systems with dedicated suction pumps.
- Combination Devices:Integrated platforms merging aspiration with mechanical retrieval.
Most installed capacity flows through Mechanical Devices. Expansion is steepest in Aspiration Devices.
Technology:
Cost tier stratification separates premium catheter-based platforms from lower-intravenous alternatives, with reimbursement differentials widening the gap between endovascular and pharmaceutical approaches.
- Catheter-Based:Transfemoral or transradial access systems with variable stiffness guidewires and distal access catheters. Comprehensive stroke centers in Japan and the United States concentrate demand, driven by FDA breakthrough device designations and J-Stroke registry data requirements.
- Intravenous:Systemic thrombolytic delivery without mechanical intervention. Rural and community hospitals persist with this approach due to tPA protocol familiarity and absence of interventional neuroradiology staffing, though extended-window mechanical thrombectomy reimbursement is eroding share.
- Endovascular:Image-guided intra-arterial mechanical clot removal.
- Device-Assisted:Hybrid pharmaceutical-mechanical combination protocols.
Endovascular platforms command the highest average selling prices. Catheter-Based systems are gaining share fastest.
End User:
Customer type determines purchasing committee composition, with capital equipment committees at hospitals diverging sharply from value-analysis groups at outpatient facilities.
- Hospitals:Comprehensive and primary stroke centers with 24/7 intervention capabilities. The United States, Germany, and Japan dominate procurement volumes, supported by network certification programs and DRG-based reimbursement that rewards rapid revascularization.
- Specialty Clinics:Focused neurovascular and cardiovascular intervention centers.
- Ambulatory Surgical Centers:Limited penetration due to stroke emergency requirements and need for intensive care unit backup.
- Research Institutions:Preclinical and clinical trial sites evaluating next-generation device platforms.
Hospital procurement accounts for the dominant revenue share. Specialty Clinics represent the steepest expansion trajectory.
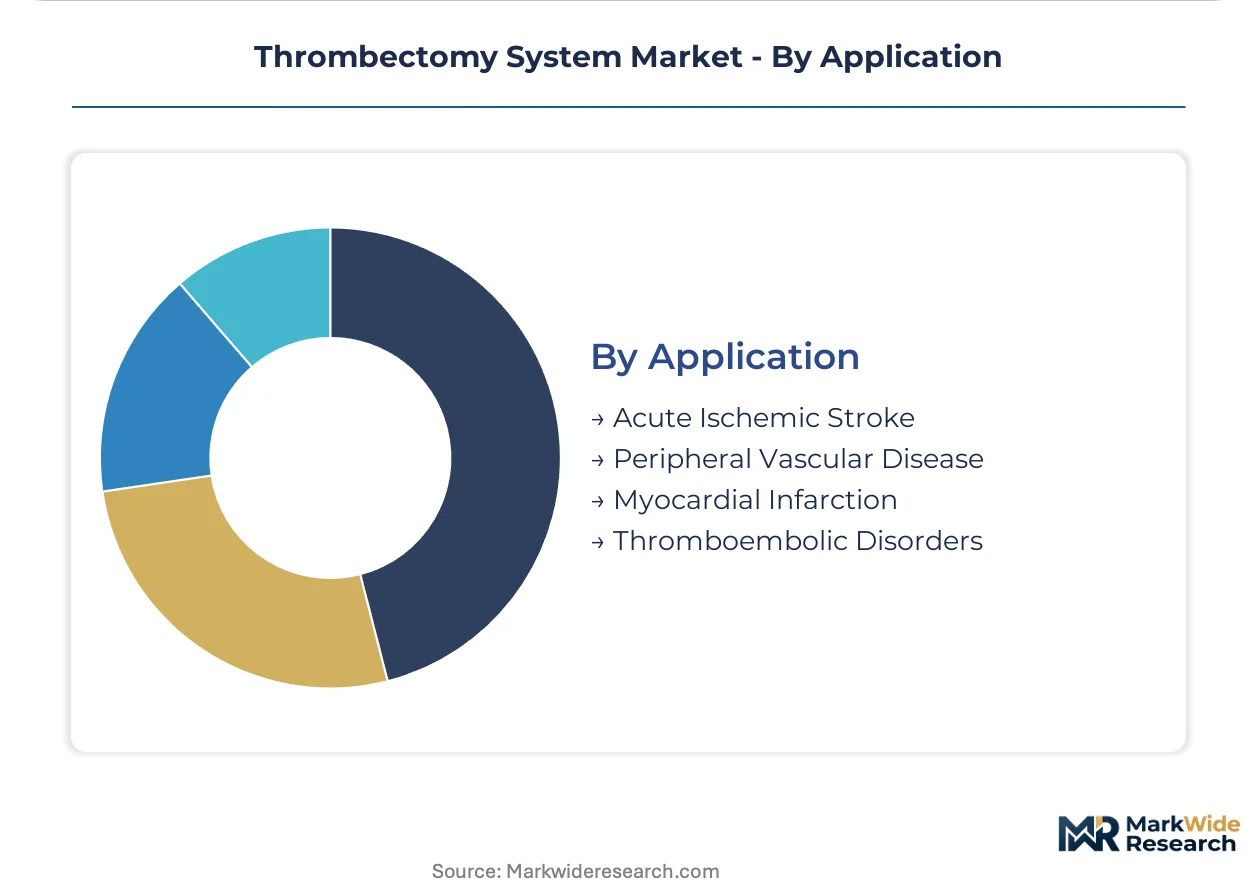
Application:
Clinical maturity varies from established acute stroke protocols to emerging peripheral indications, with regulatory clearance timelines and evidence requirements shaping commercial prioritization.
- Acute Ischemic Stroke:Large vessel occlusion intervention with established Level I evidence from randomized trials. Demand clusters at comprehensive stroke centers in the United States and Germany, driven by CMS coverage determinations and G-BA reimbursement decisions for extended treatment windows.
- Peripheral Vascular Disease:Deep vein thrombosis and pulmonary embolism mechanical thrombectomy.
- Myocardial Infarction:Coronary thrombus aspiration during percutaneous intervention.
- Thromboembolic Disorders:Broad category spanning visceral and upper extremity occlusions.
Acute Ischemic Stroke absorbs the majority of installed base. Peripheral Vascular Disease is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States stroke center certification programs outpace German network expansion in absolute facility counts, while Japanese reimbursement protocols maintain stricter evidence thresholds for extended-window procedures.
United States
Comprehensive stroke center designation through state health departments and Joint Commission accreditation compresses device procurement cycles at mid-tier hospitals. CMS extended-window coverage determinations for mechanical thrombectomy beyond six hours reshape capital allocation at secondary facilities. The Texas Medical Center cluster in Houston and Mayo Clinic's Rochester campus anchor multi-site thrombectomy platform standardization efforts.
Germany
G-BA reimbursement decisions for extended treatment windows and Level I stroke center certification through the German Stroke Society concentrate aspiration device demand. EU MDR conformity assessment requirements for Class III neurovascular devices extend regulatory timelines for manufacturers seeking CE mark renewal. The Berlin-Brandenburg metropolitan region and Munich's university hospital network drive adoption of integrated aspiration-retriever platforms.
Japan
PMDA consultative review pathways for devices with US FDA breakthrough designation accelerate market entry timelines for aspiration catheter innovations. J-Stroke registry data requirements for extended-window procedures shape clinical evidence generation strategies. The Kanto region surrounding Tokyo and Osaka's Kansai cluster concentrate comprehensive stroke center density and interventional neuroradiologist training pipelines.
United Kingdom
NHS England's stroke services specification and national clinical guidance for mechanical thrombectomy redistribute procedure volumes from hyperacute units to district general hospitals. MHRA post-Brexit regulatory alignment with EU MDR technical documentation standards affects certification continuity for existing device portfolios. London's neuroscience centers and Greater Manchester's integrated stroke network drive standardization of aspiration-first protocols.
India
CDSCO medical device rules and state-level stroke program initiatives expand addressable hospital base beyond tertiary metropolitan centers. PLI scheme incentives for domestic manufacturing of high-value medical devices attract component assembly investments. Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore medical technology cluster anchor catheter distribution infrastructure for southern and western markets.
Thrombectomy System Market Competitive Landscape
United States producers anchor the premium-tier device segment; Japanese and European specialists hold positions in catheter engineering and regulatory compliance consulting. The vendor structure concentrates around three to five integrated platform providers with full aspiration-mechanical portfolios, while mid-scale regional manufacturers compete on catheter compatibility and pump interoperability. Archetypes span diversified medical technology conglomerates with neurovascular divisions, pure-play neurointerventional specialists, and contract manufacturers supplying nitinol wire components. Competitive moves center on M&A for aspiration technology assets and strategic partnerships with academic stroke centers for clinical evidence generation.
Within the diversified conglomerate tier, Medtronic and Stryker Corporation represent integrated platform breadth spanning aspiration pumps, stent retrievers, and catheter access systems. Penumbra, Inc. occupies a position exemplifying pure-play neurointerventional specialization with concentrated engineering focus on large-bore aspiration technology. These three anchors demonstrate how competitive positioning separates through portfolio configuration rather than single-device performance claims.
| Leading Market Players |
|---|
| Penumbra, Inc. |
| Medtronic |
| Stryker Corporation |
| Boston Scientific Corporation |
| Terumo Corporation |
| Johnson & Johnson |
| AngioDynamics |
| Koninklijke Philips N.V. |
| BD Interventional |
| Others |
Value Network & Pricing Analysis
Comprehensive stroke centers in the United States, Germany, and Japan concentrate procurement volumes and anchor value-based contracting frameworks that bundle aspiration pumps with catheter systems. This buyer concentration enables premium pricing for integrated platforms while squeezing standalone device margins.
Pricing Analysis
Capacity additions in Ireland and Costa Rica for nitinol wire processing are reshaping price floors for stent retriever components. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated platforms from CE-marked alternatives and manual devices. Pricing pressure stems from CMS bundled payment pilots that collapse device reimbursement into episode-based compensation. Community hospitals exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese nitinol foundries supplying superelastic wire for stent retriever frameworks. Manufacturing concentrates in the United States, Germany, and Japan for finished devices, with Mexico and Costa Rica expanding catheter extrusion capacity. Raw material dependencies include nitinol alloy, medical-grade polymers, and platinum-iridium radiopaque markers. Tariff exposure on Chinese-sourced catheter components threatens cost structures. Distribution runs through specialized neurovascular distributors and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough device designations and EU MDR compliance timelines directly determine competitive access and pricing power.
For Market Incumbents: To counter aspiration-first protocol standardization at community hospitals, Medtronic and Stryker should deepen backward integration into large-bore catheter manufacturing and secure exclusive GPO contracts with emerging comprehensive stroke center networks. Certification investment in Japan's PMDA consultative review pathway represents the priority lever for Asia-Pacific expansion. For New Entrants and Emerging Players: EU MDR technical documentation requirements in Germany open a window for regulatory compliance consulting services and MDR transition support partnerships. Peripheral thrombectomy for venous thromboembolism presents the most penetrable white-space indication. A hospital system partnership model targeting secondary stroke centers in the United Kingdom bypasses incumbent lock-in at elite academic centers. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking aspiration technology assets to complete platform portfolios. Five-to-ten-year viability hinges on AI-integrated navigation systems and extended-window reimbursement expansion. Acquisition target archetype: pure-play aspiration specialists with FDA breakthrough designation and limited EU commercial presence. The signal to watch is CMS national coverage determination for mechanical thrombectomy beyond 24 hours.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses time-to-revenue for stent retriever innovations demonstrating substantial clinical improvement. |
| EU MDR Technical Documentation | Extended certification cycles for Class III neurovascular devices delay competitive launch sequencing in European markets. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement under value-analysis frameworks evaluating total procedure cost. |
| Software Companion Development | AI-powered clot characterization algorithms differentiate aspiration platforms through real-time device selection optimization. |
| Reimbursement Strategy | CMS extended-window coverage determinations reshape capital allocation and device procurement volumes at secondary stroke centers. |
Research Methodology
Direct dialogue with interventional neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded this analysis in clinical workflow realities and procurement decision frameworks. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare coverage determinations, and hospital procurement contract records. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, end user, application, and regional regulatory cluster dimensions.
Market size and growth trajectory outputs reflect integrated demand-side and supply-side assessment across the projection horizon. Segmentation modeling captured mechanical devices, aspiration devices, combination platforms, and manual instruments by catheter-based versus intravenous delivery technology. CAGRs derived from procedure volume elasticity to stroke center certification expansion, reimbursement policy shifts, and device innovation cycles. Forecast inputs incorporated nitinol supply constraints, EU MDR transition timelines, and Japan PMDA review pathway efficiency.
Revisions become necessary when FDA breakthrough designation criteria tighten, EU MDR notified body capacity constraints intensify, or CMS bundled payment models expand beyond pilot regions. Forecasts reflect documented assumptions about stroke center network expansion rates and interventionalist training pipeline throughput. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Medical Devices Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Bariatric Beds Market
Medical Devices
Spinal Implant Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Global Biliary Stents Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Anti-Fatigue Lenses Market