
 Brazil Angioplasty Devices Market | 2026-2036
Brazil Angioplasty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Angioplasty Devices Market Insights
Drug-eluting polymer formulations are recalibrating cost-performance trade-offs for coronary stenting in Brazil. Boston Scientific leverages its manufacturing scale to anchor supply security for balloon catheter platforms across the Southeast region. Abbott Laboratories differentiates through specialized drug-eluting stent portfolios that command preference at cardiovascular institutes. Medtronic sustains R&D intensity in intravascular lithotripsy, positioning its Shockwave-aligned technology for complex calcified lesions.
Angioplasty devices comprise catheter-based systems designed to restore luminal patency in stenosed or occluded vessels, typically incorporating balloon dilatation mechanisms, metallic or polymeric scaffolds, and guidewire navigation platforms constructed from nitinol or stainless steel with hydrophilic coatings. These systems serve the primary purpose of percutaneous revascularization, eliminating the need for open surgical intervention while enabling same-day discharge protocols. Stenting systems currently lead product type revenue pools, reflecting premium pricing for drug-eluting platforms and the procedural shift toward complete revascularization. Coronary artery disease applications dominate clinical volumes, though peripheral vascular disease represents the fastest-growing application segment as limb-salvage protocols expand into ambulatory surgical centers.
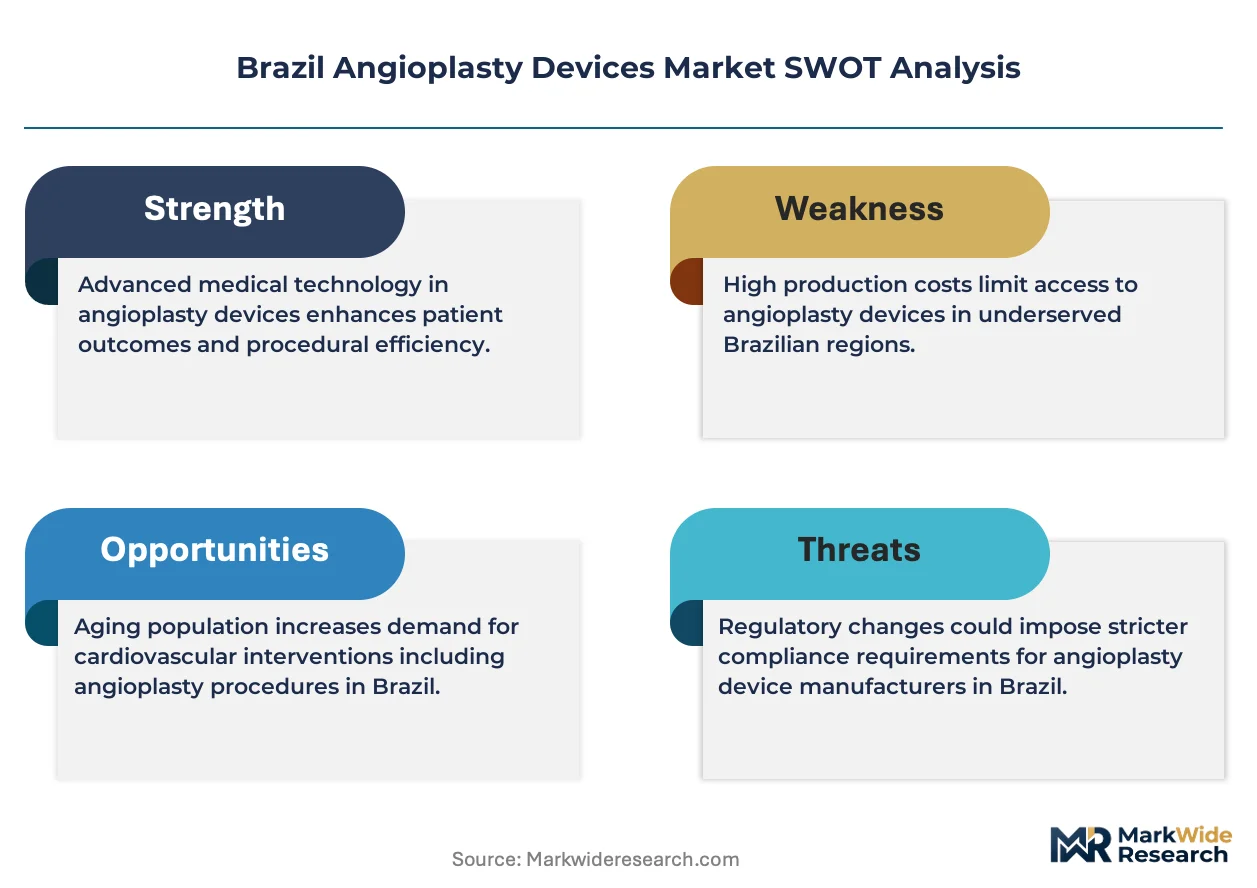
ANVISA governs medical device registration through Resolution RDC 751, mandating clinical evidence standards that align with international harmonization frameworks while maintaining Brazil-specific post-market surveillance obligations. The national regulatory framework shapes competitive dynamics by favoring manufacturers with established local quality management systems and in-country technical support infrastructure. Stakeholders must monitor evolving reimbursement thresholds under Brazil's supplementary health insurance regulator and the Ministry of Health's incorporation protocols for innovative technologies, as these determinations will gate addressable procedure volumes across public and private care pathways.
Market Dynamics
ANVISA's Resolution RDC 751 compression of clinical evidence timelines is accelerating competitive entry for next-generation stent platforms, forcing incumbent manufacturers to recalibrate local quality management investments against faster follower penetration.
Growth Catalysts
- São Paulo metropolitan corridor density:Tertiary cardiac centers cluster in this region, creating procedure volume concentration that amortizes capital equipment costs across high-throughput cath labs.
- ANVISA harmonization frameworks:Alignment with international clinical evidence standards reduces redundant testing burdens for manufacturers with established CE marking or FDA clearances.
- Drug-eluting polymer innovation:Advanced formulations reduce restenosis rates below bare-metal benchmarks, expanding addressable patient pools to diabetic and small-vessel populations previously excluded from percutaneous intervention.
Market Restraints
- Nitinol supply concentration:Brazilian manufacturers remain dependent on imported superelastic alloy feedstock from Southeast Asian refiners, exposing balloon catheter production to freight cost volatility and customs processing delays.
- Supplementary health insurance reimbursement thresholds:Brazil's national private insurance regulator maintains conservative incorporation protocols that gate novel technologies from immediate procedure coverage.
- Structural substitution from coronary artery bypass grafting:Hybrid revascularization protocols and minimally invasive surgical techniques retain preference for multi-vessel disease at high-volume cardiovascular institutes.
Strategic Opportunities
- Northeast Brazil ambulatory surgical center expansion:Limb-salvage protocols for peripheral vascular disease are penetrating Fortaleza and Recife metropolitan zones where catheterization infrastructure remains underdeveloped relative to Southeast Brazil.
- Intravascular lithotripsy convergence with imaging:Integration of Shockwave-aligned calcified lesion treatment with intravascular ultrasound guidance creates premium procedure bundles for complex coronary interventions.
- Public sector incorporation pathways:Ministry of Health technology assessment mechanisms for innovative stent platforms offer volume commitments through Sistema Único de Saúde purchasing agreements.
Industry Challenges
- Interventional cardiology fellowship pipeline constraints:Brazilian medical residency programs produce insufficient operators to match cath lab expansion rates, creating procedural bottleneck risks at new facility openings.
- ANVISA post-market surveillance compliance:Brazil-specific adverse event reporting obligations demand dedicated in-country pharmacovigilance infrastructure that strains mid-tier manufacturer resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Angioplasty Devices Market |
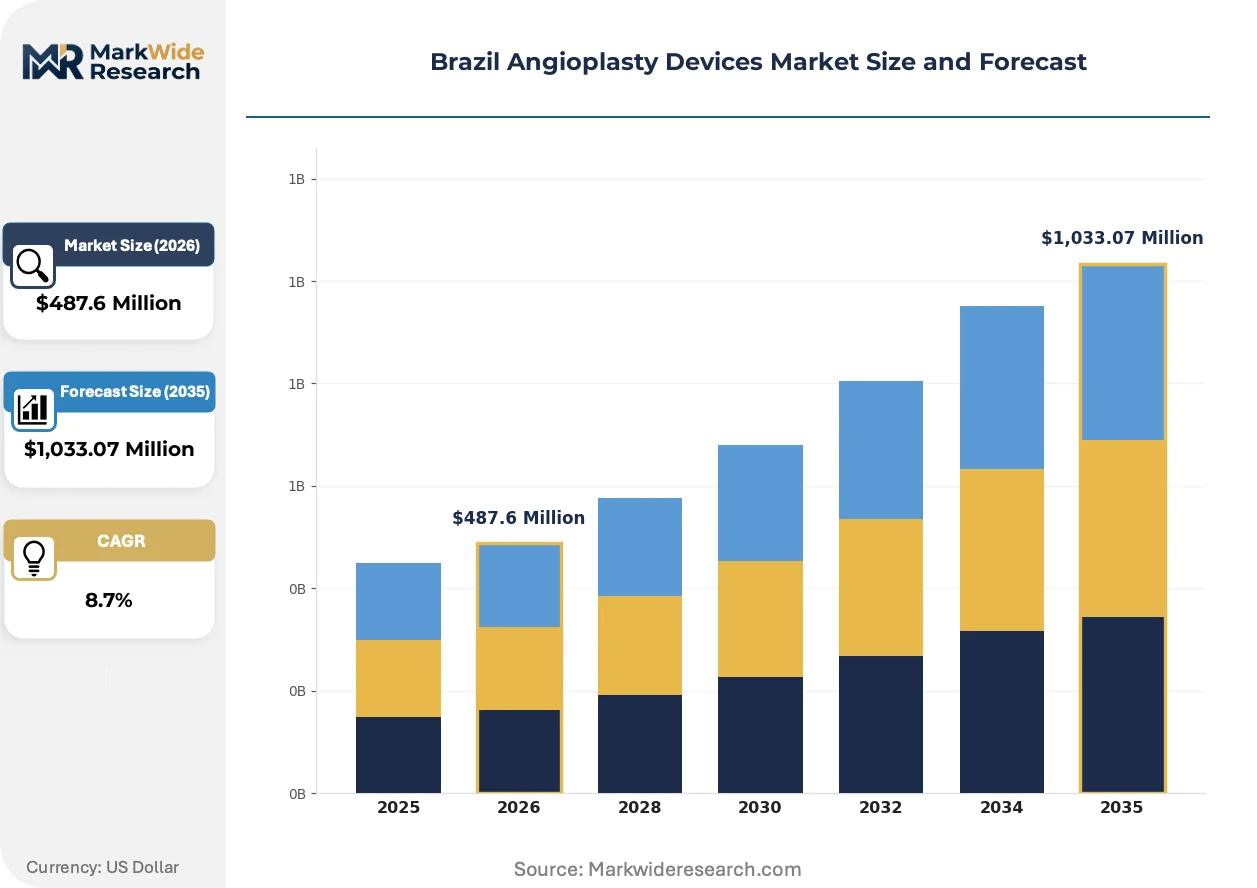
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Dilatation Catheters, Stenting Systems, Guidewires, Balloon Expandable Stents Application: Coronary Artery Disease, Peripheral Vascular Disease, Carotid Artery Stenosis, Renal Artery Stenosis End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Cardiovascular Institutes Distribution Channel: Direct Sales, Distributors, Online Sales, Hospitals Supply Chain |
| Companies Covered | Medtronic, Boston Scientific, Abbott Laboratories, Johnson & Johnson, Terumo Corporation, B. Braun, Biotronik, Philips, Shockwave Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Angioplasty Devices Market Trends and Innovations
Device miniaturization and bioresorbable scaffold development are compressing the functional lifecycle of metallic stent platforms while expanding same-day discharge eligibility criteria across Brazilian private hospital networks.
Bioresorbable vascular scaffolds constructed from poly-L-lactide polymers restore acute luminal gain then dissolve within 24-36 months, eliminating long-term metallic foreign body complications. Leading cardiovascular institutes in São Paulo and Rio de Janeiro are adopting these platforms for selected non-complex lesions at accelerating cadence. This technology is overtaking conventional durable polymer drug-eluting stents in patient segments where repeat revascularization probability exceeds implant longevity concerns.
ANVISA's updated medical device registration pathways under Resolution RDC 751 compress approval timelines from 24 months toward 12-18 months for manufacturers with established ISO 13485 quality systems. This regulatory acceleration enables faster commercialization of next-generation balloon catheter platforms. Southeast Brazil's private hospital networks are responding by compressing technology evaluation cycles and expanding preferred vendor agreements to capture early-mover clinical outcomes data.
Service unbundling is fragmenting traditional device-procedure bundled contracts as Brazilian private insurers implement separate reimbursement tracks for devices, physician professional fees, and facility costs. Ambulatory surgical centers in Curitiba and Porto Alegre are capitalizing on this disaggregation to negotiate direct device procurement relationships, bypassing hospital purchasing intermediaries. This behavioral shift concentrates procurement leverage among high-volume standalone cath labs with dedicated inventory management capabilities.
Brazil Angioplasty Devices Market Segmentation
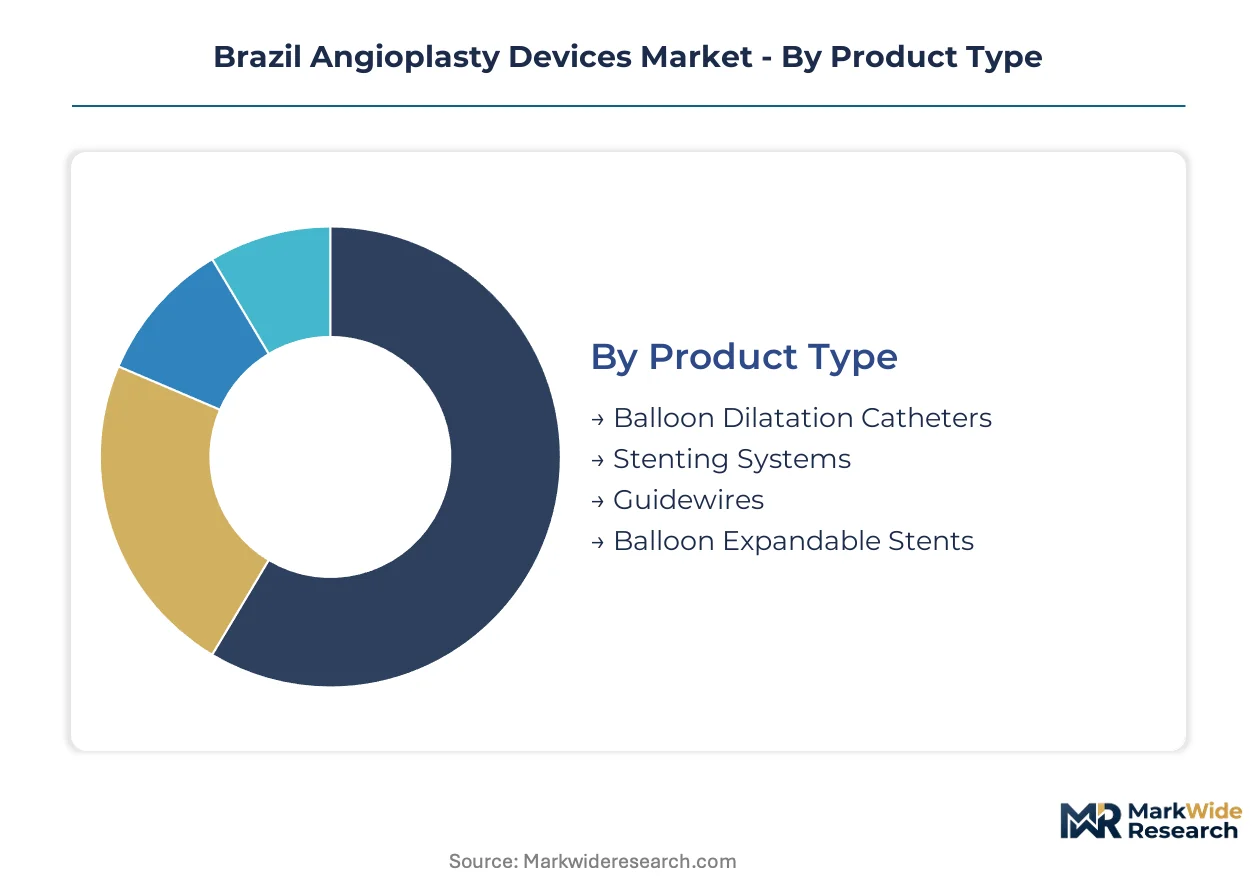
Segmentation reveals how procedural complexity, reimbursement pathways, and facility infrastructure stratify demand across Brazil's angioplasty device landscape. Understanding these divisions enables targeted positioning for manufacturers navigating ANVISA compliance and regional purchasing concentration.
Product Type:
Cost tier separates high-investment capital equipment from consumable platforms that amortize across procedure volumes.
- Stenting Systems:Drug-eluting and bare-metal platforms incorporating cobalt-chromium or platinum-chromium alloys with polymer coatings for controlled drug release. São Paulo's tertiary cardiac centers concentrate procurement of these premium systems, where private insurance reimbursement supports complete revascularization protocols. These systems absorb the largest share of device expenditure per procedure.
- Balloon Dilatation Catheters:Semi-compliant and non-compliant balloon platforms constructed from polyamide or polyethylene terephthalate with hydrophilic shaft coatings. Southeast Brazil's high-throughput cath labs drive volume concentration, with ANVISA's compressed approval timelines accelerating competitive entry for next-generation scoring and cutting balloon variants.
- Guidewires:Nitinol or stainless steel core wires with hydrophilic or hydrophobic distal coatings enabling lesion crossing.
- Balloon Expandable Stents:Stainless steel or cobalt-chromium scaffolds deployed via balloon inflation for precise lesion sizing.
Stenting systems lead volumes today; balloon dilatation catheters are gaining share fastest.
Application:
Clinical urgency and lesion anatomical complexity determine reimbursement tiering and operator specialization requirements.
- Coronary Artery Disease:Percutaneous coronary intervention for acute myocardial infarction and stable angina, utilizing drug-eluting stents and intravascular imaging guidance. São Paulo and Rio de Janeiro metropolitan corridors concentrate procedure volumes, where cardiovascular institutes maintain 24/7 primary PCI capabilities and hybrid operating suites.
- Peripheral Vascular Disease:Femoropopliteal and infrapopliteal revascularization for critical limb ischemia, employing self-expanding nitinol stents and drug-coated balloons. Fortaleza and Recife in Northeast Brazil show the steepest expansion trajectory as limb-salvage protocols penetrate previously underserved ambulatory surgical centers.
- Carotid Artery Stenosis:Carotid artery stenting with embolic protection devices for stroke prevention in high-surgical-risk patients.
- Renal Artery Stenosis:Renal artery stenting for renovascular hypertension and ischemic nephropathy management.
Coronary applications dominate current procedure counts; peripheral vascular disease is climbing the fastest.
End User:
Capital intensity and case mix sophistication separate institutional purchasers from outpatient-focused operators.
- Hospitals:Tertiary and secondary acute care facilities with dedicated cardiac catheterization laboratories, hybrid operating rooms, and 24/7 interventional coverage. São Paulo's metropolitan corridor anchors procurement concentration, where integrated supply chain agreements and group purchasing organizations consolidate vendor relationships.
- Cardiovascular Institutes:Specialized cardiac centers with fellowship-trained interventional cardiologists and research protocols for innovative device evaluation. These institutes command premium pricing acceptance and generate outcome data that influences broader adoption patterns.
- Ambulatory Surgical Centers:Standalone facilities performing elective diagnostic and interventional procedures with same-day discharge protocols.
- Specialty Clinics:Office-based practices focused on diagnostic angiography and lower-acuity interventions.
Hospitals lead volumes today; ambulatory surgical centers are expanding most quickly.
Distribution Channel:
Procurement scale and inventory velocity determine whether direct manufacturer relationships or intermediary networks deliver optimal service levels.
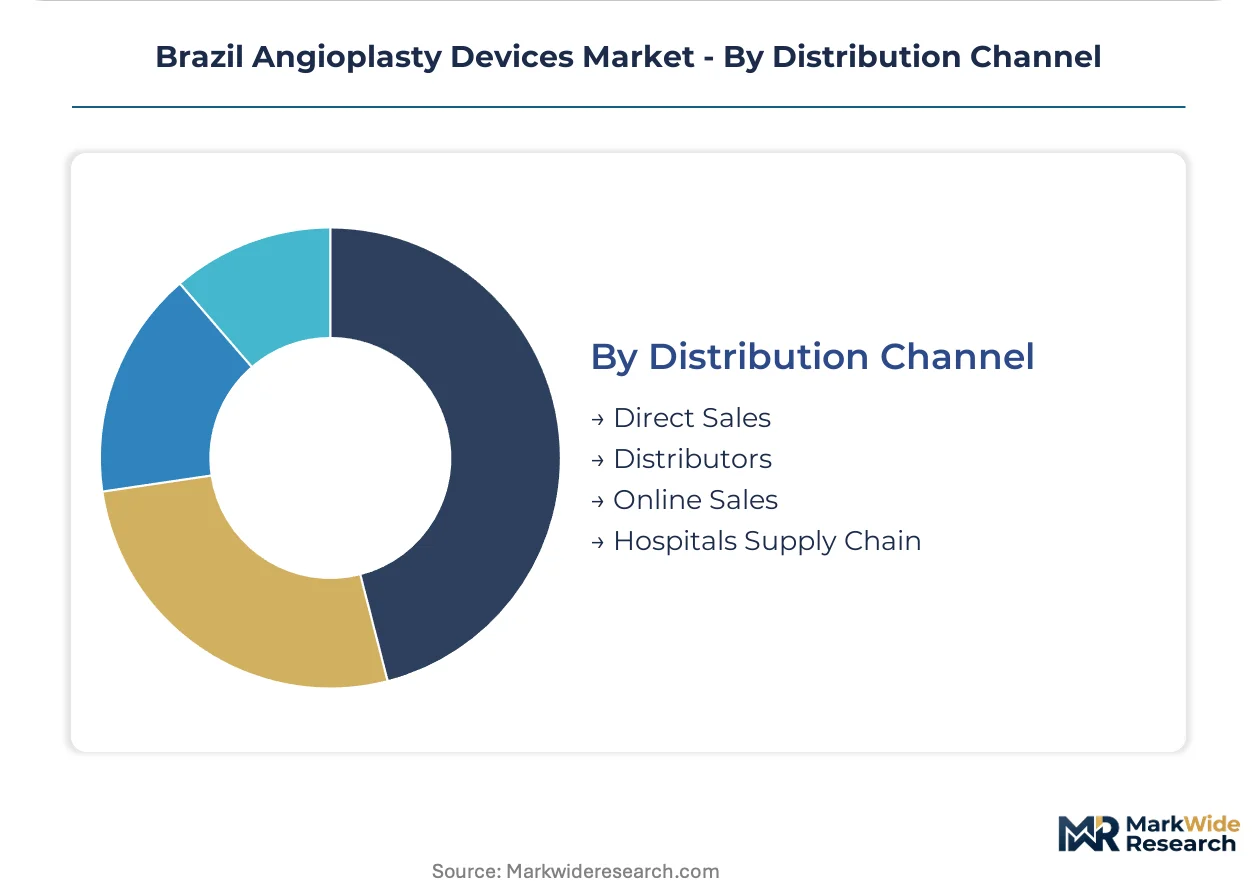
- Direct Sales:Manufacturer-to-institution relationships for high-volume accounts with dedicated field clinical specialists and consignment inventory arrangements. São Paulo's cardiovascular institutes and large hospital systems leverage direct channels to secure priority allocation during supply constraints.
- Distributors:Third-party logistics networks providing warehousing, local regulatory compliance support, and credit terms for mid-tier facilities. Northeast and Central-West Brazil regions rely heavily on distributor infrastructure where manufacturer direct presence remains limited.
- Hospital Supply Chain:Centralized procurement through multi-hospital health systems and group purchasing organizations.
- Online Sales:Digital platforms for consumable replenishment and emergency stock orders.
Direct sales lead volumes today; hospital supply chain consolidation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan corridor anchors Brazil's angioplasty device demand through dense clustering of tertiary cardiac centers and elevated private insurance penetration that enables procedure access.
São Paulo
Cardiovascular institutes and high-throughput cath labs concentrate procurement of drug-eluting stent platforms and balloon catheter systems. ANVISA's Resolution RDC 751 harmonization with international standards accelerates product registration for manufacturers targeting this corridor. São Paulo city and Campinas anchor the Southeast's interventional cardiology volumes, where group purchasing organizations consolidate vendor relationships across integrated hospital networks.
Rio de Janeiro
Hybrid operating suites and 24/7 primary PCI capabilities drive consumption of intravascular imaging and lithotripsy systems. The national supplementary health insurance regulator maintains technology assessment protocols that gate novel device coverage in private facilities. Rio de Janeiro metropolitan zone sustains preference for complete revascularization procedures at cardiovascular institutes with fellowship-trained operator density.
Minas Gerais
Belo Horizonte's expanding cath lab infrastructure supports growing adoption of peripheral vascular intervention platforms for limb-salvage protocols. Brazil's Ministry of Health incorporation mechanisms for innovative technologies determine Sistema Único de Saúde purchasing volumes in public hospitals. The state's secondary acute care facilities are upgrading catheterization capabilities to capture migrating procedure volumes from São Paulo.
Rio Grande do Sul
Porto Alegre's ambulatory surgical centers leverage service unbundling trends to negotiate direct device procurement relationships bypassing hospital intermediaries. ANVISA post-market surveillance obligations demand localized pharmacovigilance infrastructure that influences manufacturer distribution channel decisions. The southern region's standalone cath labs concentrate inventory management capabilities for high-volume consumable replenishment.
Bahia
Salvador's emerging cardiovascular centers represent frontier expansion for drug-coated balloon platforms as interventional cardiology fellowship programs scale operator supply. Brazil's customs processing frameworks for imported nitinol feedstock expose Northeast manufacturers to freight cost volatility. The state's developing procurement infrastructure relies heavily on distributor networks where direct manufacturer presence remains limited relative to Southeast Brazil.
Brazil Angioplasty Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent manufacturers recalibrate local quality management investments against compressed regulatory timelines. The vendor base stratifies across multinational conglomerates with established ISO 13485 systems, mid-tier regional specialists, and emerging technology licensors. Three archetypes define competitive positioning: integrated device-cardiology platform providers, focused interventional vascular specialists, and imaging-therapy convergence players. M&A activity and strategic technology licensing agreements represent the dominant competitive moves reshaping market structure.
Among integrated cardiovascular platform providers, Medtronic and Boston Scientific occupy positions that exemplify scale-driven supply security and manufacturing footprint advantages. Abbott Laboratories anchors the specialized drug-eluting stent tier, representing preference command at high-volume cardiovascular institutes. These three entities sit within distinct competitive vectors—device platform breadth, stent portfolio specialization, and cath lab ecosystem integration—rather than direct segment overlap.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott Laboratories |
| Johnson & Johnson |
| Terumo Corporation |
| B. Braun |
| Biotronik |
| Philips |
| Shockwave Medical |
| Others |
Pricing and Supply Chain Analysis
São Paulo's cardiovascular institutes and tertiary cardiac centers concentrate procurement leverage, anchoring a contract-based pricing model where volume commitments secure preferential terms for drug-eluting stent platforms and balloon catheter systems.
Pricing Analysis
Imported nitinol feedstock costs pass through directly to balloon catheter pricing, compressing margins for manufacturers without captive alloy supply. Three-tier pricing structure across premium drug-eluting stents, standard bare-metal platforms, and economy balloon systems reflects brand premium and ANVISA certification tier. Pricing pressure stems from service unbundling as Brazilian private insurers separate device reimbursement from facility fees. Ambulatory surgical centers in Curitiba and Porto Alegre exhibit highest price sensitivity, while São Paulo's cardiovascular institutes accept premium tiers for outcome data generation.
Supply Chain Analysis
Dual-sourcing requirements for nitinol superelastic alloys mandate qualification of Southeast Asian and European refiners, insulating Brazilian manufacturers against single-source disruption. Production draws from Malaysian and German alloy feedstock, with polyamide balloon material sourced from US and Japanese chemical producers. Tariff exposure on imported medical-grade polymers creates inventory cost volatility at Brazilian conversion facilities. Distribution runs through manufacturer direct sales for high-volume São Paulo accounts and third-party logistics networks covering Northeast and Central-West regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's angioplasty device market compounds steadily as interventional cardiology procedure volumes expand against aging demographics and coronary disease prevalence.
For Market Incumbents: Deepen backward integration into nitinol alloy supply through long-term offtake agreements with Southeast Asian refiners, insulating production from freight cost volatility. Expand consignment inventory arrangements at São Paulo cardiovascular institutes to lock out emerging competitors exploiting ANVISA's compressed approval timelines. Prioritize pharmacovigilance infrastructure investment to satisfy post-market surveillance obligations that strain mid-tier rivals. For New Entrants and Emerging Players: The gap between premium drug-eluting stent pricing and economy balloon catheter tiers offers white-space positioning for specialized peripheral vascular platforms. Target Fortaleza and Recife ambulatory surgical centers where catheterization infrastructure remains underdeveloped and distributor relationships dominate procurement. Pursue ANVISA registration alignment with existing CE marking to accelerate commercial entry ahead of direct sales network buildout. For Investors and Strategic Acquirers: Large multinational cardiovascular device conglomerates represent the most active acquirer category in this space, seeking imaging-therapy convergence capabilities and regional regulatory expertise. Over the medium-term horizon, target mid-tier manufacturers with established ISO 13485 systems and incomplete Brazil commercialization. Watch ANVISA incorporation pathway decisions for innovative stent platforms as the signal indicating public sector volume commitment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Optimization | Resolution RDC 751 alignment with ISO 13485 compresses approval timelines from 24 months toward 12-18 months. |
| Hospital System Partnership | Preferred vendor agreements at São Paulo cardiovascular institutes generate outcome data influencing broader adoption. |
| Reimbursement Strategy | Ministry of Health incorporation protocols gate Sistema Único de Saúde purchasing volumes for innovative platforms. |
| Software Companion Development | Intravascular ultrasound integration with lithotripsy systems creates premium procedure bundles for complex lesions. |
| Geographic Expansion | Northeast Brazil ambulatory surgical center penetration captures limb-salvage protocol migration from tertiary hospitals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, ANVISA regulatory consultants, and biomedical engineers with secondary validation against ANVISA registration databases, hospital procurement records, and supplementary health insurance reimbursement filings. Bottom-up procedure volume estimates triangulated against top-down device expenditure flows.
Segment-weighting approaches distributed total market value across stenting systems, balloon dilatation catheters, and guidewire platforms, with further stratification by coronary versus peripheral vascular application and hospital versus ambulatory surgical center end-use. CAGRs derived from logistic diffusion modeling of procedure adoption curves, incorporating ANVISA approval timeline compression and interventional cardiology fellowship pipeline expansion as industry-specific demand drivers.
Caveats apply where ANVISA post-market surveillance enforcement intensity or supplementary health insurance reimbursement threshold revisions could materially shift the outlook. Deviation in nitinol alloy import tariff schedules or customs processing efficiency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurofeedback Systems Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Blood Lancet Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Global Transradial Access Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Ear Tube Devices Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Artificial Spine Discs Market
Medical Devices
PPG Biosensors Market