
 Percutaneous Nephrostomy Catheters Market | 2026-2036
Percutaneous Nephrostomy Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Percutaneous Nephrostomy Catheters Market Intelligence
Aftermarket service revenue from catheter maintenance and replacement protocols is reshaping how manufacturers capture lifetime value per patient encounter. Teleflex Incorporated leverages its interventional access portfolio to sustain recurring revenue streams across hospital systems. Boston Scientific Corporation anchors its position through specialized nephrostomy portfolios that integrate with broader urological workflows. Cook Medical LLC dominates the custom-engineered catheter segment through deep relationships with academic medical centers.
Percutaneous nephrostomy catheters are hollow, radiopaque tubes inserted through the flank into the renal collecting system under imaging guidance, typically constructed from silicone or polyurethane with French sizes ranging from 6Fr to 14Fr and retention mechanisms including J-curves or pigtail loops to prevent dislodgement. These devices establish temporary or prolonged urinary diversion when retrograde ureteral access proves impossible due to obstruction, stricture, or malignancy. Pigtail catheters command the largest installed base owing to their superior retention profile and lower complication rates in long-term indwelling applications, while balloon catheters represent the fastest-expanding category as interventionalists adopt them for complex stone disease and antegrade ureteral procedures. The material dimension shows polyurethane gaining share against silicone in high-flow scenarios where column strength and kink resistance prove clinically decisive.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern market entry, with both frameworks intensifying scrutiny of material characterization and pyrogenicity documentation. The EPA and OSHA intersect indirectly through sterilization facility emissions controls and ethylene oxide exposure limits that constrain manufacturing geography choices. Stakeholders must monitor how reimbursement coding revisions for office-based nephrostomy exchanges alter site-of-service economics and catheter replacement cadence.
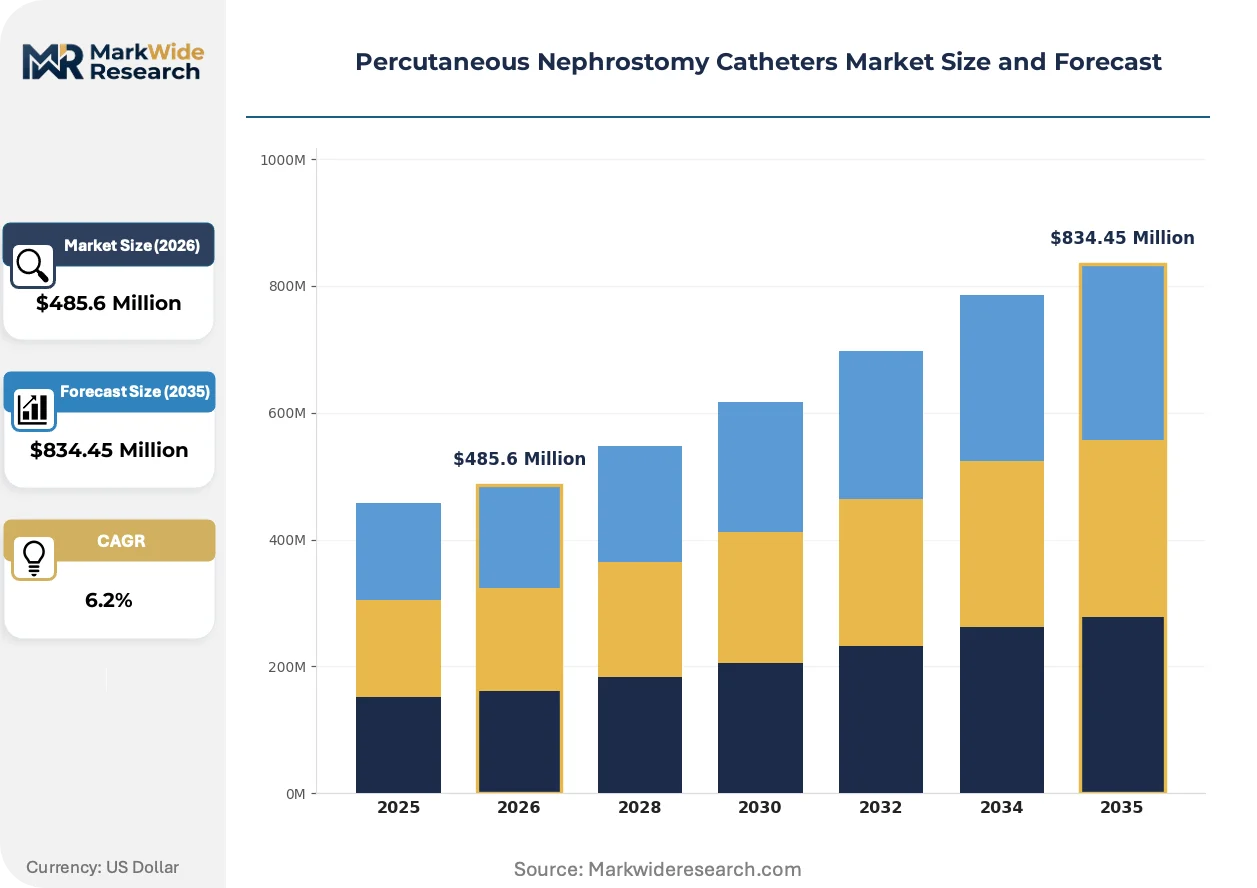
Market Dynamics
FDA and EU MDR tightening around biocompatibility documentation is forcing manufacturers to restructure material validation workflows and sterilization partnerships, compressing margins while elevating barriers for new entrants.
Growth Catalysts
- Ambulatory Surgical Center Expansion:CMS reimbursement revisions for office-based nephrostomy exchanges are redirecting procedural volume away from inpatient settings. ASC infrastructure investments in the United States accelerate catheter utilization.
- REACH Material Compliance:European chemical safety frameworks are standardizing polyurethane characterization protocols. Manufacturers achieving early REACH alignment capture preferential supply contracts with German hospital systems.
- Antegrade Ureteral Adoption:Balloon catheter technology enables complex stone disease interventions previously requiring open surgery. Interventional urology training programs are expanding balloon catheter competency requirements.
Market Restraints
- Ethylene Oxide Supply Concentration:EPA emissions controls have consolidated sterilization facility geography to the US Gulf Coast. Single-source sterilization dependency creates hurricane-season vulnerability for catheter inventory.
- Silicone Raw Material Volatility:Medical-grade silicone feedstock pricing fluctuates with semiconductor sector demand cycles. Catheter manufacturers lack hedging instruments for this input.
- Substitution by Ureteral Stents:Advances in retrograde stent placement are reclaiming some obstructed ureter cases previously requiring percutaneous access. Stent technology narrows the addressable procedure pool.
Strategic Opportunities
- Telehealth-Integrated Catheter Monitoring:Remote drainage assessment platforms are virtualizing follow-up care. Home health agencies in Japan are piloting camera-enabled drainage bag systems.
- India Interventional Urology Buildout:Underpenetrated metropolitan hospital networks in Mumbai and Bangalore are acquiring fluoroscopy suites. CDSCO streamlined 510(k)-equivalent pathways accelerate market entry timing.
- Bioresorbable Retention Mechanisms:Convergence of polymer chemistry and 3D printing enables patient-specific pigtail geometries. Academic medical centers are co-developing dissolvable retention anchors.
Industry Challenges
- Interventional Radiology Training Bottlenecks:Percutaneous nephrostomy requires fluoroscopy certification and ultrasound-guided access competency. Fellowship program expansion lags procedural demand growth.
- EU MDR Technical Documentation Burden:Clinical evidence requirements for Class IIa devices have extended conformity assessment timelines. Notified Body capacity constraints delay market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Percutaneous Nephrostomy Catheters Market |
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $834.45 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single J Catheters, Double J Catheters, Pigtail Catheters, Balloon Catheters Material: Silicone, PVC, Teflon, Polyurethane End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Home Care Application: Urinary Obstruction, Nephrolithiasis, Infection Management, Diagnostic Imaging |
| Companies Covered | Teleflex Incorporated, Medtronic plc, Boston Scientific Corporation, AngioDynamics, Inc., Argon Medical Devices, Inc., Cook Medical LLC, Cardinal Health, Inc., Olympus Corporation, BD (Becton, Dickinson and Company), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Percutaneous Nephrostomy Catheters Market Strategic Shifts & Innovations
Digital integration and material science advances are compressing the traditional catheter lifecycle while opening new service revenue models around patient monitoring and maintenance protocols.
Antimicrobial-coated polyurethane formulations are virtualizing infection prevention protocols in long-term indwelling applications. Academic medical centers in Germany and Japan are adopting silver-ion-impregnated catheters for immunocompromised patient cohorts. This technology is virtualizing the traditional prophylactic antibiotic regimen, reducing pharmacy costs while elevating material premiums.
EU MDR Article 10 technical documentation requirements are mandating pyrogenicity testing beyond previous MEDDEV guidance. Sterilization validation protocols now require endotoxin quantification at the component level. German manufacturers are consolidating supply chains to captive ethylene oxide facilities to maintain batch traceability.
Hospital purchasing consortia are consolidating catheter procurement through standardized formularies. Group Purchasing Organizations in the United States are unbundling device costs from procedural reimbursement, forcing price transparency. This concentration is most visible in integrated delivery networks across Texas and Florida, where nephrostomy exchange volumes justify direct manufacturer contracting.
Percutaneous Nephrostomy Catheters Market Segmentation
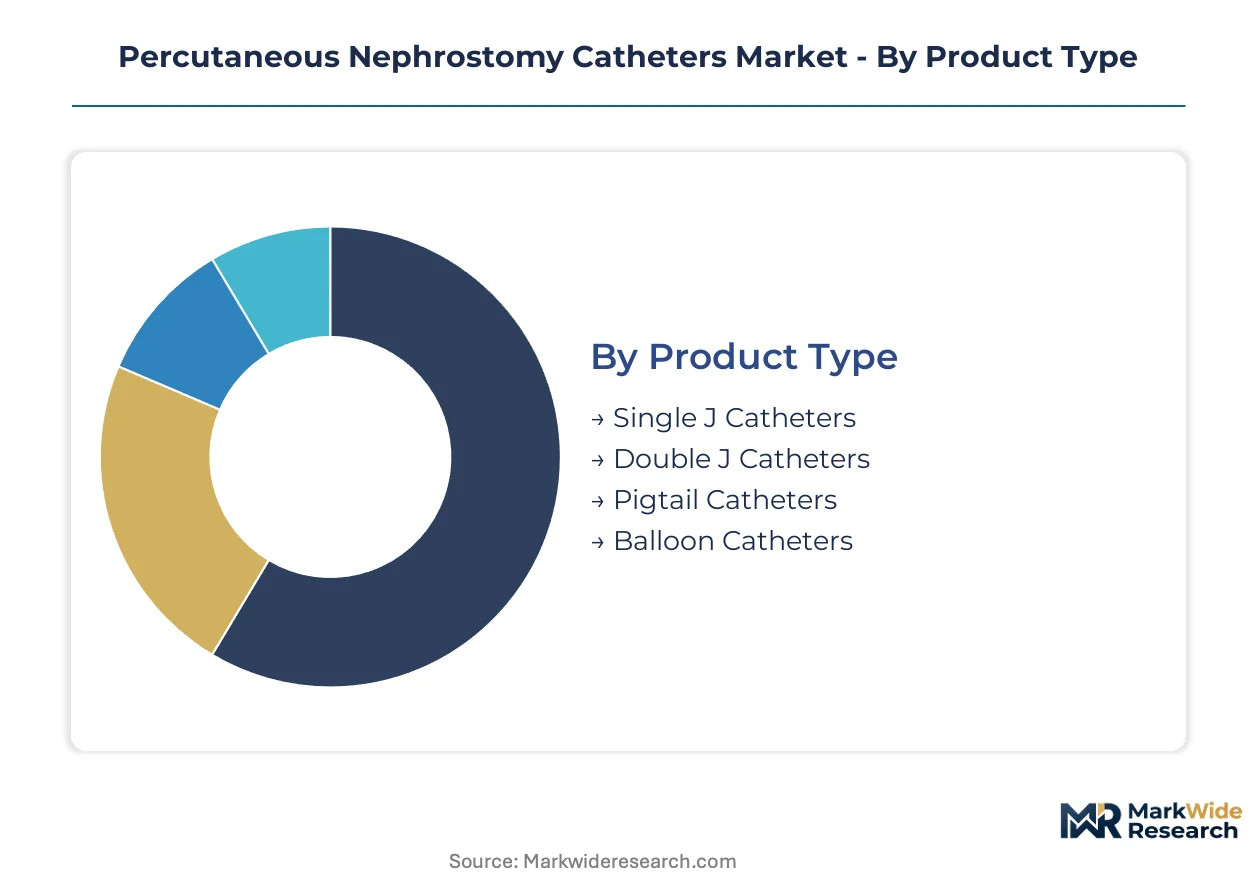
Catheter segmentation dictates aftermarket revenue architecture. Replacement cadence, maintenance protocols, and remote monitoring compatibility vary sharply across product configurations, creating divergent lifetime value profiles for manufacturers.
Product Type:
After-sales-service intensity peaks with indwelling duration. Pigtail and balloon designs demand scheduled exchange protocols that sustain recurring revenue streams.
- Pigtail Catheters:Coiled retention loops constructed from radiopaque polyurethane or silicone minimize dislodgement in long-term urinary diversion. German academic medical centers specify pigtail configurations for malignant obstruction cases exceeding 90 days indwelling time, anchoring manufacturer service contracts.
- Balloon Catheters:Integrated inflatable retention mechanisms enable antegrade ureteral access for complex stone disease. Japanese interventional urology training programs are expanding balloon catheter competency requirements, accelerating procedural adoption.
- Single J Catheters:Single-curve retention design suits short-term drainage scenarios in US ambulatory surgical centers.
- Double J Catheters:Dual J-curve configuration bridges renal pelvis to bladder in retrograde-impossible cases.
Pigtail Catheters hold the largest share; momentum sits with Balloon Catheters.
Material:
Cost tier stratification separates premium polyurethane from commodity alternatives. Material selection governs kink resistance, flow rates, and coating compatibility.
- Polyurethane:High column strength and kink resistance support high-flow drainage in interventional radiology suites. REACH compliance alignment in Germany is consolidating supply contracts with hospital systems demanding documented biocompatibility.
- Silicone:Superior biocompatibility and reduced encrustation risk serve immunocompromised cohorts. Raw material pricing volatility tied to semiconductor sector demand cycles constrains margin predictability.
- PVC:Lower unit cost positions PVC for price-sensitive procurement in Indian metropolitan hospital networks.
- Teflon:Lubricious surface properties facilitate difficult access scenarios in academic medical centers.
Polyurethane dominates high-value applications; silicone retains preference in long-term indwelling protocols.
End User:
Volume concentration shifts toward outpatient settings as reimbursement redirects procedural economics.
- Ambulatory Surgical Centers:CMS coding revisions for office-based nephrostomy exchanges are redirecting volume from inpatient settings. ASC infrastructure investments across Texas and Florida accelerate catheter utilization and replacement frequency.
- Hospitals:Integrated delivery networks consolidate procurement through standardized formularies. Group purchasing organizations unbundle device costs from procedural reimbursement, forcing price transparency.
- Outpatient Clinics:Intermediate acuity settings handle scheduled exchanges without fluoroscopy suite overhead.
- Home Care:Remote drainage assessment platforms are virtualizing follow-up care in Japanese pilot programs.
Hospitals retain the largest share; Ambulatory Surgical Centers are expanding most quickly.
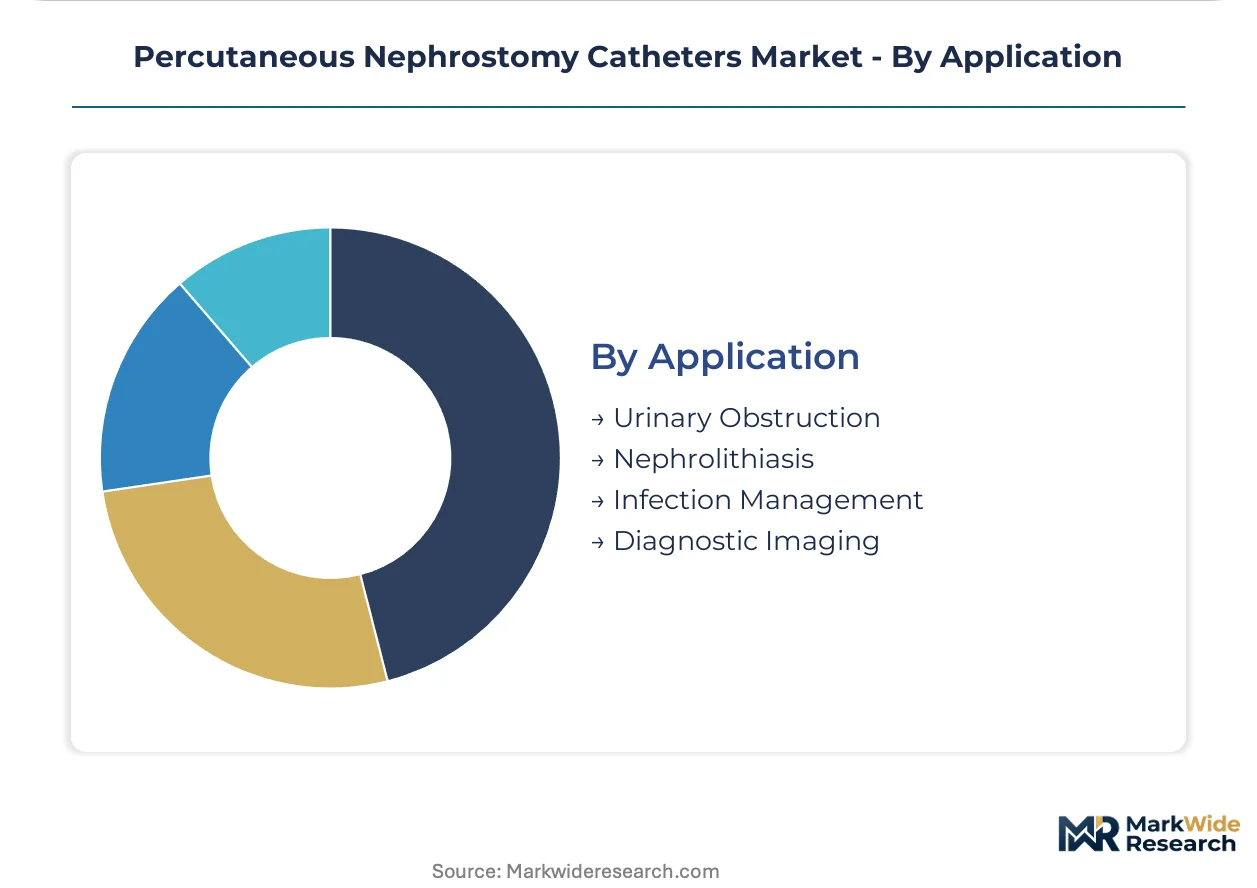
Application:
Clinical indication determines catheter specification, indwelling duration, and monitoring intensity.
- Urinary Obstruction:Malignant and benign obstructions require prolonged diversion when retrograde access fails. Silver-ion-impregnated catheters are displacing prophylactic antibiotic regimens in German immunocompromised cohorts.
- Nephrolithiasis:Antegrade stone access demands balloon catheter technology for complex calyceal anatomy. Interventional urology fellowships are expanding percutaneous nephrolithotomy training pipelines.
- Infection Management:Pyonephrosis drainage requires large-bore catheters with antimicrobial coatings.
- Diagnostic Imaging:Contrast injection protocols specify radiopaque markers and specific French sizes.
Urinary Obstruction commands the largest share; Nephrolithiasis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes percutaneous nephrostomy catheters predominantly through ambulatory surgical centers, whereas Germany and Japan maintain hospital-centric utilization patterns with longer indwelling protocols. This divergence shapes regulatory focus and service revenue architecture across geographies.
United States
CMS reimbursement revisions for office-based nephrostomy exchanges redirect procedural volume toward ASCs in Texas and Florida. FDA 510(k) clearance pathways govern market entry with intensifying scrutiny of material characterization. Integrated delivery networks across the Southeast consolidate procurement through standardized formularies.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia specify pigtail configurations for malignant obstruction cases exceeding 90 days. EU MDR Article 10 technical documentation requirements mandate pyrogenicity testing beyond previous MEDDEV guidance. Manufacturers achieving REACH alignment capture preferential supply contracts with hospital systems demanding documented biocompatibility.
Japan
Home health agencies pilot camera-enabled drainage bag systems for remote assessment in the Kanto region. PMDA regulatory frameworks align with international standards while maintaining distinct quality management requirements. Interventional urology training programs in Osaka and Nagoya expand balloon catheter competency requirements.
India
Metropolitan hospital networks in Mumbai and Bangalore acquire fluoroscopy suites for underpenetrated interventional urology services. CDSCO streamlined 510(k)-equivalent pathways accelerate market entry timing for multinational manufacturers. Price-sensitive procurement in Delhi-NCR favors PVC configurations over premium polyurethane alternatives.
United Kingdom
NHS England procurement frameworks emphasize value-based catheter selection across London and Midlands hospital trusts. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining conformity assessment timelines. Regional interventional radiology networks concentrate expertise in teaching hospitals.
Percutaneous Nephrostomy Catheters Market Key Industry Players
Capability concentration sits with specialized interventional access manufacturers; scale advantage sits with diversified medical device conglomerates. The market structures around three tiers: premium catheter specialists with deep academic center relationships, mid-scale players leveraging interventional portfolio breadth, and regional fabricators serving price-sensitive procurement. Dominant competitive moves include strategic partnerships with sterilization facilities to secure ethylene oxide supply and portfolio diversification into drainage monitoring systems.
Among diversified interventional device manufacturers, Teleflex Incorporated, Boston Scientific Corporation, and Cook Medical LLC exemplify distinct archetypes. Teleflex leverages interventional access portfolio breadth to sustain recurring revenue streams across hospital systems. Boston Scientific anchors positioning through specialized nephrostomy portfolios integrating with broader urological workflows. Cook Medical occupies a position within the custom-engineered catheter segment through relationships with academic medical centers.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Medtronic plc |
| Boston Scientific Corporation |
| AngioDynamics, Inc. |
| Argon Medical Devices, Inc. |
| Cook Medical LLC |
| Cardinal Health, Inc. |
| Olympus Corporation |
| BD (Becton, Dickinson and Company) |
| Others |
Cost & Logistics Intelligence
Ethylene oxide sterilization capacity clustering along the US Gulf Coast concentrates supply risk for catheter manufacturers while anchoring premium pricing tiers to captive facility access. Margin pools sit downstream with manufacturers securing batch-traceable sterilization partnerships and multi-year service contracts with integrated delivery networks.
Pricing Analysis
Long-term offtake agreements dominate procurement between major manufacturers and hospital purchasing consortia, with spot purchasing limited to emergency inventory replenishment. Price differentiation hinges on REACH compliance documentation for German contracts and antimicrobial coating tiers for immunocompromised protocols. Pricing pressure stems from Group Purchasing Organization unbundling of device costs from procedural reimbursement in US integrated delivery networks. Ambulatory Surgical Centers exhibit highest price sensitivity due to thinner reimbursement margins, while academic medical centers in Germany and Japan accept material premiums for documented biocompatibility.
Supply Chain Analysis
Medical-grade polyurethane feedstock draws from petrochemical complexes in Germany, the United States, and Japan, with silicone sourcing tethered to semiconductor sector demand cycles. Raw material dependencies center on isocyanates, polyols, and platinum-cured silicone elastomers. Single-source sterilization vulnerability intensifies during Atlantic hurricane season when Gulf Coast facility disruptions cascade through inventory pipelines. Distribution runs through manufacturer-direct contracting with integrated delivery networks and specialized interventional access distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter maintenance and replacement protocols are expanding service-attach revenue faster than hardware sales, with remote drainage monitoring pilots in Japan validating subscription-based follow-care models.
For Market Incumbents: Entrench market position through captive ethylene oxide sterilization investments and REACH-aligned material characterization workflows that elevate barriers for new entrants. Consolidate procurement relationships with Texas and Florida integrated delivery networks before reimbursement coding revisions fully mature. Vertical integration into drainage monitoring software complements hardware margins. For New Entrants and Emerging Players: Pursue underpenetrated metropolitan hospital networks in Mumbai and Bangalore where CDSCO streamlined pathways compress market entry timing. Target price-sensitive PVC catheter procurement in Delhi-NCR while building competency in polyurethane REACH compliance for eventual German contract eligibility. Partner with regional fluoroscopy suite installers for pull-through device adoption. For Investors and Strategic Acquirers: Capital is best deployed toward sterilization facility operators and antimicrobial coating technology platforms rather than commodity catheter fabrication. Long-term viability over a multi-year horizon favors assets with FDA 510(k) clearance momentum and established academic medical center relationships. Watch for EU MDR Notified Body capacity expansion as an inflection signal for European market authorization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct contracting with Texas integrated delivery networks secures replacement protocol revenue streams. |
| Reimbursement Strategy | CMS coding alignment for office-based exchanges redirects volume toward ambulatory surgical centers. |
| CE Marking Pathway | EU MDR Article 10 technical documentation accelerates German hospital system supply contracts. |
| Software Companion Development | Remote drainage assessment platforms virtualize follow-up care in Japanese home health pilots. |
| Backward Integration | Captive ethylene oxide facilities mitigate hurricane-season sterilization disruption risks. |
Research Approach
Initial hypotheses were tested against primary input from interventional radiologists, hospital purchasing committee members, biomedical engineers, and Group Purchasing Organization contract managers and refined through secondary validation against FDA 510(k) filings, CMS reimbursement coding databases, hospital procurement records, and EU MDR technical documentation. Bottom-up catheter unit demand estimates were triangulated with top-down market sizing across manufacturer revenue disclosures.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by catheter type, material grade, end-user setting, and clinical indication driving volume allocations. CAGRs were derived from procedural volume growth curves and replacement cadence assumptions specific to ambulatory surgical center expansion and malignant obstruction case trends.
Sensitivities concentrate around EPA ethylene oxide emissions policy shifts, EU MDR Notified Body capacity constraints, and CMS reimbursement coding revisions for office-based procedures. Cross-checking against hospital capital expenditure disclosures for fluoroscopy suite installations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Smart Stairlift Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Bioimpedance Devices Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Pleural Catheters Market
Medical Devices
Peak Flow Meters Market